
 Global Gynecological Devices Market | 2026-2036
Global Gynecological Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gynecological Devices Market Foresight
Modular surgical instrument bundles is expanding as the dominant procurement configuration, letting ambulatory surgical centers standardize workflows while reducing per-procedure costs. Hologic leverages its integrated diagnostic-imaging portfolio to anchor bundled contracts across North American hospital networks. Boston Scientific competes through specialized electrosurgical devices for endometrial ablation. CooperSurgical sustains its position in fertility and obstetrics through deep product specialization in cryosurgical systems.
Gynecological devices comprise instruments, imaging systems, and disposable consumables engineered for cervical dilation, tissue sampling, hysteroscopic visualization, and laparoscopic intervention, typically manufactured from medical-grade stainless steel, polymer composites, or single-use biocompatible plastics sterilized to ISO standards. Their primary purpose is to enable diagnostic accuracy and therapeutic precision across reproductive health procedures while minimizing patient trauma and recovery time. Surgical instruments for uterine fibroid and endometriosis procedures command concentrated margin pools due to procedural complexity and reusable-to-disposable transition dynamics. Ultrasound systems retain mature, replacement-driven demand cycles in diagnostic centers. Hysteroscopes represent the fastest-growing product type as single-use configurations displace traditional reprocessing workflows in outpatient clinics.
FDA premarket notification pathways and EU MDR conformity assessment procedures govern device clearance timelines, directly shaping R&D allocation and commercial launch sequencing for manufacturers. ISO standards for biocompatibility testing and Japan's PMDA quality management requirements further segment market access conditions across major jurisdictions. Stakeholders must monitor evolving sterilization validation protocols and reimbursement coding revisions for outpatient hysteroscopic procedures to anticipate volume shifts between inpatient and deployment settings.
Market Dynamics
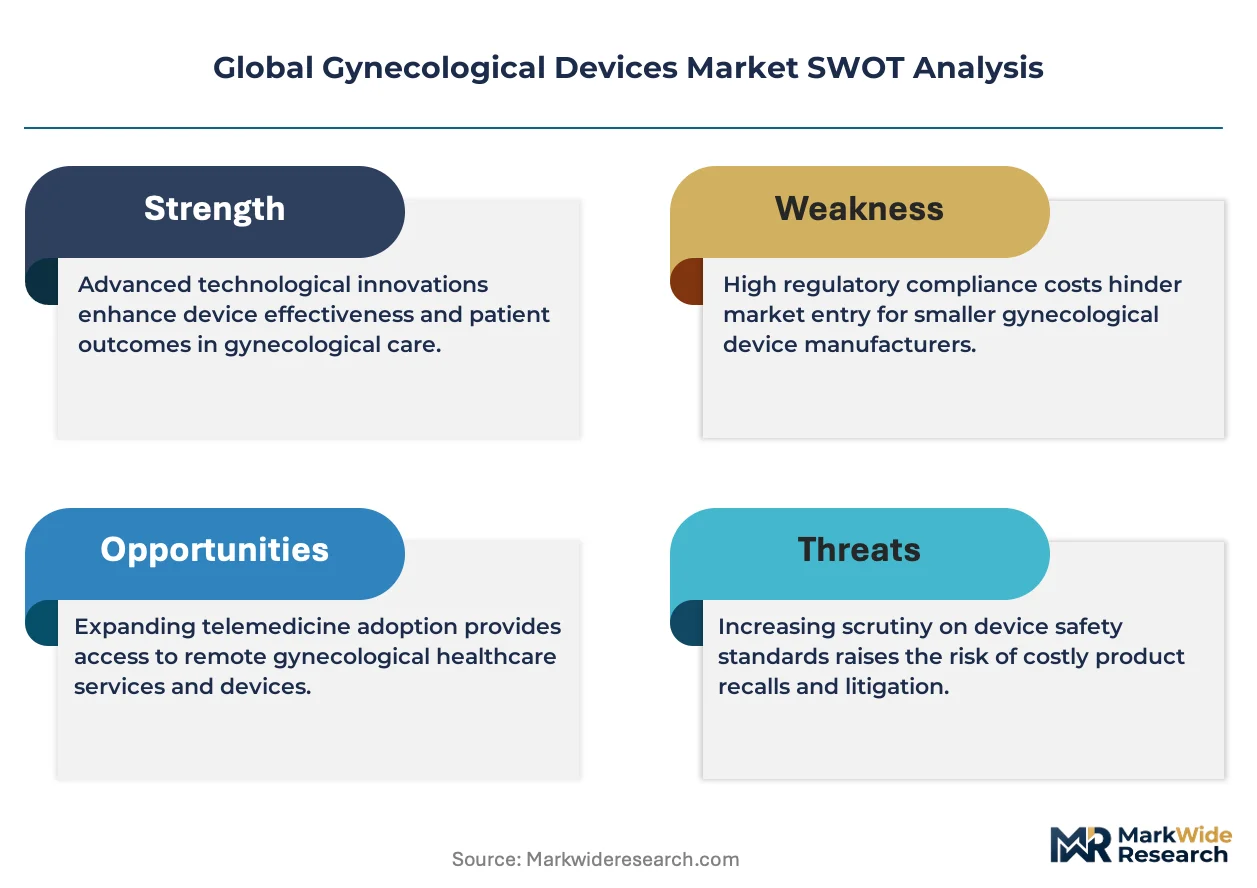
Single-use hysteroscopes are compressing reprocessing economics across outpatient networks, forcing capital equipment vendors to pivot toward disposable recurring revenue models. This shift restructures procurement relationships and margin capture away from upfront device sales.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket notification pathways for single-use endoscopes reduce commercialization timelines from 18 months to under 12 months, enabling faster product turnover.
- Ambulatory surgical center expansion:Freestanding ASCs in the United States now perform 65% of outpatient hysteroscopic procedures, creating concentrated demand for portable, sterilization-free instrument systems.
- Polymer composite materials:Medical-grade thermoplastics with comparable optical clarity to glass fibers enable cost-effective single-use manufacturing at scale.
Market Restraints
- EU MDR conformity assessment bottlenecks:Extended notified body capacity constraints delay CE marking for Class IIa surgical instruments by 8-14 months, freezing European launch schedules.
- Stainless steel supply concentration:Surgical-grade 316L sourcing depends on three German and Japanese specialty mills, exposing instrument manufacturers to alloying element price volatility.
- Reusable instrument residual value:Hospital systems with sunk capital in autoclave infrastructure resist full conversion to disposables, slowing category transition.
Strategic Opportunities
- India's CDSCO fast-track pathway:Accelerated approval for devices with prior US FDA or EU CE clearance opens access to 1.4 billion population reproductive health infrastructure.
- Teleconsultation-integrated diagnostic imaging:Cloud-connected ultrasound systems enable remote specialist interpretation, extending gynecological screening into rural and underserved markets.
- Japan's PMDA quality management harmonization:Mutual recognition agreements with ASEAN regulators create regional manufacturing hub potential for Japanese-certified producers.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face 6-month queue times at accredited laboratories, delaying prototype-to-submission cycles.
- Electrosurgical generator integration complexity:New disposable hysteroscopic electrodes require firmware compatibility validation across legacy energy platforms from multiple vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gynecological Devices Market |
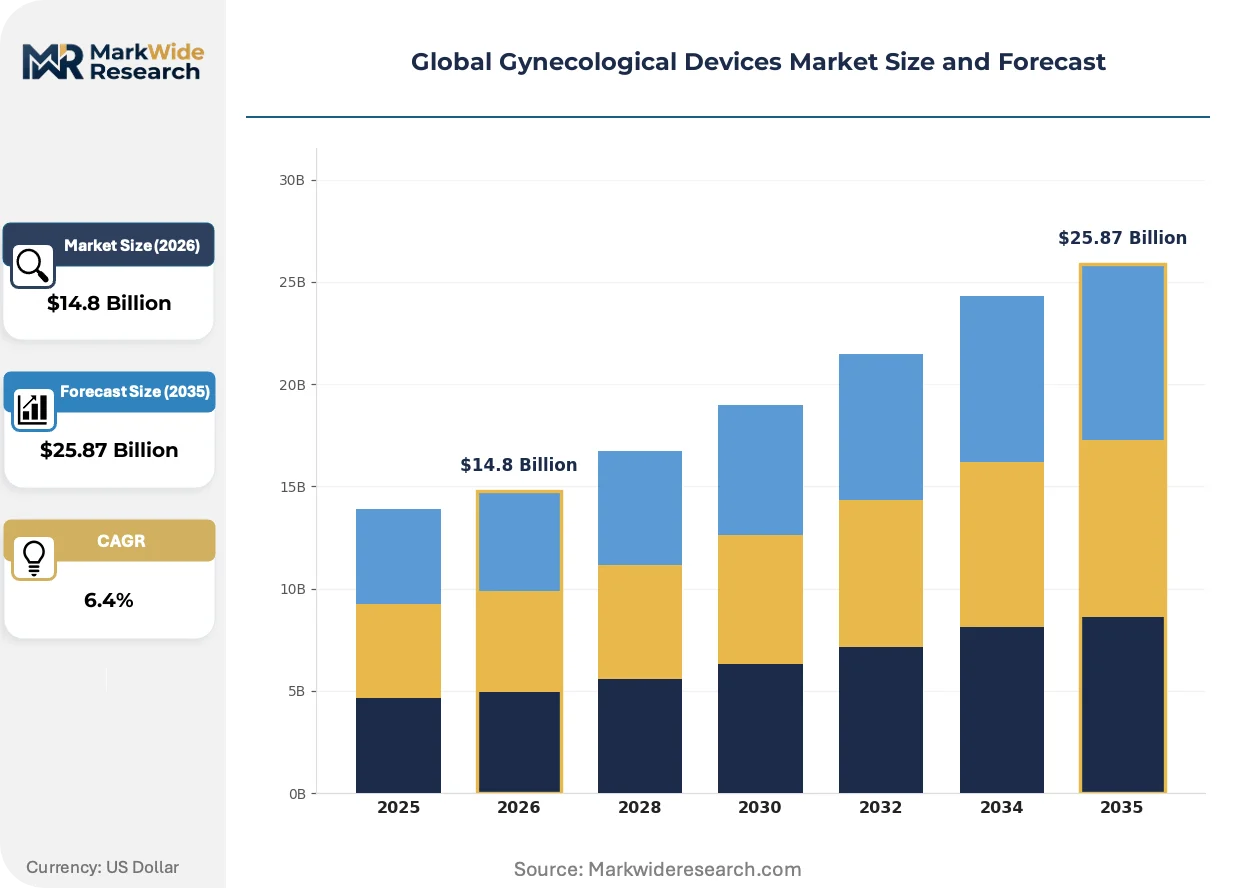
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hysteroscopes, Ultrasound Systems, Surgical Instruments, Diagnostic Kits, Catheters Application: Pelvic Organ Prolapse, Endometriosis, Uterine Fibroids, Infertility Treatments, Menstrual Disorders End User: Specialty Clinics, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutes, Academic Medical Centers Deployment: Inpatient Facilities, Outpatient Clinics, Mobile Health Units, Home Care Settings, Telehealth Platforms |
| Companies Covered | Hologic, Boston Scientific, Medtronic, CooperSurgical, Karl Storz, Stryker, Johnson & Johnson, Olympus, Richard Wolf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gynecological Devices Market Shifts & Advancements
Disposable visualization platforms are collapsing the economics of outpatient gynecological surgery, while regulatory harmonization efforts and buyer consolidation reshape competitive access. These forces compress innovation cycles and privilege integrated portfolio vendors.
Single-use hysteroscopes with integrated LED illumination and 1080p digital imaging are overtaking traditional fiber-optic reusable systems in ambulatory settings. United States-based ASC networks now specify disposable-only hysteroscopy suites to eliminate reprocessing labor and infection liability. This transition compresses capital equipment replacement cycles from seven years to per-procedure consumable purchasing.
EU MDR Article 10 post-market surveillance requirements now mandate systematic clinical follow-up data for Class IIa surgical instruments, elevating compliance costs for smaller manufacturers. German notified bodies have prioritized reproductive health device reviews, creating uneven access timelines across member states. Japanese manufacturers with pre-MDR legacy approvals leverage transitional provisions to maintain market presence while competitors face new clinical evidence barriers.
Bundled device contracts now dominate United States hospital network procurement, with single-source agreements covering hysteroscopes, electrosurgical generators, and imaging systems. Independent ASCs respond through group purchasing organizations that aggregate volume across 200-plus facilities. Germany exhibits similar concentration, where hospital system mergers in Bavaria and North Rhine-Westphalia have reduced qualified vendor lists to four integrated suppliers.
Global Gynecological Devices Market Segmentation
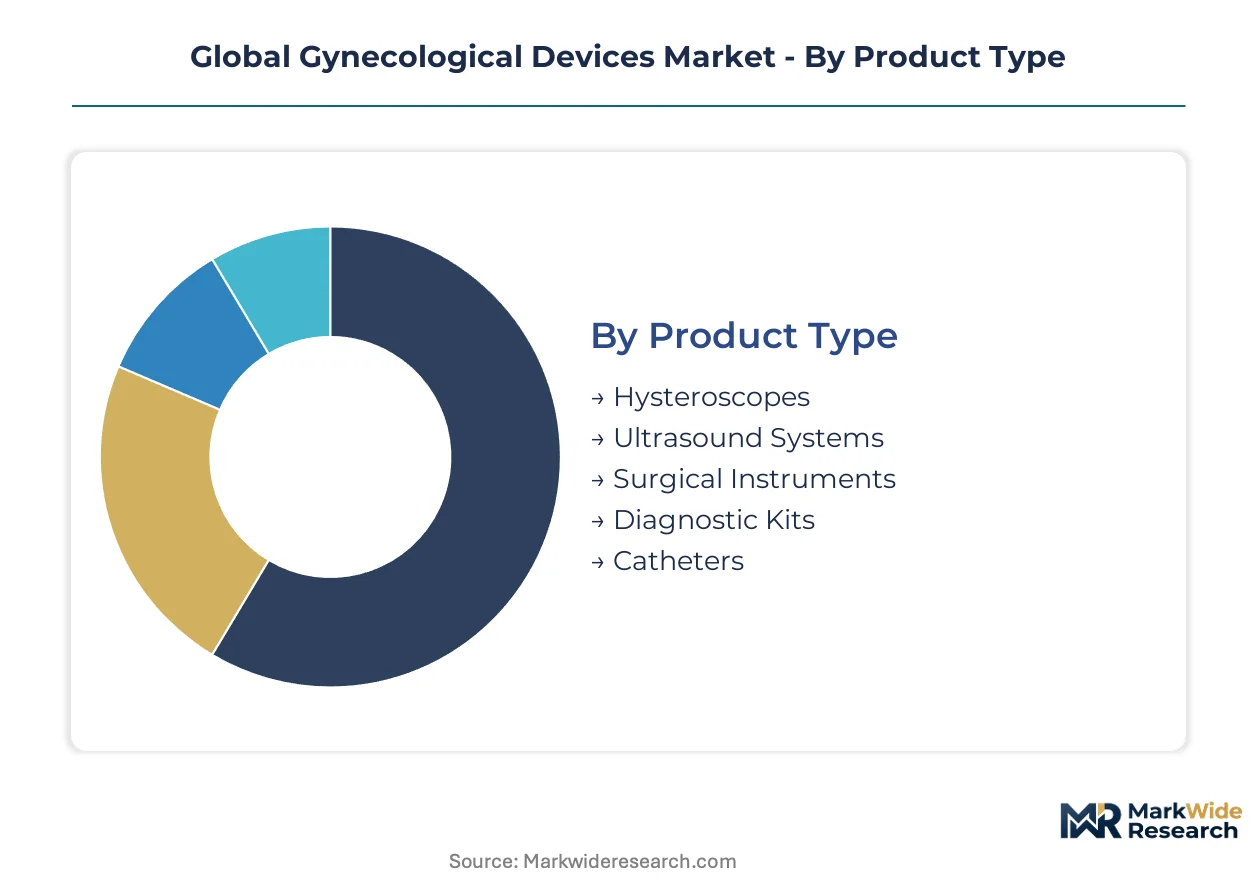
Gynecological device procurement varies sharply across clinical settings, with regulatory clearance tiers and sterilization requirements driving portfolio architecture. Manufacturers must align product specifications with specific FDA 510(k) or EU MDR pathways governing each segment's commercial trajectory.
Product Type:
FDA Class II 510(k) clearances dominate hysteroscope and surgical instrument submissions, while ultrasound systems face stricter diagnostic imaging quality standards under PMDA and Health Canada requirements.
- Hysteroscopes:Single-use polymer configurations with integrated LED illumination eliminate reprocessing infrastructure. ASC networks in the United States now specify disposable-only suites to reduce infection liability and labor overhead.
- Surgical Instruments:Electrosurgical devices for endometrial ablation and tissue resection command concentrated margin pools due to reusable-to-disposable transition dynamics and procedural complexity requirements.
- Ultrasound Systems:Mature replacement cycles in diagnostic centers concentrate demand in Germany and Japan.
- Diagnostic Kits:Cervical sampling and HPV testing consumables flow through bundled laboratory contracts.
- Catheters:Uterine and fallopian access devices serve fertility clinics with specialized delivery requirements.
Hysteroscopes sit at the top of the volume ranking, with surgical instruments climbing the fastest.
Application:
Procedure reimbursement codes determine device selection, with outpatient hysteroscopic interventions attracting distinct coding from inpatient surgical admissions.
- Uterine Fibroids:Myomectomy and ablation procedures drive demand for electrosurgical generators and tissue morcellation systems across United States hospital networks.
- Endometriosis:Laparoscopic excision requires specialized graspers and energy devices, with German clinics leading adoption of advanced bipolar systems.
- Infertility Treatments:Hysteroscopic tubal cannulation and embryo transfer catheters serve fertility specialists in Spain and the Czech Republic.
- Pelvic Organ Prolapse:Mesh and native tissue repair kits face varying regulatory acceptance across EU member states.
- Menstrual Disorders:Endometrial sampling devices and ablation systems address abnormal uterine bleeding in outpatient settings.
Uterine fibroids anchor procedure volume, though endometriosis interventions are gaining share fastest amid diagnostic awareness expansion.
End User:
Capital intensity and sterilization capability separate procurement patterns, with high-volume surgical centers favoring disposable platforms over capital equipment investments.
- Ambulatory Surgical Centers:Freestanding United States facilities perform the majority of outpatient hysteroscopic procedures, driving concentrated demand for portable, sterilization-free systems.
- Specialty Clinics:Fertility and reproductive health centers in Japan and South Korea prioritize imaging integration and cryopreservation compatibility.
- Diagnostic Centers:Ultrasound replacement cycles concentrate in urban hospital networks with radiology department consolidation.
- Academic Medical Centers:Teaching hospitals maintain reusable instrument fleets and autoclave infrastructure.
- Research Institutes:Clinical trial device procurement follows distinct IRB and investigational device exemption pathways.
Ambulatory surgical centers command the steepest volume trajectory, while academic medical centers exhibit slowest conversion to disposable platforms.
Deployment:
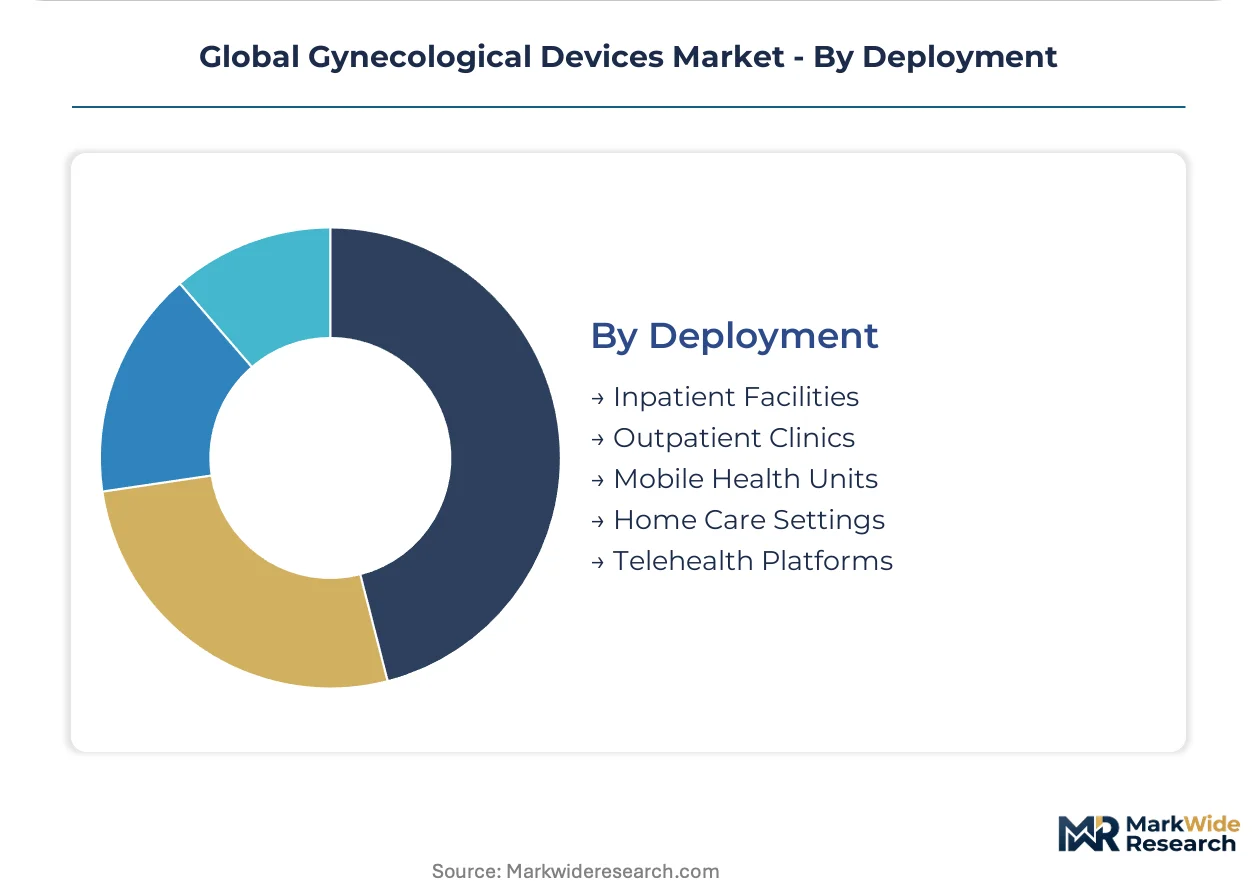
Site-of-care economics reshape device specifications, with reimbursement differentials between inpatient and outpatient settings driving procurement channel selection.
- Outpatient Clinics:United States-based networks specify single-use hysteroscopy suites to eliminate reprocessing labor and capital equipment depreciation.
- Inpatient Facilities:Hospital operating rooms retain reusable instrument systems and centralized sterilization departments.
- Telehealth Platforms:Remote consultation integration demands cloud-connected ultrasound systems with specialist interpretation capabilities.
- Mobile Health Units:Portable diagnostic imaging serves rural screening programs in India and Brazil.
- Home Care Settings:Fertility monitoring devices and patient-administered hormone testing kits expand access outside clinical facilities.
Outpatient clinics lead deployment volume, with telehealth platforms showing the most rapid expansion trajectory amid rural access initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The gynecological devices industry traces its modern commercial origins to German precision engineering clusters that pioneered rigid endoscopy in the 1960s, later scaling through Japanese fiber-optic innovations and United States disposable manufacturing platforms.
United States
FDA 510(k) clearance acceleration for single-use hysteroscopes drives procurement velocity at ambulatory surgical centers. The Consolidated Appropriations Act outpatient surgery reimbursement provisions favor same-day hysteroscopic procedures. Dallas-Fort Worth ASC networks now specify disposable-only suites, eliminating reprocessing infrastructure entirely.
Germany
EU MDR notified body capacity constraints delay CE marking timelines for Class IIa surgical instruments. The country's national pharmaceutical regulator enforces post-market surveillance mandates under Article 10 clinical follow-up requirements. Tuttlingen surgical instrument manufacturers face extended conformity assessment queues, compressing competitive access for smaller producers.
Japan
PMDA quality management harmonization with ASEAN regulators creates regional manufacturing hub positioning. METI medical device reimbursement pricing reforms incentivize domestic production of advanced bipolar energy systems. Osaka-based producers leverage transitional MDR provisions to maintain European market presence while competitors navigate new clinical evidence barriers.
India
CDSCO fast-track approval pathways for devices with prior FDA or CE clearance accelerate market entry. The country's national pharmaceutical regulator prioritizes reproductive health infrastructure expansion under national health mission programs. Maharashtra fertility clinic networks drive hysteroscopic tubal cannulation device procurement, supported by Mumbai diagnostic imaging distributor consolidation.
United Kingdom
NHS bundled procurement frameworks concentrate hospital network vendor selection to integrated portfolio suppliers. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements. London teaching hospitals retain reusable instrument fleets and centralized sterilization departments, slowing disposable platform conversion relative to outpatient networks.
Global Gynecological Devices Market Competitive Landscape
The competitive structure tilts toward integrated diagnostic-surgical portfolio vendors with established hospital network contracting relationships. Tier-one suppliers anchor bundled agreements spanning imaging systems, energy platforms, and disposable consumables. Mid-tier specialists occupy narrow verticals in fertility cryopreservation or advanced bipolar energy delivery. Dominant competitive moves include strategic partnerships for ASC network penetration and portfolio diversification into single-use visualization platforms.
Among United States-based diversified health technology conglomerates, Hologic and Boston Scientific occupy positions anchoring integrated diagnostic-imaging and specialized electrosurgical portfolios respectively. CooperSurgical represents the deep specialization archetype in fertility and obstetrics verticals. These three exemplify contrasting strategic postures: integrated breadth versus targeted depth versus disposable platform scale.
| Leading Market Players |
|---|
| Hologic |
| Boston Scientific |
| Medtronic |
| CooperSurgical |
| Karl Storz |
| Stryker |
| Johnson & Johnson |
| Olympus |
| Richard Wolf |
| Others |
Supply & Pricing Matrix
Medical-grade 316L stainless steel price indices cascade through German and Japanese specialty mill contracts into three-tier pricing structures across premium, standard, and economy device tiers. Procurement officers at United States ASC networks leverage volume aggregation through group purchasing organizations to compress standard-tier hysteroscope pricing, while premium-tier integrated imaging bundles retain pricing power through diagnostic-surgical workflow lock-in.
Pricing Analysis
Subscription-based consumable purchasing dominates hysteroscope procurement as single-use platforms displace capital equipment sales. Price differentiation hinges on FDA 510(k) clearance tier and optical resolution specification, with 1080p digital imaging systems commanding substantial premiums over standard-definition alternatives. Pricing pressure intensifies in standard-tier surgical instruments as Chinese polymer composite manufacturers enter European distribution channels. Ambulatory surgical centers exhibit acute price sensitivity, while academic medical centers with sunk autoclave infrastructure demonstrate inelastic demand for premium reusable systems.
Supply Chain Analysis
Medical-grade thermoplastic resin supply rests on German specialty chemical producers and Japanese polymer compounders with ISO 10993 biocompatibility certification. Surgical-grade 316L stainless steel draws from three German and Japanese specialty mills, while LED illumination modules source predominantly from South Korean semiconductor foundries. Single-source vulnerability concentrates in EU MDR notified body capacity for Class IIa conformity assessment. Distribution runs through hospital network procurement departments, group purchasing organizations, and specialized medical device distributors serving ASC networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gynecological devices market functions as a geographic-arbitrage play where EU MDR conformity assessment delays of 8-14 months create competitive entry windows for Japanese manufacturers with PMDA-ASEAN mutual recognition leverage.
For Market Incumbents: Deploy backward integration into medical-grade polymer compounding to secure thermoplastic supply continuity against alloying element price volatility. Anchor bundled diagnostic-surgical contracts across North American hospital networks before single-use hysteroscope commoditization erodes margin pools. Counter emerging Chinese polymer composite entrants through exclusive GPO agreements with United States ASC networks. For New Entrants and Emerging Players: Launch via telehealth-integrated diagnostic imaging partnerships targeting rural Indian markets under CDSCO fast-track pathways. Penetrate fertility clinic verticals in Spain and the Czech Republic through specialized hysteroscopic tubal cannulation devices. Exploit EU MDR Article 10 clinical follow-up gaps for Class IIa instruments to establish beachhead positions before incumbent transitional provisions expire. For Investors and Strategic Acquirers: Asymmetric upside sits with Japanese-certified manufacturers leveraging PMDA-ASEAN harmonization for regional hub positioning. Five-to-ten year viability favors integrated portfolio vendors with hospital network contracting relationships over single-product specialists facing reimbursement coding volatility. Monitor FDA 510(k) clearance acceleration timelines for single-use visualization platforms as inflection indicators for category transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket pathways compress commercialization timelines for single-use hysteroscopes under 12 months. |
| Hospital System Partnership | Bundled contracts spanning imaging, energy platforms, and consumables lock out competing vendors at ASC networks. |
| CE Marking Pathway Investment | German notified body prioritization for reproductive health devices creates uneven European access timelines. |
| Software Companion Development | Cloud-connected ultrasound systems enable remote specialist interpretation extending screening into rural markets. |
| Reimbursement Strategy | CMS outpatient surgery coding revisions directly shift procedure volume between inpatient and ambulatory settings. |
Research Methodology
Direct dialogue with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at notified bodies grounded qualitative insights. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR Article 10 post-market surveillance filings, CMS Medicare reimbursement coding updates, and hospital procurement database aggregators. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segment-level outputs reflect modeled trajectories across product type, application, end user, and deployment setting dimensions throughout the forecast period. CAGRs were derived from procedure volume elasticity to reimbursement coding, regulatory clearance velocity differentials, and materials cost trajectory assumptions. Industry-specific inputs incorporated sterilization infrastructure depreciation schedules and single-use conversion rates at United States ASC networks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body capacity constraints or abrupt stainless steel alloying element price spikes. Projections reflect assumptions regarding FDA 510(k) pathway continuity and outpatient surgery reimbursement stability. A small set of named triggers—PMDA-ASEAN mutual recognition expansion, CDSCO fast-track pathway revisions, and CMS coding updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
General Surgical Devices Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Tourniquet Systems Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Intervertebral Implants Market