
 Europe Spinal Fusion Devices Market | 2026-2036
Europe Spinal Fusion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Spinal Fusion Devices Market Insights
Titanium alloys are displacing stainless steel in posterior spinal instrumentation, and this material transition is realigning cost structures and supplier economics across European manufacturing chains. Medtronic leverages its Galway, Ireland facility to sustain high-volume production of porous titanium interbody cages for the EU market. Stryker competes through its European distribution network, which anchors its presence in German and French hospital systems. Zimmer Biomet differentiates via specialized instrumentation sets designed for minimally invasive lumbar approaches.
Europe spinal fusion devices encompass implantable systems and biologics engineered to immobilize vertebral segments and promote arthrodesis, typically incorporating titanium or PEEK constructs with surface modifications to enhance osseointegration. These devices serve the primary purpose of restoring spinal stability in patients with degenerative pathologies, deformities, or trauma-induced instability. Spinal instrumentation and interbody cages command the dominant share of product value, reflecting their essential role in construct biomechanics and their higher ASPs relative to bone graft substitutes. Minimally invasive surgery technology represents the fastest-expanding dimension, as hospitals prioritize reduced length of stay and lower complication rates in bundled payment environments.
The EU Medical Device Regulation (MDR) and CE marking framework now impose stricter clinical evaluation requirements on Class III implantable devices, extending approval timelines and elevating documentation costs for manufacturers seeking European market access. Germany's Federal Institute for Drugs and Medical Devices (BfArM) and France's ANSM enforce national vigilance protocols that shape post-market surveillance obligations and recall procedures across their respective jurisdictions. Stakeholders must monitor how notified body capacity constraints under MDR implementation continue to create bottlenecks for new product certifications.
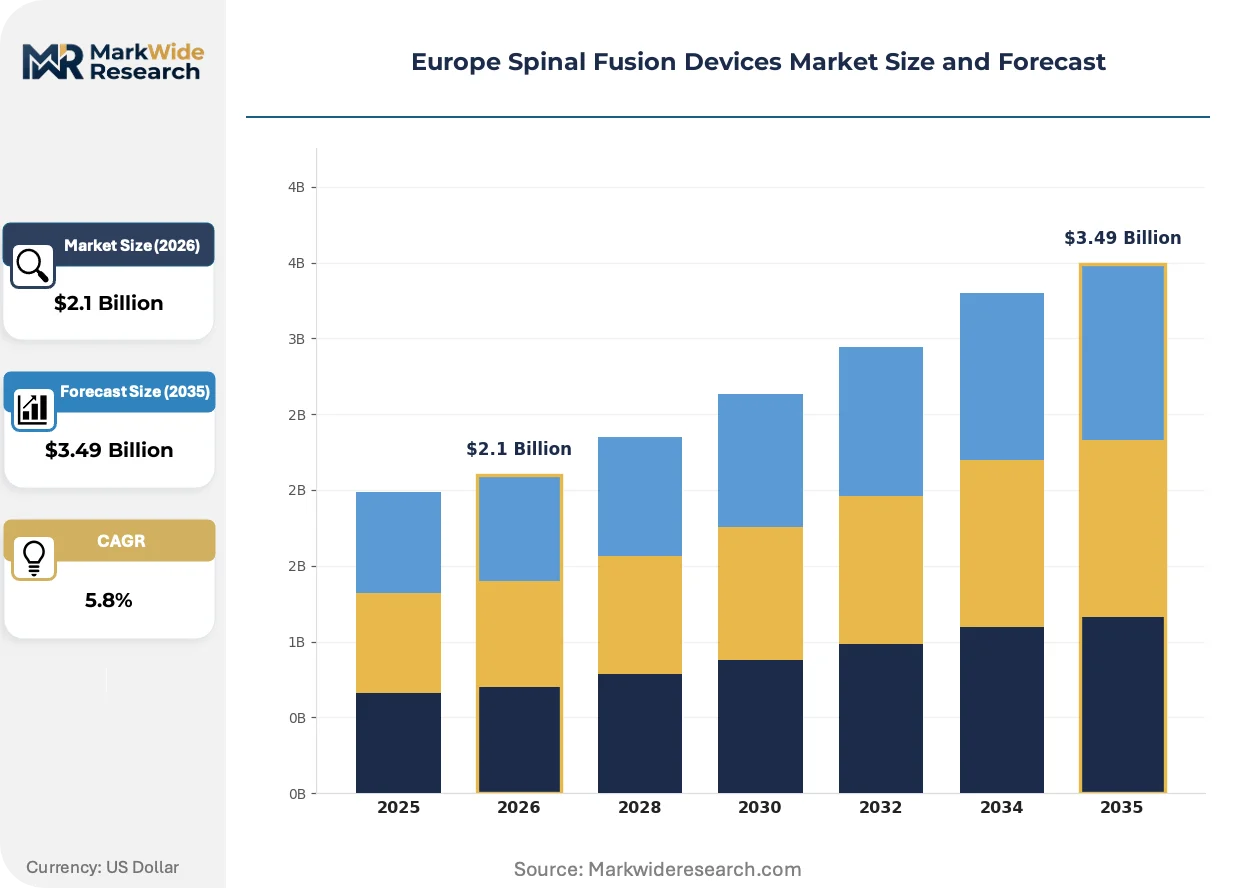
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product launch timelines while simultaneously elevating clinical evidence requirements, forcing manufacturers to restructure their European regulatory strategies around notified body capacity constraints and extended conformity assessment periods.
Growth Catalysts
- CE marking pathway expansion:The MDR's reinforced clinical evaluation requirements for Class III implantable devices is channeling investment toward robust post-market surveillance infrastructure across German and French hospital systems.
- Minimally invasive surgery technology:Hospitals in bundled payment environments are prioritizing reduced length of stay and lower complication rates, accelerating demand for specialized instrumentation sets designed for lumbar approaches.
- German spine center concentration:The country's dense network of specialized orthopedic facilities and favorable reimbursement frameworks is concentrating procedural volume and device procurement decisions.
Market Restraints
- Notified body capacity scarcity:MDR implementation bottlenecks are extending certification timelines for new interbody cage designs, delaying market entry by 12-18 months for some manufacturers.
- Titanium alloy cost volatility:The displacement of stainless steel in posterior instrumentation is exposing supply chains to raw material price swings from specialty metal refiners.
- Biologics substitution pressure:Bone graft substitutes and synthetic osteoinductive materials are capturing cases previously requiring fusion hardware in select degenerative indications.
Strategic Opportunities
- Eastern European procedural expansion:Poland and Czech Republic hospital systems are modernizing orthopedic departments, creating first-mover advantages for instrumentation suppliers establishing training partnerships.
- 3D-printed porous titanium convergence:Additive manufacturing with surface topology optimization is enabling patient-specific interbody geometries that accelerate osseointegration timelines.
- Day surgery regulatory tailwind:France's ANSM pathway simplifications for ambulatory spinal procedures is expanding addressable case volumes beyond traditional inpatient settings.
Industry Challenges
- Specialized surgical training deficits:Minimally invasive lumbar approaches require distinct technical competencies that outpace current fellowship program output in several European markets.
- MDR technical documentation burden:The expanded clinical evidence requirements for implantable devices are straining regulatory affairs teams and compressing R&D-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Spinal Fusion Devices Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Spinal Instrumentation, Fixed Stabilization Systems, Interbody Cages End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Technology: Bone Regeneration, Minimally Invasive Surgery, Biologics, Navigation Systems Application: Degenerative Disc Disease, Scoliosis, Spinal Fractures, Tumors |
| Companies Covered | Medtronic, Stryker, Zimmer Biomet, DePuy Synthes, Globus Medical, NuVasive, Orthofix Medical, B. Braun Melsungen, ATEC Spine, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Spinal Fusion Devices Market Trends and Innovations
Titanium surface engineering is actively compressing the boundary between implant biomechanics and biological response, with European manufacturers racing to integrate additive manufacturing capabilities ahead of notified body certification bottlenecks.
Porous titanium interbody cages with engineered surface roughness profiles are unifying mechanical load-bearing function with enhanced bone ingrowth kinetics. German university hospitals are adopting these constructs at accelerating rates for multi-level degenerative cases. The technology is unifying previously separate product categories—standard cages and biologic enhancers—into single-device solutions that simplify hospital supply chains.
The EU MDR's vigilance reporting requirements are reshaping post-market surveillance obligations across implantable device portfolios. Manufacturers must now maintain systematic clinical follow-up registries that extend far beyond legacy adverse event documentation. Spinal instrumentation with longer implantation lifecycles faces disproportionate documentation burdens, driving consolidation in product line strategies.
Hospital procurement committees are consolidating vendor relationships around full-procedure solution providers rather than discrete component suppliers. French and German buying groups are negotiating bundled contracts covering cages, screws, and biologics from single sources. This concentration is most visible in Germany's Rhineland hospital networks, where orthopedic service line directors now prioritize inventory simplification over component-level price competition.
Europe Spinal Fusion Devices Market Segmentation
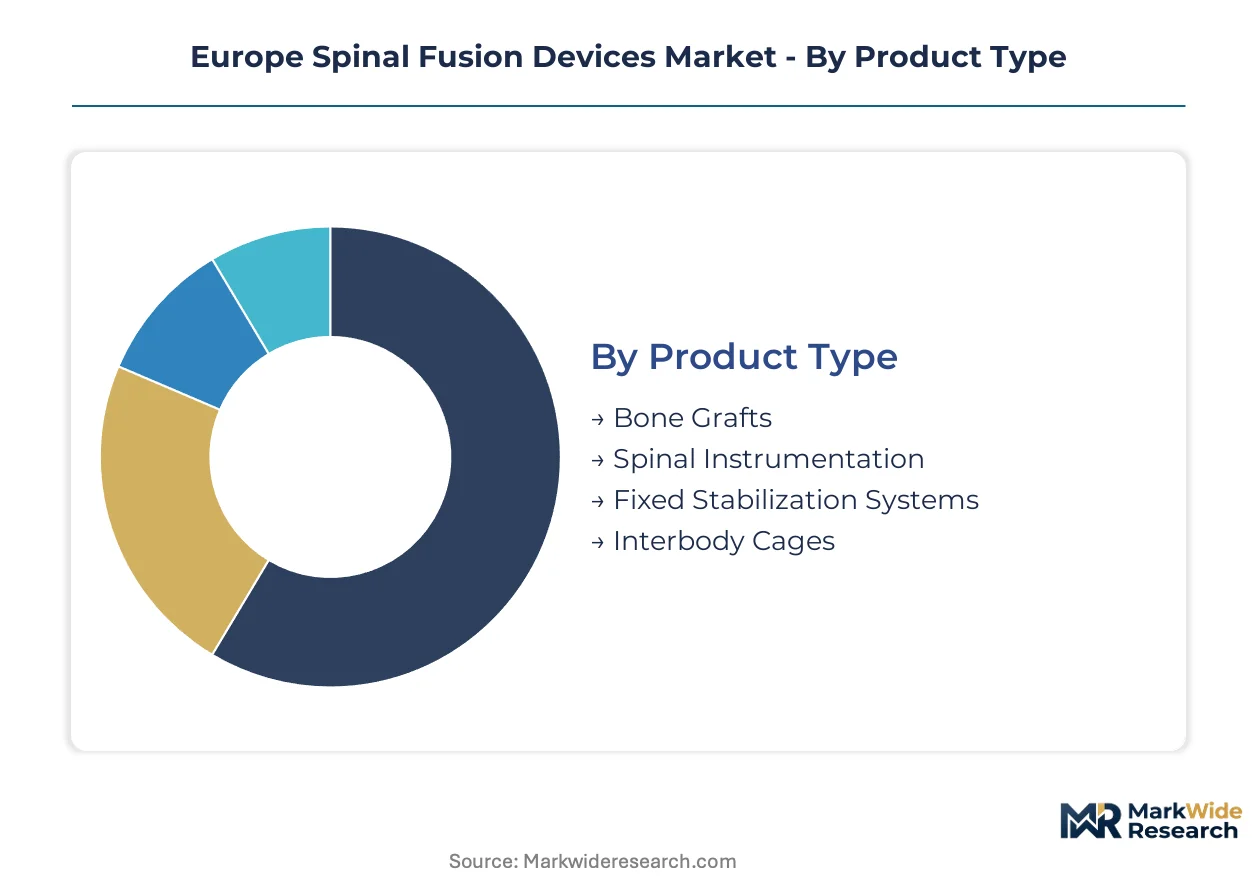
Segmentation in Europe spinal fusion devices reveals how procurement committees balance immediate surgical efficacy against long-term construct durability. Upgrade cycles vary dramatically across product categories, with instrumentation hardware refreshing every 5-7 years while biologic adjuncts turn over within 18-24 months.
Product Type:
Replacement intensity diverges sharply across hardware categories, with posterior instrumentation systems demanding capital-intensive refresh cycles while biologic components rotate through consumable replenishment models.
- Spinal Instrumentation:Titanium and cobalt-chrome constructs incorporating pedicle screws, rods, and connectors provide mechanical stabilization across multi-level fusions. German university hospitals in Munich and Heidelberg are consolidating procurement around single-vendor instrumentation platforms to reduce sterilization complexity and OR turnaround times.
- Interbody Cages:PEEK and porous titanium implants maintain disc height and promote arthrodesis through load-sharing biomechanics. French spine centers in Lyon and Paris are prioritizing 3D-printed titanium cages with engineered surface porosity to accelerate osseointegration in elderly osteoporotic patients.
- Bone Grafts:Autograft, allograft, and synthetic osteoconductive materials fill interbody spaces to stimulate fusion mass formation. Procurement runs through hospital pharmacy committees with quarterly volume commitments.
- Fixed Stabilization Systems:Rigid constructs immobilizing vertebral segments through screw-rod assemblies. Demand concentrates in trauma cases requiring immediate mechanical stability.
Volume placements concentrate in Spinal Instrumentation; the faster expansion belongs to Interbody Cages.
End User:
Site-of-care economics are fragmenting the customer base, with ambulatory migration in France and Germany creating distinct purchasing behaviors between high-acuity hospitals and streamlined surgical facilities.
- Hospitals:Tertiary and secondary acute care facilities performing complex multi-level fusions and deformity corrections. Germany's Rhineland hospital networks anchor regional procurement concentration through orthopedic service line consolidation.
- Surgical Centers:Ambulatory facilities performing single-level decompressions and instrumented fusions under enhanced recovery protocols. France's ANSM pathway simplifications are accelerating case volume migration to these settings around Paris and Marseille.
- Orthopedic Clinics:Specialist practices managing pre-operative workup and post-operative rehabilitation. Patient funnel relationships influence implant selection upstream.
- Rehabilitation Centers:Post-acute facilities monitoring fusion maturation and functional recovery. Device selection impact is indirect through outcome reporting.
Revenue gravity sits with Hospitals; Surgical Centers are climbing the fastest as ambulatory eligibility expands.
Technology:
Capability investment cycles separate established platforms from emerging modalities, with navigation and biologics commanding disproportionate R&D allocation against mature hardware systems.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reducing tissue disruption and blood loss. German spine centers in Berlin and Hamburg are prioritizing specialized instrumentation sets that enable lateral and oblique lumbar approaches with reduced length of stay.
- Biologics:Bone morphogenetic proteins, demineralized bone matrices, and synthetic osteoinductive materials enhancing fusion biology. France's ANSM maintains distinct vigilance protocols for these products compared to hardware devices.
- Bone Regeneration:Cellular and acellular therapies stimulating osteoblast differentiation and vascular ingrowth. Clinical evidence requirements under EU MDR are extending development timelines.
- Navigation Systems:Intraoperative imaging and robotic guidance improving screw placement accuracy. Capital equipment sales cycle is elongated by hospital budget committee review.
Procurement volume favors Minimally Invasive Surgery; Navigation Systems show the steepest expansion trajectory as accuracy demands intensify.
Application:
Indication severity and patient age profile determine construct complexity, with deformity cases requiring comprehensive instrumentation against simpler trauma or degenerative presentations.
- Degenerative Disc Disease:Spondylosis and disc collapse driving single and multi-level anterior and posterior fusions. Germany's aging demographics are concentrating procedural volume in specialized spine centers across Bavaria and Baden-Württemberg.
- Scoliosis:Deformity correction requiring extensive posterior instrumentation with osteotomy techniques. French and German pediatric and adult deformity programs anchor regional referral patterns.
- Spinal Fractures:Traumatic instability requiring short-segment stabilization. Acute care pathways compress decision timelines.
- Tumors:Oncologic resection and reconstruction with expandable cages and long-segment constructs. Case complexity demands multidisciplinary coordination.
Procedure volume concentrates in Degenerative Disc Disease; Scoliosis applications are gaining share fastest as adult deformity recognition improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical technology zones in Ireland and Germany are concentrating spinal device manufacturing, with Galway's medtech cluster anchoring EU production capacity for porous titanium implants.
Germany
Bavaria and Baden-Württemberg host dense networks of university spine centers performing complex multi-level fusions. BfArM enforces national vigilance protocols that shape post-market surveillance obligations for implantable devices. The Rhineland hospital networks concentrate procurement decisions through orthopedic service line consolidation around Cologne and Düsseldorf.
France
Aging demographics in Île-de-France and Provence-Alpes-Côte d'Azur are driving procedural volume for degenerative disc disease interventions. ANSM pathway simplifications for ambulatory spinal procedures are expanding case volumes beyond traditional inpatient settings. Lyon and Paris spine centers prioritize 3D-printed titanium cages with engineered surface porosity for elderly osteoporotic patients.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex deformity surgery in designated tertiary centers across London and the Midlands. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines for certain device categories. The Oxford-Cambridge-London arc anchors academic-industrial collaboration on navigation-guided spinal instrumentation.
Switzerland
Swissmedic maintains distinct approval pathways for high-risk implantable devices that run parallel to EU MDR certification. Basel and Zurich host concentrated orthopedic research institutes collaborating with German surgical centers. The country's precision manufacturing base supplies specialized instrumentation components to EU assemblers.
Poland
Hospital systems in Warsaw and Kraków are modernizing orthopedic departments with EU structural fund support. The national reimbursement agency is expanding coverage for minimally invasive lumbar procedures. Training partnerships with German spine centers are transferring technical competencies for lateral and oblique surgical approaches.
Europe Spinal Fusion Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-procedure solution providers capturing hospital procurement committee preference over discrete component suppliers. The vendor base concentrates around three strategic tiers: diversified orthopedic conglomerates with European distribution networks, mid-cap spine specialists with differentiated minimally invasive platforms, and regional fabricators supplying instrumentation blanks and surface-modified titanium blanks. M&A activity targets navigation and robotics capabilities, while capacity expansion concentrates in Ireland and Switzerland to maintain EU market access under MDR compliance requirements.
Among diversified orthopedic conglomerates, Medtronic, Stryker, and Zimmer Biomet occupy positions that exemplify different competitive vectors. Medtronic represents the vertically integrated archetype with captive manufacturing in Ireland. Stryker exemplifies distribution-network dominance anchored in German and French hospital procurement channels. Zimmer Biomet sits within the specialization tier, its positioning reflecting differentiated instrumentation design for specific surgical approaches. These three anchors illustrate how scale, geographic coverage, and technical focus split available share in European spinal fusion procurement.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Zimmer Biomet |
| DePuy Synthes |
| Globus Medical |
| NuVasive |
| Orthofix Medical |
| B. Braun Melsungen |
| ATEC Spine |
| Others |
Pricing and Supply Chain Analysis
German and French hospital procurement committees are consolidating vendor relationships around full-procedure solution providers, forcing suppliers to bundle cages, screws, and biologics into single-source contracts that compress component-level margins while rewarding inventory simplification.
Pricing Analysis
Short lead-time premiums for MDR-certified interbody cages command pricing advantages over spot inventory from non-EU sources awaiting notified body recertification. Three-tier pricing structure across premium, standard, and economy levels separates 3D-printed porous titanium constructs from conventional PEEK cages and basic stainless steel instrumentation. Cost compression in standard-tier posterior instrumentation is intensifying because of raw material volatility from specialty metal refiners. Ambulatory surgical centers in France exhibit the highest price sensitivity, while German university spine centers prioritize construct durability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for explanted spinal instrumentation are minimal given permanent implantation, though instrument tray refurbishment cycles every 5-7 years create secondary service revenue streams for manufacturers. Manufacturing concentrates in Ireland, Switzerland, and Germany, with Galway's medtech cluster anchoring EU production of porous titanium interbody cages. Supply chains rest on titanium sponge from specialty refiners, PEEK polymer from industrial chemical suppliers, and precision-machined instrumentation blanks. Single-source vulnerability exists for additive manufacturing feedstock certified to MDR biocompatibility standards. Distribution runs through hospital procurement committees and orthopedic service line directors rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe spinal fusion devices market is becoming a vertical-integration race, with manufacturers pursuing captive production of porous titanium feedstock to secure MDR-compliant supply chains against notified body certification bottlenecks.
For Market Incumbents: Hedge against biologics substitution pressure by deepening backward integration into surface-modified titanium production and expanding training partnerships with Polish and Czech hospital systems. Lock in multi-year procurement contracts with Rhineland hospital networks before ambulatory migration fragments purchasing volume. For New Entrants and Emerging Players: Direct-to-surgeon digital education platforms offer lower-friction entry than traditional distributor relationships, particularly for minimally invasive instrumentation sets targeting French surgical centers. Prioritize 3D-printed patient-specific cage geometries where regulatory pathways remain unsettled and incumbent documentation advantages are weakest. For Investors and Strategic Acquirers: The window for entry favors mid-cap spine specialists with differentiated additive manufacturing capabilities and existing CE marking under MDR transition provisions. Monitor notified body capacity expansion announcements as the inflection indicator for certification timeline normalization and new product launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements extend timelines for Class III implantable devices. |
| Hospital System Partnership | German Rhineland networks consolidate procurement around single-vendor instrumentation platforms. |
| Backward Integration | Captive porous titanium production secures supply against specialty refiner volatility. |
| Software Companion Development | Navigation-guided screw placement systems require capital equipment sales cycles through budget committees. |
| Reimbursement Strategy | France's ANSM ambulatory pathway simplifications expand addressable case volumes beyond inpatient settings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. BfArM vigilance databases, ANSM market surveillance reports, notified body capacity disclosures, and EU MDR technical documentation guidelines provided regulatory context. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations across product categories.
Granularity-level modeling captured interbody cages, spinal instrumentation, and biologics as distinct product types; hospitals, surgical centers, and orthopedic clinics as end-user channels; and minimally invasive surgery, navigation systems, and biologics as technology modalities. CAGRs were derived from procedure volume trajectories, ASP erosion curves, and ambulatory migration rates across the analysis window. Forecast inputs included aging demographic projections, MDR implementation timelines, and bundled payment penetration assumptions.
The model holds under stable notified body capacity and continued German reimbursement favorability; deviation in MDR enforcement intensity or ambulatory eligibility expansion would shift volume and value trajectories. Practitioners should monitor ANSM pathway announcements and BfArM vigilance reporting thresholds for early signals of regulatory environment evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Annuloplasty System Market
Medical Devices
Pipetting Systems Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Manometry System Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Medical Injection Molding Machine Market