
 Global Hernia Repair Devices Market | 2026-2036
Global Hernia Repair Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hernia Repair Devices Market Foresight
The EU Green Deal's circular-economy mandate for medical plastics is consolidating procurement criteria across European hospital networks. Medtronic plc leverages its laparoscopic platform breadth to sustain recurring revenue from fixation device consumables. Baxter International Inc. anchors its position through in-house production of biological graft substrates.
Hernia repair devices encompass synthetic and biologically derived implants, mechanical fixation systems, and specialized instrumentation designed to reinforce abdominal wall defects under physiological load conditions, typically manufactured from polypropylene, polyester, or porcine dermal collagen matrices. These products restore fascial integrity and prevent recurrence in ventral, inguinal, and diaphragmatic hernias. Mesh implants generate the deepest margin pools due to recurring revision procedures, while robotic-assisted technology commands premium pricing despite slower penetration. Laparoscopic approaches dominate volume in ambulatory settings where faster recovery drives patient throughput.
The FDA's 510(k) pathway demands substantial equivalence benchmarks for novel mesh compositions, while EMA's MDR transition extends clinical evaluation timelines for European market access. Japan's PMDA imposes additional biocompatibility testing protocols on permanent synthetic meshes. Stakeholders must monitor evolving reimbursement thresholds for outpatient robotic procedures against shifting biological graft adoption curves.
Market Dynamics
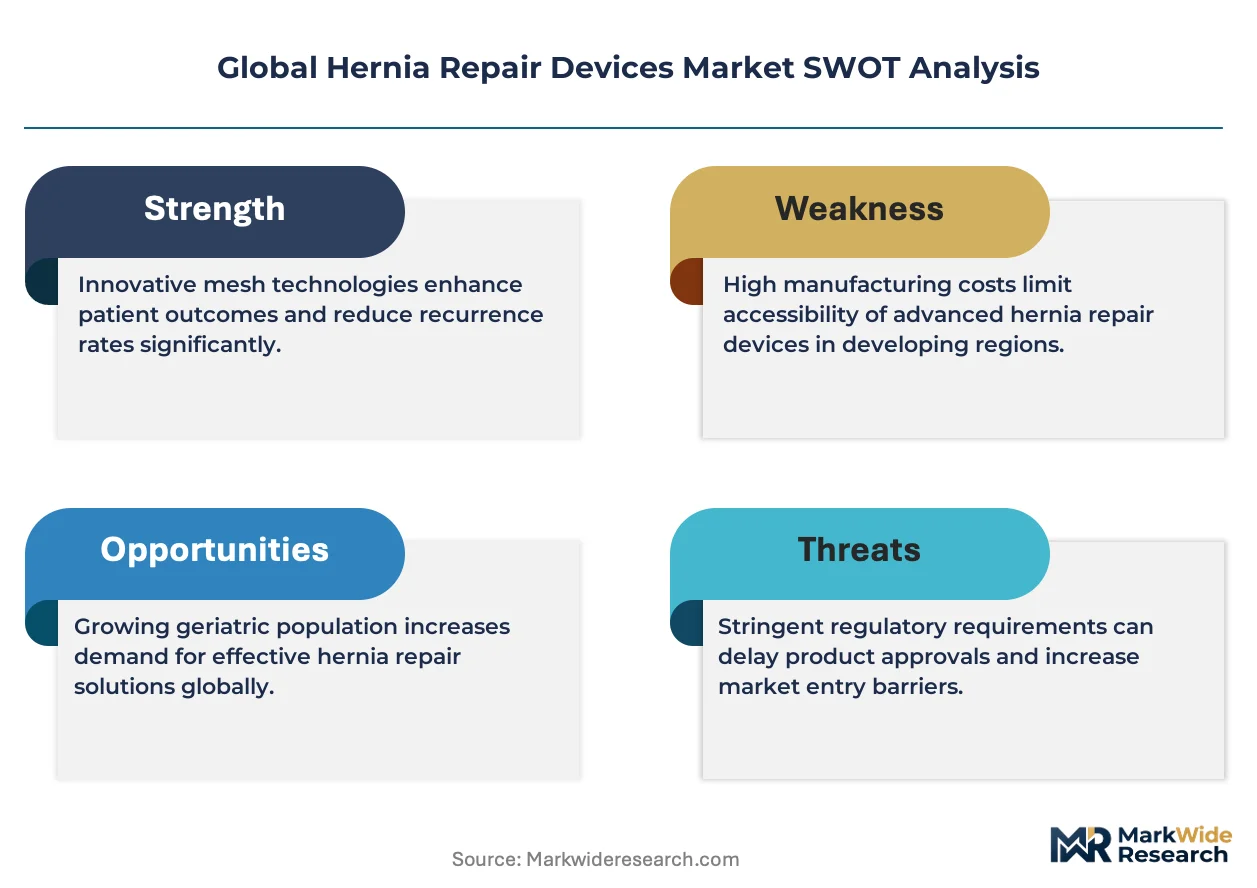
The EU Medical Device Regulation's tightened clinical evidence requirements for permanent implants are compressing approval timelines and forcing manufacturers to restructure R&D budgets toward longitudinal safety studies rather than incremental product iterations.
Growth Catalysts
- Outpatient surgical infrastructure:Ambulatory surgery centers in the United States, Germany, and China are expanding capacity for minimally invasive hernia procedures, creating volume pull for fixation device consumables and specialized laparoscopic instrumentation.
- Biological graft substrates:Porcine dermal collagen matrices command premium pricing in revision cases where synthetic mesh complications have accumulated, expanding addressable patient populations beyond primary repair.
- REACH circular-economy mandates:The EU Green Deal's medical plastics recycling requirements are consolidating procurement criteria across European hospital networks, favoring suppliers with verified sustainable manufacturing footprints.
Market Restraints
- Polypropylene raw material concentration:Synthetic mesh production depends on petrochemical feedstocks subject to energy price volatility and geographic supply concentration in Gulf Coast refineries.
- PMDA biocompatibility testing:Japan's permanent synthetic mesh protocols add 18-24 months to market access timelines, creating regulatory friction against standardized global product launches.
- Chronic pain litigation exposure:Historical product liability settlements involving certain mesh compositions have elevated insurance costs and dampened physician willingness to adopt novel synthetic formulations.
Strategic Opportunities
- Robotic-assisted ventral repair:Underpenetrated adoption of robotic platforms in Indian and Brazilian tertiary hospitals creates whitespace for premium-priced integrated mesh-fixation systems.
- Same-day discharge protocols:CMS reimbursement thresholds for outpatient robotic procedures in the United States are expanding eligible case volumes beyond traditional inpatient settings.
- 3D-printed patient-specific implants:Convergence of additive manufacturing with preoperative CT modeling enables anatomically matched mesh geometries for complex multi-recurrence defects.
Industry Challenges
- MDR technical documentation:The EU's extended clinical evaluation timelines for Class III implantable devices strain regulatory affairs staffing and compress product refresh cycles.
- Laparoscopic skill acquisition:Tension-free mesh placement in minimally invasive inguinal repair requires specialized training pathways that outpace current fellowship program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hernia Repair Devices Market |
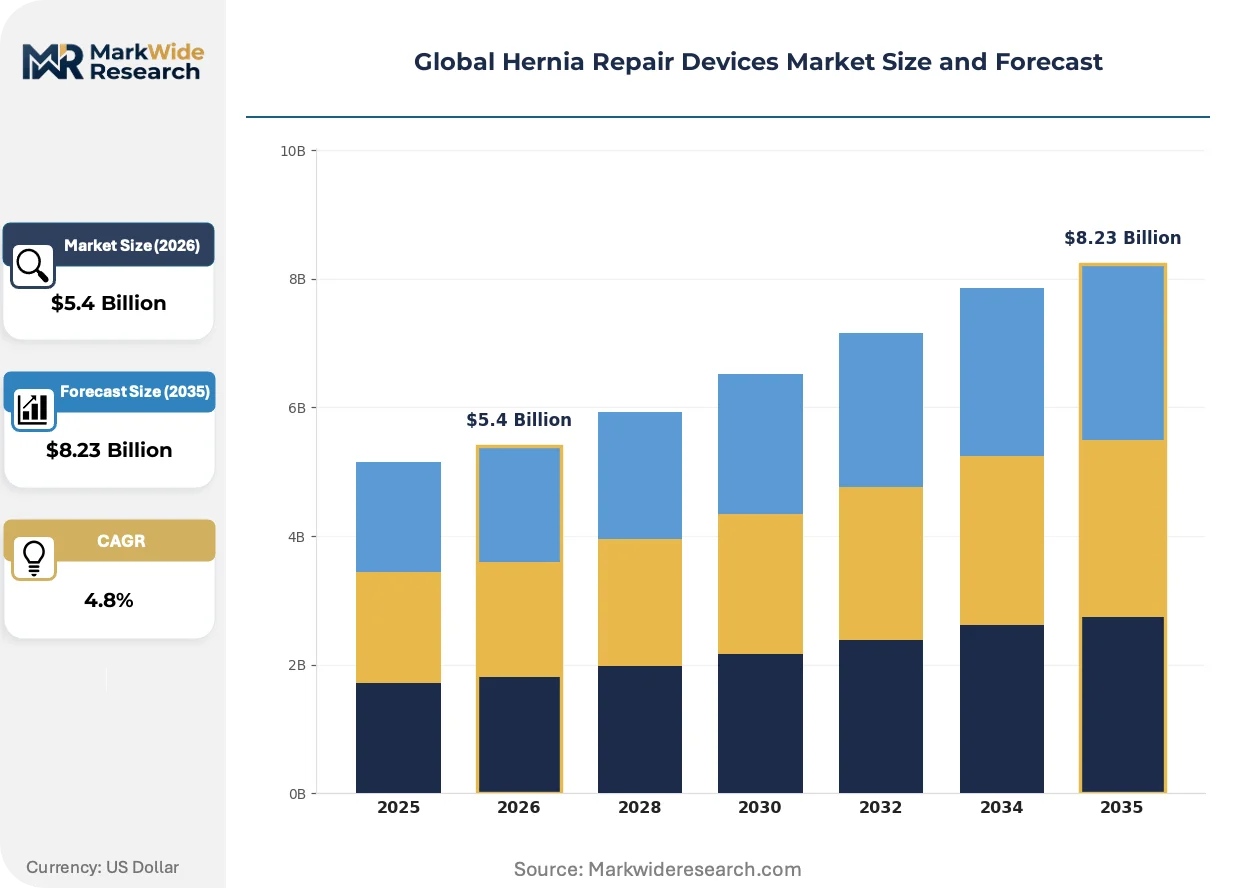
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh Implants, Fixation Devices, Surgical Instruments, Biological Grafts, Adhesives Technology: Laparoscopic, Robotic-Assisted, Open Surgery, Tension-Free Repair, Mesh-Free Repair Application: Inguinal Repair, Femoral Repair, Umbilical Repair, Incisional Repair, Hiatal Repair End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Physician Offices |
| Companies Covered | B. Braun SE, Cook Medical, Medtronic plc, Baxter International Inc., AbbVie Inc., Ethicon Inc., W. L. Gore & Associates, Integra Lifesciences, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hernia Repair Devices Market Shifts & Advancements
Device miniaturization and materials science advances are compressing the invasiveness gradient between open and laparoscopic approaches, while regulatory convergence pressures are standardizing safety documentation across historically fragmented national frameworks.
Absorbable synthetic meshes incorporating polylactic acid copolymers are decentralizing the hernia repair site-of-care by enabling earlier return-to-activity protocols. Ambulatory surgery centers in Germany and the United States are adopting these formulations for selected inguinal cases previously routed to inpatient facilities. The structural consequence is a compression of average length-of-stay metrics that shifts revenue capture toward preoperative planning and postoperative monitoring services rather than bed-day billing.
The FDA's 510(k) substantial equivalence pathway for novel mesh compositions now demands expanded predicate device safety profiles, extending premarket notification review cycles. Manufacturers are responding by consolidating product pipelines around established material platforms rather than pioneering unproven chemistries. Synthetic polyester meshes with decade-long implant histories are capturing disproportionate regulatory bandwidth compared to experimental biological alternatives.
Hospital procurement departments are unbundling mesh-implant purchasing from bundled procedure payments, creating direct price transparency that compresses manufacturer margins. Group purchasing organizations in the United States are consolidating contract awards across multi-hospital systems, displacing individual facility-level negotiations. This concentration is most visible in Midwestern integrated delivery networks where standardized mesh specifications now span 15-20 affiliated surgical centers.
Global Hernia Repair Devices Market Segmentation
Hernia repair device purchasing decisions pivot on procedure reimbursement rates, surgical site-of-care migration, and patient risk stratification for synthetic versus biological materials. Segmentation reveals how technology adoption curves diverge across ambulatory and inpatient settings, with fixation device consumables capturing recurring revenue streams distinct from capital-intensive robotic platforms.
Product Type:
Hospital procurement departments weigh upfront implant costs against revision surgery liability exposure when selecting product categories.
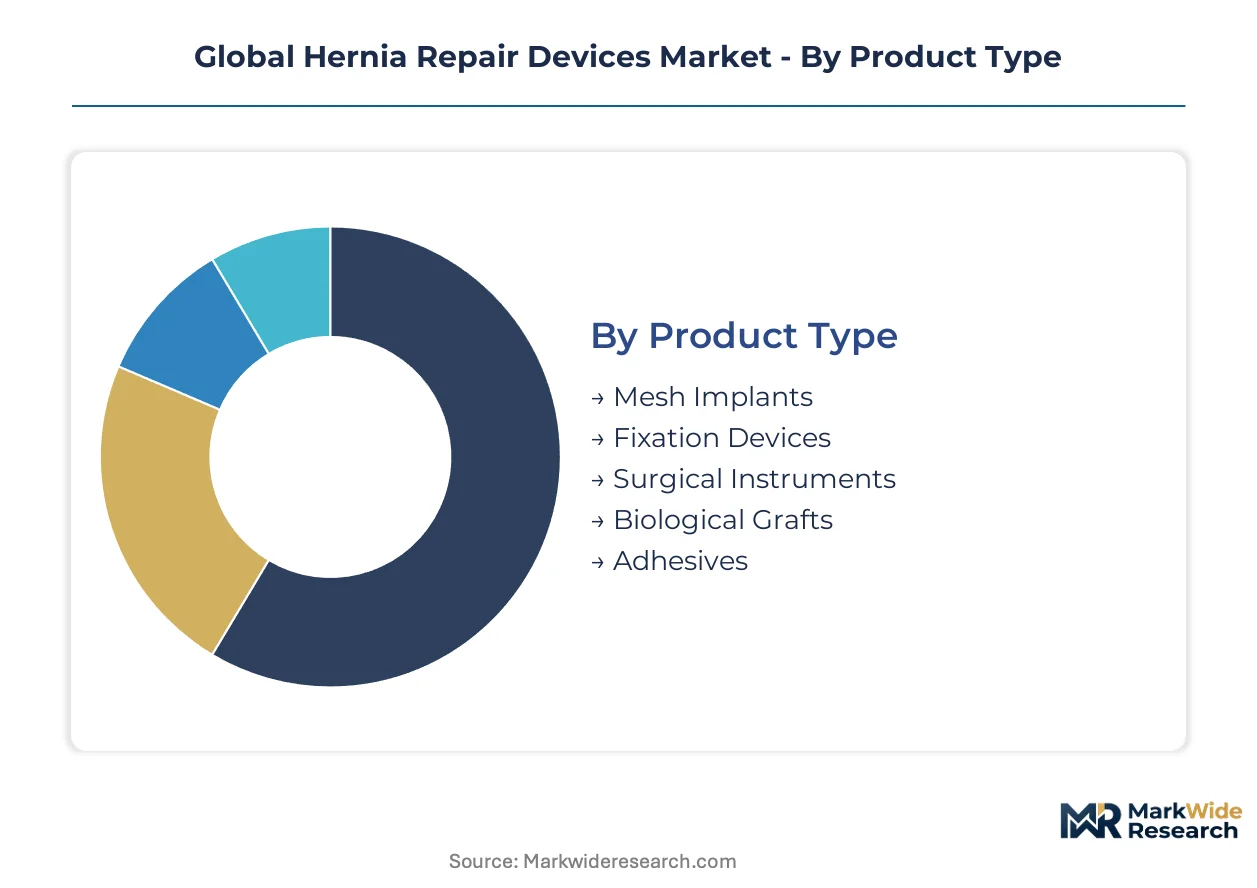
- Mesh Implants:Polypropylene and polyester meshes dominate ventral and inguinal repairs, with porcine dermal collagen matrices commanding premium positioning in contaminated fields. United States ambulatory surgery centers drive volume for lightweight macroporous formulations that enable same-day discharge protocols.
- Fixation Devices:Tacks, anchors, and suture-based systems secure mesh placement in laparoscopic procedures. German hospital networks concentrate demand for absorbable fixation alternatives that eliminate chronic foreign body response in thin-patient populations.
- Surgical Instruments:Graspers, dissecting forceps, and trocar systems enable minimally invasive access. Standardized laparoscopic toolsets face pricing pressure from group purchasing organization consolidation.
- Biological Grafts:Acellular dermal matrices derived from human or animal tissue address complex multi-recurrence defects. Premium pricing limits adoption to revision cases and high-risk surgical fields in tertiary referral centers.
- Adhesives:Synthetic sealants and fibrin-based products augment mechanical fixation in selected ventral repairs. Limited clinical evidence constrains penetration beyond investigational protocols.
Mesh implants lead on scale; biological grafts lead on momentum.
Technology:
Reimbursement differentials between inpatient and outpatient settings accelerate platform migration decisions.
- Laparoscopic:Minimally invasive approaches utilizing insufflation and camera guidance enable bilateral inguinal repair through single-access techniques. China invests in laparoscopic training infrastructure to expand rural surgical capacity.
- Robotic-Assisted:Da Vinci and competing platforms command per-procedure premiums for ventral hernia repair. Indian tertiary hospitals represent underpenetrated whitespace for integrated mesh-fixation system placement.
- Open Surgery:Traditional tissue approximation without mesh reinforcement persists in resource-constrained settings and contaminated wound scenarios.
- Tension-Free Repair:Lichtenstein and similar techniques using mesh reinforcement without suture tension dominate inguinal repair volume in United States community hospitals.
- Mesh-Free Repair:Pure tissue repair with autologous flap reconstruction addresses selected umbilical and small ventral defects. Limited to pediatric populations and mesh-contraindicated patients.
Laparoscopic approaches anchor current volume; robotic-assisted systems climb the fastest.
Application:
Patient anatomy and hernia etiology determine mesh selection criteria and procedural complexity tiers.
- Inguinal Repair:Indirect and direct inguinal defects constitute the highest-volume application segment. Lightweight polypropylene meshes with large pore sizes reduce chronic pain incidence in United States male patient populations.
- Incisional Repair:Ventral defects arising from prior surgical wounds demand larger mesh footprints and complex fixation patterns. German university hospitals pioneer 3D-printed patient-specific implants for multi-recurrence cases.
- Femoral Repair:Narrow canal defects in female patients require specialized mesh geometries. Lower absolute volume concentrates in European surgical practices with higher female hernia diagnosis rates.
- Umbilical Repair:Congenital and acquired paraumbilical defects favor small-format meshes in outpatient settings. Pediatric applications drive biological graft preference to accommodate growth.
- Hiatal Repair:Diaphragmatic defects at the esophageal hiatus combine mesh reinforcement with fundoplication techniques. Reflux disease comorbidity expands addressable patient pools in aging United States demographics.
Inguinal repair leads on scale; incisional repair gains share fastest.
End User:
Capital equipment requirements and case-mix complexity stratify purchasing authority across delivery settings.
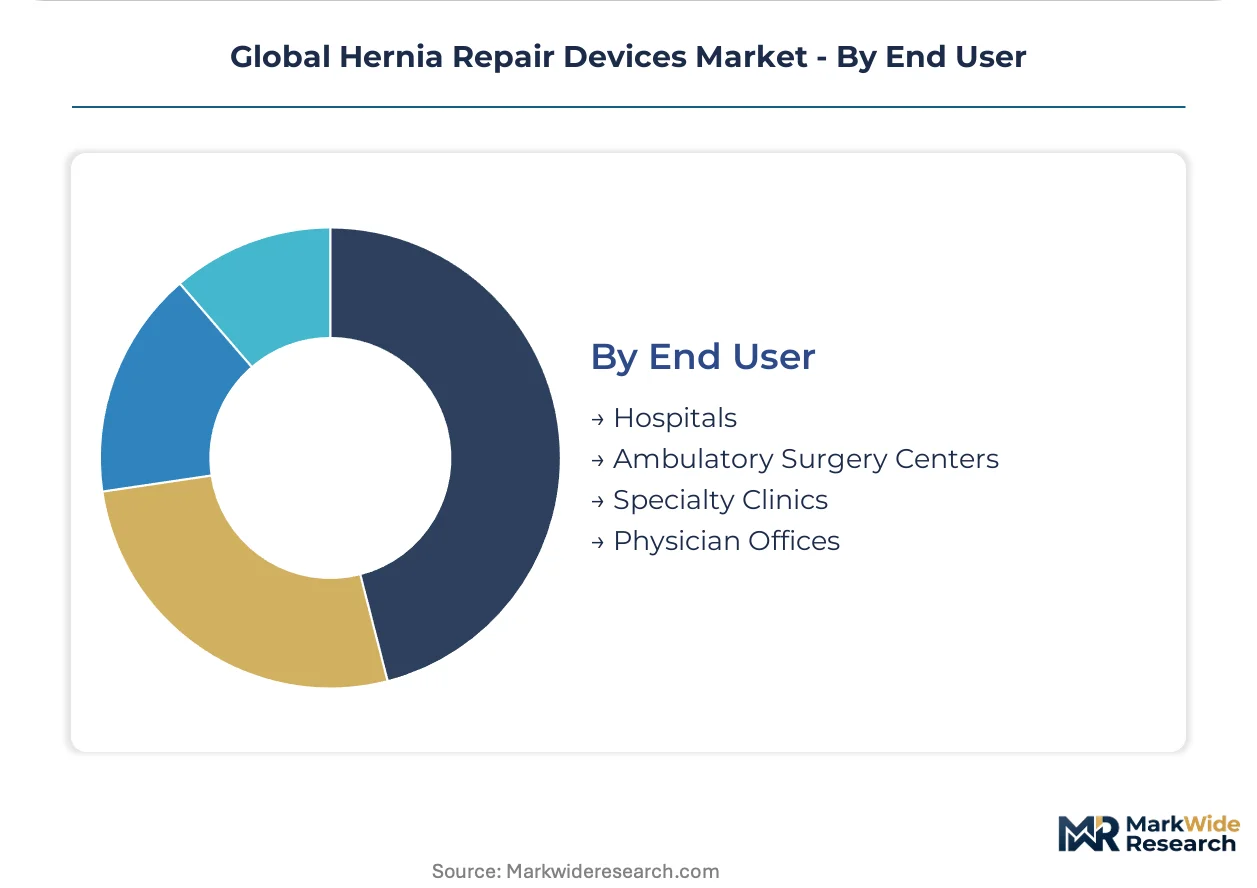
- Hospitals:Inpatient surgical departments manage complex ventral and hiatal repairs requiring extended monitoring. United States academic medical centers anchor demand for robotic platform capital expenditure.
- Ambulatory Surgery Centers:Freestanding facilities capture uncomplicated inguinal and umbilical cases under CMS outpatient reimbursement thresholds. German day-surgery networks expand capacity through standardized laparoscopic protocols.
- Specialty Clinics:Hernia-focused surgical practices concentrate expertise and case volume for referral patterns. Direct-to-employer contracting drives price transparency in selected United States metropolitan markets.
- Physician Offices:Office-based procedures remain limited to diagnostic assessment and postoperative follow-up. Regulatory constraints prevent implant placement outside licensed surgical facilities.
Hospitals lead on scale; ambulatory surgery centers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern hernia repair techniques trace their commercial origins to the United States, where tension-free mesh reinforcement and laparoscopic instrumentation first achieved scale. The industry's geographic footprint now spans surgical clusters across North America, Europe, and Asia-Pacific, each shaped by distinct reimbursement architectures and regulatory pathways.
United States
CMS outpatient reimbursement thresholds drive ambulatory surgery center expansion for uncomplicated inguinal repairs. The FDA's 510(k) substantial equivalence pathway compresses premarket timelines for established mesh compositions. The Midwestern integrated delivery network corridor concentrates group purchasing organization consolidation across 15-20 affiliated surgical centers.
Germany
Day-surgery networks expand capacity through standardized laparoscopic protocols for ventral and inguinal defects. The EU Medical Device Regulation's Class III implantable device requirements extend clinical evaluation timelines for novel biological grafts. Bavarian university hospitals pioneer 3D-printed patient-specific implants for complex multi-recurrence cases.
China
Rural surgical capacity investments accelerate laparoscopic training infrastructure deployment. The NMPA imposes biocompatibility testing protocols that add procedural steps to permanent synthetic mesh registrations. The Yangtze River Delta surgical cluster concentrates demand for lightweight macroporous formulations in tertiary referral centers.
Japan
Aging demographics expand addressable patient pools for hiatal and incisional repair procedures. The PMDA's permanent synthetic mesh protocols add 18-24 months to market access timelines against standardized global launches. The Kanto region anchors demand for robotic-assisted ventral repair platforms in academic medical centers.
India
Tertiary hospital infrastructure investments create whitespace for integrated mesh-fixation system placement in robotic-assisted procedures. The CDSCO's medical device registration framework imposes documentation requirements that favor established material platforms. Mumbai and Delhi surgical clusters concentrate expertise for complex revision cases requiring biological graft substrates.
Global Hernia Repair Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across biological graft versus synthetic mesh differentiation. The vendor base organizes into three tiers: diversified medical technology conglomerates with laparoscopic platform breadth, specialized biological substrate manufacturers with in-house tissue processing capabilities, and regional synthetic mesh suppliers competing on price. Consolidation pressures favor players with captive supply of porcine dermal collagen matrices and verified sustainable manufacturing footprints under REACH circular-economy mandates.
Within the diversified technology tier, Medtronic plc and Baxter International Inc. exemplify contrasting strategic positions. Medtronic leverages laparoscopic platform breadth to sustain recurring revenue from fixation device consumables across ambulatory settings. Baxter anchors its position through in-house production of biological graft substrates that command premium pricing in revision cases. Ethicon Inc. and B. Braun SE occupy positions spanning both synthetic mesh and biological alternatives, reflecting portfolio diversification strategies that hedge against material-specific litigation exposure.
| Leading Market Players |
|---|
| B. Braun SE |
| Cook Medical |
| Medtronic plc |
| Baxter International Inc. |
| AbbVie Inc. |
| Ethicon Inc. |
| W. L. Gore & Associates |
| Integra Lifesciences |
| Becton Dickinson and Company |
| Others |
Supply & Pricing Matrix
Absorbable synthetic mesh production scaling simultaneously compresses per-unit manufacturing costs and concentrates polymer feedstock demand among specialized chemical suppliers. Hospital procurement unbundling of implant purchasing from bundled procedure payments feeds price transparency directly into supplier selection criteria.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates biological graft substrates from lightweight synthetic meshes from commodity polypropylene formulations. Price differentiation rests on clinical evidence depth and regulatory certification tier—FDA 510(k) cleared predicates command premiums over novel compositions awaiting longitudinal safety data. Cost compression in the synthetic mesh tier intensifies as group purchasing organization consolidation across United States Midwestern integrated delivery networks squeezes manufacturer margins. Ambulatory surgery centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while German university hospitals absorb premium pricing for patient-specific 3D-printed implants.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biological graft shipments has pushed suppliers toward regional tissue processing facilities. Manufacturing concentrates in the United States, Germany, and China—each anchoring distinct regulatory compliance zones. Raw material sourcing draws from Gulf Coast petrochemical refineries for polypropylene mesh substrates, Bavarian porcine processing facilities for dermal collagen matrices, and Yangtze River Delta polymer plants for absorbable synthetic formulations. Single-source vulnerability in porcine-derived biological substrates stems from African swine fever disruptions to herd availability. Distribution runs through hospital procurement departments, group purchasing organizations, and specialized surgical device distributors serving ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU MDR compliance costs in Germany run substantially higher than CDSCO registration pathways in India, creating margin expansion opportunities for manufacturers with dual-hemisphere production footprints.
For Market Incumbents: Extend biological graft substrate portfolios through captive supply of porcine dermal collagen matrices to defend against synthetic mesh litigation exposure. Deepen laparoscopic platform integration with robotic-assisted system partnerships to capture outpatient reimbursement expansion. Prioritize REACH circular-economy certification to secure European hospital network procurement consolidation. For New Entrants and Emerging Players: Direct-to-surgeon digital education platforms offer low-friction entry into robotic-assisted ventral repair training gaps across Indian and Brazilian tertiary hospitals. Target same-day discharge protocol adoption curves in United States ambulatory surgery centers with lightweight macroporous mesh formulations. White-space concentrates in 3D-printed patient-specific implant services for complex multi-recurrence defects. For Investors and Strategic Acquirers: Valuations sit cheapest among regional synthetic mesh suppliers lacking biological graft diversification. Long-term viability over the next decade hinges on MDR technical documentation capabilities and sustainable manufacturing footprints under EU Green Deal mandates. Watch for inflection in CMS reimbursement thresholds for outpatient robotic procedures as signal for platform penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | EU Medical Device Regulation compliance secures Class III implantable device market access across German hospital networks. |
| Biological Graft Substrate Backward Integration | In-house porcine dermal collagen processing captures premium pricing in revision cases and reduces supply disruption exposure. |
| Robotic Platform Hospital Partnership | Da Vinci system placement in Indian tertiary hospitals creates integrated mesh-fixation system pull-through revenue. |
| Absorbable Synthetic Mesh Scale-Up | Polylactic acid copolymer manufacturing expansion enables same-day discharge protocol adoption in United States ambulatory centers. |
| 3D-Printed Patient-Specific Implant Development | Preoperative CT modeling convergence with additive manufacturing addresses complex multi-recurrence defects in German university hospitals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included hernia-focused surgeons, hospital purchasing committee members, biomedical engineers at device manufacturers, group purchasing organization contracts managers, and regulatory affairs specialists navigating FDA 510(k) and EMA MDR pathways. Secondary validation drew from FDA 510(k) premarket notification databases, EMA MDR technical documentation filings, CMS Medicare reimbursement schedules, hospital procurement contract registries, and clinical trial registries tracking mesh safety outcomes. Bottom-up demand modeling triangulated against top-down macroeconomic healthcare expenditure trends.
Segment-weighting approaches anchored volume and value projections across the analysis window. The analytical framework modeled product type segmentation—mesh implants, fixation devices, surgical instruments, biological grafts, adhesives—against technology platform adoption curves, application-specific procedure volumes, and end-user site-of-care migration. CAGRs derived from procedure volume elasticity to reimbursement threshold shifts, robotic platform penetration rates, and biological graft substitution patterns in revision cases. Forecast inputs included laparoscopic training infrastructure deployment timelines and REACH circular-economy mandate compliance trajectories.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted ventral repair would alter the outlook if capital expenditure constraints persist in Indian and Brazilian tertiary hospitals. Forecasts reflect assumptions around EU MDR clinical evidence requirements, CMS outpatient reimbursement stability, and polypropylene feedstock price volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Light Therapy Market