
 Asia Pacific Hearing Aids Market | 2026-2036
Asia Pacific Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hearing Aids Market Insights
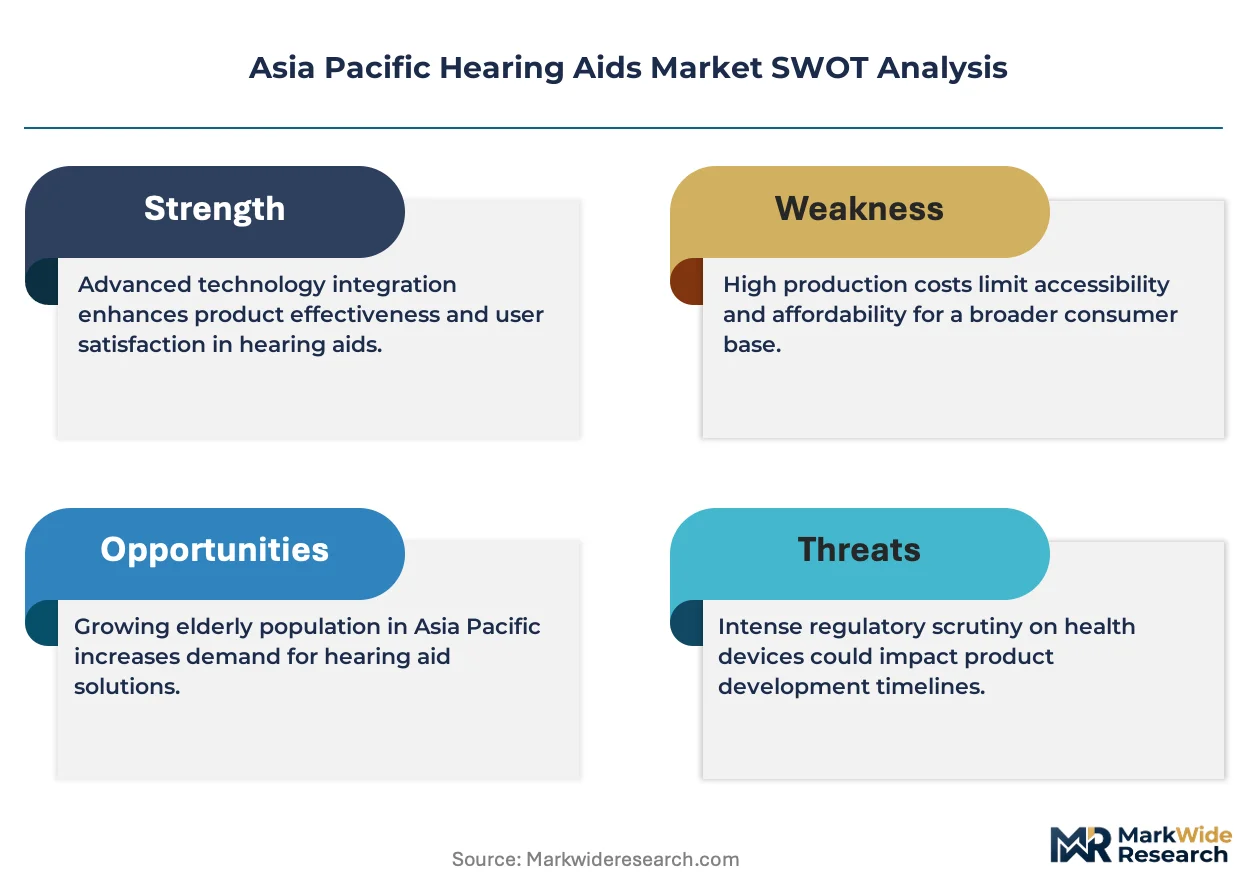
The EU Green Deal is decoupling hearing aid manufacturing from carbon-intensive supply chains, and Asia Pacific assemblers now face parallel pressure from Japan's METI circular economy guidelines. Sonova Holding AG leverages its Swiss-Asia manufacturing footprint to sustain component traceability across multiple production sites. WS Audiology AS anchors its regional R&D in Singapore, while GN Store Nord AS competes through its dedicated China distribution infrastructure.
Hearing aids are electroacoustic wearable devices that amplify sound through digital signal processing, with modern units integrating Bluetooth Low Energy and AI-driven environmental classification to restore auditory perception for sensorineural and conductive hearing loss. Digital technology leads unit shipments across the Asia Pacific region, while Smart hearing aids represent the fastest-expanding margin pool as AI personalization commands premium positioning. The geriatrics end user segment dominates absolute volume, though adult demand for discreet RIC and CIC form factors is reshaping product mix priorities.
Australia's TGA, Japan's PMDA, and China's NMPA collectively enforce divergent medical device classification standards that fragment registration timelines and compliance costs for manufacturers seeking multi-country market access. South Korea's MFDS recently aligned its software-as-medical-device rules with IEC 62304, easing AI-enabled hearing aid approvals but adding cybersecurity validation burdens. Stakeholders must monitor how India's CDSCO adapts its medical device rules to hearing-specific categories, as this will determine whether domestic production incentives redirect supply chain investments toward South Asian manufacturing hubs.
Market Dynamics
Japan's METI circular economy guidelines are forcing hearing aid assemblers to reconfigure component sourcing and end-of-life recovery systems across their Asia Pacific manufacturing networks.
Growth Catalysts
- Aging demographics in Japan:The country's super-aged society generates sustained replacement demand for RIC and BTE devices among geriatric end users with progressive sensorineural decline.
- China's NMPA streamlined Class II medical device pathways:Reduced registration timelines for digital hearing aids accelerate market entry for international manufacturers targeting coastal province consumers.
- Bluetooth Low Energy integration:Direct streaming compatibility with smartphones and televisions is expanding addressable demand among working-age adults seeking discreet auditory assistance.
Market Restraints
- Semiconductor dependency on Taiwan and South Korea:Concentrated MEMS microphone and DSP chip fabrication creates vulnerability to regional supply disruptions and foundry allocation constraints.
- PMDA software-as-medical-device validation requirements:Japan's cybersecurity and algorithm transparency mandates extend approval timelines for AI-enabled environmental classification features.
- OTC hearing aid substitution in Australia:TGA's 2022 reclassification of select self-fitting devices for mild-to-moderate loss segments pressures traditional prescriptive channel volumes.
Strategic Opportunities
- Underpenetrated rural India:CDSCO's anticipated hearing-specific medical device rules and domestic production incentives could redirect supply chain investments toward South Asian assembly hubs.
- Teleaudiology channel expansion:Remote fitting and real-time adjustment protocols reduce geographic barriers to specialist access in Australia's Northern Territory and China's western provinces.
- AI-driven personalization convergence:Integration of on-device machine learning with cloud-based audiometric databases enables premium pricing for adaptive soundscape processing.
Industry Challenges
- Audiologist training pipeline constraints:Certified professional shortages in Vietnam and Indonesia limit effective device fitting and after-sales support scaling.
- Multi-jurisdiction registration complexity:Divergent electromagnetic compatibility testing between Japan's PMDA and South Korea's MFDS fragments compliance resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hearing Aids Market |
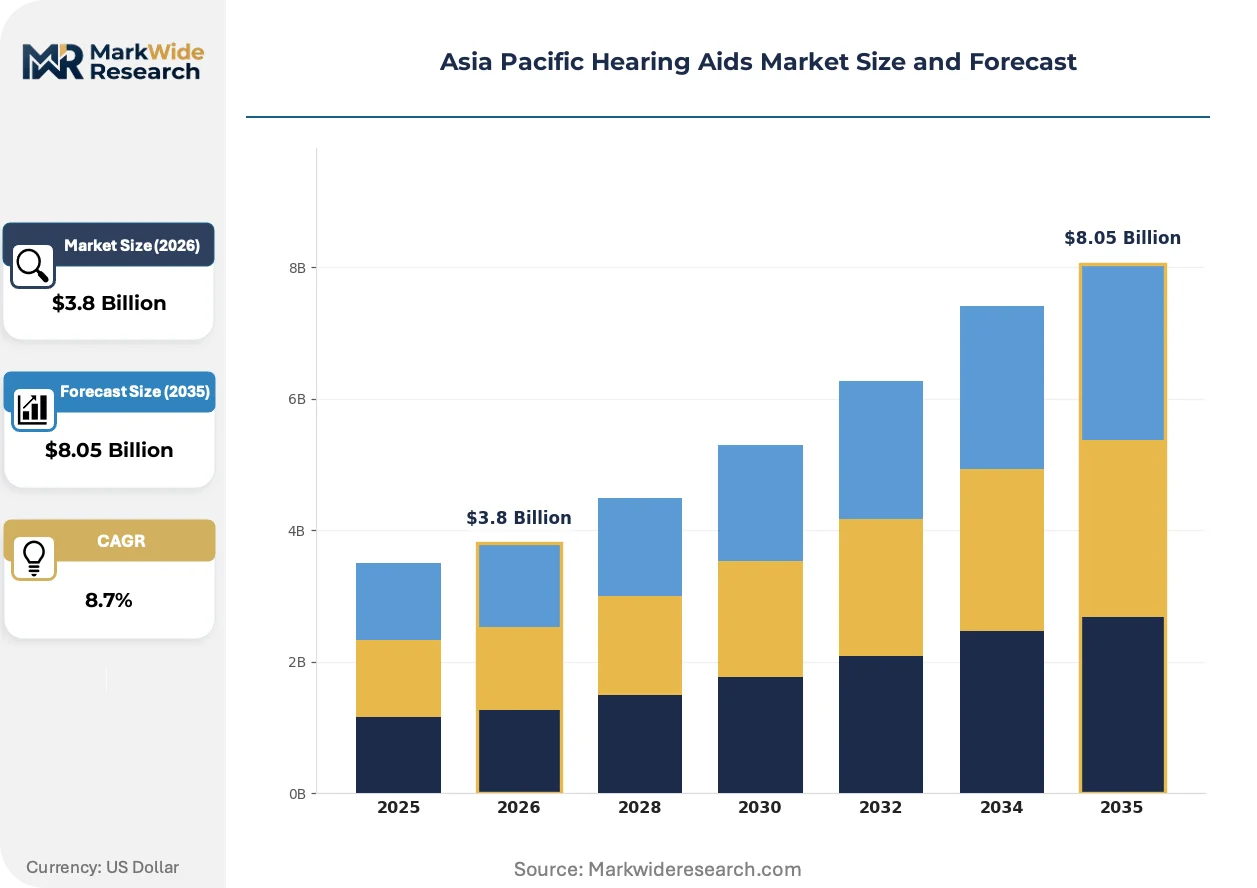
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BTE, ITE, RIC, CIC Technology: Analog, Digital, Smart, Wireless End User: Adults, Children, Geriatrics, Military Distribution Channel: Retail, Online, Hospitals, Clinics |
| Companies Covered | Sonova Holding AG, WS Audiology AS, GN Store Nord AS, Cochlear Ltd, Demant A/S, Starkey Laboratories Inc., MED-EL, Rion Co. Ltd., Arphi Electronics Private Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hearing Aids Market Trends and Innovations
Deep learning environmental classification is compressing the gap between premium and standard device performance tiers while reshaping how manufacturers segment their Asia Pacific product portfolios.
On-device neural networks for real-time sound scene analysis is automating the transition from manual program selection to autonomous acoustic optimization. Adult users in China's tier-one cities are adopting these capabilities fastest, with geriatric segments in Japan following as interface simplification improves. This automation is compressing the traditional six-to-eight-year replacement cycle by demonstrating measurable hearing outcome improvements within the first year of use.
South Korea's MFDS alignment with IEC 62304 for software-as-medical-device oversight is accelerating AI-enabled hearing aid approvals while imposing new cybersecurity validation burdens. Manufacturers must now submit algorithm change control protocols and post-market surveillance plans for machine learning updates. This regulatory evolution most affects premium product lines targeting Seoul's metropolitan healthcare networks, where MFDS clearance serves as a credibility marker for regional export.
Direct-to-consumer online channels are displacing traditional audiology clinic gatekeeping in Australia's urban centers and China's e-commerce corridors. Established retail networks respond by unbundling diagnostic services from device sales, offering hearing assessments as standalone appointments. This channel fragmentation is most visible in Shanghai and Sydney, where smartphone-based hearing screening apps reduce initial consultation friction for price-sensitive first-time buyers.
Asia Pacific Hearing Aids Market Segmentation
Product architecture, signal processing sophistication, and channel access patterns fragment the Asia Pacific hearing aids landscape into distinct margin pools. Manufacturers calibrate R&D allocation and pricing strategy against how each segment concentrates demand across Japan's geriatric corridors, China's coastal cities, and Australia's emerging direct-to-consumer pathways.
Product Type:
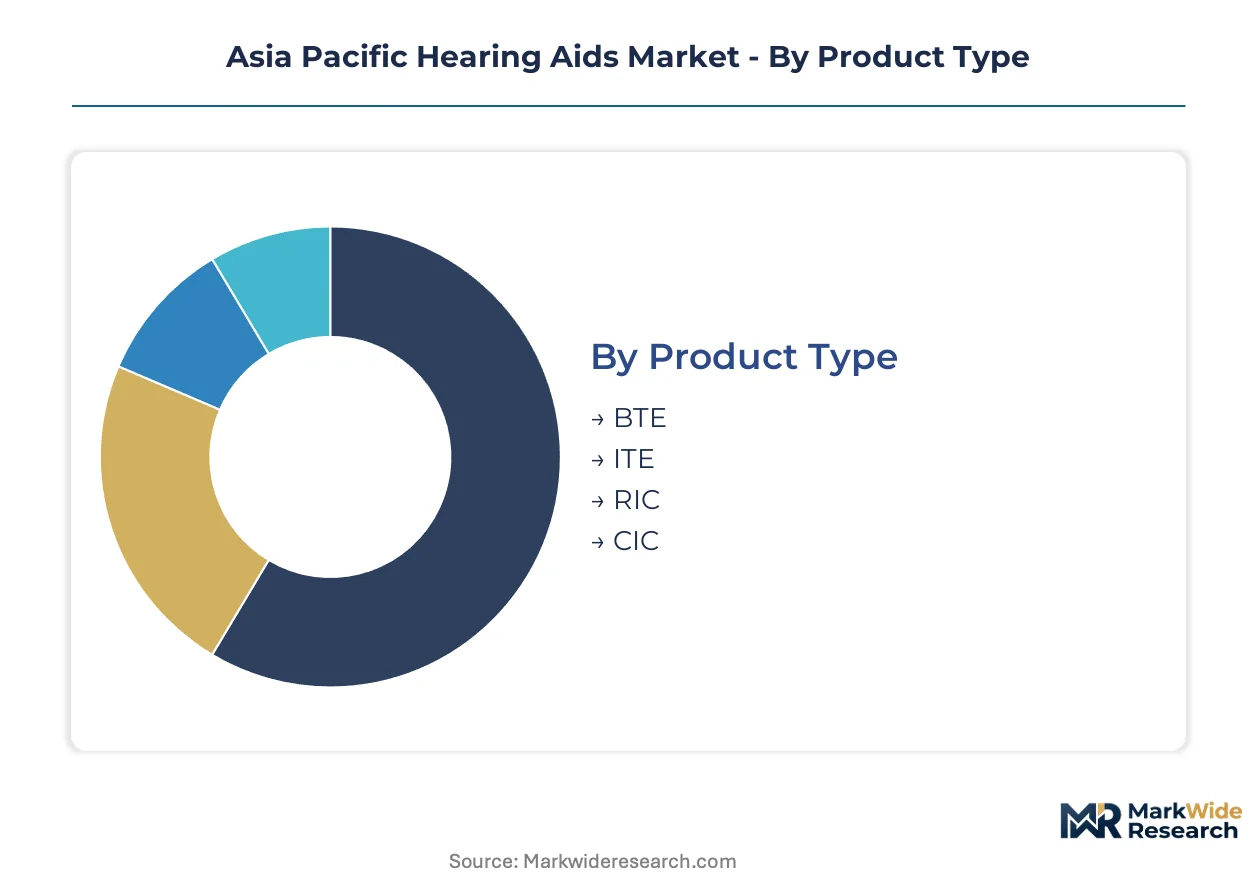
Volume leadership sits with established behind-the-ear configurations, while discreet in-canal designs command expanding premiums among working-age professionals.
- BTE:Behind-the-ear housings contain power amplifiers and directional microphones in a durable shell worn posterior to the pinna. Japan's geriatric end users in Osaka and Fukuoka prefectures generate sustained replacement cycles for these high-power configurations addressing progressive sensorineural decline.
- RIC:Receiver-in-canal architectures separate the speaker from the main housing, enabling slimmer profiles without sacrificing amplification range. Australia's working-age adults in Sydney and Melbourne drive fastest adoption here, with TGA's streamlined approvals reducing time-to-market for Bluetooth-enabled RIC variants.
- ITE:In-the-ear devices occupy the concha and canal in a single custom-molded unit. China's tier-two cities show rising demand for these mid-tier configurations balancing discretion with cost accessibility.
- CIC:Completely-in-canal miniaturization places all components within the ear canal aperture, rendering devices nearly invisible. South Korea's MFDS cybersecurity mandates for wireless CIC units extend validation timelines for manufacturers targeting Seoul's metropolitan networks.
Today's leader: BTE. Tomorrow's challenger: RIC.
Technology:
Signal processing sophistication stratifies pricing tiers from basic amplification through autonomous environmental adaptation.
- Digital:Digital signal processors convert analog sound waves into numerical data for algorithmic filtering, compression, and feedback cancellation. Unit shipments concentrate across China's coastal provinces where NMPA's Class II pathways accelerate market entry for international manufacturers.
- Smart:On-device neural networks enable real-time sound scene classification and autonomous program selection without manual intervention. Adult users in Shanghai and Beijing adopt these capabilities fastest, with measurable hearing outcome improvements compressing traditional replacement cycles.
- Analog:Continuous electrical signal amplification without digital conversion persists in price-sensitive rural segments across Indonesia and Vietnam where audiologist training pipeline constraints limit fitting complexity.
- Wireless:Bluetooth Low Energy and proprietary radio protocols enable direct audio streaming from smartphones and televisions. Australia's TGA 2022 reclassification of self-fitting devices pressures traditional wireless prescriptive channel volumes for mild-to-moderate loss segments.
Digital technology anchors current volume. Smart capabilities are climbing the fastest.
End User:
Demographic concentration and clinical indication shape device specification requirements and channel access patterns.
- Geriatrics:Progressive age-related sensorineural hearing loss drives demand for high-power, easy-to-manage configurations with large controls and telecoil compatibility. Japan's super-aged society generates absolute volume concentration across Hokkaido through Kyushu.
- Adults:Working-age users with noise-induced or early-onset loss prioritize discreet form factors and smartphone connectivity for professional settings. China's tier-one cities show fastest adoption of AI-enabled environmental classification among this cohort.
- Children:Pediatric fittings require tamper-resistant battery compartments, robust moisture protection, and frequency-lowering algorithms for congenital sensorineural conditions. Australia's Northern Territory teleaudiology programs expand geographic access for pediatric diagnostic and fitting services.
- Military:Tactical hearing protection with selective amplification and impulse noise suppression serves defense applications across South Korea and Australia's defense procurement channels.
Geriatrics dominate absolute volume. Adult demand is gaining share fastest.
Distribution Channel:
Channel configuration determines margin capture, fitting service bundling, and regulatory compliance burden.
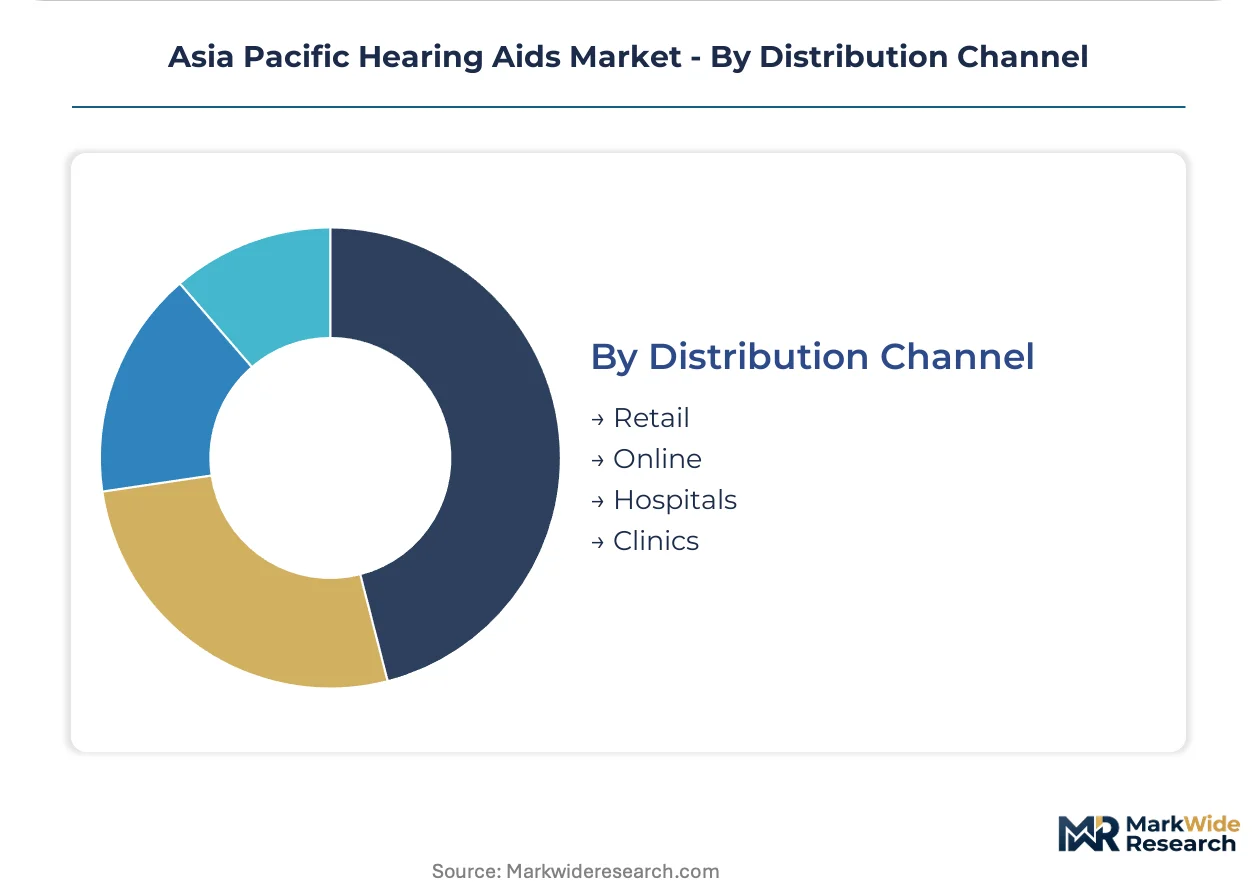
- Retail:Dedicated audiology clinics and hearing instrument specialists provide diagnostic, fitting, and after-sales adjustment services. Established networks in Japan and South Korea respond to online competition by unbundling assessments from device sales.
- Online:Direct-to-consumer platforms and e-commerce marketplaces displace traditional gatekeeping in Australia's urban centers and China's digital corridors. Smartphone-based hearing screening apps reduce initial consultation friction for price-sensitive first-time buyers in Sydney and Shanghai.
- Hospitals:Otolaryngology departments and audiology centers within hospital systems handle complex cases requiring surgical consultation or comorbid condition management. India's anticipated CDSCO hearing-specific rules may redirect supply chain investments toward hospital channel penetration.
- Clinics:Independent audiology practices and multi-specialty outpatient facilities balance diagnostic capability with personalized service. Vietnam and Indonesia face certified professional shortages limiting effective clinic-based fitting and support scaling.
Retail maintains channel leadership. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hearing aid manufacturing in Asia Pacific traces its industrial lineage to post-war Japan, where precision electronics firms first adapted transistor technology for auditory prosthetics. This foundation seeded the region's current concentration of component fabrication and final assembly networks.
Japan
Super-aged demographics in Osaka and Fukuoka prefectures sustain replacement demand for high-power BTE configurations. METI circular economy guidelines mandate end-of-life component recovery systems. Tokyo-based assemblers reconfigure supply chains to meet PMDA software-as-medical-device validation timelines for AI-enabled units.
China
Rising disposable incomes in Shanghai and Beijing accelerate adoption of discreet RIC form factors among working-age professionals. NMPA streamlined Class II medical device pathways compress registration timelines for international manufacturers. Coastal province distributors expand teleaudiology services into western hinterlands.
Australia
TGA's 2022 reclassification of self-fitting devices for mild-to-moderate loss segments pressures traditional prescriptive channel volumes. Sydney and Melbourne working-age adults drive fastest RIC adoption with Bluetooth streaming compatibility. Northern Territory teleaudiology programs reduce geographic barriers to specialist access.
South Korea
MFDS alignment with IEC 62304 for software-as-medical-device oversight accelerates AI-enabled hearing aid approvals. Seoul metropolitan healthcare networks demand cybersecurity validation for wireless CIC units. Busan-Ulsan fabrication clusters supply MEMS microphone components to regional assemblers.
India
Anticipated CDSCO hearing-specific medical device rules could redirect supply chain investments toward South Asian assembly hubs. Maharashtra and Gujarat manufacturing zones position for domestic production incentives. Certified audiologist shortages in rural markets limit effective fitting and after-sales support scaling.
Asia Pacific Hearing Aids Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia Pacific hearing aids landscape. Vertically integrated European-headquartered manufacturers with Swiss-Asia fabrication footprints face competition from specialized R&D anchors and dedicated distribution infrastructure operators. The market structure consolidates around three archetypes: precision component fabricators with captive MEMS supply, software-centric platform developers leveraging cloud-based audiometric databases, and channel-integrated specialists unbundling diagnostic services from device sales. Dominant competitive moves include teleaudiology platform partnerships and AI personalization technology licensing.
Within the precision fabrication tier, Sonova Holding AG and WS Audiology AS exemplify divergent geographic positioning strategies. Sonova leverages its Swiss-Asia manufacturing footprint to sustain component traceability across multiple production sites. WS Audiology anchors its regional R&D operations in Singapore while competing through dedicated distribution infrastructure. GN Store Nord AS occupies a position emphasizing China-facing channel control. These three entities represent the spectrum from component-integrated fabrication to market-access specialization.
| Leading Market Players |
|---|
| Sonova Holding AG |
| WS Audiology AS |
| GN Store Nord AS |
| Cochlear Ltd |
| Demant A/S |
| Starkey Laboratories Inc. |
| MED-EL |
| Rion Co. Ltd. |
| Arphi Electronics Private Limited |
| Others |
Pricing and Supply Chain Analysis
Smart-premium bifurcation against basic-digital tiers splits both component sourcing strategies and margin capture across Asia Pacific manufacturing networks. AI-enabled units with on-device neural networks command component premiums from Taiwan MEMS foundries and South Korean DSP fabricators, while economy digital devices source standardized chipsets through China's coastal assembly corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Asia Pacific hearing aids landscape by signal processing sophistication and wireless capability. Price differentiation hinges on AI personalization certification under Japan's PMDA software-as-medical-device rules and Bluetooth Low Energy integration costs. Cost compression in economy tiers intensifies because China's NMPA streamlined Class II pathways attract low-cost manufacturers. Geriatric end users in Japan's prefectures show least price sensitivity, while first-time adult buyers in China's tier-two cities exhibit highest elasticity.
Supply Chain Analysis
MEMS microphone and DSP chip supply rests on Taiwan Semiconductor Manufacturing and South Korean foundry clusters, with secondary sourcing through Japan's precision component specialists. Raw material dependencies span rare-earth magnets for miniature receivers, medical-grade silicones for ear-mold fabrication, and lithium-ion cells for rechargeable architectures. Single-source vulnerability concentrates in Taiwan's 8-inch MEMS wafer capacity. Distribution runs through audiology clinic networks in Japan and South Korea, direct-to-consumer platforms in Australia, and hospital procurement channels in India's emerging regulatory environment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific hearing aids market compounds steadily as aging demographics across Japan, China, and Australia generate replacement cycles that outpace economic cyclicality.
For Market Incumbents: Lock in component traceability across Swiss-Asia manufacturing footprints to satisfy Japan's METI circular economy guidelines for end-of-life recovery. Secure captive MEMS supply agreements with Taiwan foundries before foundry allocation constraints tighten. Defend against OTC hearing aid substitution in Australia by unbundling diagnostic services from device sales to preserve clinic relationships. For New Entrants and Emerging Players: Teleaudiology platform partnerships offer the fastest channel access into Australia's Northern Territory and China's western provinces where audiologist density remains thin. Target rural India before CDSCO's anticipated hearing-specific medical device rules formalize domestic production incentives that favor established assemblers. Lead with smartphone-based hearing screening apps to reduce initial consultation friction among price-sensitive first-time buyers. For Investors and Strategic Acquirers: Consolidation pressure builds where software-centric platform developers lack captive fabrication capacity to meet PMDA cybersecurity validation timelines. Five-to-ten year viability favors precision component fabricators with backward integration into MEMS supply and cloud-based audiometric database operators. Watch India's CDSCO rule finalization as the inflection signal for whether supply chain investments redirect toward South Asian assembly hubs.| Strategic Initiative | Industry Significance |
|---|---|
| Teleaudiology Platform Partnership | Remote fitting protocols reduce geographic barriers in Australia's Northern Territory and China's western provinces. |
| AI Personalization Technology Licensing | On-device neural network integration commands premium positioning under Japan's PMDA software-as-medical-device oversight. |
| MEMS Supply Agreement | Captive microphone component access insulates against Taiwan foundry allocation constraints and tariff exposure. |
| Domestic Production Incentive Capture | India's CDSCO hearing-specific rules may redirect assembly investments toward Maharashtra and Gujarat manufacturing zones. |
| Circular Economy Compliance Investment | End-of-life recovery systems satisfy Japan's METI guidelines and EU Green Deal supply chain decoupling pressures. |
Research Methodology
Direct dialogue with audiology clinic directors, biomedical engineers at hearing instrument manufacturers, hospital purchasing committee members, and GPO contracts managers grounded qualitative assessments. Secondary validation drew from FDA 510(k) filings for hearing aid devices, TGA medical device registration databases, NMPA Class II approval records, and CMS Medicare hearing aid coverage data. Bottom-up unit shipment estimates triangulated against top-down demographic penetration models.
Segment-level outputs across product architecture, signal processing technology, end-user demographic, and distribution channel dimensions calibrated CAGRs against historical replacement cycle compression from AI-enabled environmental classification adoption. The modeling framework incorporated PMDA software-as-medical-device approval timelines, NMPA registration pathway efficiency metrics, and teleaudiology penetration rates as industry-specific forecast inputs.
Revisions become necessary when semiconductor foundry allocation constraints intensify, India's CDSCO delays hearing-specific medical device rule finalization, or Australia's OTC hearing aid reclassification expands beyond mild-to-moderate loss segments. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Nebuliser Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Surgical Display Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Blood Lancet Market
Medical Devices
Capnography Devices Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Knee Walkers Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Global Automated Suturing Devices Market