
 Global Gamma Probe Device Market | 2026-2036
Global Gamma Probe Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gamma Probe Device Market Foresight
Buyer concentration among cancer treatment hospitals is recalibrating procurement patterns across the Global Gamma Probe Device Market. Hologic leverages its installed base in breast imaging to extend service contracts into gamma probe replacements. Thermo Fisher Scientific anchors semiconductor detector supply chains through captive sourcing of cadmium zinc telluride crystals. Dilon Technologies specializes in handheld gamma probes for ambulatory surgical centers competing on portability metrics.
A gamma probe device detects gamma ray emissions from radiopharmaceutical tracers to guide surgeons toward targeted tissue during oncologic and endocrine procedures. These instruments typically employ scintillation crystals paired with photomultiplier tubes or solid-state semiconductor detectors, achieving spatial resolution under one centimeter at operating distances of one to three centimeters from tissue surfaces. Handheld gamma probes occupy the largest revenue pool due to universal adoption in sentinel lymph node biopsy workflows, while automated scanning systems capture premium pricing in academic centers pursuing standardized mapping protocols. Cadmium zinc telluride semiconductor detectors represent the fastest-expanding technology segment as manufacturers displace legacy scintillation platforms with room-temperature operation and improved energy resolution.
FDA 510(k) clearance requirements govern device entry into the United States, while EU MDR and CE marking obligations reshape European market access timelines for gamma probe manufacturers. ISO 13485 quality management certification has become a baseline procurement filter for oncology clinics and surgical centers evaluating vendor qualifications. Stakeholders must monitor reimbursement parity between radioguided and conventional surgical techniques as payors recalibrate coverage policies across major healthcare systems.
Market Dynamics
Cadmium zinc telluride semiconductor detectors are compressing replacement cycles across academic medical centers while EU MDR reclassification extends European market access timelines.
Growth Catalysts
- Radioguided surgical program expansion:Cancer treatment hospitals in Germany are scaling sentinel lymph node biopsy workflows under EU MDR device classification requirements.
- ISO 13485 certification baseline:Oncology clinics now filter vendor qualifications through quality management certification, elevating procurement standards.
- Semiconductor detector platforms:Academic medical centers in the United States are driving replacement demand for room-temperature operation systems with improved energy resolution.
Market Restraints
- Cadmium zinc telluride crystal supply concentration:Captive sourcing arrangements limit independent manufacturer access to high-purity semiconductor substrates.
- EU MDR technical documentation burden:European device reclassification extends conformity assessment timelines for gamma probe manufacturers.
- Scintillation crystal obsolescence risk:Legacy photomultiplier tube platforms face accelerated depreciation as healthcare systems prioritize semiconductor architectures.
Strategic Opportunities
- Ambulatory surgical center penetration:Handheld gamma probe portability metrics align with same-day discharge protocols in United States outpatient facilities.
- Reimbursement parity expansion:Payor recalibration of coverage policies for radioguided versus conventional surgical techniques creates billing pathway opportunities.
- Artificial intelligence convergence:Machine learning algorithms are integrating with gamma probe spatial mapping to automate tissue localization.
Industry Challenges
- Clinical physicist training gaps:Radiation safety certification requirements for operating room staff outpace specialized education program availability.
- FDA 510(k) predicate device alignment:Substantial equivalence determinations for novel semiconductor architectures encounter reference standard ambiguities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gamma Probe Device Market |
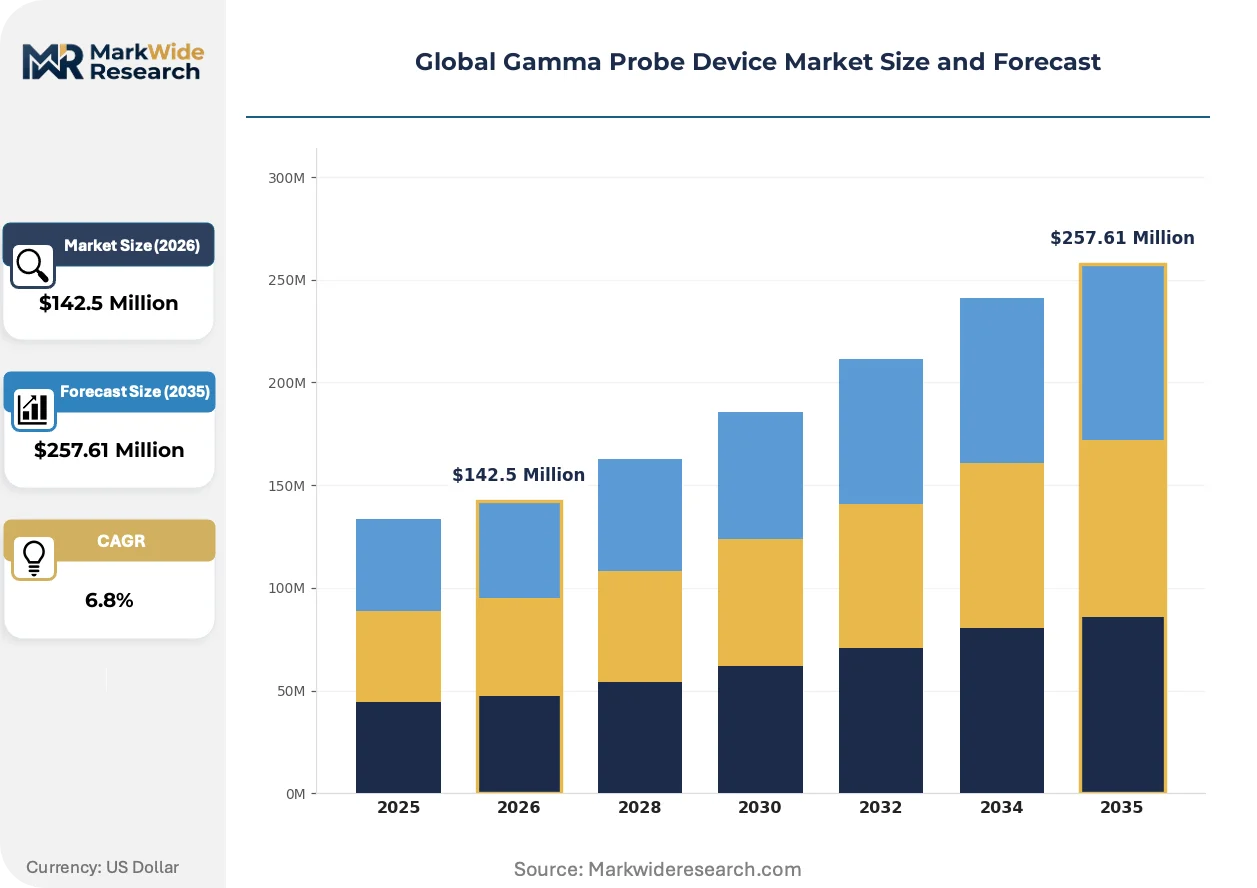
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Gamma Probes, Automated Scanning Systems, Dual-Modality Probes, Wearable Detectors, Portable Instruments Technology: Scintillation Detectors, Semiconductor Detectors, Ionization Chambers, Photomultiplier Tubes, Cadmium Zinc Telluride Application: Sentinel Lymph Node Biopsy, Tumor Localization, Parathyroid Surgery, Bone Scan Surgery, Radioguided Surgery End User: Oncology Clinics, Surgical Centers, Research Laboratories, Diagnostic Imaging Facilities, Cancer Treatment Hospitals |
| Companies Covered | Hologic, Thermo Fisher Scientific, Wake Medical, Raditec Medical, Dilon Technologies, Lake Shore Cryotronics, Intramedical Imaging, Tron Medical, Biodex Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gamma Probe Device Market Shifts & Advancements
Device miniaturization and detector material substitution are compressing form factors while regulatory harmonization efforts reshape quality management expectations.
Semiconductor gamma probe technology is integrating solid-state cadmium zinc telluride detectors to eliminate cryogenic cooling requirements. Academic medical centers in the United States are adopting these platforms for sentinel lymph node mapping procedures. The technology is integrating photon-counting electronics that compress signal processing latency below legacy scintillation thresholds.
EU MDR Article 120 transitional provisions are forcing gamma probe manufacturers to restructure technical documentation for higher-risk device classifications. German notified bodies are extending conformity assessment timelines for active implantable surgical instruments. European cancer treatment hospitals are responding by consolidating procurement around vendors with established quality management system certifications.
After-sales service unbundling is fragmenting traditional equipment-vendor relationships in United States academic medical centers. Third-party biomedical engineering firms are capturing preventive maintenance contracts previously held by original equipment manufacturers. This pattern concentrates in high-volume breast cancer treatment hospitals seeking operational expenditure flexibility over capital-intensive service agreements.
Global Gamma Probe Device Market Segmentation
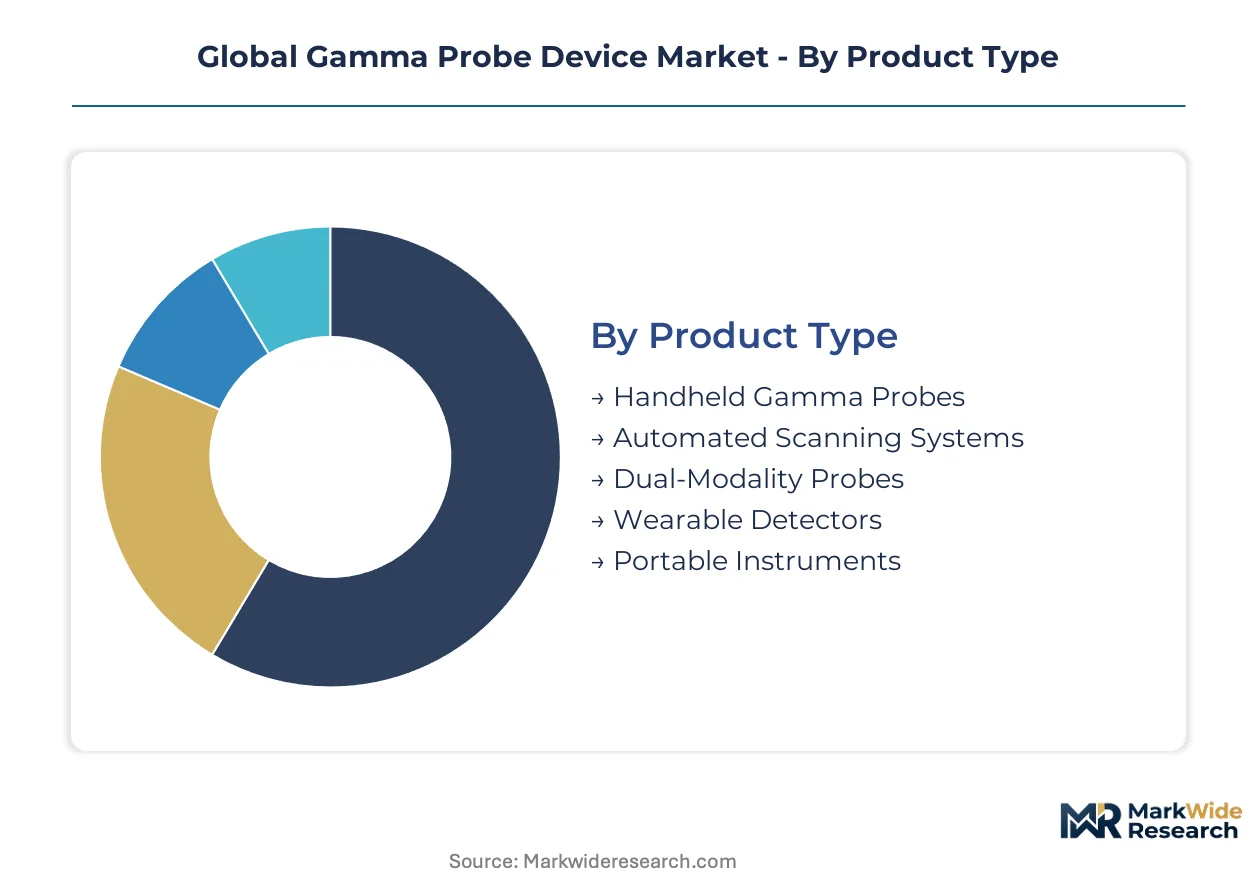
Gamma probe device segmentation reveals distinct procurement patterns across surgical workflows and detector technologies. Hospital capital committees evaluate product categories against specific procedure volumes, while technology choices increasingly hinge on semiconductor supply security rather than legacy performance benchmarks.
Product Type:
Procurement committees differentiate capital allocation between handheld units for high-volume outpatient workflows and integrated systems requiring dedicated installation space.
- Handheld Gamma Probes:Compact battery-operated units weighing under 500 grams enable single-surgeon operation without ancillary staff. Cancer treatment hospitals in Germany deploy these for sentinel lymph node biopsy workflows under EU MDR active implantable device classifications. Demand concentrates in ambulatory surgical centers seeking same-day discharge protocol compatibility.
- Automated Scanning Systems:Motorized gantry-mounted detectors generate standardized three-dimensional activity maps for complex tumor localization procedures. Academic medical centers in the United States prioritize these platforms for multi-surgeon teaching environments where reproducible documentation supports resident training programs.
- Dual-Modality Probes:Hybrid instruments combining gamma detection with optical or ultrasound guidance reduce instrument exchanges during parathyroid surgery.
- Wearable Detectors:Chest-mounted or head-mounted form factors free both hands during extended radioguided procedures.
- Portable Instruments:Wheeled cart-based systems bridge handheld convenience with scanning system sensitivity for diagnostic imaging facilities.
Handheld gamma probes lead volumes today; automated scanning systems are gaining share fastest in academic procurement cycles.
Technology:
Detector material selection now determines total cost of ownership more than initial acquisition price, with cooling infrastructure and calibration labor reshaping lifecycle economics.
- Scintillation Detectors:Sodium iodide crystal-photomultiplier tube assemblies deliver proven sensitivity at ambient temperatures but require frequent gain stabilization. Legacy installed bases in European oncology clinics face accelerated replacement as manufacturers discontinue thallium-doped crystal supply lines.
- Cadmium Zinc Telluride:Room-temperature semiconductor substrates eliminate liquid nitrogen logistics while improving energy resolution from 9% to 2% at 140 keV. Thermo Fisher Scientific's captive crystal sourcing constrains independent manufacturer access to high-purity tellurium supply chains.
- Semiconductor Detectors:Silicon PIN diode architectures serve cost-sensitive portable instrument segments with moderate resolution requirements.
- Ionization Chambers:Gas-filled detectors persist in research laboratory calibration workflows requiring absolute dose quantification.
- Photomultiplier Tubes:Vacuum tube signal amplification remains specified for dual-modality probes requiring nanosecond timing resolution.
Scintillation detectors retain installed base dominance; cadmium zinc telluride is climbing the fastest as replacement cycles accelerate.
Application:
Procedure reimbursement codes directly shape device feature requirements, with Medicare physician fee schedules influencing detector sensitivity specifications.
- Sentinel Lymph Node Biopsy:Standardized radiocolloid injection protocols demand probes detecting 99mTc sulfur colloid at 0.1 millicurie residual activity. United States breast surgery programs drive annual replacement demand as probe tips degrade from repeated sterilization cycles.
- Tumor Localization:Occult lesion identification requires directional sensitivity patterns distinguishing target tissue from injection site shine-through. German cancer treatment hospitals are expanding these workflows under EU MDR quality management system mandates.
- Parathyroid Surgery:Intraoperative 99mTc-sestamibi washout monitoring favors probes with rapid background subtraction algorithms.
- Bone Scan Surgery:Orthopedic oncology applications integrate gamma probes with fluoroscopic navigation for metastatic lesion excision.
- Radioguided Surgery:Broad category encompassing non-oncologic applications including thyroid and neuroendocrine procedures.
Sentinel lymph node biopsy anchors current procedure volumes; tumor localization is expanding most quickly as staging protocols intensify.
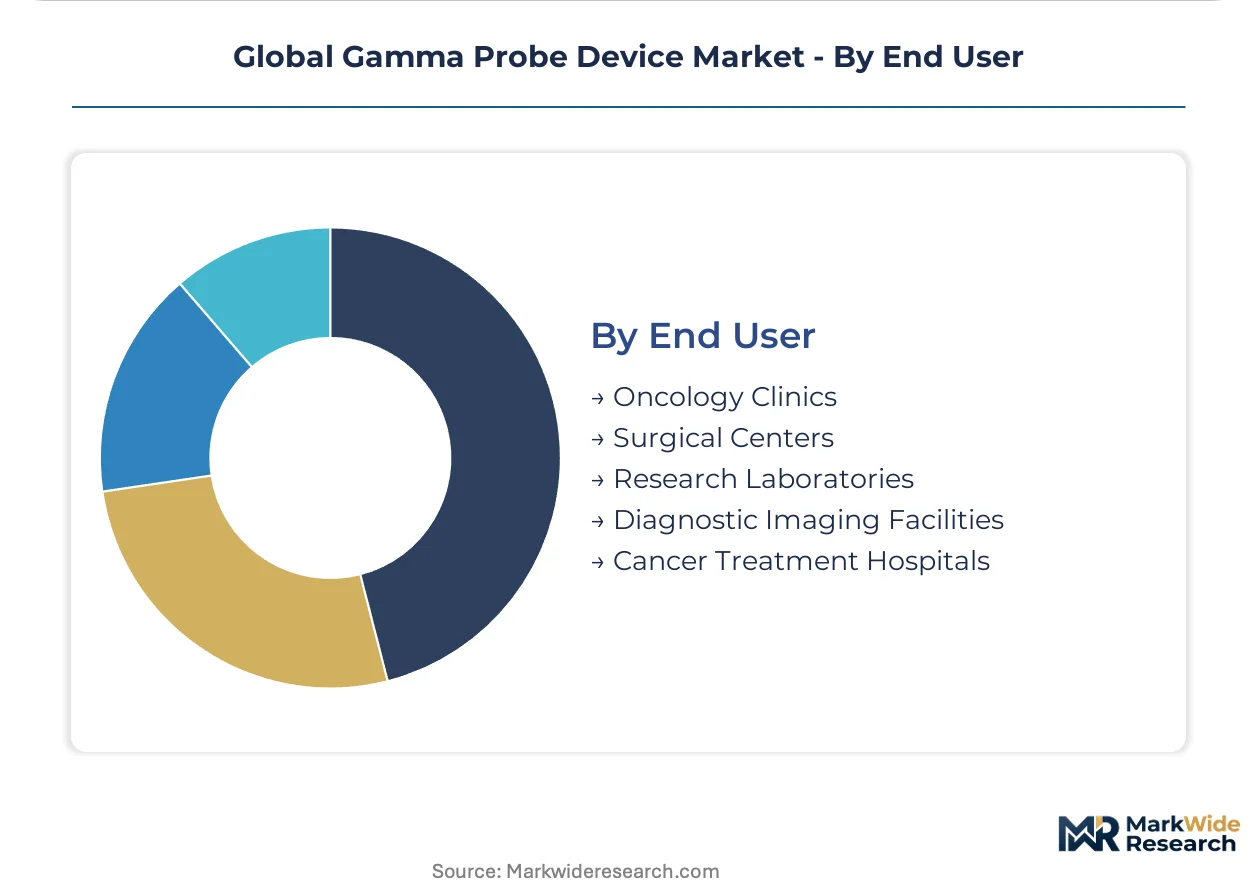
End User:
Capital availability and procurement autonomy vary dramatically across facility types, with independent surgical centers prioritizing lease structures over outright purchase.
- Cancer Treatment Hospitals:Comprehensive oncology service lines justify multi-probe inventories supporting parallel operating room schedules. These institutions in the United States are driving semiconductor detector adoption through consolidated vendor negotiations.
- Surgical Centers:Ambulatory facilities prioritize handheld gamma probe portability metrics and disposable sheath compatibility for rapid turnover.
- Oncology Clinics:Office-based practices concentrate demand on single-probe systems with simplified calibration requirements.
- Research Laboratories:Academic medical center physics departments specify custom detector geometries for radiopharmaceutical development protocols.
- Diagnostic Imaging Facilities:Hybrid nuclear medicine-surgical units require probes integrating with existing gamma camera quality assurance programs.
Cancer treatment hospitals command the largest procurement budgets; surgical centers are adding probe capacity fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized surgical physicists and radiation safety officers concentrate in Germany, the United States, Japan, and Australia, anchoring regional demand for advanced gamma probe platforms. These professional clusters drive procurement sophistication and accelerate technology transitions.
United States
Academic medical centers in Boston and Houston drive replacement cycles for semiconductor detector platforms. FDA 510(k) clearance requirements govern device entry, with substantial equivalence determinations for novel architectures encountering reference standard ambiguities. The Greater Boston cluster anchors demand through consolidated vendor negotiations.
Germany
Cancer treatment hospitals in Munich and Heidelberg expand radioguided surgical programs under EU MDR device classification requirements. EU MDR Article 120 transitional provisions force manufacturers to restructure technical documentation for higher-risk classifications. German notified bodies extend conformity assessment timelines for active implantable surgical instruments.
Japan
PMDA regulatory pathways shape market access timelines for semiconductor detector platforms. METI industrial policy supports domestic production of high-purity tellurium substrates. The Kansai region around Osaka concentrates procurement through university hospital networks pursuing standardized mapping protocols.
Australia
TGA conformity assessment requirements align with EU MDR technical documentation standards, simplifying parallel market access. Diagnostic imaging facilities in Sydney and Melbourne integrate gamma probes with existing nuclear medicine quality assurance programs. The Sydney cluster leads adoption of portable instruments bridging handheld convenience with scanning system sensitivity.
Switzerland
Swissmedic certification requirements elevate quality management system expectations for oncology clinic procurement. Research laboratories in Basel and Zurich specify custom detector geometries for radiopharmaceutical development protocols. The Basel cluster anchors European demand for ionization chamber calibration workflows.
Global Gamma Probe Device Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers in the Global Gamma Probe Device Market. Conglomerates leverage installed bases in adjacent diagnostic imaging to extend service contracts into gamma probe replacements. Pure-play specialists concentrate on handheld portability metrics for ambulatory surgical center penetration. Two strategic archetypes dominate: diversified life science platforms with captive semiconductor supply chains, and focused surgical instrument specialists competing on form factor innovation. Competitive moves concentrate on backward integration into crystal sourcing and unbundling of after-sales service relationships.
Among diversified life science platforms, Thermo Fisher Scientific anchors semiconductor detector supply chains through captive sourcing arrangements. Hologic leverages its installed base in breast imaging to extend service contracts. Dilon Technologies exemplifies the focused specialist archetype, concentrating on handheld gamma probes for ambulatory surgical centers where portability metrics determine procurement outcomes. These three companies represent distinct competitive vectors: supply chain control, installed base monetization, and surgical workflow specialization.
| Leading Market Players |
|---|
| Hologic |
| Thermo Fisher Scientific |
| Wake Medical |
| Raditec Medical |
| Dilon Technologies |
| Lake Shore Cryotronics |
| Intramedical Imaging |
| Tron Medical |
| Biodex Medical Systems |
| Others |
Supply & Pricing Matrix
Academic medical center procurement committees in the United States are consolidating vendor negotiations around semiconductor detector specifications, forcing manufacturers to absorb cadmium zinc telluride crystal cost premiums or cede share to Thermo Fisher Scientific's captive supply chain. This demand compression cascades through pricing tiers as independent manufacturers sacrifice margin to maintain ISO 13485-certified hospital access.
Pricing Analysis
Capacity additions in Japan's high-purity tellurium substrate production are reshaping price floors for cadmium zinc telluride semiconductor detectors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and after-sales service bundling. Price differentiation hinges on FDA 510(k) clearance status and ISO 13485 quality management certification. Cost compression in economy handheld probes is intensifying as ambulatory surgical centers prioritize disposable sheath compatibility over detector sensitivity. Oncology clinics exhibit highest price sensitivity; cancer treatment hospitals with consolidated procurement budgets show lowest.
Supply Chain Analysis
Probe refurbishment and trade-in programs for legacy scintillation crystal units are creating reverse-logistics flows that feed secondary market supply. Manufacturing concentrates in the United States, Germany, and Japan. High-purity tellurium, cadmium zinc telluride crystals, and photomultiplier tubes constitute critical input dependencies. Single-source vulnerability permeates semiconductor substrate sourcing as Thermo Fisher Scientific's captive arrangements constrain independent access. Distribution runs through original equipment manufacturer service networks and third-party biomedical engineering firms capturing preventive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Gamma Probe Device Market functions as a regulatory compounder where EU MDR reclassification timelines and FDA 510(k) predicate device ambiguities continuously elevate compliance costs and consolidate procurement around certified vendors.
For Market Incumbents: To counter third-party biomedical engineering firms capturing preventive maintenance contracts, Hologic and Thermo Fisher Scientific should unbundle service agreements into modular subscription tiers while deepening backward integration into cadmium zinc telluride crystal production. Certification investment in EU MDR technical documentation capabilities represents the critical defensive lever. For New Entrants and Emerging Players: The price-point gap between premium semiconductor detector platforms and economy scintillation legacy systems opens viable entry corridors. Ambulatory surgical centers in the United States present the most penetrable white space, with portability metrics and same-day discharge protocol compatibility as the decisive go-to-market angle. Target lease-structured procurement models over capital purchase. For Investors and Strategic Acquirers: Asymmetric upside sits with focused surgical instrument specialists possessing handheld form factor innovation capabilities and established ISO 13485 quality management systems. Long-term viability across the analysis window favors acquisition targets with semiconductor detector integration roadmaps and European notified body relationships. Monitor EU MDR conformity assessment timeline extensions as inflection signals for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 120 transitional provisions force technical documentation restructuring for higher-risk device classifications. |
| Hospital System Partnership | Consolidated vendor negotiations at academic medical centers in Boston and Houston anchor semiconductor detector replacement demand. |
| Backward Integration | Captive sourcing of cadmium zinc telluride crystals insulates margins from tellurium supply concentration. |
| Software Companion Development | Machine learning algorithms integrating with gamma probe spatial mapping automate tissue localization workflows. |
| Reimbursement Strategy | Payor recalibration of coverage policies for radioguided versus conventional surgical techniques creates billing pathway opportunities. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down semiconductor detector supply tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiation safety officers combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 13485 certification registries. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices map detector technology adoption curves against procedure volume projections across the modeling period. Segmentation dimensions include product type, detector technology, application workflow, and end-user facility tier. CAGRs derive from weighted average of procedure growth rates and replacement cycle compression factors. Forecast inputs incorporate EU MDR conformity assessment timeline elasticity and semiconductor substrate supply availability.
Caveats apply where EU MDR notified body capacity constraints or cadmium zinc telluride crystal supply disruptions could materially shift the outlook. Practitioners should monitor reimbursement parity negotiations between radioguided and conventional surgical techniques for early signals of demand acceleration or deceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Heating Pads Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
Cervical Implants Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Medication Management System Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Carotid Stents Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market