
 Anesthesia Resuscitators Masks Market | 2026-2036
Anesthesia Resuscitators Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Resuscitators Masks Market Analysis
Single-use silicone molding is reconfiguring manufacturing economics across the anesthesia resuscitators masks landscape, compressing per-unit costs while elevating biocompatibility thresholds. Ambu A/S leverages its integrated Danish production footprint to sustain premium positioning in pediatric and neonatal mask lines. Drägerwerk AG & Co. KGaA anchors European hospital procurement through deep anesthesia workstation bundling. Medtronic Plc competes in North American acute care channels with broad critical care portfolios that include resuscitation accessories.
Anesthesia resuscitators masks are patient interface devices typically fabricated from medical-grade silicone, PVC, or thermoplastic elastomer, designed to form a sealed conduit for gas delivery during controlled ventilation, resuscitation, or inhalational anesthesia induction. Wall thickness tolerances of 1.5–3.0 millimeters and shore hardness ratings between 30A and 50A determine seal integrity across adult, pediatric, and neonatal facial anatomies. Adult masks dominate procurement volumes in hospital settings, while specialty masks command margin premiums for difficult airway management and MRI-compatible configurations. Silicone material grades capture preference in reusable segments, whereas PVC sustains cost-driven disposable adoption across high-throughput surgical centers.
The FDA's 510(k) clearance pathway and the European Union's Medical Device Regulation shape design dossier requirements, clinical validation burdens, and post-market surveillance obligations for mask manufacturers seeking cross-border commercialization. ISO 10993 biocompatibility testing and ISO 5356-1 connector standards further constrain material selection and dimensional interoperability across anesthesia breathing systems. Stakeholders must monitor evolving notified body capacity in Europe and the trajectory of FDA digital health pre-certification pilots, as these regulatory currents will determine which manufacturers can sustain multi-jurisdiction compliance without portfolio rationalization.
Market Dynamics
Single-use silicone molding is compressing per-unit manufacturing costs while elevating biocompatibility thresholds, forcing reusable mask suppliers to defend margin positions through specialized pediatric and difficult airway configurations. This technology shift is redistributing procurement volumes toward high-throughput ambulatory surgical centers.
Growth Catalysts
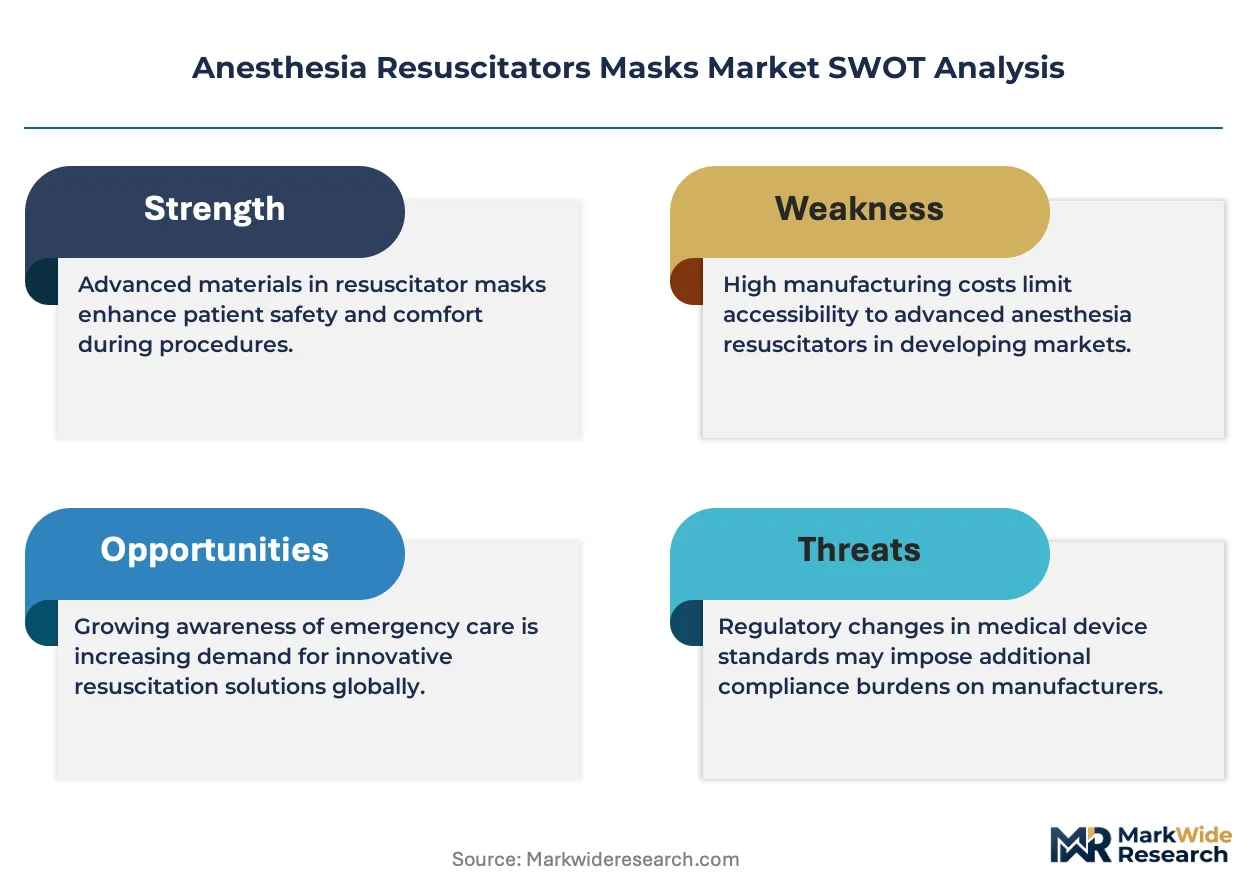
- FDA 510(k) pathway tightening:The FDA's updated premarket notification requirements for Class II medical devices are accelerating quality differentiation among manufacturers, privileging suppliers with robust clinical validation dossiers.
- Ambulatory surgical center expansion:United States outpatient facility construction is outpacing hospital operating room growth, concentrating disposable mask demand in high-turnover procedural settings.
- Silicone material substitution:Medical-grade silicone grades are displacing PVC in premium segments, driven by superior seal integrity and extended reuse cycles in anesthesia workstations.
Market Restraints
- Medical-grade silicone price volatility:Raw material supply concentration in East Asian petrochemical corridors exposes manufacturers to input cost swings that compress disposable segment margins.
- European notified body capacity constraints:EU MDR implementation bottlenecks are extending certification timelines, freezing new product introductions and portfolio rationalization decisions.
- Reusable mask residual value:Silicone reusability in hospital anesthesia workstations sustains installed base longevity, dampening replacement cycle frequency for premium mask lines.
Strategic Opportunities
- India surgical infrastructure buildout:CDSCO regulatory harmonization with ISO standards is lowering market entry barriers for CE-certified manufacturers targeting tier-2 city hospital procurement.
- MRI-compatible mask development:Non-ferrous material configurations for magnetic resonance environments address an underserved niche in diagnostic-surgical hybrid suites.
- Direct-to-facility distribution:Bypassing traditional medical-surgical distributors through integrated logistics platforms captures margin and accelerates inventory turns for high-volume purchasers.
Industry Challenges
- ISO 10993 biocompatibility testing backlog:Contract laboratory capacity shortages are delaying cytotoxicity and sensitization study completion, stretching product launch schedules.
- Anesthesia workstation integration complexity:Proprietary connector geometries from Drägerwerk and Mindray lock mask suppliers into OEM-specific tooling investments that fragment production scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Resuscitators Masks Market |
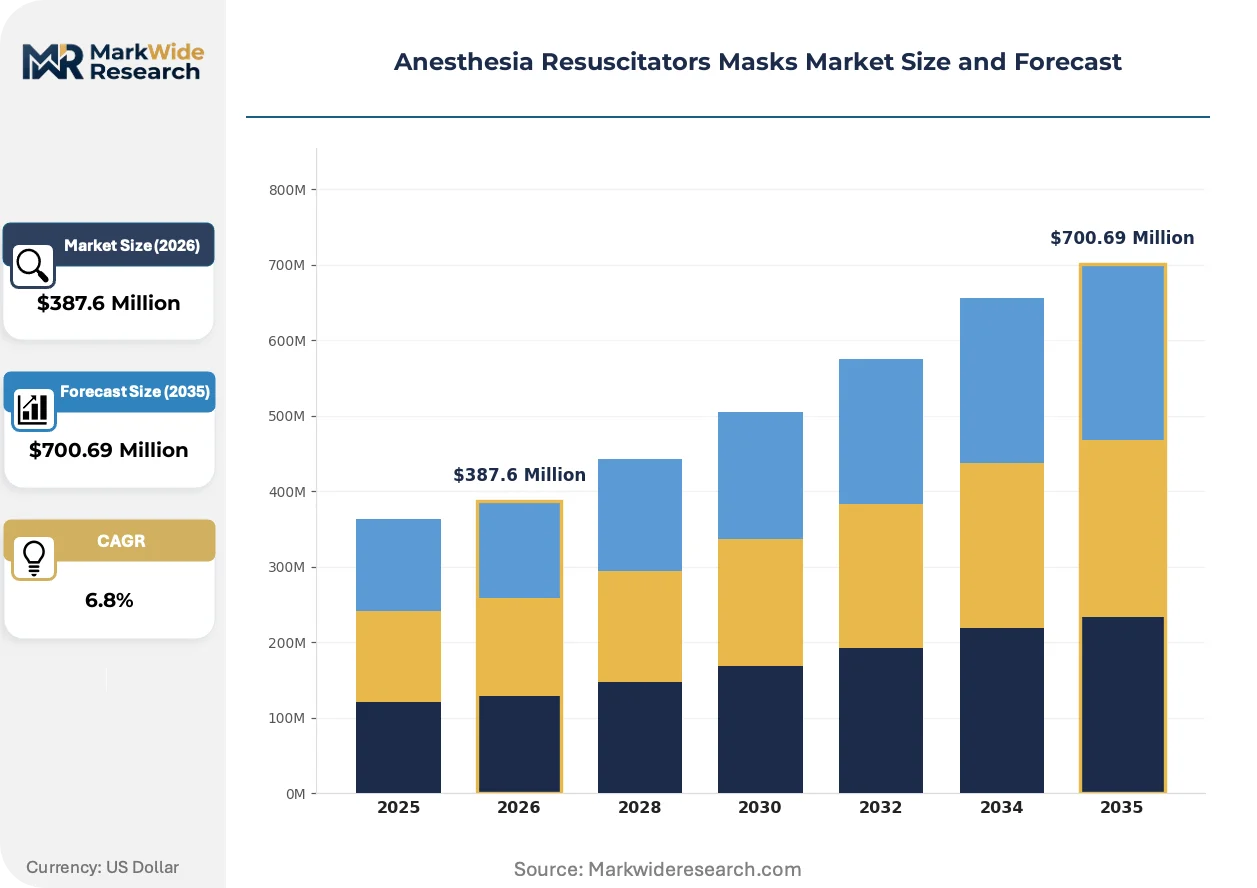
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Masks, Pediatric Masks, Neonatal Masks, Specialty Masks Material: Silicone, PVC, Rubber, Foam End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Emergency Services Application: Anesthesia, Resuscitation, Ventilation, Oxygen Therapy |
| Companies Covered | Ambu A/S, Teleflex Incorporated, Drägerwerk AG & Co. KGaA, Cardinal Health Inc., Flexicare Group Ltd., GE HealthCare Technologies Inc., Medtronic Plc, Intersurgical Ltd., GaleMed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Resuscitators Masks Market Emerging Trajectories
Digital integration across anesthesia delivery systems is digitizing patient interface monitoring, compressing the traditional separation between mask hardware and ventilation software control layers.
Embedded pressure sensors and wireless flow monitoring modules are digitizing real-time seal integrity feedback during controlled ventilation. Academic medical centers in Germany and the United States are piloting these smart mask configurations for difficult airway algorithms. The technology is digitizing anesthesia record documentation, reducing manual respiratory parameter transcription and enabling predictive leak detection before circuit disconnect.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa devices. Manufacturers must now maintain electronic implantable device-style vigilance systems for masks previously exempt from active monitoring. European hospital procurement consortia are consolidating supplier lists to those with MDR-compliant quality management systems, squeezing mid-tier competitors from tender participation.
Consolidated purchasing through United States group purchasing organizations is compressing vendor diversity in anesthesia accessories. Hospital systems are unbundling mask procurement from anesthesia workstation bundling, enabling direct price comparison across silicone and PVC alternatives. This behavioral shift is most visible in the Southeast and Midwest regions, where Ascension and CommonSpirit procurement rationalization programs are standardizing disposable mask specifications across 500-plus facility networks.
Anesthesia Resuscitators Masks Market Segmentation
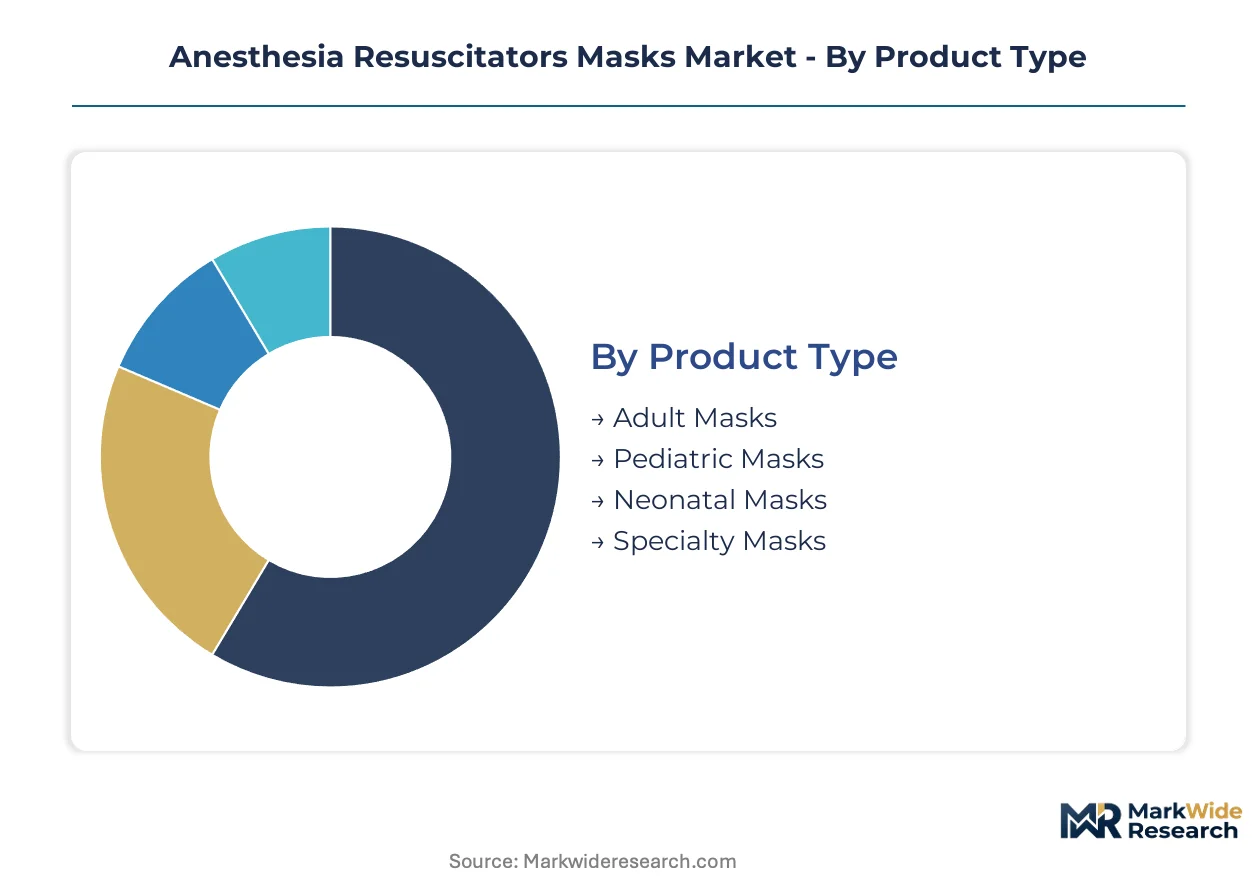
Patient interface geometry and material selection in anesthesia resuscitators masks determine seal integrity, reuse cycles, and regulatory classification. Procurement patterns diverge sharply between high-throughput surgical centers prioritizing disposability and anesthesia workstations demanding extended-use silicone durability.
Product Type:
Volume concentration across patient age bands reflects surgical caseload distribution and reimbursement-driven site-of-care migration.
- Adult Masks:Standardized anatomical profiles accommodate 90th percentile adult facial dimensions with shore hardness ratings between 35A and 45A. Hospital operating rooms in the United States absorb the bulk of procurement volume, though ambulatory surgical center uptake is compressing average order cycle times.
- Pediatric Masks:Downsized cushion geometries with reduced dead space accommodate developing facial structures and lower tidal volumes. Demand concentrates in pediatric specialty hospitals and academic medical centers with dedicated pediatric anesthesia services.
- Neonatal Masks:Ultra-soft silicone formulations with 30A shore hardness minimize pressure necrosis risk on preterm infant skin.
- Specialty Masks:MRI-compatible and difficult airway configurations incorporate non-ferrous hardware and adjustable cushion geometries.
Adult masks hold installed capacity. Specialty masks are rotating up the share rankings.
Material:
Cost tier positioning and biocompatibility requirements segment manufacturers between premium reusable and economy disposable supply chains.
- Silicone:Medical-grade platinum-cured formulations deliver 500-plus autoclave cycles with maintained seal elasticity. European hospital procurement consortia specify silicone for anesthesia workstation bundles, privileging vendors with ISO 10993 cytotoxicity dossiers.
- PVC:Plasticized polyvinyl chloride dominates high-turnover disposable segments through sub-dollar per-unit economics. Ambulatory surgical centers in the United States specify PVC for single-use protocols, though DEHP plasticizer scrutiny is elevating interest in alternative formulations.
- Rubber:Natural and synthetic rubber compounds persist in legacy anesthesia systems and developing market price-sensitive procurement.
- Foam:Cushion foam layers enhance comfort in prolonged ventilation applications and non-invasive positive pressure interfaces.
Silicone captures margin concentration. PVC is expanding most quickly in high-throughput settings.
End User:
Customer type determines volume scale, specification complexity, and distributor channel requirements.
- Hospitals:Integrated anesthesia workstations demand connector interoperability with Drägerwerk and Mindray proprietary geometries. United States health system consolidation is standardizing mask specifications across 500-plus facility networks.
- Ambulatory Surgical Centers:High-turnover procedural settings prioritize disposable PVC masks with minimal reprocessing infrastructure. United States outpatient facility construction is outpacing hospital operating room growth.
- Home Care Settings:Non-invasive ventilation and sleep apnea applications require patient-operated mask interfaces with simplified headgear.
- Emergency Services:Pre-hospital resuscitation demands compact, field-sterilizable configurations with universal connector compatibility.
Hospitals anchor procurement value. Ambulatory surgical centers are gaining share fastest.
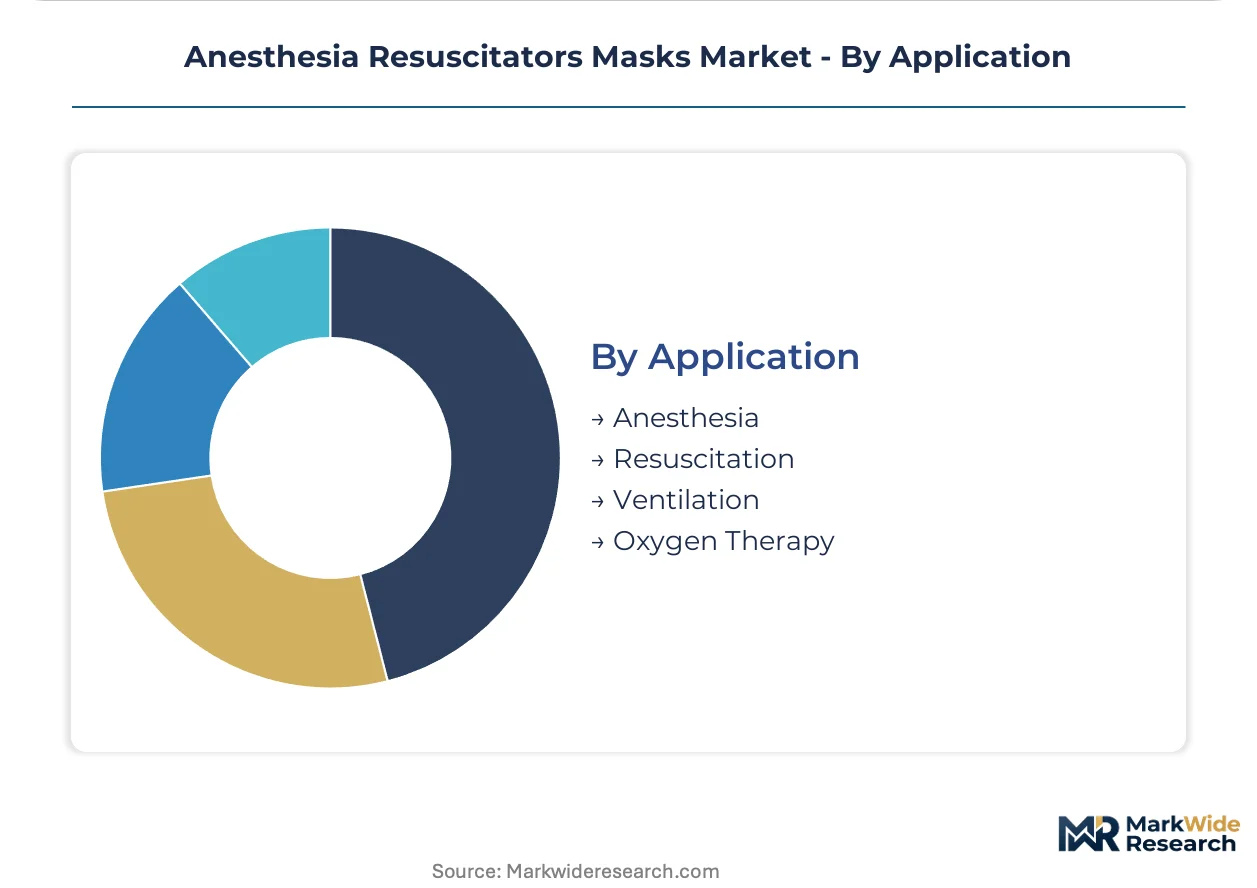
Application:
Functional use case dictates dead space tolerance, pressure monitoring integration, and gas flow resistance specifications.
- Anesthesia:Inhalational induction requires tight seal integrity with scavenging system compatibility to minimize occupational exposure. Academic medical centers in Germany are piloting embedded pressure sensors for real-time seal feedback.
- Resuscitation:Bag-valve-mask ventilation prioritizes rapid deployment and one-handed seal maintenance for cardiac arrest protocols.
- Ventilation:Controlled mechanical ventilation interfaces incorporate 22mm ISO 5356-1 connectors with minimal apparatus dead space.
- Oxygen Therapy:Simple oxygen delivery masks emphasize patient comfort over seal precision, utilizing open designs with variable FiO2 delivery.
Anesthesia commands specification leadership. Ventilation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish-manufactured silicone masks reach hospital procurement networks across Germany and the United States through specialized medical-surgical distributors. East Asian petrochemical corridors supply medical-grade silicone raw material to molding facilities serving ambulatory surgical centers in North America and Europe.
United States
Ambulatory surgical center construction outpaces hospital operating room expansion, concentrating disposable PVC mask demand in high-turnover procedural settings. FDA 510(k) premarket notification requirements for Class II medical devices privilege suppliers with robust clinical validation dossiers. Southeast and Midwest health system networks standardize mask specifications across 500-plus facility procurement programs.
Germany
Academic medical centers pilot embedded pressure sensors for real-time seal feedback during difficult airway algorithms. EU Medical Device Regulation post-market surveillance mandates systematic clinical follow-up data collection for Class IIa devices. Bavarian and Baden-Württemberg industrial clusters host anesthesia workstation bundling operations that anchor European hospital procurement.
China
Domestic surgical infrastructure buildout drives demand for cost-optimized disposable mask configurations in tier-2 city hospitals. NMPA regulatory harmonization with ISO standards shapes design dossier requirements for cross-border commercialization. Yangtze River Delta petrochemical corridors concentrate medical-grade silicone raw material production.
India
CDSCO regulatory alignment with ISO standards lowers market entry barriers for CE-certified manufacturers targeting tier-2 city hospital procurement. Government hospital infrastructure programs expand operating room capacity in Maharashtra and Karnataka. Delhi-NCR and Tamil Nadu medical device distribution hubs channel imported and domestic mask supplies to regional healthcare networks.
Japan
PMDA quality management system requirements sustain premium positioning for silicone reusable mask lines in anesthesia workstation bundles. METI industrial policy supports domestic manufacturing of high-precision medical devices. Kanto and Kansai metropolitan hospital networks maintain stringent connector interoperability specifications with proprietary workstation geometries.
Anesthesia Resuscitators Masks Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around three archetypes: integrated anesthesia workstation bundlers, disposable-focused high-throughput suppliers, and pediatric-neonatal specialty fabricators. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into MRI-compatible configurations.
Among European-anchored manufacturers, Drägerwerk AG & Co. KGaA and Ambu A/S exemplify divergent strategic positions. Drägerwerk occupies the workstation-integrated bundling tier through proprietary connector geometries that lock mask suppliers into OEM-specific tooling investments. Ambu A/S represents the integrated production model with Danish manufacturing footprints sustaining premium positioning in specialized patient age bands. Medtronic Plc anchors the North American acute care channel presence through critical care portfolio breadth that encompasses resuscitation accessories alongside anesthesia interfaces.
| Leading Market Players |
|---|
| Ambu A/S |
| Teleflex Incorporated |
| Drägerwerk AG & Co. KGaA |
| Cardinal Health Inc. |
| Flexicare Group Ltd. |
| GE HealthCare Technologies Inc. |
| Medtronic Plc |
| Intersurgical Ltd. |
| GaleMed Corporation |
| Others |
Supply Flow & Price Mechanics
Medical-grade silicone price volatility originating in East Asian petrochemical corridors compresses disposable segment margins while simultaneously widening spreads between premium reusable and economy disposable tiers, forcing manufacturers to reconfigure sourcing footprints and inventory strategies around this input cost instability.
Pricing Analysis
Next-generation embedded sensor configurations command substantial premiums over current-generation silicone molding and prior-generation PVC alternatives. Pricing stratifies across premium, standard, and economy tiers driven by ISO 10993 certification grade and volume scale procurement. Cost compression in the disposable PVC tier is intensifying because ambulatory surgical centers negotiate consolidated GPO contracts. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with anesthesia workstation bundles show lowest.
Supply Chain Analysis
Extended payment terms from United States health system consolidators strain working capital for Danish and German manufacturers serving European hospital procurement. Raw material production concentrates in China, Germany, and the United States for medical-grade silicone, PVC resin, and platinum catalyst formulations. Component sourcing draws from Yangtze River Delta petrochemical clusters, Bavarian industrial zones, and domestic compounding facilities. Single-source vulnerability persists for platinum-cured silicone grades. Distribution runs through specialized medical-surgical distributors and direct-to-facility logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated through United States health system consolidation, with Ascension and CommonSpirit procurement rationalization programs standardizing specifications across 500-plus facility networks, shifting negotiating leverage toward institutional purchasers.
For Market Incumbents: Harden FDA 510(k) dossier robustness against tightening premarket notification requirements that privilege suppliers with extensive clinical validation. Deepen backward integration into medical-grade silicone compounding to offset East Asian petrochemical price volatility. Fortify anesthesia workstation bundling relationships with proprietary connector geometries that lock out competing mask suppliers. For New Entrants and Emerging Players: Establish a beachhead in MRI-compatible mask configurations for diagnostic-surgical hybrid suites, an underserved niche with limited incumbent focus. Target tier-2 city hospital procurement in India where CDSCO regulatory harmonization lowers entry barriers for CE-certified manufacturers. Pursue direct-to-facility distribution partnerships to bypass established medical-surgical distributor markups. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape toward manufacturers with notified body-certified quality management systems and active post-market surveillance infrastructure. Long-term viability favors targets with demonstrated multi-jurisdiction compliance capabilities spanning FDA, CE marking, and emerging market regulators. Monitor notified body capacity expansion in Europe as the signal for accelerated new product introduction timelines.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Certification | EU notified body approval enables continued European hospital procurement consortium participation. |
| Silicone Compounding Backward Integration | In-house platinum-cured formulation production insulates margins from East Asian petrochemical volatility. |
| Embedded Sensor Module Development | Digital integration with Drägerwerk and Mindray workstation protocols captures next-generation premium positioning. |
| Ambulatory Surgical Center Direct Distribution | Bypassing Cardinal Health and Medline distributor networks captures margin in high-turnover disposable segments. |
| Pediatric-Neonatal Specialty Line Expansion | Ultra-soft 30A shore hardness formulations command margin premiums in academic medical center niches. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation repositories, and hospital procurement contract filings preceded structured interviews with anesthesia department heads, biomedical engineering directors, GPO contracts managers, and medical-surgical distributor category leads. Secondary validation drew from ISO standards documentation, notified body capacity reports, and petrochemical trade flow data. Bottom-up patient interface unit demand modeling triangulated against top-down anesthesia workstation installation base estimates.
Baseline assumptions held regulatory pathway timelines and health system consolidation trajectories fixed across the projection horizon, with scenario variants testing accelerated ambulatory surgical center expansion and delayed EU MDR certification completion. Segmentation dimensions encompassed patient age band, material grade tier, end-user facility type, and regional regulatory cluster. CAGRs were derived from surgical volume elasticity models and replacement cycle frequency analysis, incorporating anesthesia procedure growth rates and workstation upgrade patterns.
Stress conditions across silicone raw material price bands, notified body capacity constraints, and health system procurement consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and baseline conditions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
APAC Ablation Devices Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Water Flosser Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Medical Device Cros Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Manometry System Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Asia-Pacific General Surgical Devices Market