
 Marine Oil Water Separators Market | 2026-2036
Marine Oil Water Separators Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Oil Water Separators Market Analysis
IMO Resolution MEPC.107(49) is bifurcating the competitive landscape into certified system integrators and component suppliers without type-approval. Alfa Laval AB leverages its extensive port service network to sustain aftermarket revenue streams. Wartsila Oyj Abp anchors its position through backward integration into control automation and sensor diagnostics. GEA Group AG differentiates via specialization in high-capacity units for crude oil tankers and FPSO vessels.
Marine oil water separators are pressure-vessel systems engineered to reduce hydrocarbon content in bilge and ballast water below 15 ppm, employing gravity settling, coalescing media, or membrane filtration as primary mechanisms. Coalescing separators occupy the largest installed base due to proven reliability under variable sea states and feedstock compositions. Ultrafiltration technology leads growth trajectories as ship operators seek compliance certainty ahead of anticipated regulatory tightening. Port facility installations represent the most concentrated margin pool, driven by centralized wastewater processing economies and recurring maintenance contracts.
The US Coast Guard enforces EPA Vessel General Permit discharge limits, while the EU's MRV Maritime Regulation and IMO's DCS framework collectively reshape equipment specifications across Atlantic and Mediterranean trade lanes. China's MEE implements GB standards for domestic shipyard compliance, creating parallel certification requirements for suppliers serving the Yangtze River Delta build cluster. Stakeholders must monitor the convergence of ballast water and bilge treatment regulations, as integrated system mandates could displace standalone separator architectures.
Market Dynamics
Membrane-based ultrafiltration is decomposing the legacy coalescing separator installed base as ship operators confront MARPOL Annex I discharge thresholds tightening below 15 ppm across major flag states.
Growth Catalysts
- MARPOL Annex I enforcement:Port state control inspections in Singapore, Rotterdam, and Houston are flagging vessels with non-compliant bilge discharge systems, forcing retrofits.
- Offshore platform expansion:Floating production storage and offloading vessels in the North Sea and Gulf of Mexico require high-capacity separators with redundant membrane trains.
- Sensor diagnostics integration:Real-time oil-in-water monitoring with automated data logging is becoming mandatory for EPA Vessel General Permit compliance in US waters.
Market Restraints
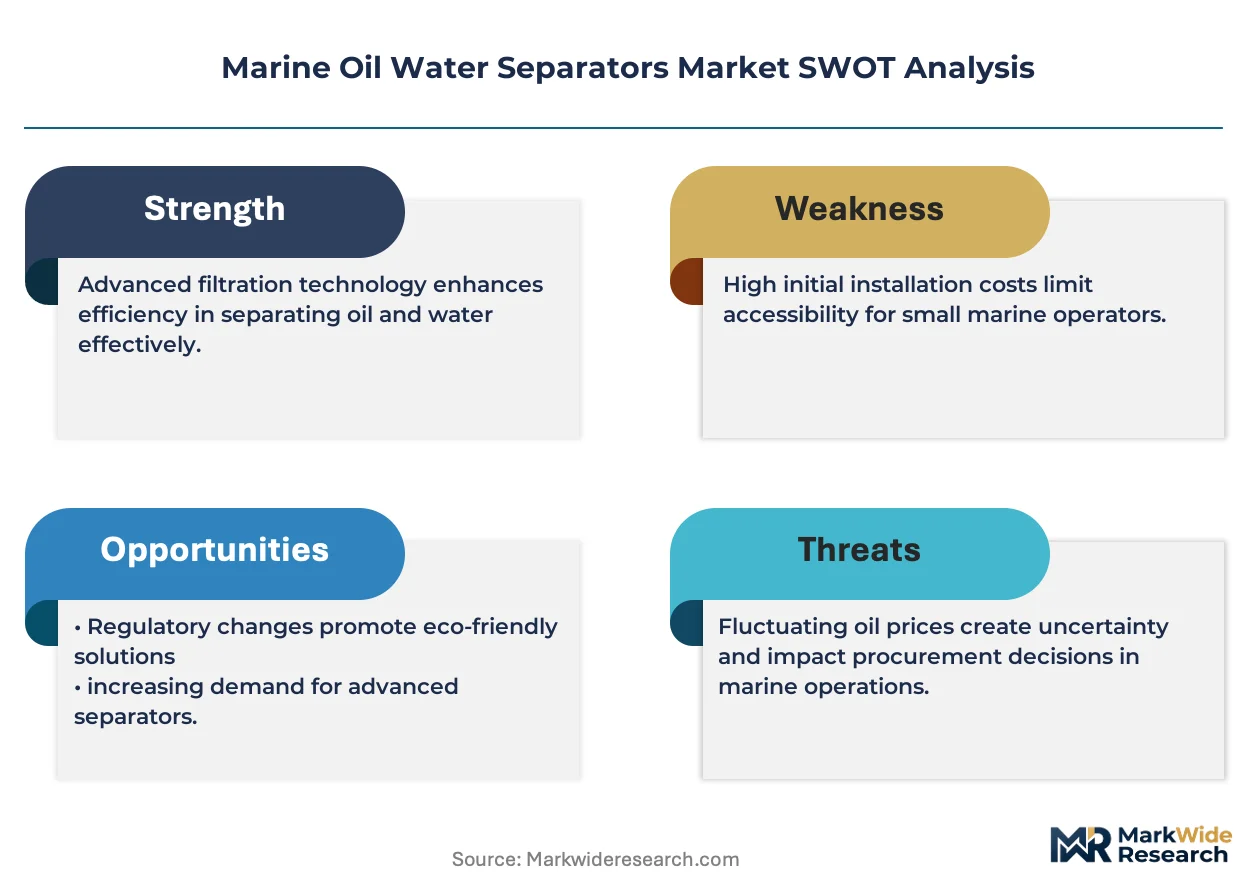
- Specialized alloy costs:Duplex stainless steel and super-duplex grades for seawater corrosion resistance face volatile nickel and molybdenum pricing from Indonesian and Philippine ore supply.
- Certification bottlenecks:IMO MEPC.107(49) type-approval timelines stretch 18-24 months, freezing out unproven entrants from commercial bidding.
- Gravity separator substitution:Simple gravity settling tanks with enhanced coalescing packs satisfy older vessel operators in flag-of-convenience registries with lax port state control.
Strategic Opportunities
- Vietnamese shipyard build-out:Hai Phong and Ba Ria-Vung Tau yards are expanding crude tanker and bulk carrier construction, creating greenfield separator specification windows.
- Ballast-bilge integration:IMO's pending unified treatment mandates could displace standalone architectures with combined systems capturing both waste streams.
- Port facility centralization:Singapore's Tuas megaport and Rotterdam's Maasvlakte terminals are consolidating wastewater processing, creating recurring service contract pools.
Industry Challenges
- Marine automation engineering scarcity:Control system integration for separator-to-vessel network connectivity requires hybrid skill sets combining process engineering with maritime cybersecurity.
- Legacy vessel retrofit access:Engine room spatial constraints on pre-2010 built tonnage limit membrane skid dimensions, forcing modular designs with higher installation labor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Oil Water Separators Market |
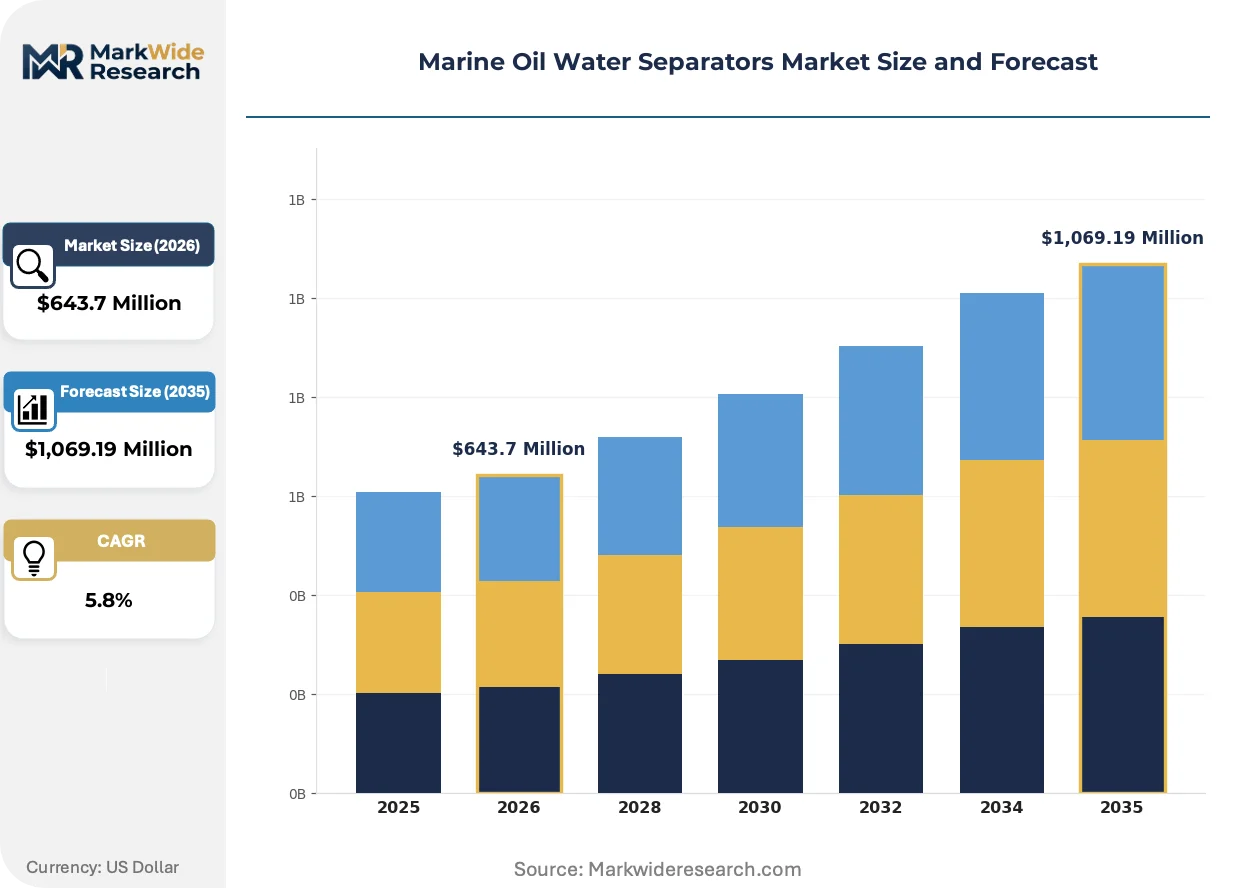
| Market Size in 2026 | $643.7 Million |
| Market Size in 2035 | $1,069.19 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Separators, Coalescing Separators, Membrane Separators, Chemical Separators End User: Shipping Companies, Oil & Gas Industry, Maritime Agencies, Fishing Vessels Technology: Electrocoagulation, Ultrafiltration, Biological Treatment, Advanced Oxidation Installation Type: Onboard Systems, Port Facilities, Wastewater Treatment Plants, Mobile Units |
| Companies Covered | Compass Water Solutions, Inc., Freytech Inc., Promac B.V., Sulzer Ltd, Wartsila Oyj Abp, Alfa Laval AB, GEA Group AG, Victor Marine Ltd., SkimOIL, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Oil Water Separators Market Emerging Trajectories
Active filtration mechanisms are overtaking passive separation as regulatory certainty becomes the dominant purchase criterion ahead of hardware lifecycle cost.
Ceramic membrane ultrafiltration is decomposing the competitive advantage of incumbent coalescing pack suppliers. These inorganic filters achieve consistent 5 ppm discharge without chemical demulsifier injection. FPSO operators in Brazil's pre-salt fields and North Sea decommissioning projects are specifying ceramic trains for heavy crude emulsion stability. The technology is compressing maintenance intervals from quarterly coalescing pack replacement to annual membrane cleaning cycles.
EPA's Vessel General Permit 2013 modification and subsequent enforcement guidance are reshaping equipment specifications for US-flagged and US-trading vessels. The permit's numeric effluent limits and electronic reporting mandates have eliminated grandfathered gravity-only systems from commercial viability. Ship managers operating Jones Act tankers and Great Lakes bulk carriers are prioritizing certified systems with automated sampling protocols over lower-cost uncertified alternatives.
Buyer consolidation among top-20 container lines is concentrating procurement leverage with fleet technical managers in Copenhagen, Geneva, and Singapore. These centralized purchasing functions are unbundling separator supply from shipyard newbuild contracts, creating direct manufacturer relationships and compressing distributor margins. The shift is most visible in ultra-large container vessel orders where technical specifications are set at headquarters level rather than delegated to Asian yard engineering teams.
Marine Oil Water Separators Market Segmentation
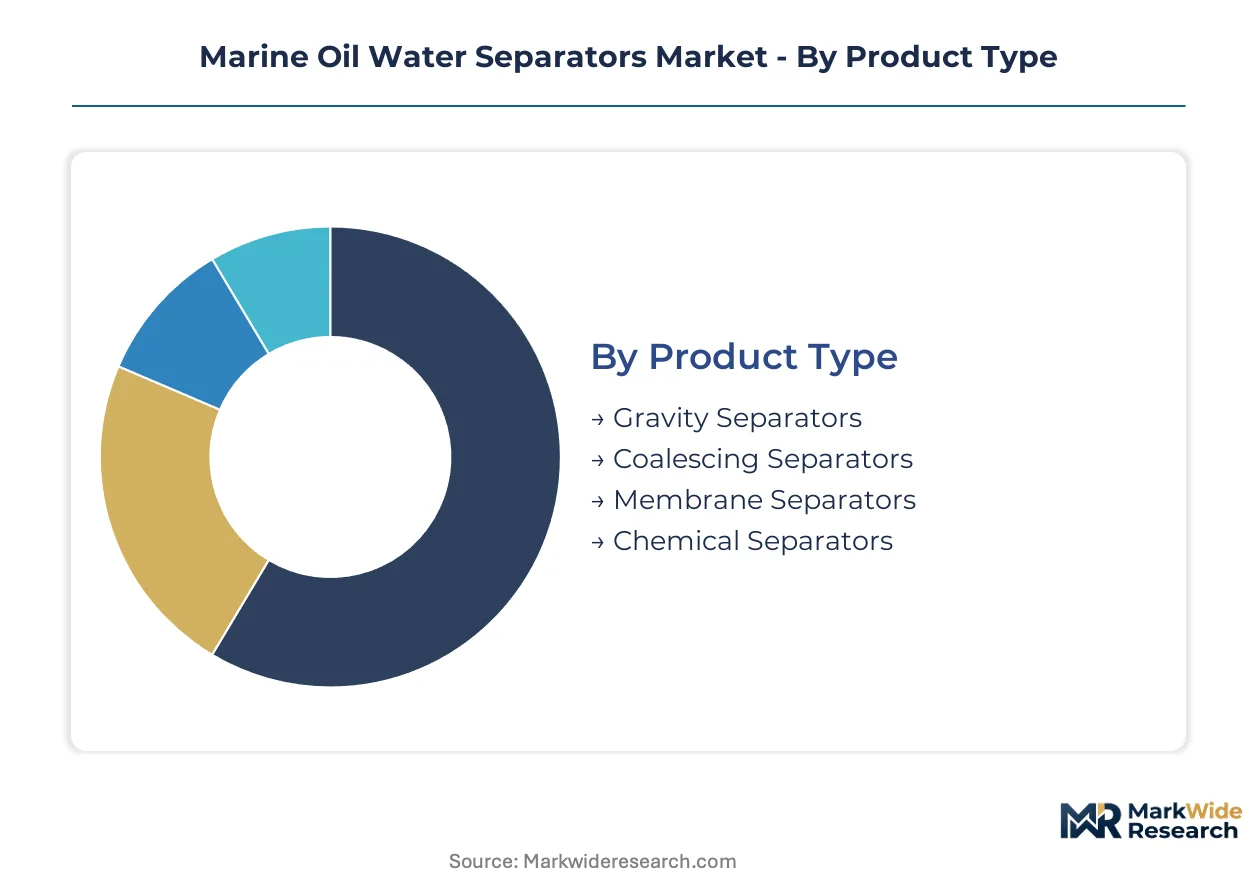
Marine oil water separator procurement channels bifurcate sharply between shipyard-integrated newbuild specifications and aftermarket retrofit contracts. Channel selection determines margin capture, certification requirements, and service revenue attachment rates across the product lifecycle.
Product Type:
Gravity separators and coalescing units flow through established shipyard supply chains with long-term service contracts, while membrane systems increasingly bypass yards for direct fleet operator procurement.
- Gravity Separators:Passive settling tanks with internal baffle configurations achieve 15 ppm discharge through density differential separation without moving parts. Demand concentrates in older bulk carriers registered under Panamanian and Liberian flags where port state control enforcement remains intermittent. Operators favor these units for minimal maintenance burden during extended ocean transits.
- Coalescing Separators:Packed media beds leverage oleophilic surface properties to agglomerate fine oil droplets into separable fractions. Singapore's Tuas megaport and Rotterdam's Maasvlakte terminals specify these systems for centralized bilge water processing, driven by MARPOL Annex I compliance certainty requirements and recurring media replacement revenue streams.
- Membrane Separators:Ceramic and polymeric ultrafiltration modules achieve sub-5 ppm discharge without chemical injection.
- Chemical Separators:Demulsifier dosing systems break stable emulsions through surfactant-induced phase separation.
Coalescing separators dominate installed base. Membrane separators are where expansion concentrates.
End User:
End-user concentration shapes pricing power and specification authority, with top-20 container lines consolidating technical procurement at headquarters level while fragmented fishing fleets defer to yard recommendations.
- Shipping Companies:Container lines, tanker operators, and bulk carriers face direct liability for MARPOL violations under port state control. Maersk, MSC, and COSCO headquarters technical teams in Copenhagen, Geneva, and Shanghai now unbundle separator procurement from newbuild contracts, compressing distributor margins while demanding automated monitoring integration.
- Oil & Gas Industry:FPSO operators and offshore platform managers require redundant membrane trains with 99.9% availability guarantees. Brazil's pre-salt fields and North Sea decommissioning projects specify ceramic ultrafiltration for heavy crude emulsion stability, driven by zero-discharge regulatory commitments and production continuity requirements.
- Maritime Agencies:Coast guard and port authority installations prioritize certified systems with tamper-evident data logging for enforcement evidence.
- Fishing Vessels:Smaller fleet operators in Southeast Asian and West African waters favor basic gravity systems with minimal capital outlay.
Shipping companies command specification authority. Oil and gas operators are climbing the fastest for high-capacity membrane systems.
Technology:
Technology selection tracks regulatory stringency gradients, with ultrafiltration penetrating flag states with active port state control while electrocoagulation retains share in enforcement-light jurisdictions.
- Electrocoagulation:Sacrificial aluminum or iron anodes generate flocculating hydroxides through electrochemical dissolution. Demand persists in Chinese domestic coastal shipping where MEE enforcement of GB standards creates compliance pressure without mandating specific separation mechanisms, allowing lower capital cost solutions.
- Ultrafiltration:Cross-flow membrane modules with 0.01-0.1 micron pore ratings exclude emulsified oil droplets without phase change. US-flagged Jones Act tankers and Great Lakes bulk carriers specify these systems under EPA Vessel General Permit numeric effluent limits, where automated sampling protocols eliminate grandfathered gravity-only alternatives from commercial viability.
- Biological Treatment:Aerobic bacterial consortia degrade soluble hydrocarbons to carbon dioxide and biomass.
- Advanced Oxidation:Hydroxyl radical generation through ozone, UV, or Fenton chemistry mineralizes recalcitrant organics.
Ultrafiltration dominates new specification. Electrocoagulation retains retrofit share in cost-sensitive fleets.
Installation Type:
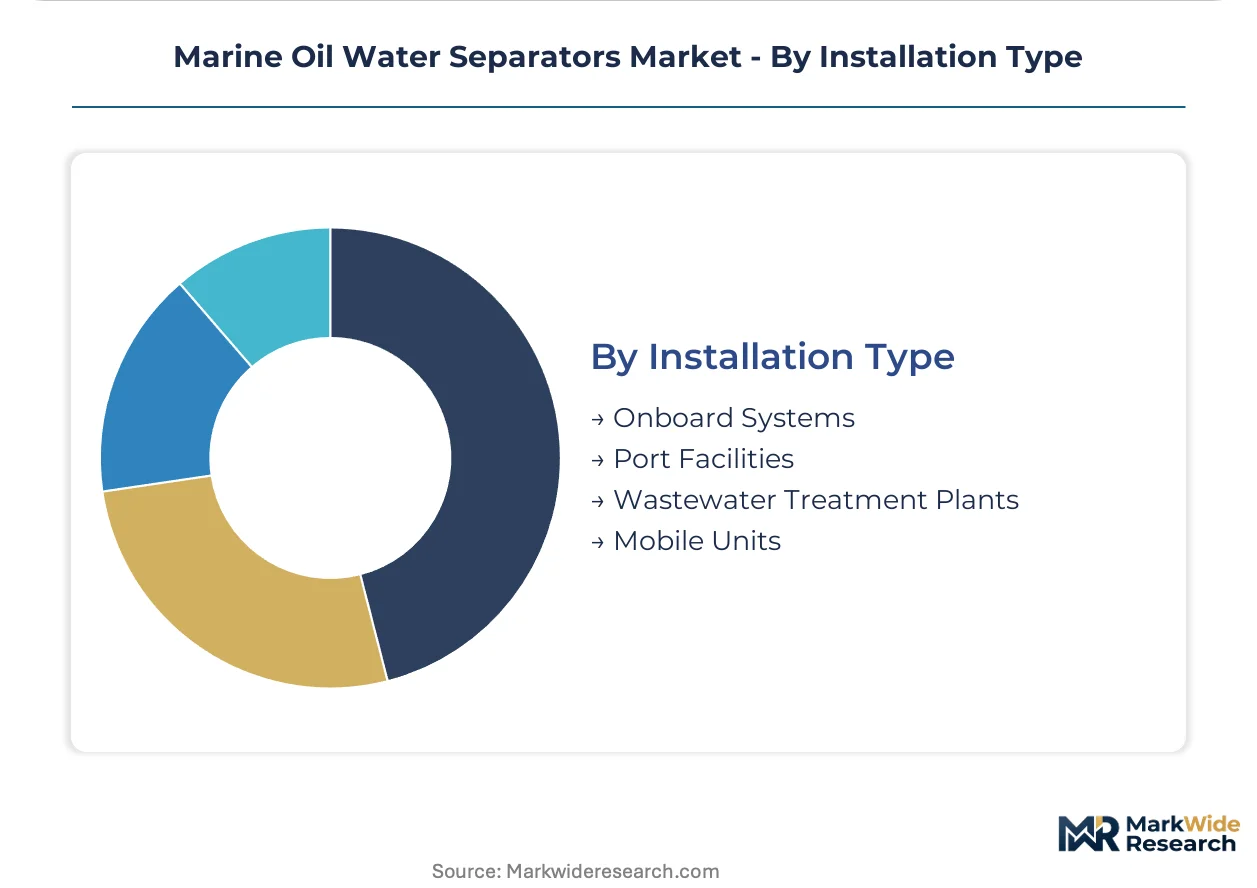
Installation location determines system scale, redundancy architecture, and service contract structure, with port facilities capturing the most concentrated margin pools through centralized processing economics.
- Onboard Systems:Skid-mounted packages integrated into engine room bilge circuits with real-time oil-in-water monitoring. Pre-2010 built tonnage faces spatial constraints forcing modular designs with elevated installation labor, particularly in Mediterranean and Southeast Asian repair yards where legacy vessel retrofit activity concentrates.
- Port Facilities:Shore-based reception and treatment systems serving multiple vessels through pipeline connections. Singapore's Tuas and Rotterdam's Maasvlakte terminals are consolidating wastewater processing, creating recurring maintenance contract pools with 10-15 year service agreements and guaranteed throughput pricing.
- Wastewater Treatment Plants:Land-based industrial facilities processing concentrated marine waste streams.
- Mobile Units:Containerized or trailer-mounted systems for emergency response and temporary operations.
Onboard systems retain volume leadership. Port facilities are gaining share fastest through megaport centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's Maasvlakte terminals anchor European demand for centralized marine wastewater processing infrastructure, while Singapore's Tuas megaport consolidation drives Southeast Asian specification trends.
United States
EPA Vessel General Permit enforcement and Jones Act tanker operations sustain demand for certified ultrafiltration systems. The US Coast Guard mandates automated oil-in-water monitoring with tamper-evident data logging for enforcement evidence. Houston's port facility cluster and Great Lakes bulk carrier repair yards concentrate retrofit activity for pre-2010 built tonnage facing spatial constraints.
Germany
North Sea offshore decommissioning projects and FPSO operations require redundant membrane trains with availability guarantees. The country's implementation of EU MRV Maritime Regulation and IMO DCS framework shapes equipment specifications for Atlantic trade lanes. Hamburg and Bremerhaven port authorities prioritize certified systems for centralized bilge water reception facilities.
Singapore
Tuas megaport centralization creates recurring 10-15 year service contract pools for high-capacity coalescing and membrane systems. The Maritime and Port Authority enforces MARPOL Annex I compliance through active port state control inspections flagging non-compliant vessels. Jurong shipyard cluster and surrounding Southeast Asian build centers concentrate newbuild specification windows for crude tankers and bulk carriers.
China
Yangtze River Delta shipyard compliance with MEE GB standards creates parallel certification requirements for domestic and export vessels. The country's dual carbon goals and maritime decarbonization policies reshape equipment specifications across coastal shipping lanes. Shanghai and Ningbo-Zhoushan port clusters drive demand for shore-based reception systems with guaranteed throughput pricing structures.
Brazil
Pre-salt field FPSO operators specify ceramic ultrafiltration for heavy crude emulsion stability under zero-discharge regulatory commitments. ANVISA and environmental agency oversight of offshore production continuity requirements sustains demand for redundant system architectures. Rio de Janeiro and São Paulo engineering procurement centers concentrate technical specification authority for floating production assets.
Marine Oil Water Separators Market Vendor Landscape
Listed leaders compete with private specialists across certification timelines and aftermarket service reach, creating a tiered structure where type-approval status determines bidding eligibility. The competitive landscape bifurcates between integrated system providers with port service networks and component fabricators serving as tier-2 suppliers. Strategic archetypes include full-lifecycle service integrators, membrane technology specialists, and shipyard-embedded equipment packagers. Dominant competitive moves center on backward integration into control automation and geographic expansion through port facility service contracts.
Among Nordic-listed industrial conglomerates, Alfa Laval AB and Wartsila Oyj Abp exemplify the full-lifecycle service archetype, leveraging extensive port service networks to sustain aftermarket revenue attachment. GEA Group AG represents the high-capacity specialization tier, with German engineering heritage positioning it for crude tanker and FPSO vessel specifications. Swiss-based Sulzer Ltd occupies a distinct position among pump and separation technology providers, reflecting the concentration of European industrial engineering capability in this regulated equipment category.
| Leading Market Players |
|---|
| Compass Water Solutions, Inc. |
| Freytech Inc. |
| Promac B.V. |
| Sulzer Ltd |
| Wartsila Oyj Abp |
| Alfa Laval AB |
| GEA Group AG |
| Victor Marine Ltd. |
| SkimOIL, Inc. |
| Others |
Supply Flow & Price Mechanics
Ceramic membrane substitution for polymeric coalescing packs is redrawing procurement geography toward German and Japanese ceramic foundries while compressing margin structures for incumbent pack suppliers dependent on quarterly replacement cycles. This materials transition simultaneously elevates upfront system costs and extends service intervals, altering how ship operators evaluate total lifecycle economics.
Pricing Analysis
Certification level under IMO MEPC.107(49) creates the primary spread between premium type-approved systems and uncertified alternatives. Three-tier pricing structure across IMO-certified, CE-marked, and non-certified equipment segments reflects differential compliance certainty. Pricing pressure stems from buyer consolidation among top-20 container lines unbundling procurement from shipyard contracts. Flag-of-convenience operators exhibit highest price sensitivity, while Jones Act and EU-flagged fleets prioritize certified systems regardless of premium.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Singapore port congestion shape component landed costs for European and Asian system integrators. Duplex stainless steel plate mills in Sweden and Finland anchor supply for corrosion-resistant pressure vessels, while ceramic membrane substrates draw from Japanese and German precision ceramics manufacturers. Single-source vulnerability concentrates in Indonesian and Philippine nickel-molybdenum ore supply for super-duplex alloys. Distribution runs through shipyard-embedded equipment packagers and direct fleet operator procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine oil water separation is approaching a platform-economics inflection where automated monitoring data streams and predictive maintenance algorithms become the primary value capture mechanism, displacing hardware margins. Interoperability between separator control systems and vessel-wide automation networks is the critical ecosystem shift.
For Market Incumbents: Compound aftermarket revenue attachment by embedding sensor diagnostics and predictive maintenance algorithms into type-approved system architectures. Deepen backward integration into ceramic membrane substrate production to defend margin position against specialty materials suppliers. Prioritize port facility service contract concentration at Singapore Tuas and Rotterdam Maasvlakte terminals where recurring maintenance pools are consolidating. For New Entrants and Emerging Players: Differentiate on ceramic membrane ultrafiltration specialization for FPSO heavy crude applications where incumbent coalescing suppliers lack emulsion stability performance. Target Vietnamese shipyard build-out at Hai Phong and Ba Ria-Vung Tau yards for greenfield specification windows before procurement centralizes. Pursue direct fleet operator relationships rather than shipyard channel dependence. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement acceleration phase that favors integrated system providers with type-approval moats and port service networks. Long-term viability rests on data-enabled service revenue streams rather than hardware shipment cyclicality. Acquisition targets should demonstrate automated monitoring integration capabilities and established IMO certification timelines. Watch EPA Vessel General Permit enforcement intensity as inflection indicator for US-market premium system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Membrane Production | Captures margin pool from Japanese and German substrate suppliers while securing supply continuity for FPSO specifications. |
| Port Facility Service Contract Concentration | Locks in 10-15 year recurring revenue streams at Singapore Tuas and Rotterdam Maasvlakte megaport consolidations. |
| Automated Monitoring Platform Development | Enables predictive maintenance offerings that satisfy EPA tamper-evident data logging mandates for Jones Act compliance. |
| Vietnamese Shipyard Direct Specification | Bypasses distributor margin compression by establishing fleet operator relationships before procurement centralizes. |
| Ballast-Bilge Integrated System Architecture | Positions for anticipated IMO unified treatment mandates that would displace standalone separator installations. |
Methodological Framework
A spread of perspectives from fleet technical managers at container line headquarters, shipyard procurement officers at Singapore and Chinese build centers, port authority environmental compliance leads, and aftermarket service directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through IMO MEPC submission databases, EPA Vessel General Permit enforcement records, and classification society type-approval registries. Bottom-up vessel fleet analysis and top-down regulatory impact assessment were triangulated against equipment shipment tracking.
Segmentation dimensions modeled include separation technology type, installation location, vessel class, and regulatory compliance tier across the projection horizon. CAGRs were derived from equipment specification trends correlated with fleet age profiles and port state control enforcement intensity. Forecast inputs incorporated MARPOL Annex I amendment trajectories, nickel alloy price volatility assumptions, and shipyard capacity expansion schedules.
Forecasts assume regulatory continuity in IMO MARPOL enforcement, EPA Vessel General Permit numeric limits, and EU MRV Maritime Regulation implementation; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Frac Services Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Global Artificial Lift Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Crude Oil Carriers Market