
 Riserless Light Well Intervention Market | 2026-2036
Riserless Light Well Intervention Market Size, Share, and Industry Trends Forecast 2026-2036
Riserless Light Well Intervention Market Analytics
Subsea equipment leasing channels is tilting toward integrated service packages that bundle vessels, intervention tools, and remote monitoring. Schlumberger leverages its subsea technology portfolio to control deployment logistics across multiple basins. Baker Hughes anchors its position through proprietary riserless intervention tools designed for high-pressure wellheads. TechnipFMC competes by sustaining manufacturing scale in subsea production systems that interface directly with light intervention architectures.
Riserless light well intervention deploys wireline, coiled tubing, or hydraulic workover techniques through a subsea lubricator or moonpool system without a rigid riser, typically operating at water depths exceeding 300 meters to restore or enhance well productivity. The method eliminates riser installation time and reduces vessel day-rate exposure, making it economically viable for marginal field rejuvenation and subsea well maintenance. Wireline services lead the service type segment due to established reliability in perforation and logging operations, though coiled tubing services represent the fastest-growing category as operators push into live-well milling and scale removal. Production optimization commands the largest application share because subsea choke adjustments and chemical injection repairs deliver immediate barrel recovery without well shut-in.
Offshore regulators including the US Bureau of Safety and Environmental Enforcement, Norway's Petroleum Safety Authority, and Brazil's national petroleum agency enforce well integrity and barrier management standards that directly shape intervention frequency and documentation requirements. The US Safety and Environmental Management Systems rule and Norway's Management Regulations mandate systematic verification of subsea well barriers, compelling operators to schedule proactive light interventions rather than reactive repairs. Stakeholders must monitor evolving decommissioning liability frameworks and vessel emission standards, as these will determine whether riserless economics retain their edge over platform-based alternatives.
Market Dynamics
Subsea well integrity mandates from multiple national regulators are compressing intervention cycles and forcing operators toward riserless architectures that minimize platform downtime. This regulatory pressure interacts with vessel day-rate volatility to reshape contracting structures across the value chain.
Growth Catalysts
- Norway's Management Regulations:Systematic barrier verification requirements compel North Sea operators to schedule proactive light interventions rather than deferred repairs, directly expanding service demand.
- Wireline perforation reliability:Mature wireline technologies enable rapid deployment for logging and perforation operations without well shut-in, sustaining adoption in brownfield rejuvenation programs.
- Gulf of Mexico base decline:Deepwater legacy wells along the US Gulf Coast exhibit accelerating production decay, creating concentrated demand for riserless choke adjustments and chemical injection repairs.
Market Restraints
- Specialized vessel scarcity:Purpose-built intervention vessels concentrate among a limited pool of North Sea and Gulf of Mexico operators, creating booking bottlenecks during seasonal demand peaks.
- High-pressure wellhead compatibility:Proprietary riserless tool interfaces limit interchangeability across subsea hardware generations, fragmenting service provider capabilities.
- Platform-based intervention economics:Existing platform infrastructure at shallow-water brownfields offers lower marginal cost for workover operations, constraining riserless penetration in depths below 300 meters.
Strategic Opportunities
- Brazil pre-salt expansion:Brazil's national petroleum agency enforcement of well integrity standards across pre-salt developments creates untapped demand for remote diagnostic and light intervention services.
- Coiled tubing live-well milling:Emerging scale removal and milling applications through coiled tubing expand serviceable addressable market beyond traditional wireline scopes.
- Integrated service packaging:Bundling vessels, intervention tools, and remote monitoring into unified contracts captures margin from fragmented procurement patterns.
Industry Challenges
- Subsea lubricator certification timelines:Pressure-containing equipment qualification for high-pressure high-temperature wells extends deployment lead times and compresses operational windows.
- Cross-disciplinary crew composition:Riserless operations require simultaneous expertise in subsea systems, dynamic positioning, and well intervention, narrowing available talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riserless Light Well Intervention Market |
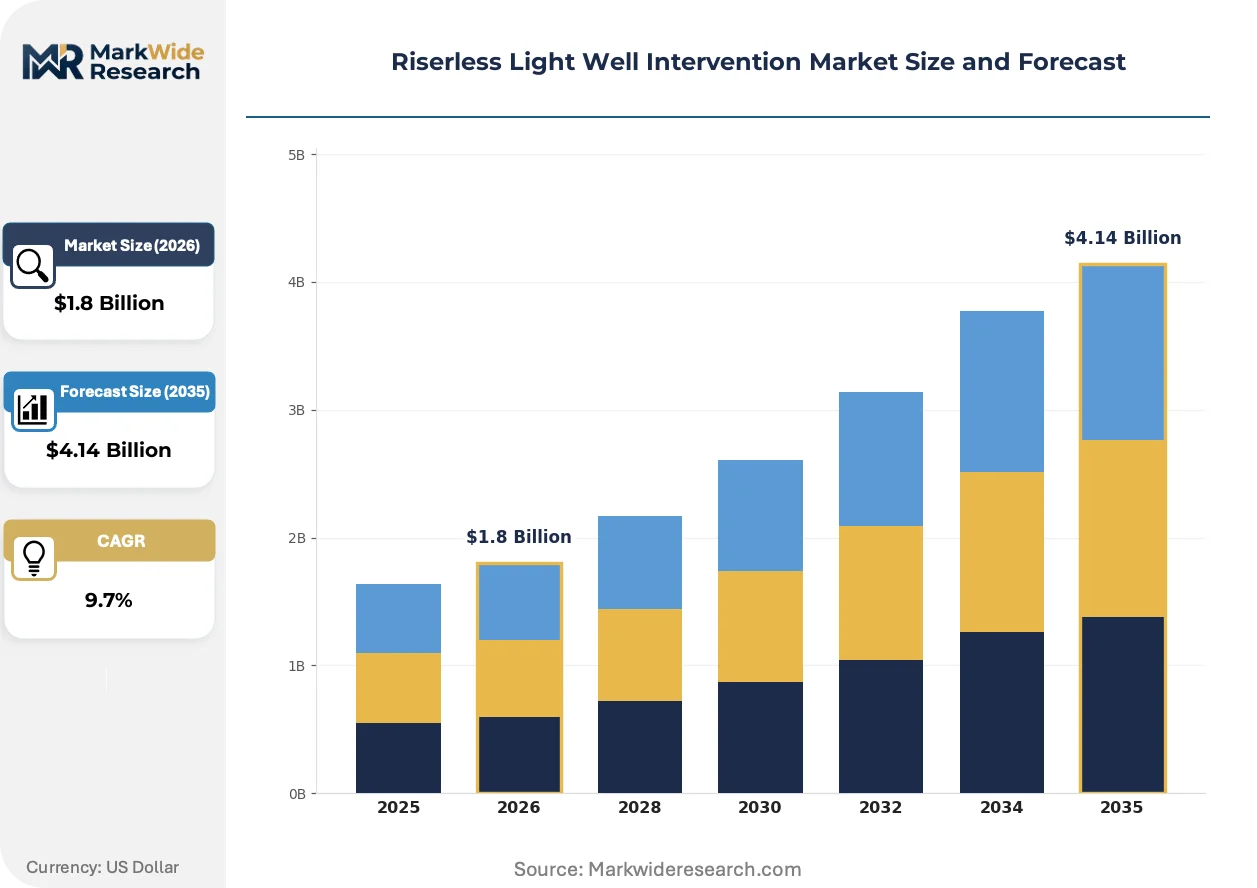
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wireline Services, Coiled Tubing Services, Intervention Services, Drilling Services Application: Production Optimization, Well Maintenance, Well Completion, Asset Recovery End User: Oil & Gas Operators, Service Companies, Independent Producers, Energy Firms Technology: Subsea Technology, Remote Operation, Intervention Tools, Diagnostic Equipment |
| Companies Covered | Schlumberger, TechnipFMC, Expro, NOV, Helix Energy Solutions, Halliburton, Oceaneering, Aker Solutions, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riserless Light Well Intervention Market Evolving Landscape
Remote monitoring architectures and autonomous subsea systems are reconfiguring intervention economics by reducing vessel dependency and enabling predictive maintenance scheduling. These shifts compress the traditional trade-off between intervention frequency and operational cost.
Subsea resident robotics and autonomous intervention systems are rendering obsolete the conventional vessel-tethered deployment model for routine diagnostic operations. Offshore operators in the North Sea and Gulf of Mexico are piloting resident systems for continuous well monitoring. This shift is compressing intervention response times from weeks to hours while reducing carbon-intensive vessel movements.
The US Bureau of Safety and Environmental Enforcement Safety and Environmental Management Systems rule mandates systematic hazard analysis and barrier verification documentation for all subsea operations. Operators must now maintain real-time well integrity records accessible to federal inspectors. Subsea choke adjustment and chemical injection repair services face heightened documentation burdens, driving investment in digital twin technologies that automate compliance reporting.
Service unbundling is fragmenting traditional integrated contracts as asset operators separate vessel chartering from tool provision and remote diagnostics. Major Gulf of Mexico producers now tender vessel, lubricator, and monitoring services through distinct procurement channels. This pattern is most visible among independent operators seeking to optimize day-rate exposure against intervention frequency.
Riserless Light Well Intervention Market Segmentation
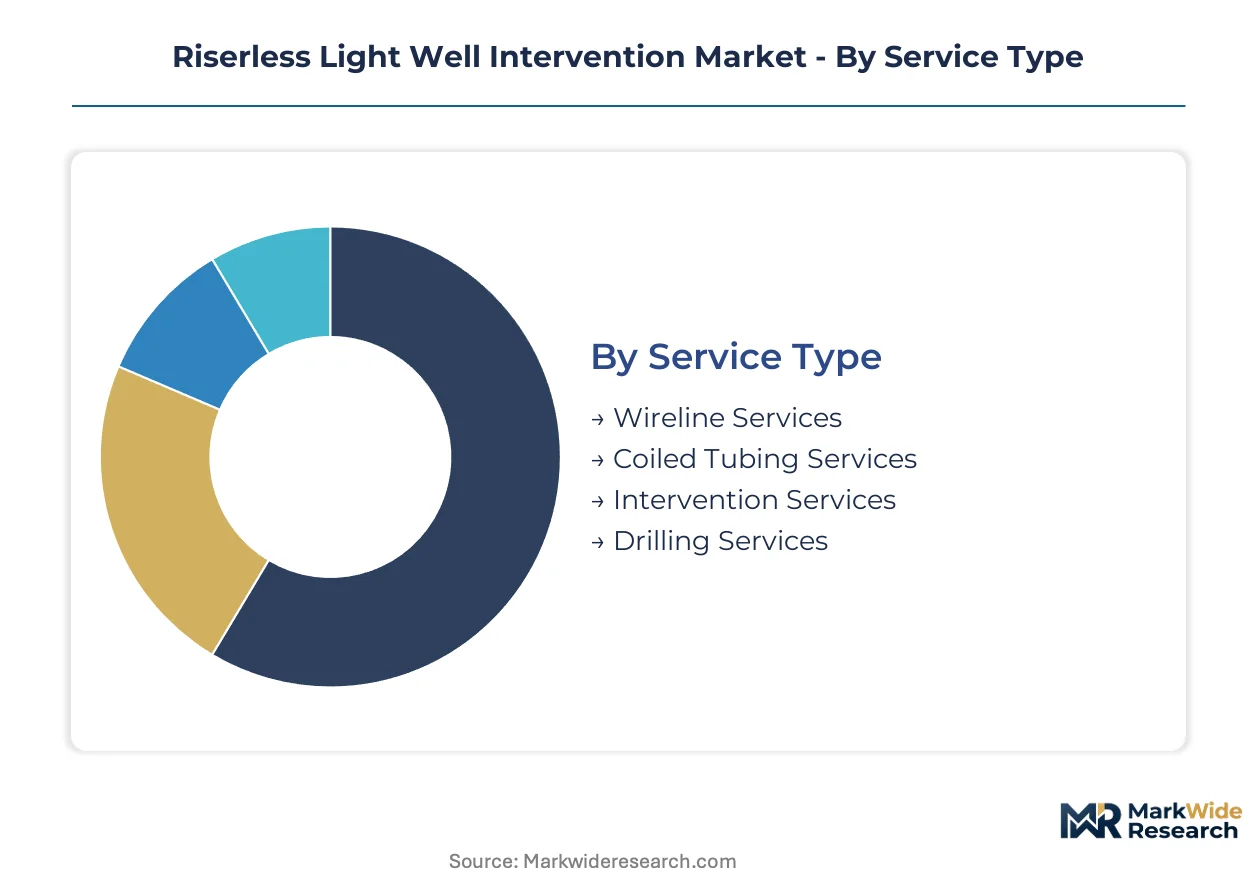
Riserless light well intervention spans four distinct segmentation axes that reflect the interplay between deployment technology, well lifecycle stage, and operator procurement models. Each category reveals different margin structures and competitive dynamics across the value chain.
Service Type:
Mature wireline capabilities dominate current deployment frequency, while emerging coiled tubing applications reshape addressable scope for live-well operations.
- Wireline Services:Conventional cable-based deployment enables perforation, logging, and plug setting without well shut-in. Demand concentrates along the US Gulf Coast deepwater corridor where brownfield operators prioritize rapid choke adjustments and barrier verification mandated by the US Bureau of Safety and Environmental Enforcement.
- Coiled Tubing Services:Continuous tubing deployment supports live-well milling, scale removal, and nitrogen lifting at pressures exceeding wireline limits. Norwegian North Sea operators are expanding adoption for subsea wellbore cleanouts where Norway's Petroleum Safety Authority mandates documented barrier integrity.
- Intervention Services:Hydraulic workover and pumping operations for well kill and circulation.
- Drilling Services:Slim-hole sidetracking and re-entry drilling through subsea lubricator systems.
Wireline retains volume leadership; coiled tubing holds the steepest expansion curve.
Application:
Cost tier segmentation separates immediate barrel recovery operations from capital-intensive completion activities, with maintenance interventions occupying the mid-tier spend profile.
- Production Optimization:Subsea choke adjustments, gas lift repairs, and chemical injection restoration deliver immediate production uplift without shut-in. Gulf of Mexico independents concentrate procurement here to combat base decline rates from legacy deepwater wells.
- Well Maintenance:Scale removal, sand cleanout, and tubular integrity verification sustain well deliverability. Norway's Petroleum Safety Authority systematic barrier verification requirements are compressing intervention cycles for this application.
- Well Completion:Perforation, stimulation, and lower completion installation for new zones.
- Asset Recovery:Plug and abandonment preparation, reservoir data acquisition for decommissioning.
Production optimization commands the largest spend tier; well maintenance is expanding most quickly on regulatory compulsion.
End User:
Customer type fragmentation reflects divergent procurement sophistication, with integrated operators favoring bundled contracts and independents unbundling vessel from tool provision.
- Oil & Gas Operators:Integrated majors and national oil companies with direct well ownership and long-term intervention scheduling.
- Service Companies:Integrated oilfield service providers delivering bundled vessel, tool, and monitoring packages across multiple basins.
- Independent Producers:Asset operators with concentrated Gulf of Mexico or North Sea positions optimizing day-rate exposure against intervention frequency.
- Energy Firms:Diversified energy companies with subsea assets transitioning from exploration to production optimization.
Oil & Gas Operators retain contract volume leadership; Independent Producers are gaining share fastest through unbundled procurement.
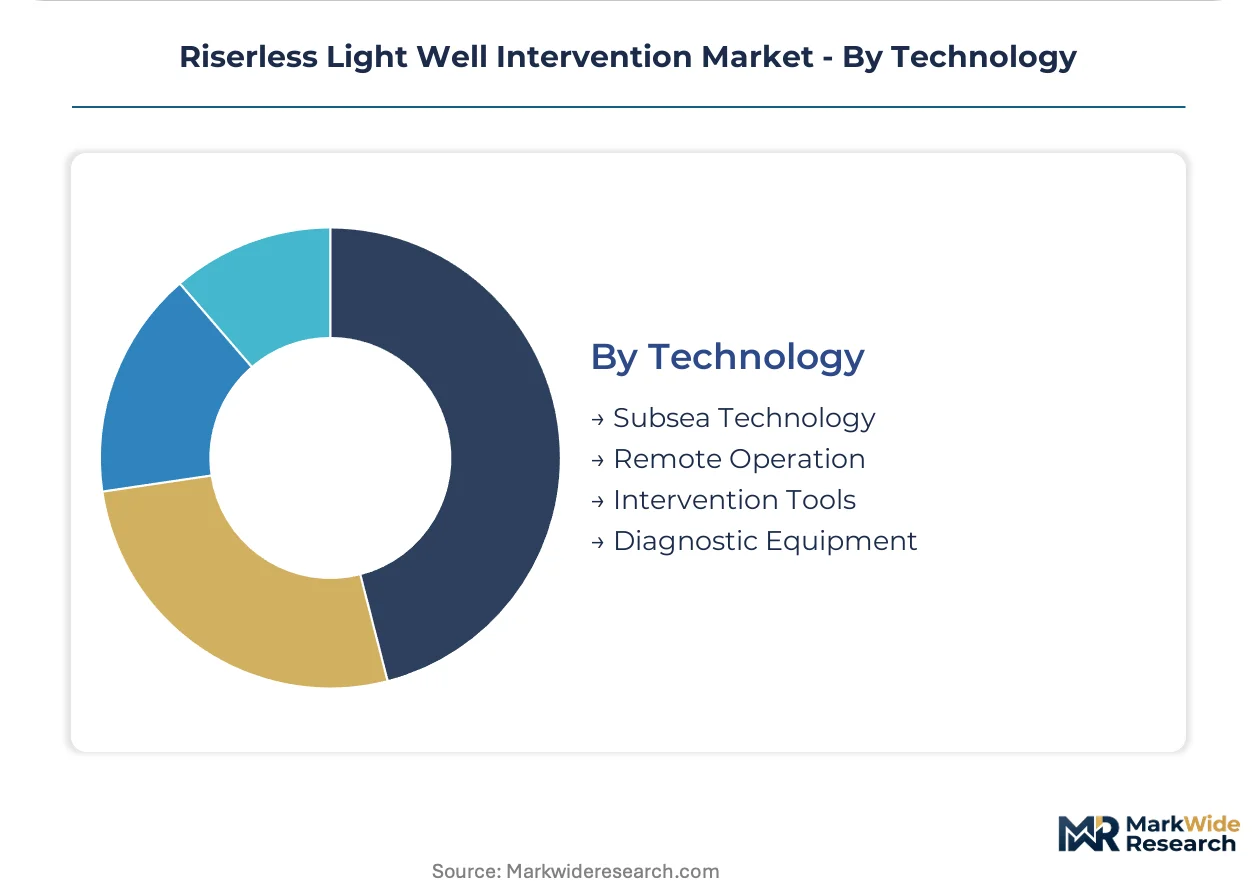
Technology:
Supply concentration clusters around subsea system integration, with remote operation architectures emerging as the primary margin expansion vector.
- Subsea Technology:Subsea lubricators, wellhead interfaces, and pressure control systems enabling riserless deployment. Gulf of Mexico and North Sea vessel operators concentrate procurement with TechnipFMC and Baker Hughes for high-pressure wellhead compatibility.
- Remote Operation:Surface-controlled downhole tools and real-time monitoring systems reducing vessel dependency. Brazil's national petroleum agency enforcement of well integrity documentation is accelerating investment here.
- Intervention Tools:Wireline tractors, coiled tubing connectors, and hydraulic workover snubbing systems.
- Diagnostic Equipment:Logging tools, pressure sensors, and flow measurement instruments for barrier verification.
Subsea Technology retains installed base leadership; Remote Operation is climbing the fastest on carbon reduction and crew scarcity pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's Petroleum Safety Authority mandates systematic barrier verification for subsea wells, accelerating riserless intervention demand across the North Sea. The US Bureau of Safety and Environmental Enforcement enforces Safety and Environmental Management Systems documentation requirements that compress intervention cycles. Brazil's national petroleum agency extends well integrity standards to pre-salt developments, creating new service demand corridors.
United States
Gulf of Mexico independents combat accelerating base decline rates from legacy deepwater wells through riserless choke adjustments and chemical injection repairs. The US Bureau of Safety and Environmental Enforcement mandates real-time well integrity records accessible to federal inspectors, driving investment in digital twin technologies. Houston anchors the deepest concentration of intervention vessel operators and subsea technology procurement.
Norway
North Sea brownfield operators expand riserless adoption to defer platform decommissioning costs while satisfying stringent documentation requirements. Norway's Petroleum Safety Authority Management Regulations compel proactive light interventions rather than deferred repairs, directly expanding service demand. Stavanger and Bergen host the primary clusters of subsea system integrators and specialized intervention vessel operators.
Brazil
Pre-salt development operators face escalating well integrity enforcement from the national petroleum agency across ultra-deepwater fields. Regulatory pressure for remote diagnostic capabilities accelerates investment in surface-controlled downhole tools and real-time monitoring systems. Rio de Janeiro concentrates national oil company procurement and subsea technology integration activities.
United Kingdom
North Sea asset operators navigate mature field rejuvenation economics where riserless methods eliminate riser installation time and reduce vessel day-rate exposure. The country's offshore regulator enforces well integrity and barrier management standards that shape intervention frequency requirements. Aberdeen maintains its position as the primary hub for subsea engineering expertise and intervention service procurement.
Riserless Light Well Intervention Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service providers capable of bundling vessels, intervention tools, and remote monitoring into unified contracts. Three archetypes dominate: full-service oilfield conglomerates with subsea technology portfolios, specialized intervention vessel operators with dynamic positioning capabilities, and subsea system manufacturers with proprietary wellhead interfaces. Competitive moves concentrate on strategic partnerships to secure vessel availability and technology licensing to expand high-pressure tool compatibility.
Within the integrated service tier, Schlumberger leverages its subsea technology portfolio across multiple basins, while Baker Hughes anchors positioning through proprietary riserless intervention tool development. TechnipFMC exemplifies the subsea system manufacturing archetype, sustaining production scale in architectures that interface directly with light intervention systems. These three companies represent distinct competitive vectors: deployment logistics control, high-pressure tool specialization, and manufacturing scale integration.
| Leading Market Players |
|---|
| Schlumberger |
| TechnipFMC |
| Expro |
| NOV |
| Helix Energy Solutions |
| Halliburton |
| Oceaneering |
| Aker Solutions |
| Baker Hughes |
| Others |
Value Network & Pricing Analysis
Subsea lubricator manufacturing concentrates in Norway and the United Kingdom, anchoring margin capture with vessel operators and integrated service providers who bundle deployment logistics. This upstream concentration of pressure-control equipment production translates directly into pricing power for high-pressure wellhead-compatible systems, while fragmented tool provision downstream intensifies competition for wireline and coiled tubing services.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates proprietary high-pressure wellhead interfaces from generic lubricator rentals and unbundled tool provision. Price differentiation rests on certification grade for HPHT applications and vessel day-rate bundling scale. Cost compression in standard-tier wireline services is intensifying because independent Gulf of Mexico producers unbundle procurement to optimize exposure. Independent producers exhibit highest price sensitivity; integrated majors with long-term North Sea decommissioning timelines show lowest.
Supply Chain Analysis
Single-source vulnerability for dynamic positioning intervention vessels concentrates supply risk between Norway and the United States Gulf Coast, with limited alternative capacity in Brazil. Raw material dependencies span high-grade steel forgings for wellhead connectors, subsea electronics for remote monitoring, and specialized alloys for pressure-containing components. Distribution runs through integrated service contracts that bundle vessel charter, lubricator provision, and real-time diagnostics into unified procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Riserless light well intervention operates as a defensive-moat market where regulatory entrenchment creates substantial switching costs for operators locked into documented barrier verification workflows. Norway's Petroleum Safety Authority and the US Bureau of Safety and Environmental Enforcement mandate systematic compliance architectures that embed incumbent service providers into operator workflows.
For Market Incumbents: Pre-empt vessel scarcity bottlenecks by securing long-term dynamic positioning capacity in the North Sea and Gulf of Mexico through strategic charter agreements or fleet expansion. Proprietary wellhead interface development represents the priority lever against emerging coiled tubing specialists threatening high-pressure application share. Backward integration into subsea lubricator manufacturing captures margin from Norwegian and UK equipment fabricators facing capacity constraints. For New Entrants and Emerging Players: Brazil pre-salt ultra-deepwater fields represent the most penetrable entry point, where national petroleum agency enforcement of well integrity standards outpaces local remote diagnostic capability development. Coiled tubing live-well milling for scale removal applications offers second white-space targeting, as established wireline incumbents underinvest in pressure-rated continuous tubing systems. Partner with national oil company procurement offices in Rio de Janeiro to secure pilot deployment contracts that generate regulatory referenceability. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed intervention vessel operators concentrated in Aberdeen and Houston that require technology refresh capital for autonomous system integration. Five-to-ten year viability hinges on carbon reduction mandates compressing vessel-tethered deployment economics in favor of resident robotics. Monitor Brazil national petroleum agency pre-salt contracting velocity as the inflection indicator for remote operation technology valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Packaging | Bundling vessels, tools, and monitoring captures margin from fragmented procurement patterns among Gulf of Mexico independents. |
| Proprietary Wellhead Interface Development | High-pressure compatibility investments by Baker Hughes and TechnipFMC lock out interchangeability-dependent competitors. |
| Resident Robotics Pilot Programs | North Sea operators testing autonomous systems reduce carbon-intensive vessel movements and compress response times. |
| Brazil Pre-Salt Market Entry | Remote diagnostic capabilities align with national petroleum agency enforcement across ultra-deepwater developments. |
| Dynamic Positioning Fleet Expansion | Vessel scarcity in seasonal demand peaks creates booking bottlenecks that concentrated capacity alleviates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, vessel operator contract disclosures, and subsea equipment procurement databases to establish intervention frequency baselines. Interviews with North Sea asset integrity managers, Gulf of Mexico drilling superintendents, subsea system procurement leads, and offshore regulatory compliance officers inform operational reality. Secondary sources include US Bureau of Safety and Environmental Enforcement incident reports, Norway Petroleum Safety Authority audit summaries, and Brazil national petroleum agency pre-salt development permits. Bottom-up triangulation of vessel day-rate structures and top-down reconciliation of operator capital expenditure disclosures validate market sizing.
Forecast inputs span service type segmentation across wireline, coiled tubing, and hydraulic workover deployment; application tiering from production optimization through asset recovery; and technology architecture differentiation between subsea lubricator systems and remote operation platforms. Modeled projections incorporate regulatory mandate enforcement timelines, base decline rates from legacy deepwater wells, and carbon reduction pressures on vessel economics. CAGRs derive from intervention frequency elasticity against barrel recovery economics and documented barrier verification cycle compression.
Practitioners should monitor Brazil national petroleum agency enforcement velocity, North Sea decommissioning liability framework revisions, and vessel emission standard tightening for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Oman Directional Drilling Market