
 Tricone Bits Market | 2026-2036
Tricone Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Tricone Bits Market Insights
Multi-source procurement toward captive manufacturing is rebalancing supply relationships across the tricone bits value chain. Schlumberger leverages backward integration into bit manufacturing to secure margins on integrated drilling services. Baker Hughes sustains technology leadership through proprietary bearing seal designs that extend run life in abrasive formations. Halliburton anchors its position by controlling distribution channels to independent drilling contractors across North American shale plays.
Tricone bits are three-cone rotary drill bits engineered with milled steel teeth or tungsten carbide inserts, typically manufactured through precision forging, heat treatment, and hardfacing processes to achieve hardness ratings exceeding HRC 60 for cutting structures. These tools penetrate sedimentary and crystalline rock formations by combining crushing, scraping, and chipping actions under weight-on-bit loads ranging from 1,000 to 10,000 pounds per inch of bit diameter. Tungsten carbide tooth variants command the largest revenue share due to their superior wear resistance in interbedded formations, while steel tooth configurations retain cost advantages in soft-rock applications where penetration rate outweighs durability. Oil drilling applications generate the deepest margin pools as operators prioritize single-run reliability over initial bit cost in deepwater and extended-reach programs.
API Q2 and ISO 10424-1 standards govern dimensional tolerances, material grades, and performance testing protocols that determine market access for premium product tiers. The EPA's methane emissions regulations and OSHA drilling safety directives indirectly shape bit demand by accelerating drilling efficiency requirements that favor longer-lasting cutting structures. Stakeholders must monitor how API specification revisions and carbon-intensity disclosure mandates from institutional operators reshape procurement criteria and supplier qualification timelines.
Market Dynamics
Horizontal drilling intensity in North American shale basins is compressing replacement cycles and forcing manufacturers to prioritize single-run reliability over unit economics. API Q2 certification requirements are simultaneously raising material grade thresholds and extending supplier qualification timelines.
Growth Catalysts
- Deepwater exploration depth records:Offshore contractors in the Gulf of Mexico and Brazil's pre-salt formations are deploying premium tungsten carbide variants for extended-reach programs exceeding 30,000 feet measured depth.
- EPA methane regulations:Stricter emissions monitoring under the Inflation Reduction Act is accelerating drilling efficiency mandates that favor longer-lasting cutting structures over frequent bit trips.
- Permian Basin horizontal intensity:Texas and New Mexico operators sustain replacement demand through multi-stage lateral completions that consume three to five bits per wellbore.
Market Restraints
- Tungsten carbide supply concentration:Raw material sourcing depends on Chinese smelter capacity and Russian ferrotungsten exports, creating price volatility exposure for insert manufacturers.
- API Q2 compliance friction:Certification audits require 18-24 month qualification cycles that lock out mid-tier suppliers from premium tier procurement pools.
- Fixed cutter substitution:Polycrystalline diamond compact bits capture share in homogeneous sandstone formations where penetration rate trumps durability requirements.
Strategic Opportunities
- Geothermal energy drilling:Enhanced geothermal systems in Nevada and Utah require bits rated for crystalline basement rock temperatures exceeding 300 degrees Fahrenheit.
- Carbon capture well construction:Class VI injection well programs under EPA underground injection control rules demand corrosion-resistant bearing seals for decades-long service life.
- Digital fleet integration:Real-time vibration monitoring systems paired with predictive wear algorithms enable outcome-based bit rental models.
Industry Challenges
- Heat treatment specialist scarcity:Precision forging and hardfacing operations require metallurgists certified to NADCAP standards, with workforce gaps concentrated in Oklahoma and Texas manufacturing hubs.
- ISO 10424-1 testing backlog:Third-party validation laboratory capacity constraints delay new product introductions by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tricone Bits Market |
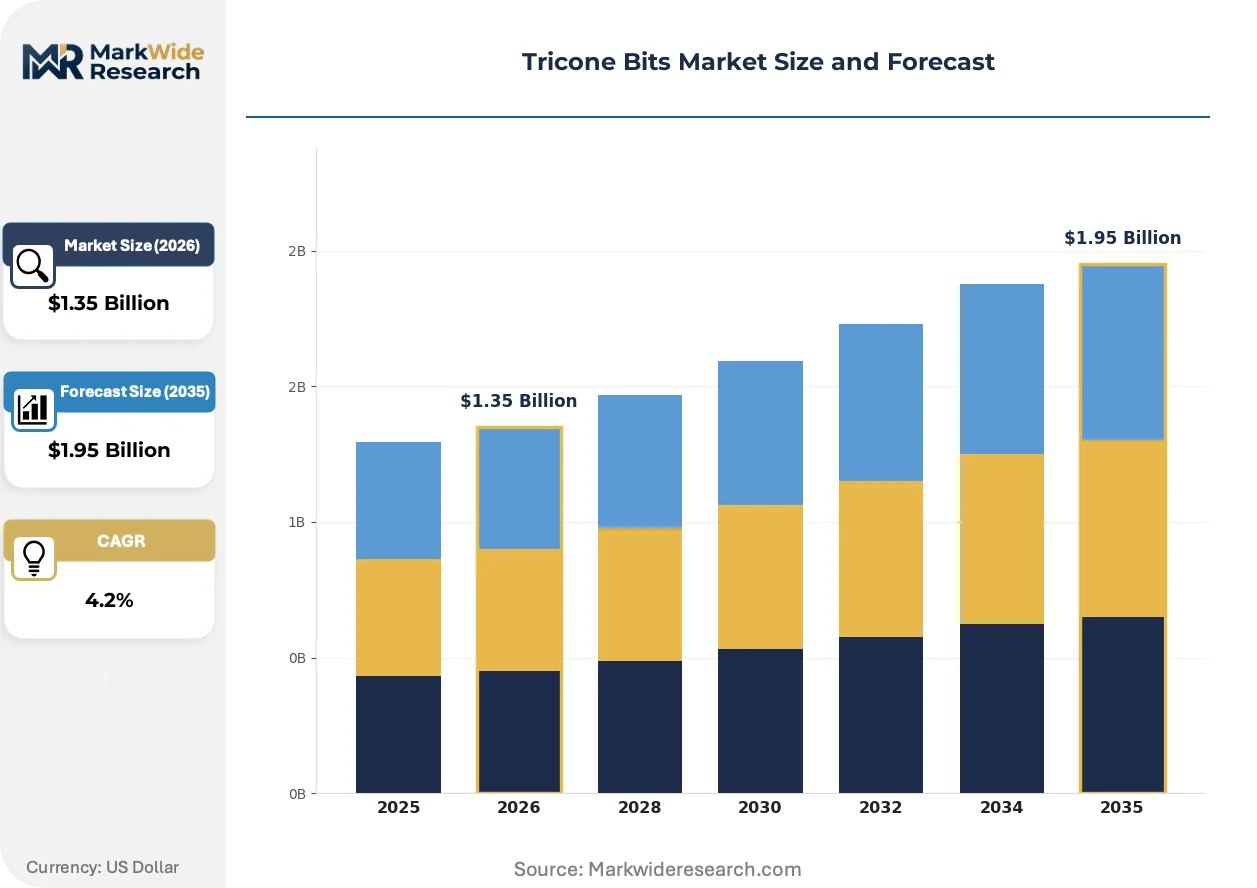
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $1.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Tooth, Tungsten Carbide Tooth, Steel Insert, Natural Diamond, Synthetic Diamond Application: Oil Drilling, Gas Extraction, Mining Projects, Water Well Drilling, Geothermal Drilling End User: Drilling Contractors, Exploration Companies, Mining Corporations, Energy Producers, Municipal Water Authorities Drilling Formation: Soft Rock, Medium Rock, Hard Rock, Mixed Formation, Conglomerate |
| Companies Covered | Schlumberger, Baker Hughes, Halliburton, Sandvik, NOV, Atlas Copco, Varel Energy Solutions, Volgaburmash, Uralburmash, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tricone Bits Market Trends and Innovations
Material science advances and downhole telemetry integration are redefining performance benchmarks across tricone bit categories. Manufacturers now compete on predictive durability rather than initial penetration rates.
Hybrid cutting structures combining milled steel gage protection with tungsten carbide inserts are expanding into interbedded formation applications previously dominated by pure insert designs. Permian Basin operators are adopting these configurations for transitional zones between shale and limestone stringers. The technology is expanding into mid-tier price segments as Chinese forging houses achieve API Q2 compliance.
EPA methane performance standards under the Inflation Reduction Act are mandating sealed bearing systems that eliminate lubricant venting during drilling operations. Manufacturers must redesign grease reservoir geometries to maintain pressure differentials across 10,000-foot vertical intervals. Offshore Gulf of Mexico contractors face the steepest compliance costs due to deepwater pressure cycling requirements.
Integrated bit-and-BHA rental packages are displacing discrete tool purchases among independent drilling contractors. Oklahoma-based service companies now bundle vibration-resistant bit designs with real-time downhole sensors under fixed daily rates. This model concentrates most rapidly in the Permian Basin where capital-constrained operators prioritize cash flow predictability over equipment ownership.
Tricone Bits Market Segmentation
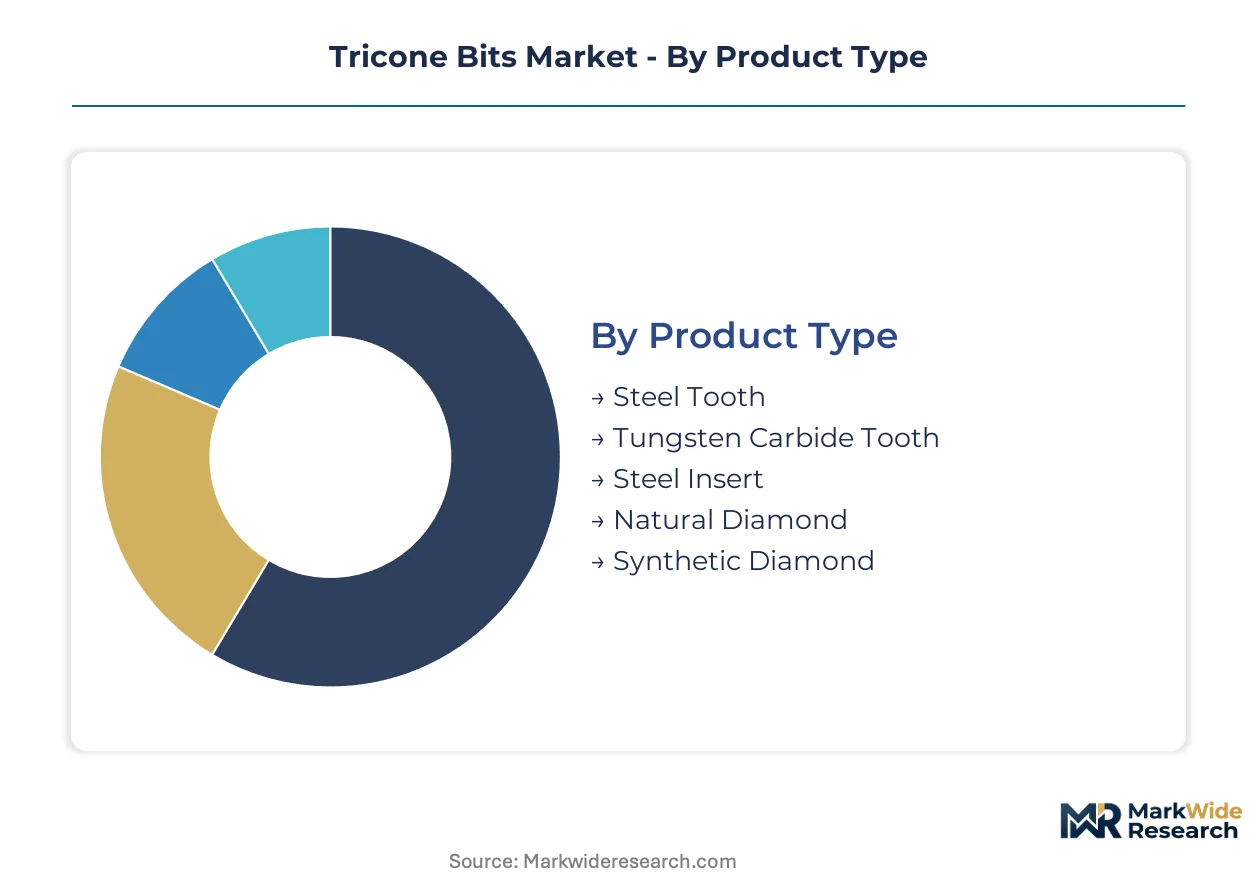
Tricone bit procurement patterns diverge sharply across product specifications, application intensity, and formation hardness. Each segmentation axis reveals distinct margin pools and supplier qualification thresholds that reshape competitive positioning.
Product Type:
Material composition and tooth geometry determine wear resistance, penetration rate, and API certification tier eligibility.
- Tungsten Carbide Tooth:Inserts manufactured from sintered tungsten carbide-cobalt matrix deliver hardness exceeding HRC 70 for interbedded shale and limestone stringers. Demand concentrates in the Permian Basin where horizontal laterals sustain three-to-five-bit replacement cycles per wellbore.
- Steel Tooth:Milled alloy steel cutting structures achieve lower unit costs through precision forging without carbide brazing. Soft-rock applications in the Appalachian Basin prioritize penetration rate over durability where formation abrasiveness remains minimal.
- Steel Insert:Hybrid configurations combine steel body construction with selective carbide placement at high-wear gage locations. Oklahoma manufacturers target mid-tier contractors seeking cost optimization in transitional drilling zones.
- Natural Diamond:Surface-set industrial diamond crystals bonded to matrix bodies address ultra-hard crystalline formations exceeding 25,000 psi compressive strength. Geothermal contractors in Nevada deploy these for basement rock penetration.
- Synthetic Diamond:Polycrystalline diamond compact variants manufactured through high-pressure high-temperature synthesis compete for share in homogeneous sandstone intervals where fixed cutter reliability improves.
Tungsten Carbide Tooth leads on scale; Synthetic Diamond leads on momentum.
Application:
End-use intensity and regulatory exposure create divergent procurement criteria across verticals.
- Oil Drilling:Deepwater Gulf of Mexico programs and extended-reach Permian laterals command premium pricing for sealed bearing systems. EPA methane performance standards under the Inflation Reduction Act mandate lubricant containment across 10,000-foot pressure differentials.
- Gas Extraction:Marcellus and Utica shale operators prioritize penetration rate in dry gas windows where formation drillability permits steel-tooth economics. Appalachian drilling contractors compress replacement cycles through high-rotation-rate parameters.
- Mining Projects:Open-pit copper and iron ore operations in Arizona and Minnesota consume large-diameter bits for blast hole preparation. Volume procurement contracts favor established API Q2-certified suppliers.
- Water Well Drilling:Municipal authorities in Texas and California specify corrosion-resistant bearing seals for decades-long service life in aquifer access programs. Budget constraints limit specification tiers relative to hydrocarbon applications.
- Geothermal Drilling:Enhanced geothermal systems in Utah require bits rated for temperatures exceeding 300 degrees Fahrenheit in crystalline basement rock. DOE funding programs accelerate technology qualification timelines.
Oil Drilling dominates value capture; Geothermal Drilling shows steepest expansion trajectory.
End User:
Capital structure and technical capability determine procurement modality and supplier relationship intensity.
- Drilling Contractors:Independent operators across North American shale plays favor integrated bit-and-BHA rental packages over discrete purchases. Oklahoma service companies bundle vibration-resistant designs with real-time downhole sensors.
- Exploration Companies:Venture-backed operators in the Denver-Julesburg Basin prioritize single-run reliability to minimize non-productive time during appraisal drilling. Premium tungsten carbide variants dominate specification sheets.
- Mining Corporations:Tier-one copper producers in Arizona negotiate multi-year supply agreements with volume pricing escalators tied to tungsten carbide feedstock indices.
- Energy Producers:Integrated majors operating Gulf of Mexico assets specify API Q2-certified sealed bearing systems with predictive wear monitoring integration.
- Municipal Water Authorities:California Department of Water Resources procurement standards emphasize corrosion resistance and documented service life over initial acquisition cost.
Drilling Contractors anchor volume demand; Exploration Companies drive specification escalation.
Drilling Formation:
Rock mechanics properties dictate cutting structure selection and expected bit life.
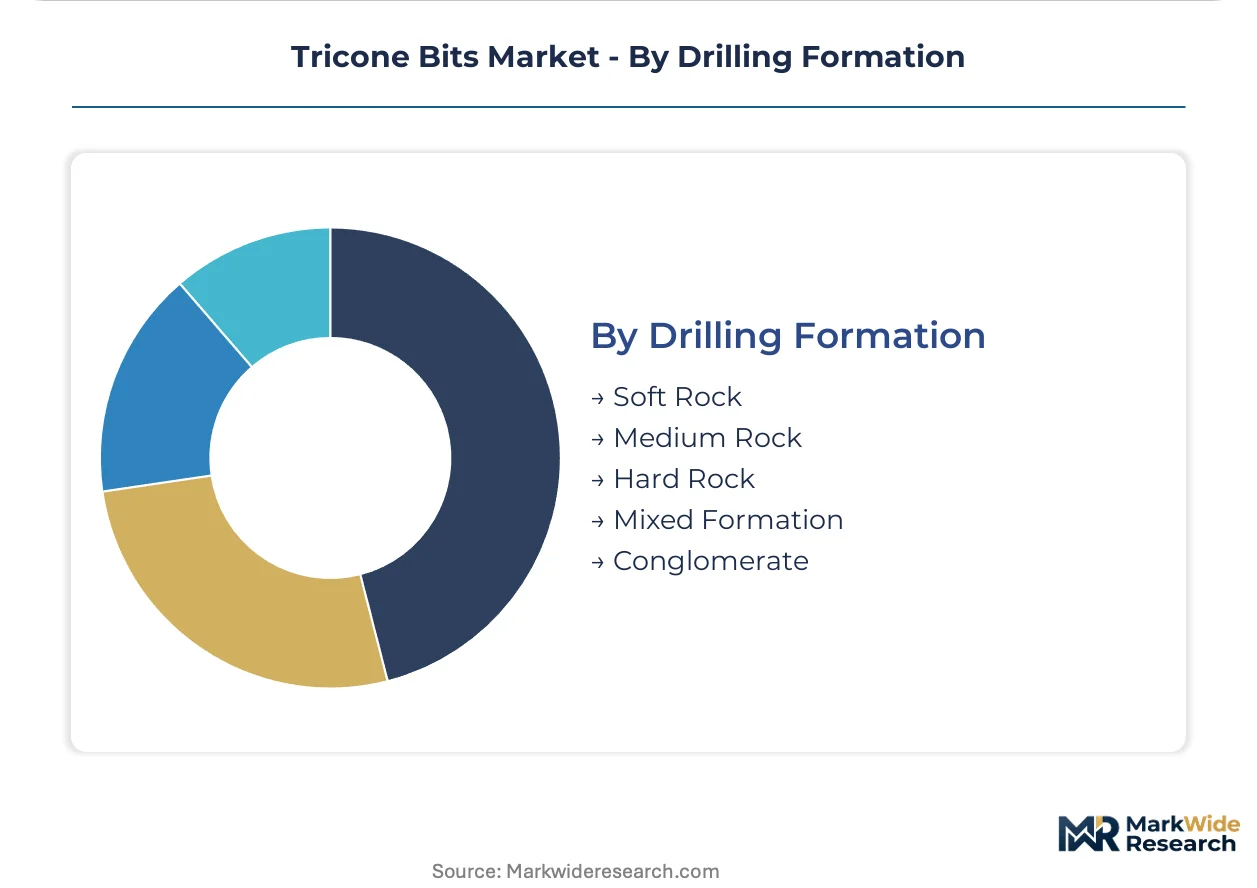
- Mixed Formation:Interbedded shale, sandstone, and limestone stringers in the Permian Basin demand hybrid cutting structures with selective carbide reinforcement. Abrasive wear patterns accelerate at formation boundaries.
- Hard Rock:Granite and basalt basement drilling in geothermal programs requires natural diamond or premium tungsten carbide inserts with enhanced gage protection. Heat generation at cutter interface limits rotation parameters.
- Soft Rock:Unconsolidated sands and clays in the Gulf Coast permit steel-tooth economics where penetration rate optimization outweighs durability requirements.
- Medium Rock:Calcareous shales in the Williston Basin represent the specification midpoint where insert quality and bearing seal reliability determine competitive differentiation.
- Conglomerate:Cemented gravel formations in alluvial basins impose impact loading that favors robust leg structure design over cutting structure refinement alone.
Mixed Formation commands premium pricing; Hard Rock applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin spanning Texas and New Mexico anchors global tricone bit procurement intensity, with horizontal drilling programs sustaining replacement cycles that outpace other production zones. API specification Q2 certification requirements and EPA methane regulations under the Inflation Reduction Act are reshaping procurement criteria across North American shale plays. Deepwater exploration in the Gulf of Mexico and Brazil's pre-salt formations drives premium-tier demand for sealed bearing systems rated to 30,000 feet measured depth.
United States
Horizontal drilling intensity in the Permian Basin compresses replacement cycles to three-to-five bits per wellbore, with Texas and New Mexico operators prioritizing single-run reliability. EPA methane performance standards mandate sealed bearing systems that eliminate lubricant venting across 10,000-foot pressure differentials. Oklahoma manufacturing hubs concentrate precision forging and hardfacing operations, though NADCAP-certified metallurgist scarcity constrains capacity expansion.
Brazil
Pre-salt formation drilling in the Santos Basin demands premium tungsten carbide variants for extended-reach programs exceeding 30,000 feet measured depth. The national petroleum regulator enforces strict well integrity standards that favor API Q2-certified suppliers with documented bearing seal performance. Rio de Janeiro serves as the procurement coordination center for offshore contractors operating Campos and Santos basin assets.
China
Tungsten carbide feedstock concentration in Chinese smelter capacity creates supply chain leverage for domestic bit manufacturers seeking cost advantages in steel-tooth segments. The Ministry of Ecology and Environment enforces dual carbon goals that indirectly favor longer-lasting cutting structures over frequent replacement cycles. Zhengzhou and Xi'an industrial clusters house forging operations achieving incremental API Q2 compliance for mid-tier export markets.
Russia
Ferrotungsten export capacity from Russian smelters supplies insert manufacturers across Eastern European and Central Asian drilling markets. The country's national technical regulation agency maintains GOST certification requirements that run parallel to ISO 10424-1 standards for dimensional tolerances. Ural region manufacturing centers produce bits targeting Siberian oilfield development and export markets in Kazakhstan and Uzbekistan.
Canada
Montney and Duvernay shale operators in Alberta and British Columbia deploy hybrid cutting structures for interbedded formation drilling where limestone stringers interrupt shale sequences. Environment and Climate Change Canada methane regulations align with US EPA standards, creating cross-border procurement harmonization for sealed bearing systems. Calgary-based drilling contractors favor integrated bit-and-BHA rental packages to preserve capital flexibility in volatile commodity price environments.
Tricone Bits Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue geothermal and carbon capture adjacent spaces where certification barriers remain lower. The vendor base stratifies across three tiers: integrated oilfield service conglomerates with captive manufacturing, specialized bit manufacturers with proprietary bearing seal designs, and regional forging houses competing on cost in steel-tooth segments. Dominant competitive moves include backward integration into tungsten carbide supply chains and strategic partnerships with real-time downhole telemetry providers.
Within the integrated service tier, Schlumberger, Baker Hughes, and Halliburton exemplify divergent strategic postures. Schlumberger anchors premium positioning through backward integration into bit manufacturing that secures margins on integrated drilling services. Baker Hughes occupies technology leadership archetype through proprietary bearing seal designs referenced in industry specifications. Halliburton sits within distribution control archetype by channeling products to independent drilling contractors across North American shale plays. Among specialized manufacturers, Sandvik and NOV represent European and North American engineering-focused alternatives, while Varel Energy Solutions, Volgaburmash, and Uralburmash populate regional supply tiers serving price-sensitive procurement pools.
| Leading Market Players |
|---|
| Schlumberger |
| Baker Hughes |
| Halliburton |
| Sandvik |
| NOV |
| Atlas Copco |
| Varel Energy Solutions |
| Volgaburmash |
| Uralburmash |
| Others |
Pricing and Supply Chain Analysis
Tungsten carbide feedstock costs originating in Chinese smelter capacity cascade through three distinct pricing tiers before reaching Gulf of Mexico offshore contractors, with API Q2 certification requirements acting as the primary gate between mid-tier and premium procurement pools.
Pricing Analysis
Input-cost pass-through from ferrotungsten price volatility anchors pricing stratification across premium, standard, and economy tiers. API Q2 certification grade and bearing seal technology specifications drive price differentiation, with sealed bearing systems commanding multiples over open-bearing alternatives. Pricing pressure stems from fixed cutter bit substitution in homogeneous sandstone formations, compressing margins in steel-tooth segments. Independent drilling contractors in the Permian Basin exhibit highest price sensitivity, while integrated majors prioritize single-run reliability over unit economics.
Supply Chain Analysis
Freight costs from Zhengzhou and Xi'an industrial clusters to Oklahoma manufacturing hubs amplify working capital requirements for mid-tier producers seeking API compliance. Supply concentrates in China for tungsten carbide feedstock, the United States for precision forging and hardfacing operations, and Russia for ferrotungsten exports. Raw material dependencies center on tungsten ore concentrates, cobalt binder alloys, and high-grade alloy steel forgings. Single-source vulnerability in Chinese smelter capacity creates structural exposure to export restriction risk. Distribution runs through integrated service company channels, independent rental fleets, and direct procurement by exploration companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tricone bits market functions as a stable compounder where horizontal drilling intensity in North American shale basins sustains predictable replacement demand regardless of commodity price cycles.
For Market Incumbents: Deploy backward integration into tungsten carbide supply chains to secure margin pools against Chinese feedstock volatility. Deepen API Q2 certification investment to lock out mid-tier competitors from premium offshore procurement pools. Channel control through integrated bit-and-BHA rental packages defends position against fixed cutter substitution in sandstone applications.
For New Entrants and Emerging Players: Launch via geothermal drilling contractors in Nevada and Utah where temperature-rated bearing seal requirements favor specialized engineering over scale economies. Target carbon capture well construction under EPA Class VI injection rules as the most penetrable adjacent vertical. Pursue digital fleet integration partnerships with predictive wear algorithm providers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where NADCAP-certified metallurgist scarcity constrains capacity expansion in Oklahoma and Texas manufacturing hubs. The market supports long-term viability framing around replacement cycle predictability in shale basins and regulatory-mandated drilling efficiency improvements. Acquisition target archetypes include specialized bearing seal designers and regional forging houses achieving incremental API Q2 compliance. Watch EPA methane enforcement intensity as the signal indicating premium tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Supply | Captive feedstock sourcing insulates margins against Chinese export volatility and Russian supply disruption. |
| API Q2 Certification Investment | Extended qualification cycles create defensive moats around premium tier procurement pools in offshore markets. |
| Digital Fleet Integration Partnership | Predictive wear algorithms enable outcome-based rental models preferred by capital-constrained Permian operators. |
| Geothermal Application Development | DOE funding programs accelerate technology qualification for 300°F crystalline basement drilling requirements. |
| Sealed Bearing System Redesign | EPA methane performance standards mandate lubricant containment across 10,000-foot pressure differentials. |
Research Methodology
Multiple input streams — drilling contractor procurement managers, precision forging operations directors, API certification auditors, and tungsten carbide supply specialists — were reconciled against secondary validation from EIA drilling activity data, SEC filings from integrated service companies, customs records for ferrotungsten trade flows, and API specification revision documentation. Bottom-up triangulation across product type, application intensity, and formation hardness segmentation dimensions was cross-checked against top-down market sizing from replacement cycle modeling in major shale basins.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeling spanning material composition grade, end-use regulatory exposure, drilling formation hardness, and geographic procurement cluster. CAGRs were derived from replacement cycle frequency analysis and horizontal lateral length expansion trends. Forecast inputs incorporated EPA methane regulation enforcement trajectories and pre-salt formation drilling depth records from Brazil's Santos Basin.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tungsten carbide supply disruption or accelerated fixed cutter substitution scenarios. Forecasts reflect documented assumptions regarding horizontal drilling intensity maintenance and API specification stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
Natural Gas Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Drilling Services Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Canada LNG Market