
 Pipeline Pigging Services Market | 2026-2036
Pipeline Pigging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Pigging Services Market Analysis
Midstream pipeline operators is rotating procurement priority from routine cleaning contracts toward integrity verification programs that combine inline inspection with predictive analytics. T.D. Williamson, Inc. anchors its position through proprietary magnetic flux leakage tool technology deployed across North American transmission corridors. Baker Hughes Company leverages digital twin integration to differentiate its smart pigging portfolio beyond conventional metal-loss detection. ROSEN Group specializes in ultrasonic crack detection systems that sustain premium positioning in sour-gas environments.
Pipeline pigging services encompass the mechanical propulsion of inspection, cleaning, and sealing devices through pressurized conduits using differential pressure, with smart pigs incorporating electromagnetic acoustic transducers capable of detecting wall-thickness variations below one millimeter. These services prevent catastrophic failures, optimize flow efficiency, and extend asset life across hydrocarbon and water infrastructure networks. Smart pigging commands the dominant value share due to regulatory mandates for crack and corrosion mapping, while wet pigging retains volume leadership in crude oil systems where paraffin and scale removal cycles recur quarterly. Gas distribution applications generate the fastest expansion as hydrogen blending trials and biomethane injection accelerate compatibility testing requirements.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces integrity management rules under 49 CFR Part 195, compelling operators to baseline and reassess high-consequence area pipelines at defined intervals. The American Petroleum Institute's API 1163 standard governs inline inspection system qualifications, creating barrier-to-entry effects for service providers lacking third-party tool-verification credentials. Stakeholders must monitor evolving methane-emission detection mandates and hydrogen infrastructure compatibility standards that will reshape pigging tool specifications and operator certification requirements.
Market Dynamics
Pipeline integrity mandates under 49 CFR Part 195 are compressing reassessment cycles for high-consequence area infrastructure, forcing midstream operators to integrate predictive analytics with inline inspection workflows rather than treating pigging as discrete maintenance events.
Growth Catalysts
- Regulatory Baseline Requirements:PHMSA's integrity management rules compel operators in Texas and Alberta to deploy smart pigs for crack detection at defined intervals, creating recurring revenue pools for inspection service providers.
- Hydrogen Infrastructure Trials:Biomethane injection and hydrogen blending across European distribution networks generate compatibility testing demand that requires specialized pigging tool specifications.
- Electromagnetic Acoustic Transducers:Wall-thickness detection below one millimeter enables early-stage corrosion mapping that prevents catastrophic failure events in sour-gas transmission corridors.
Market Restraints
- Specialized Tool Fabrication Concentration:Magnetic flux leakage and ultrasonic crack detection systems rely on precision sensor manufacturing concentrated in Germany and Japan, exposing procurement timelines to single-source vulnerabilities.
- API 1163 Certification Barriers:Third-party tool-verification credentials required under American Petroleum Institute standards filter out regional service providers lacking capital for qualification testing.
- Quarterly Wet Pigging Substitution:Automated chemical injection systems for paraffin and scale removal in crude oil pipelines reduce mechanical cleaning frequency in select basins.
Strategic Opportunities
- Digital Twin Convergence:Integration of inline inspection data with asset simulation platforms enables predictive maintenance contracts that extend service provider relationships beyond single-run engagements.
- Urban Gas Distribution Networks:Aging cast-iron replacement programs in Northeast US metropolitan areas create demand for pre-commissioning pigging and cleanliness verification.
- Methane Detection Mandates:Emerging EPA leak detection and repair requirements for transmission infrastructure expand pigging scope to include emission quantification during standard inspection runs.
Industry Challenges
- Electromagnetic Sensor Calibration Expertise:Shortage of technicians qualified to interpret magnetic flux leakage and ultrasonic data streams creates inspection backlogs during peak demand windows.
- Legacy Pipeline Geometry Constraints:Tight-radius bends and variable wall thickness in pre-1980 transmission corridors limit smart pig tool compatibility, requiring custom launcher modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Pigging Services Market |
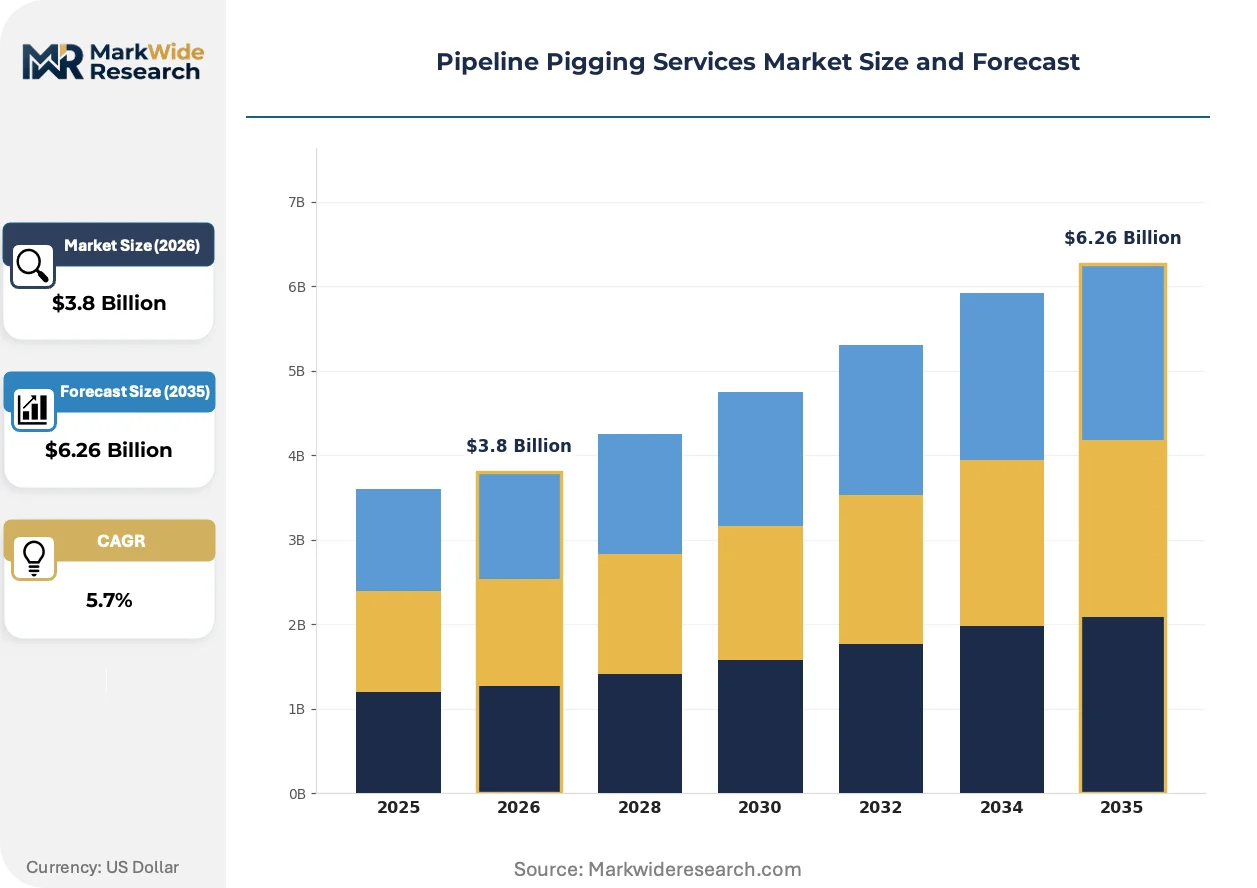
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dry Pigging, Wet Pigging, Smart Pigging, Liquid Pigging Application: Oil Transportation, Gas Distribution, Water Supply, Chemical Processing End User: Utilities, Oil & Gas Companies, Chemical Manufacturers, Marine Operators Installation: Onshore, Offshore, Subsea, Inland |
| Companies Covered | Schlumberger Limited, Quest Integrity Group, Inc., ROSEN Group, MISTRAS Group, NDT Global Services, T.D. Williamson, Inc., Halliburton Company, Applus+, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Pigging Services Market Emerging Trajectories
Sensor fusion architectures and real-time data transmission are collapsing the latency between inspection execution and integrity decision-making, compressing the traditional weeks-long analysis cycle into hours.
Tri-axial magnetic flux leakage sensors combined with eddy current arrays are decomposing the historical trade-off between metal-loss detection and crack identification, enabling single-run assessments that previously required sequential tool deployments. Permian Basin operators are adopting these hybrid configurations for baseline assessments of new gathering lines. The convergence is compressing per-mile inspection costs while expanding the addressable pipeline population that qualifies for comprehensive assessment.
PHMSA's pending updates to 49 CFR Part 192 for gas distribution integrity management are accelerating inline inspection adoption in medium-pressure networks previously exempt from formal assessment programs. The regulatory expansion is forcing municipal utilities to contract specialized pigging services for the first time. Northeast US distribution operators are responding by consolidating procurement across multi-state footprints to secure volume pricing.
Service bundling is restructuring buyer-vendor relationships as midstream operators negotiate multi-year integrity management agreements that subsume discrete pigging runs within comprehensive asset performance contracts. The unbundling of inspection execution from data interpretation is creating separate competitive arenas for field operations and analytics platforms. Texas and Alberta transmission corridors exhibit the most advanced contracting structures, with operators separating tool deployment from diagnostic reporting through distinct vendor relationships.
Pipeline Pigging Services Market Segmentation
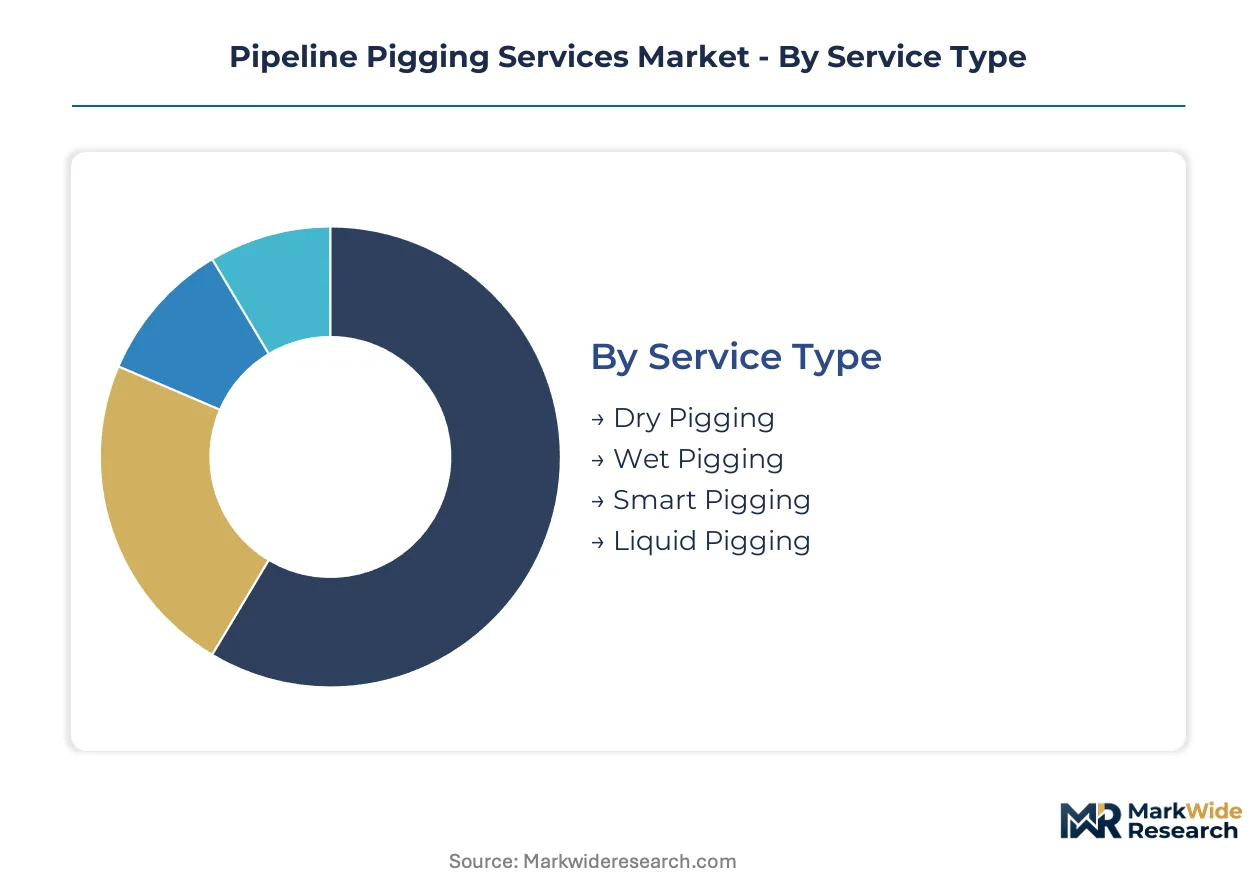
Pipeline pigging services fragment across service modalities, infrastructure types, and operator profiles that each carry distinct procurement rhythms and technical specifications. Understanding these partitions reveals where inspection technology investments concentrate versus where routine maintenance contracts dominate revenue stability.
Service Type:
Dry pigging and wet pigging deployments cluster around domestic crude gathering networks in Texas and North Dakota, while smart pigging contracts increasingly cross into export-oriented transmission corridors serving Canadian oil sands and US Gulf Coast LNG terminals.
- Smart Pigging:Electromagnetic acoustic transducers and magnetic flux leakage sensors detect wall-thickness variations below one millimeter, enabling crack mapping in sour-gas transmission lines across Alberta and Permian Basin corridors where PHMSA mandates compressed reassessment cycles.
- Wet Pigging:Chemical-laden pigs remove paraffin and scale deposits from crude oil pipelines, with quarterly deployment cycles concentrated in Bakken shale gathering systems where automated injection alternatives have not yet displaced mechanical cleaning.
- Dry Pigging:Foam and brush configurations sweep debris from natural gas distribution lines, dominating pre-commissioning cleanliness verification in Northeast US cast-iron replacement programs.
- Liquid Pigging:Gel and solvent-based systems flush hydrocarbon residues from product pipelines, serving refined product terminals along Colonial Pipeline corridors.
Smart pigging commands the established base. The steepest expansion runs through wet pigging as chemical formulation advances extend cleaning efficacy intervals.
Application:
Cost tiering separates inspection-intensive gas distribution from volume-driven crude transport, with hydrogen blending trials creating a premium tier for compatibility verification services.
- Oil Transportation:Paraffin management and corrosion monitoring dominate procurement across Permian and Bakken gathering networks where high wax-content crude demands frequent mechanical intervention.
- Gas Distribution:Inline inspection adoption accelerates in medium-pressure municipal networks as PHMSA expands 49 CFR Part 192 integrity requirements, forcing first-time contracting among Northeast US utilities.
- Water Supply:Sediment removal and biofilm control sustain recurring revenue in municipal aqueduct systems, particularly in Southwest US states confronting scaling from hard-water mineral content.
- Chemical Processing:Product purity verification and cross-contamination prevention drive specialized pigging protocols at Gulf Coast petrochemical complexes.
Oil transportation absorbs the highest absolute spending. Gas distribution is climbing fastest as regulatory baselines extend to previously exempt infrastructure.
End User:
Volume concentration sits with integrated oil and gas majors operating across multiple basins, while utilities and chemical manufacturers represent fragmented, price-sensitive procurement segments.
- Oil & Gas Companies:Midstream operators in Texas and Alberta negotiate multi-year integrity management agreements that bundle smart pigging with predictive analytics, collapsing discrete run contracts into comprehensive asset performance structures.
- Utilities:Municipal gas distribution operators in Pennsylvania, New York, and Massachusetts consolidate procurement across multi-state footprints to secure volume pricing for first-time inline inspection programs.
- Chemical Manufacturers:Gulf Coast petrochemical complexes demand specialized cleanliness verification for product-grade pipelines, with procurement fragmented across facility-specific engineering teams.
- Marine Operators:Offshore loading lines and subsea export pipelines require subsea launcher compatibility and ROV-assisted pig recovery, limiting qualified service provider pools.
Oil and gas companies anchor contract value. Utilities are expanding fastest as regulatory mandates penetrate municipal infrastructure.
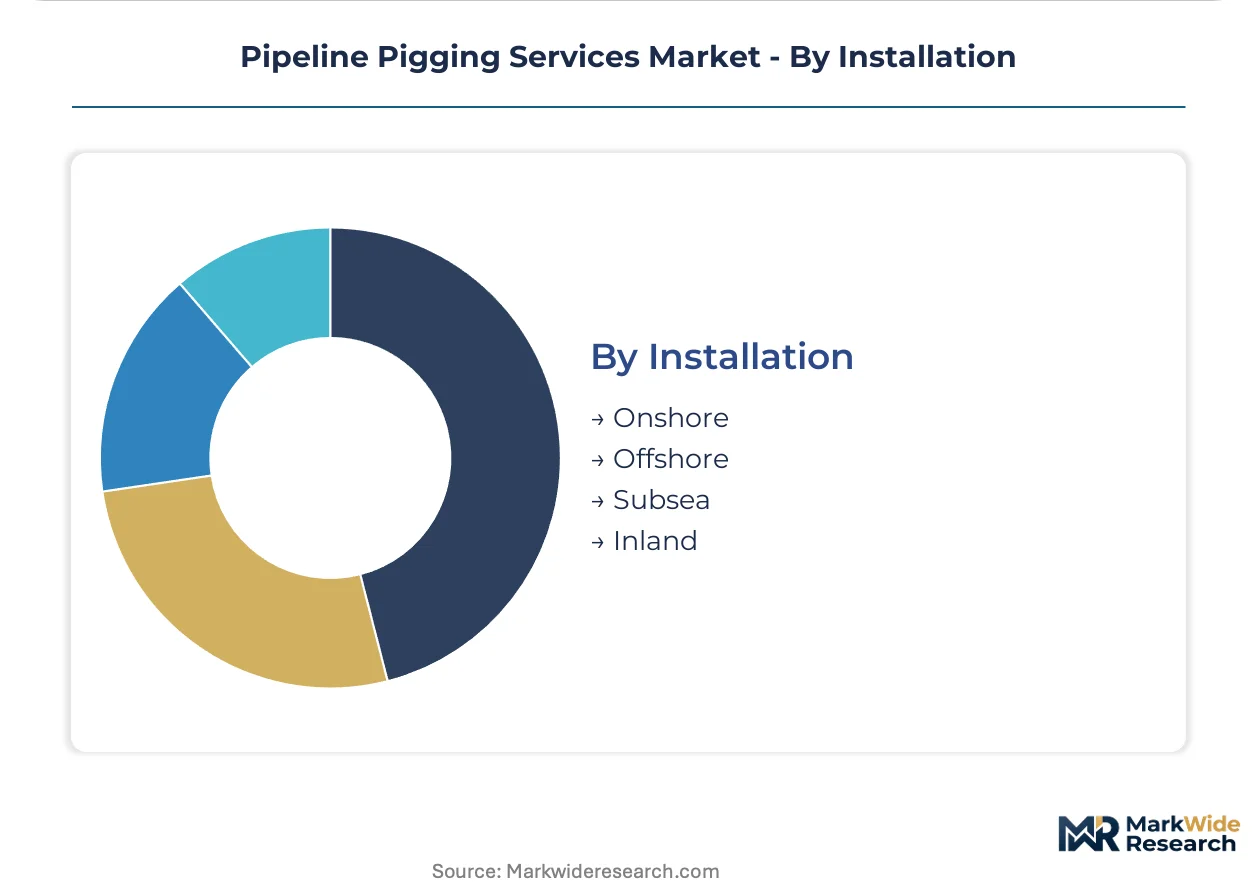
Installation:
Onshore deployments dominate service volume while offshore and subsea segments command premium pricing for specialized launcher modifications and marine logistics.
- Onshore:Standard launcher and receiver configurations support the bulk of inspection activity across North American transmission corridors, with tool compatibility limitations emerging in pre-1980 pipelines with tight-radius bends.
- Offshore:Platform-based pigging operations require weather-window scheduling and helicopter logistics, concentrating demand in Gulf of Mexico production facilities and North Sea export systems.
- Subsea:Tethered and autonomous pig systems address tieback pipelines and flowlines where launcher access requires vessel intervention, with tool retrieval complexity filtering service provider participation.
- Inland:River crossing and marshland pipelines in Louisiana and coastal Texas demand amphibious launcher access and seasonal water-level coordination.
Onshore work underpins revenue stability. Subsea installations are gaining share fastest as deepwater production tiebacks multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Keystone Pipeline System and its extensions through the US Midwest anchor North American crude transport infrastructure, while the Trans-Alaska Pipeline Network underwrites Arctic corridor maintenance demand. These backbone systems concentrate smart pigging procurement across jurisdictions with diverging regulatory baselines.
United States
Permian Basin gathering lines and Colonial Pipeline refined product corridors generate concentrated inspection demand. PHMSA enforces 49 CFR Part 195 integrity management rules that mandate smart pigging cycles for high-consequence area infrastructure. Houston-Gulf Coast petrochemical clusters host the densest service provider concentration for subsea launcher modifications.
Canada
Alberta oil sands export pipelines and Trans Mountain expansion corridors sustain premium inspection contracting. The Canadian Energy Regulator imposes pipeline integrity requirements under the Onshore Pipeline Regulations that mirror PHMSA intervals. Calgary-Edmonton shale corridors concentrate magnetic flux leakage tool deployment for sour-gas transmission.
Germany
OPAL and NEL natural gas interconnectors linking Russian supply routes prior to 2022 now require hydrogen compatibility verification for repurposed hydrogen corridors. The Federal Network Agency enforces Gas Network Development Plan standards that mandate inline inspection for transmission pressure tiers. Ruhr industrial clusters drive demand for pre-commissioning cleanliness verification in converted steel pipelines.
Saudi Arabia
East-West Pipeline and Master Gas System transmission corridors anchor Gulf regional inspection volume. The Saudi Standards, Metrology and Quality Organization aligns pipeline safety protocols with API 1163 certification requirements. Jubail industrial city petrochemical complexes generate specialized pigging demand for product-grade pipeline cleanliness.
Australia
North West Shelf offshore export lines and Cooper Basin onshore gathering systems sustain subsea and inland inspection cycles. The National Offshore Petroleum Safety and Environmental Management Authority regulates pipeline integrity for Commonwealth waters infrastructure. Perth-Broome marine logistics corridors concentrate ROV-assisted pig recovery operations for deepwater tiebacks.
Pipeline Pigging Services Market Vendor Landscape
Concentration sits with integrated energy service conglomerates that bundle pigging execution with reservoir engineering and completions portfolios. Tiered competition separates full-integrity providers from specialized tool fabricators and regional field contractors. Strategic archetypes include technology licensors with proprietary sensor platforms, asset-light field service aggregators, and vertically integrated oilfield majors. Competitive positioning hardens around M&A absorption of niche ultrasonic specialists and strategic partnerships linking tool deployment with predictive analytics platforms.
Among North American inspection specialists, T.D. Williamson, Inc. and Quest Integrity Group, Inc. occupy positions within the premium-tier smart pigging segment, while Baker Hughes Company exemplifies the integrated conglomerate archetype that subsumes discrete pigging runs within comprehensive asset performance agreements. These entities represent divergent strategic postures: specialized technology depth versus bundled service breadth across the integrity management value chain.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Quest Integrity Group, Inc. |
| ROSEN Group |
| MISTRAS Group |
| NDT Global Services |
| T.D. Williamson, Inc. |
| Halliburton Company |
| Applus+ |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day sensor procurement lead times for magnetic flux leakage tools concentrate pricing power with German and Japanese precision manufacturers, compressing margins for field service providers while amplifying cost pass-through to midstream operators in Texas and Alberta.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API 1163-certified smart pigging suites from unverified regional contractors and basic cleaning-only deployments. Price differentiation rests on certification grade and after-sales diagnostic bundling, with premium tiers commanding substantial uplifts for predictive analytics integration. Cost compression in standard-tier wet pigging is intensifying because automated chemical injection systems displace mechanical cleaning frequency in Bakken shale corridors. Municipal utilities exhibit highest price sensitivity due to first-time inline inspection mandates, while integrated majors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Inventory buffers for electromagnetic acoustic transducers rarely exceed sixty days, exposing procurement timelines to fabrication bottlenecks in Germany, Japan, and select US precision manufacturing clusters. Raw material dependencies center on rare-earth magnetic alloys, specialized ultrasonic ceramics, and high-pressure sealing elastomers. Single-source vulnerability concentrates in sensor calibration equipment, where two German fabricators supply the majority of North American inspection fleets. Distribution runs through authorized service depots in Houston, Calgary, and Rotterdam, with field deployment logistics coordinated via operator-owned launcher networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PHMSA's pending expansion of 49 CFR Part 192 to medium-pressure gas distribution networks constitutes a regulatory inflection that will double the addressable pipeline population requiring formal assessment, transforming a concentrated midstream market into a fragmented municipal utility opportunity.
For Market Incumbents: Shield proprietary sensor platforms through accelerated API 1163 certification investments that raise qualification barriers for regional entrants. Deepen backward integration into electromagnetic transducer fabrication to reduce exposure to German and Japanese supply concentration, while consolidating multi-year integrity management contracts across Permian and Alberta corridors to lock out specialized analytics competitors.
For New Entrants and Emerging Players: Anchor in Northeast US metropolitan gas distribution markets where aging cast-iron replacement programs and first-time PHMSA compliance obligations outpace incumbent service capacity. Target municipal utilities consolidating procurement across Pennsylvania, New York, and Massachusetts multi-state footprints, with a go-to-market angle emphasizing rapid deployment capability for pre-commissioning cleanliness verification.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because integrity mandate expansion creates recurring revenue visibility independent of commodity price cycles. Acquisition focus should center on ultrasonic crack detection specialists with sour-gas credentials and digital twin integration capabilities. The signal to watch is EPA methane detection rule finalization, which would expand pigging scope to emission quantification and accelerate tooling refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| API 1163 Certification Investment | Third-party tool verification credentials filter regional competitors from high-consequence area contracts. |
| Digital Twin Platform Integration | Asset simulation convergence extends service relationships beyond discrete inspection runs. |
| Sensor Fusion Technology Licensing | Tri-axial magnetic flux leakage combined with eddy current arrays compresses per-mile assessment costs. |
| Multi-Year Integrity Management Agreements | Comprehensive asset performance contracts collapse procurement fragmentation across Texas and Alberta operators. |
| Subsea Launcher Modification Capability | Deepwater tieback multiplication in Gulf of Mexico and North Sea creates premium pricing tier. |
Methodological Framework
Operator-level perspectives from midstream integrity managers, municipal utility engineering directors, PHMSA compliance officers, and smart pigging tool fabricators anchored the qualitative base, cross-validated against Pipeline and Hazardous Materials Safety Administration incident databases, American Petroleum Institute certification registries, Canadian Energy Regulator filings, and North American transmission corridor maintenance disclosure records. Bottom-up segmentation modeling triangulated with top-down macro demand indicators.
Sensitivity analysis across service type, application, end-user category, and installation environment informed volume and value outputs over the projection horizon. CAGRs derived from regression analysis of historical inspection cycle compression rates, regulatory mandate expansion timelines, and hydrogen infrastructure trial adoption curves. Industry-specific forecast inputs incorporated PHMSA reassessment interval modifications and European hydrogen blending compatibility testing requirements.
Decision-makers should treat outputs as directional under sustained regulatory enforcement intensity and stable midstream capital allocation assumptions; material deviation in mandate timing or operator budget prioritization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
India Oil and Gas Market
Oil & Gas
Japan AI in Oil and Gas Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Shale Shakers Market