
 Crude Oil Carriers Market | 2026-2036
Crude Oil Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Oil Carriers Market Analysis
A shift from single-source chartering toward multi-source contracting is rebalancing fleet deployment strategies across the crude tanker sector. Frontline Ltd leverages its scale advantage in the VLCC segment to secure long-term fixtures with national oil companies. Mitsui O.S.K. Lines, Ltd. anchors its competitive stance through backward integration into shipbuilding and technical management. Euronav NV differentiates via its younger fleet profile and fuel-efficient vessel designs.
Crude oil carriers are purpose-built maritime vessels engineered to transport unrefined petroleum in bulk, with VLCCs exceeding 300,000 deadweight tons and double-hull construction mandated under MARPOL Annex I for spill prevention. The vessel type segmentation shows VLCCs commanding the dominant share of tonne-mile demand on Middle East-to-Asia routes, while Aframax units capture margin pools in regional short-haul trades where port constraints limit larger vessel access. Suezmax carriers occupy a transitional position, competing for Atlantic basin cargoes that VLCCs cannot economically serve.
The International Maritime Organization enforces EEXI and CII carbon intensity metrics that compel fleet operators to retrofit engines or retire inefficient tonnage. The EU Emissions Trading System extends carbon pricing to maritime transport, reshaping cost structures on Europe-bound routes. Stakeholders must monitor regulatory divergence between IMO frameworks and regional carbon schemes when positioning newbuild orders and retrofit investments.
Market Dynamics
The International Maritime Organization's EEXI and CII carbon intensity metrics are forcing fleet operators into immediate retrofit decisions or accelerated scrapping of inefficient tonnage, compressing effective supply capacity while reshaping newbuild specifications toward dual-fuel propulsion and wind-assist technologies.
Growth Catalysts
- Asia-Pacific refinery expansion:China, India, and South Korea are commissioning new cracking capacity that deepens import dependency and extends voyage distances for Middle East crude, amplifying tonne-mile demand for VLCCs on long-haul routes.
- EU Emissions Trading System extension:Carbon pricing now applies to maritime transport serving Europe-bound cargoes, creating competitive differentiation for vessels with verified emissions profiles and documented carbon intensity scores.
- Dual-fuel engine retrofits:LNG-ready propulsion systems are penetrating the orderbook as shipowners hedge against future fuel availability and regulatory stringency at major bunkering hubs.
Market Restraints
- Steel price volatility:Newbuild construction costs fluctuate with plate steel input pricing, deterring speculative ordering and compressing shipyard margins across South Korean and Japanese builders.
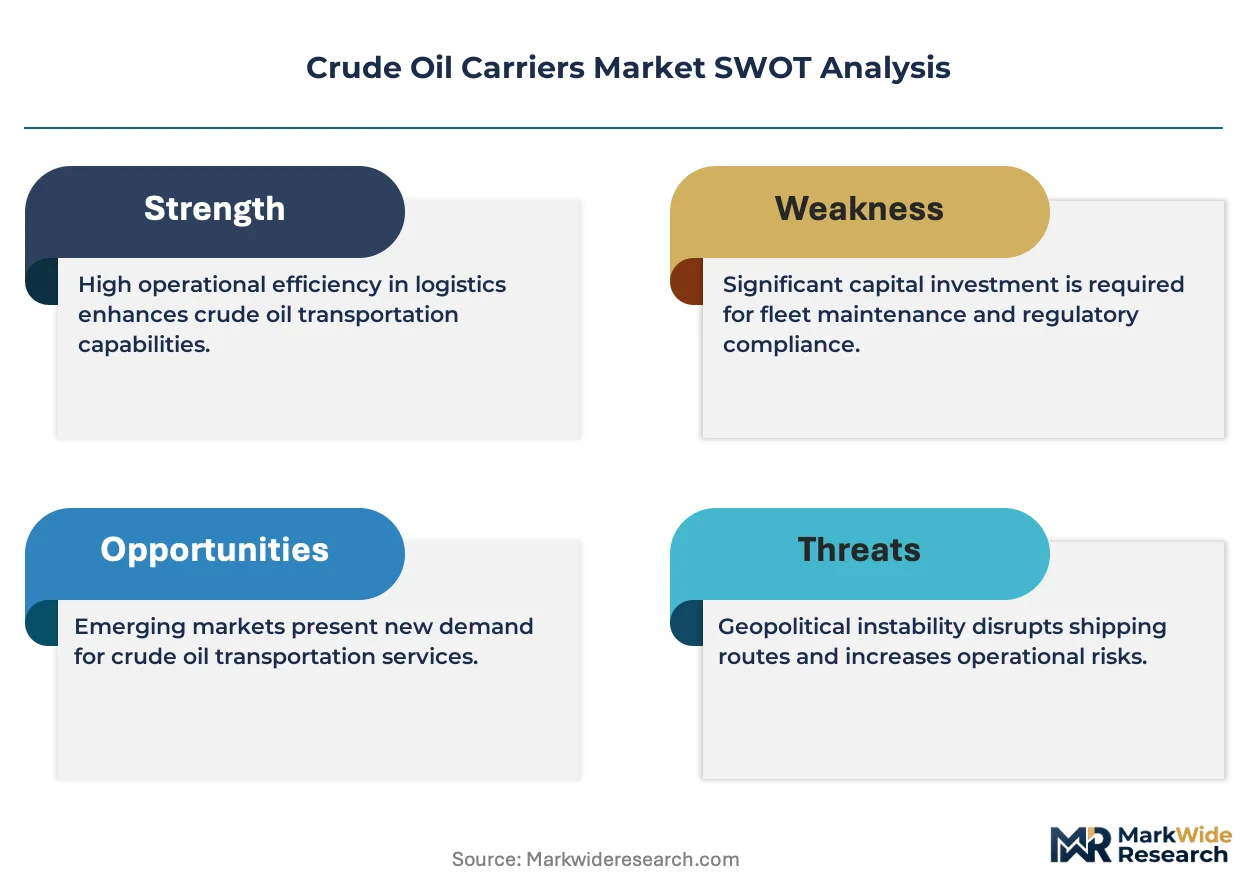
- Concentrated ownership structures:A small cohort of Greek and Norwegian shipowners controls significant VLCC tonnage, creating oligopolistic fixture pricing and limiting charterer bargaining power in tight markets.
- Substitution by pipeline infrastructure:Russian crude redirection via ESPO pipeline to China and potential Caspian corridor expansions threaten to displace tanker volumes on historically dominant routes.
Strategic Opportunities
- Carbon capture-ready vessel designs:Onboard CO2 capture systems are emerging as a compliance pathway for existing tonnage, with classification societies developing certification frameworks for retrofitted absorption units.
- Digital freight contracting platforms:Blockchain-enabled spot chartering is reducing fixture latency and counterparty verification costs, particularly for short-haul Aframax trades in the Atlantic basin.
- Brazilian pre-salt export growth:Deepwater production expansion off Brazil's coast is generating new long-haul crude flows to Asia, creating demand for ice-class strengthened tonnage on South Atlantic routes.
Industry Challenges
- Marine engineer shortage:Specialized training for dual-fuel propulsion and emissions monitoring equipment is outpacing available certification programs at maritime academies in Greece, Norway, and Singapore.
- CII rating volatility:Vessel carbon intensity scores fluctuate with voyage optimization and weather routing, complicating charterer pre-fixture assessments and resale valuation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Oil Carriers Market |
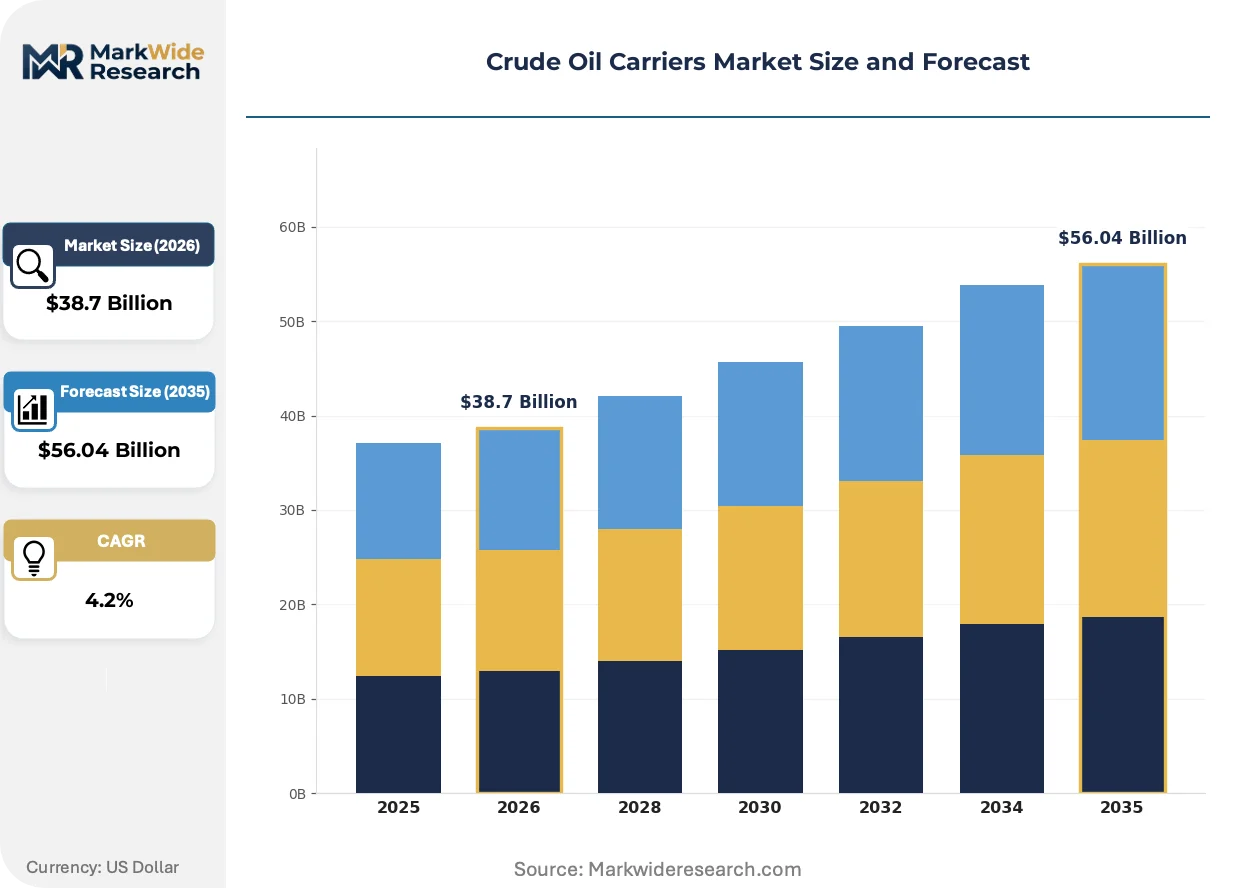
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cargo Type: Crude Oil, Refined Oil, Condensate, Bitumen Vessel Type: Aframax, Suezmax, VLCC, ULCC End User: Refineries, Shipping Companies, Traders, Brokers Construction Material: Steel, Composite, Aluminum, Others |
| Companies Covered | Euronav NV, Frontline Ltd, Teekay Corporation, DHT Holdings, Inc., China COSCO Shipping Energy, Mitsui O.S.K. Lines, Ltd., Tsakos Energy Navigation Ltd., Scorpio Tankers Inc., MOL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Oil Carriers Market Emerging Trajectories
Propulsion technology, regulatory compliance architecture, and chartering behavior are undergoing simultaneous transformation, with vessel economics now determined as much by emissions profile as by cargo capacity and speed.
Wind-assist rotor sails and kite systems are converging with conventional engine propulsion to reduce fuel consumption on long-haul routes. Mitsui O.S.K. Lines and other Japanese operators are piloting hard sail installations on VLCCs, with early deployments showing single-digit percentage fuel savings on Middle East-to-Japan voyages. This hybrid architecture is compressing the payback period for emissions-reduction investments and forcing charterers to value wind-readiness in fixture negotiations.
The EU Emissions Trading System now imposes carbon costs on maritime transport serving European ports, with compliance obligations phased in through 2026. Shipowners must surrender allowances for documented emissions, reshaping cost structures on West African and North Sea crude routes. Affected operators are responding by prioritizing younger, more efficient tonnage for Europe-bound fixtures and accelerating retirement of pre-2010 built vessels.
Charterers are consolidating purchasing power through multi-year offtake agreements with national oil companies, displacing spot-market exposure. This concentration is compressing fixture liquidity and shifting risk allocation toward shipowners, with Chinese refiners and Indian public sector undertakings leading the contracting shift. The behavioral change is most visible in Middle East export markets, where term fixtures now dominate VLCC employment patterns.
Crude Oil Carriers Market Segmentation
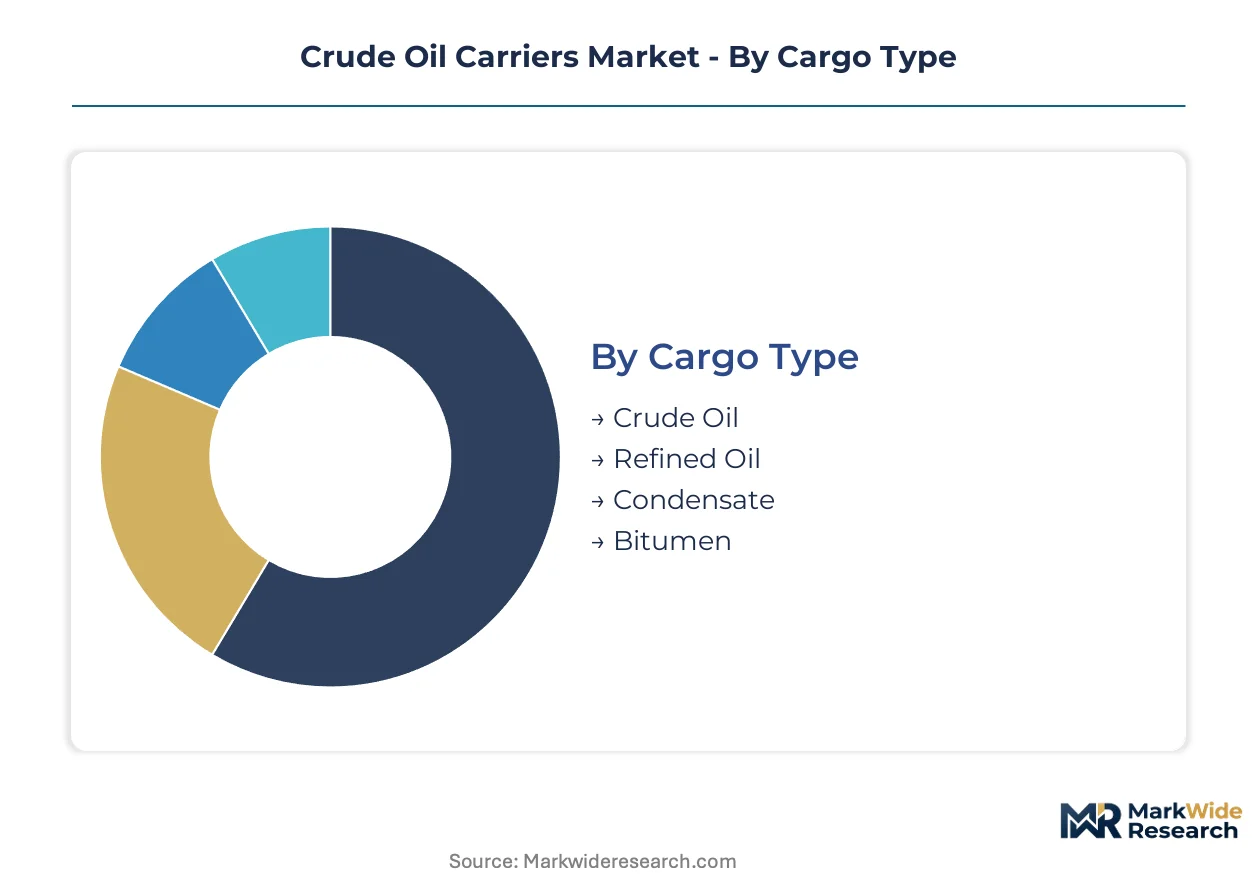
Segmentation in crude oil carriers determines charter rates, regulatory compliance pathways, and vessel deployment economics. Each dimension—cargo chemistry, hull specifications, customer type, and construction standards—carries distinct certification burdens and operational constraints that reshape fleet investment decisions.
Cargo Type:
MARPOL Annex I certification requirements vary sharply by cargo chemistry, with persistent oil residues triggering stricter tank cleaning protocols and slop management systems than volatile distillates.
- Crude Oil:Unrefined petroleum with high sulfur and heavy fraction content demands double-hull construction and segregated ballast tanks under MARPOL regulations. Middle East-to-Asia long-haul routes concentrate demand for VLCCs purpose-built for this cargo, with IMO 2023 carbon intensity rules now favoring vessels with documented emissions profiles on these fixtures.
- Refined Oil:Distillate and gasoline products require coated cargo tanks to prevent contamination and preserve product quality. Product tankers serving European refineries face EU Emissions Trading System compliance costs that crude-dedicated vessels avoid, shifting deployment patterns toward shorter-haul Atlantic basin trades.
- Condensate:Ultra-light hydrocarbon mixtures from gas processing need pressure-rated cargo systems and specialized vapor recovery equipment.
- Bitumen:Viscous residual fuel requires heated cargo tanks maintaining temperatures above 150°C during transport.
Leading the category by volume: Crude Oil. Growing fastest: Condensate.
Vessel Type:
Cost tiers separate these segments, with capital intensity scaling exponentially from regional Aframax units to ultra-large crude carriers demanding dedicated terminal infrastructure.
- VLCC:Very Large Crude Carriers exceeding 300,000 deadweight tons dominate tonne-mile economics on Middle East-to-Asia routes. Chinese and Indian refinery expansions concentrate demand for these vessels, with dual-fuel LNG-ready propulsion now penetrating newbuild specifications to hedge against future bunker fuel availability at Singapore and Fujairah hubs.
- Aframax:Medium-range tankers between 80,000 and 120,000 deadweight tons capture margin pools in port-constrained regional trades. Brazilian pre-salt exports to Atlantic basin destinations favor these units where draft limitations exclude larger vessels, with ice-class strengthening requirements growing on South Atlantic routes.
- Suezmax:Vessels sized for Suez Canal transit compete for Atlantic basin cargoes that VLCCs cannot economically serve.
- ULCC:Ultra Large Crude Carriers exceeding 500,000 deadweight tons face severe port access restrictions and limited employment opportunities.
Highest capital commitment: VLCC. Steepest expansion trajectory: Aframax.
End User:
Procurement patterns diverge sharply across customer types, with national oil companies favoring term fixtures while trading houses exploit spot volatility.
- Refineries:Integrated downstream operators in China, India, and South Korea are consolidating purchasing power through multi-year offtake agreements with Saudi Aramco and ADNOC, displacing spot-market exposure and compressing fixture liquidity for shipowners serving these term structures.
- Shipping Companies:Fleet operators face compressed margins from concentrated Greek and Norwegian ownership structures that limit charterer bargaining power in tight markets, with carbon intensity ratings now determining fixture access to EU-bound cargoes.
- Traders:Commodity merchants arbitrage temporal and geographic price differentials through floating storage and ship-to-ship transfers.
- Brokers:Intermediary fixtures are migrating toward blockchain-enabled digital platforms that reduce counterparty verification costs and fixture latency.
Dominant contract volume: Refineries. Gaining share fastest: Traders.
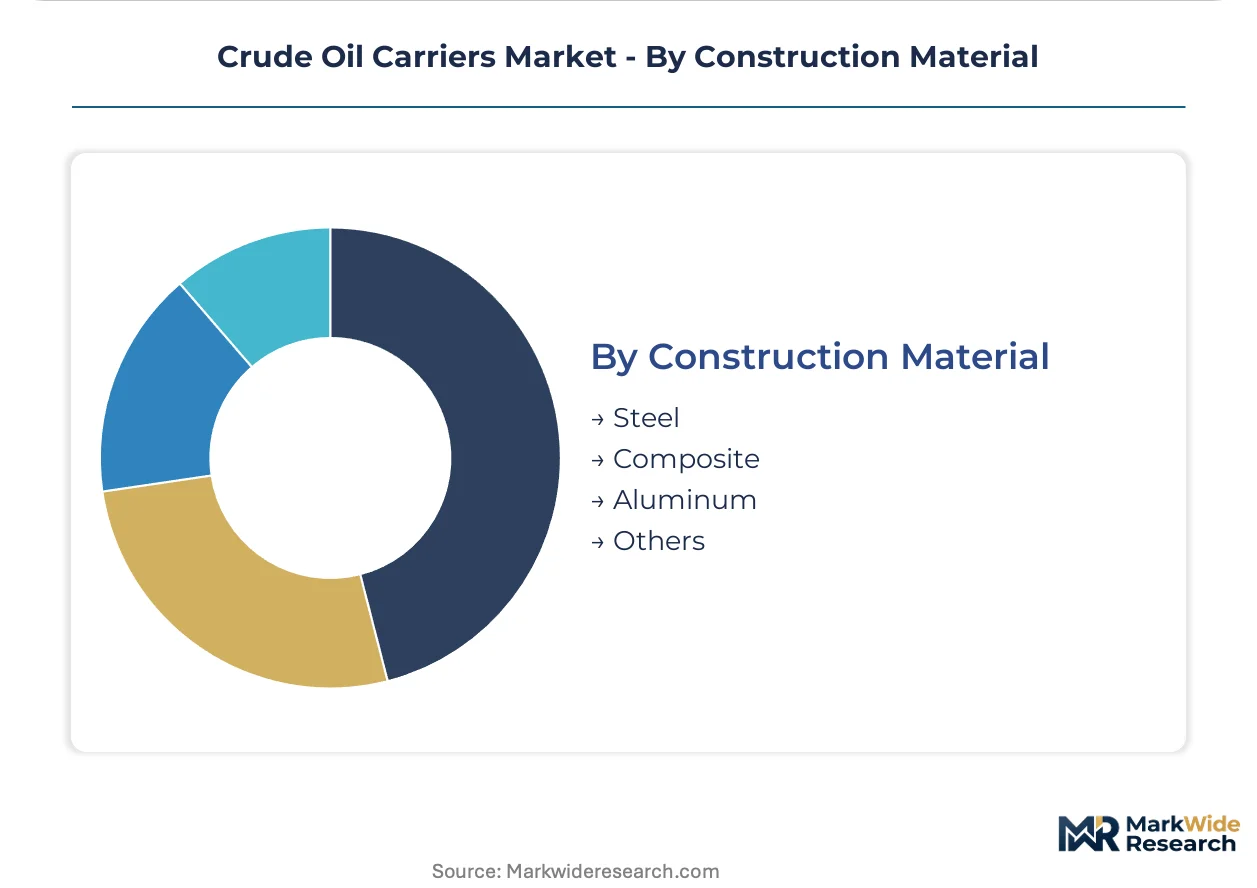
Construction Material:
Supply concentration in East Asian shipyards dictates material availability, with South Korean and Japanese builders controlling premium steel plate sourcing for compliant hull structures.
- Steel:High-tensile marine-grade plate remains mandatory for double-hull crude carrier construction under MARPOL Annex I, with shipyards in South Korea and Japan managing volatile input costs that deter speculative ordering and compress builder margins.
- Composite:Fiber-reinforced polymer applications concentrate in superstructure and piping systems where weight reduction improves vessel efficiency metrics under IMO carbon intensity calculations.
- Aluminum:Lightweight alloy deployment is limited to accommodation modules and select deck equipment due to spark hazard restrictions in hydrocarbon service.
- Others:Experimental materials including titanium cladding and corrosion-resistant alloys remain niche applications.
Absolute volume leader: Steel. Climbing the fastest: Composite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese refinery expansion and Indian import dependency concentrate crude tanker demand in Asia. Fleet renewal pressures radiate from Singapore and Fujairah bunkering hubs. Regulatory divergence between IMO frameworks and EU carbon schemes reshapes deployment economics across trade lanes.
China
Independent refiners in Shandong province and Sinopec's integrated complexes drive VLCC fixture volumes on Middle East import routes. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate retirement of pre-2010 tonnage serving Chinese ports. Dalian and Qingdao anchor the country's crude receiving infrastructure, with dedicated terminals handling over 300,000 deadweight ton vessels.
India
Public sector undertakings including Indian Oil and Bharat Petroleum deepen long-haul import dependency as domestic production declines. The Directorate General of Shipping mandates phased compliance with IMO carbon intensity indicators for vessels under Indian flag or charter. Reliance Industries' Jamnagar complex and Kochi Refineries in Kerala concentrate demand for Suezmax and VLCC units on West African and Latin American routes.
South Korea
GS Caltex and SK Energy expand cracking capacity that extends voyage distances for Middle East crude. The Ministry of Oceans and Fisheries aligns domestic regulations with IMO EEXI and CII implementation timelines. Ulsan and Yeosu industrial clusters host Asia's densest concentration of refinery-integrated petrochemical complexes, generating dedicated tanker demand for specific crude grades.
United States
Gulf Coast export terminals in Houston and Corpus Christi generate backhaul VLCC demand to Asia, reversing traditional trade flow patterns. The Environmental Protection Agency enforces vessel emissions standards under the Clean Air Act that parallel IMO frameworks. LOOP terminal facilities in Louisiana accommodate fully loaded ultra-large crude carriers, creating infrastructure asymmetry with East Coast port constraints.
Norway
Equinor's integrated trading arm and independent Norwegian shipowners control significant VLCC tonnage through Oslo-listed entities. The Norwegian Maritime Authority implements EU ETS compliance requirements ahead of full maritime carbon pricing integration. Stavanger and Oslo anchor Europe's densest concentration of crude tanker ownership and technical management expertise.
Crude Oil Carriers Market Vendor Landscape
Fleet renewal through newbuild ordering and accelerated scrapping dominates the current landscape as owners respond to IMO 2023 carbon intensity regulations. Ownership concentrates among Greek and Norwegian-controlled entities operating through tax-advantaged jurisdictions. Three archetypes define competitive positioning: scale-driven VLCC specialists, diversified multi-segment operators, and integrated trading-house affiliates. Strategic differentiation hinges on vessel age profiles and documented emissions compliance, with dual-fuel propulsion readiness emerging as a fixture-access determinant.
Within the scale-specialist tier, Frontline Ltd and Euronav NV exemplify asset-heavy positioning focused on ultra-large crude carrier employment. Mitsui O.S.K. Lines, Ltd. occupies a distinct integrated archetype, combining fleet operation with backward integration into shipbuilding and technical management. These entities represent contrasting strategic postures: pure-play tanker exposure versus diversified maritime conglomerate structure, with each configuration responding differently to carbon pricing and charterer consolidation pressures.
| Leading Market Players |
|---|
| Euronav NV |
| Frontline Ltd |
| Teekay Corporation |
| DHT Holdings, Inc. |
| China COSCO Shipping Energy |
| Mitsui O.S.K. Lines, Ltd. |
| Tsakos Energy Navigation Ltd. |
| Scorpio Tankers Inc. |
| MOL |
| Others |
Supply Flow & Price Mechanics
Dual-fuel LNG-ready propulsion premiums against conventional bunker-dependent tonnage create a bifurcated charter market that manifests in both fixture rate divergence and shipyard orderbook concentration toward South Korean and Japanese builders with certified dual-fuel capability. This tiered capability gap reshapes supply chain procurement as owners prioritize yard slots with proven LNG system integration over price-competitive alternatives.
Pricing Analysis
Volume-weighted fixtures on Middle East-to-Asia routes trade at compressed margins compared to carbon-efficient premium tiers serving EU-bound cargoes under the EU Emissions Trading System. Price differentiation rests on documented CII ratings and dual-fuel readiness, with charterers least sensitive in Indian public sector term contracts and most sensitive in Atlantic basin spot markets. Pricing pressure stems from concentrated Greek and Norwegian ownership structures that limit charterer bargaining power in tight supply windows.
Supply Chain Analysis
Freight cost asymmetries between laden eastbound and ballast westbound legs concentrate newbuild demand at South Korean, Japanese, and Chinese shipyards with proven LNG propulsion integration. Steel plate and specialized engine blocks from Germany and South Korea feed hull construction, with single-source vulnerability in low-speed two-stroke engine supply from MAN Energy Solutions and WinGD. Distribution runs through Singapore and Fujairah bunkering hubs that anchor global fuel availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crude tanker sector sits in a propulsion technology transition where LNG-ready dual-fuel systems displace conventional bunker-dependent engines as the baseline for fixture access to regulated trade lanes.
For Market Incumbents: Extend fleet renewal programs to capture carbon-compliant fixture premiums before regulatory stringency accelerates obsolescence of pre-2010 tonnage. Prioritize backward integration into shipbuilding slots at South Korean yards with proven LNG system certification. Defensive consolidation through targeted acquisitions of younger fleets with documented CII ratings offsets margin compression from charterer purchasing power concentration. For New Entrants and Emerging Players: The EU Emissions Trading System in Europe opens a window for carbon-efficient tonnage specialists to capture premium fixtures on West African and North Sea routes underserved by legacy operators. Target Aframax ice-class segments on Brazilian pre-salt export lanes where port constraints exclude larger vessels. Go-to-market positioning as verified emissions profile providers to European charterers bypasses incumbent scale advantages. For Investors and Strategic Acquirers: Re-rating potential sits with dual-fuel-ready fleet operators given IMO CII implementation tightening and EU carbon pricing expansion. Long-term viability favors owners with demonstrated LNG propulsion deployment and technical management capabilities rather than pure asset plays. Monitor CII rating volatility as the inflection signal for asset stranding risk and resale value compression.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Retrofit Program | Engine upgrades at MAN Energy Solutions and WinGD certified facilities secure EU ETS compliance. |
| Carbon Capture-Ready Design | Classification society frameworks from DNV and Lloyd's Register enable future absorption system integration. |
| Long-Term Offtake Partnership | Multi-year fixtures with Saudi Aramco and ADNOC displace spot market exposure for Chinese refiners. |
| Ice-Class Strengthening Investment | Hull reinforcement for South Atlantic routes captures Brazilian pre-salt export growth to Asia. |
| Digital Freight Platform Integration | Blockchain-enabled spot chartering reduces fixture latency for Atlantic basin Aframax trades. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with fleet operations directors, shipyard procurement managers, chartering executives at national oil companies, and maritime classification society surveyors. Lloyd's List intelligence, Clarksons Research vessel databases, IMO GHG strategy documents, and EU ETS implementation guidance provided triangulation points against bottom-up fleet capacity modeling and top-down trade flow analysis.
Vessel-level granularity modeled fleet composition by propulsion type, age profile, and carbon intensity rating across the projection horizon. Segmentation dimensions included cargo chemistry, vessel size class, end-user contracting structure, and construction material specification. CAGRs derived from tonne-mile demand elasticity to refinery capacity expansion and regulatory-driven supply compression, with bunker fuel price scenarios and steel cost volatility as sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for ammonia or methanol propulsion would alter the outlook for LNG-ready investment returns. Forecasts reflect assumptions about IMO regulatory enforcement consistency and EU carbon pricing trajectory. Stakeholders should weight assumptions against their own operating context and fuel hedging capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Global Artificial Lift Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Dissolvable Frac Plug Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market