
 Well Abandonment Services Market | 2026-2036
Well Abandonment Services Market Size, Share, and Industry Trends Forecast 2026-2036
Well Abandonment Services Market Outlook
Permanent well plugging revenue is reshaping contractor economics across the oilfield services stack. Schlumberger leverages integrated project management capabilities to bundle abandonment with subsurface diagnostics. Halliburton anchors its position through cementing technology leadership and specialized plugging fluids. Weatherford International competes with expandable plug systems that reduce rig time for multi-zone barriers.
Well abandonment services encompass the engineered decommissioning of hydrocarbon wells through mechanical isolation, cement placement, and site restoration to prevent fluid migration and environmental release. Operators deploy cement plugs across production zones and cap rock formations at depths exceeding 3,000 meters, with thermal and combination plugging methods selected based on downhole pressure and temperature profiles. The technique dimension shows cold abandonment dominating shallow onshore work while hot abandonment and section milling command premium pricing in deepwater contexts. Service type segmentation reveals mechanical plugging as the volume leader, though combination plugging is gaining traction for complex offshore wells with corroded casing strings.
The US Bureau of Safety and Environmental Enforcement enforces idle iron regulations that compel operators to plug non-producing Gulf of Mexico wells within strict timelines, directly stimulating service demand. The UK North Sea Transition Authority and Norway's Petroleum Safety Authority impose parallel decommissioning security obligations that require upfront financial guarantees. Stakeholders must monitor regulatory tightening in mature basins and assess whether cold abandonment tool standardization or hot abandonment technical specialization offers more durable margin protection.
Market Dynamics
Regulatory mandates from the US Bureau of Safety and Environmental Enforcement and the UK North Sea Transition Authority are accelerating procurement timelines for permanent well closure, compressing the window between well idling and plugging obligation.
Growth Catalysts
- Idle iron enforcement:The US Bureau of Safety and Environmental Enforcement compels Gulf of Mexico operators to plug non-producing wells within three years, creating predictable service demand cycles.
- Carbon accounting integration:Scope 3 emissions disclosure requirements under the EU Corporate Sustainability Reporting Directive treat methane venting from orphaned wells as a direct liability, driving preventive abandonment spending.
- Deepwater decommissioning wave:Brazil's pre-salt fields and West African offshore assets installed in the 1990s are reaching end-of-life, requiring specialized hot abandonment and section milling capabilities.
Market Restraints
- Specialized vessel scarcity:Heavy-lift decommissioning rigs and plug-and-abandonment semisubmersibles concentrate in the US Gulf of Mexico and North Sea, creating geographic supply bottlenecks for Asia-Pacific operators.
- Cement formulation cost volatility:Oilwell cement and specialized plugging fluids face input price pressure from energy-intensive clinker production and specialty additive supply chains.
- Technical limitation in HPHT wells:High-pressure high-temperature reservoirs exceeding 150°C and 10,000 psi challenge standard cement integrity, requiring extended testing protocols that elongate project timelines.
Strategic Opportunities
- Underpenetrated Southeast Asian basins:Malaysia's Sarawak and Sabah offshore fields and Indonesia's Mahakam Delta hold thousands of aging wells with limited local abandonment capacity, creating first-mover positioning for integrated service providers.
- Regulatory tailwind from methane fees:The US Inflation Reduction Act's Waste Emissions Charge penalizes venting from unplugged wells, converting compliance cost into proactive abandonment investment.
- Technology convergence of P&A and CCUS:Carbon capture utilization and storage site repurposing requires wellbore integrity verification using identical mechanical barriers and cement evaluation tools, opening shared competency markets.
Industry Challenges
- Competency attrition in cementing specialists:The upstream sector's cyclical employment patterns have thinned the ranks of experienced cementing engineers capable of designing zonal isolation for complex abandonment scenarios.
- Supply chain reconfiguration friction:Sanctions on Russian steel pipe and casing have forced rapid qualification of alternative tubular suppliers, delaying project mobilization for Russian Federation operators and their international joint venture partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Abandonment Services Market |
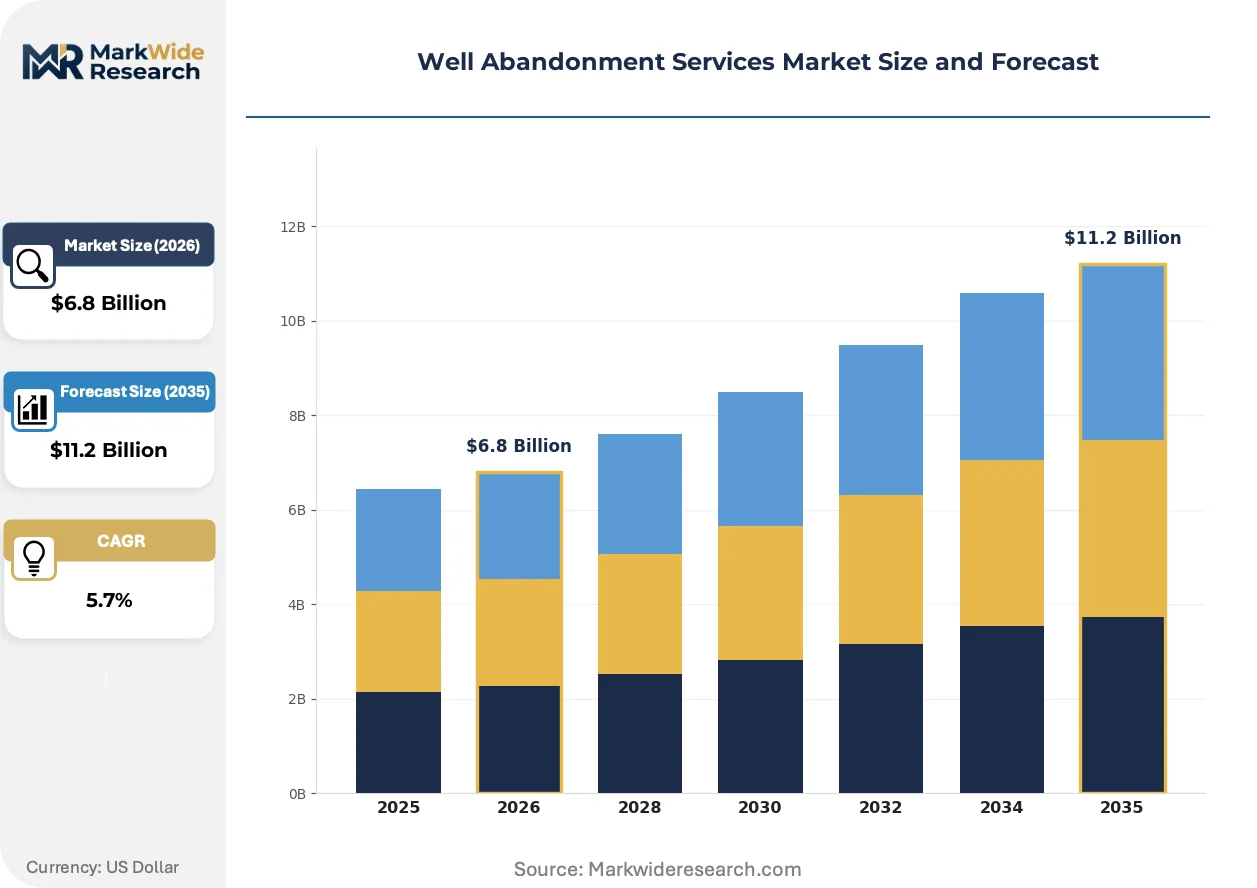
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mechanical Plugging, Cement Plugging, Thermal Plugging, Combination Plugging Technique: Cold Abandonment, Hot Abandonment, Reverse Circulation, Section Milling Application: Onshore Wells, Offshore Wells, Oil Production, Gas Production Client Type: Independent Operators, Large E&P Companies, Government Agencies, Service Providers |
| Companies Covered | Schlumberger, Halliburton, TechnipFMC, Weatherford International, Oceaneering International, Expro Group Holdings, Acteon Group, Calfrac Well Services, Petrofac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Abandonment Services Market Strategic Shifts
Mechanical barrier technology and digital verification systems are compressing rig time requirements while expanding the addressable market to marginal wells previously deemed uneconomic for permanent closure.
Expandable tubular plug systems are migrating from niche deepwater applications toward standard deployment across shelf and onshore environments. These systems create metal-to-metal seals without cement curing delays, reducing rig time from days to hours. Major Gulf of Mexico independents now specify expandable barriers for multi-zone abandonment campaigns, forcing cementing-centric contractors to diversify or cede share.
The UK North Sea Transition Authority's revised decommissioning security arrangements now require upfront financial guarantees based on third-party cost estimates rather than operator self-assessment. This policy shift accelerates security posting timelines and increases total guarantee volumes by an estimated 40 percent for late-life assets. Small-cap North Sea operators are responding by pre-negotiating fixed-price abandonment contracts to lock in service costs and reduce guarantee exposure.
Integrated project delivery models are displacing discrete service procurement for multi-well abandonment programs. Large E&P companies now bundle subsurface diagnostics, plugging engineering, and site restoration under single accountability contracts rather than tendering each phase separately. This concentration is most visible in the US Gulf of Mexico, where majors have consolidated vendor panels to three or four integrated providers per basin.
Well Abandonment Services Market Segmentation
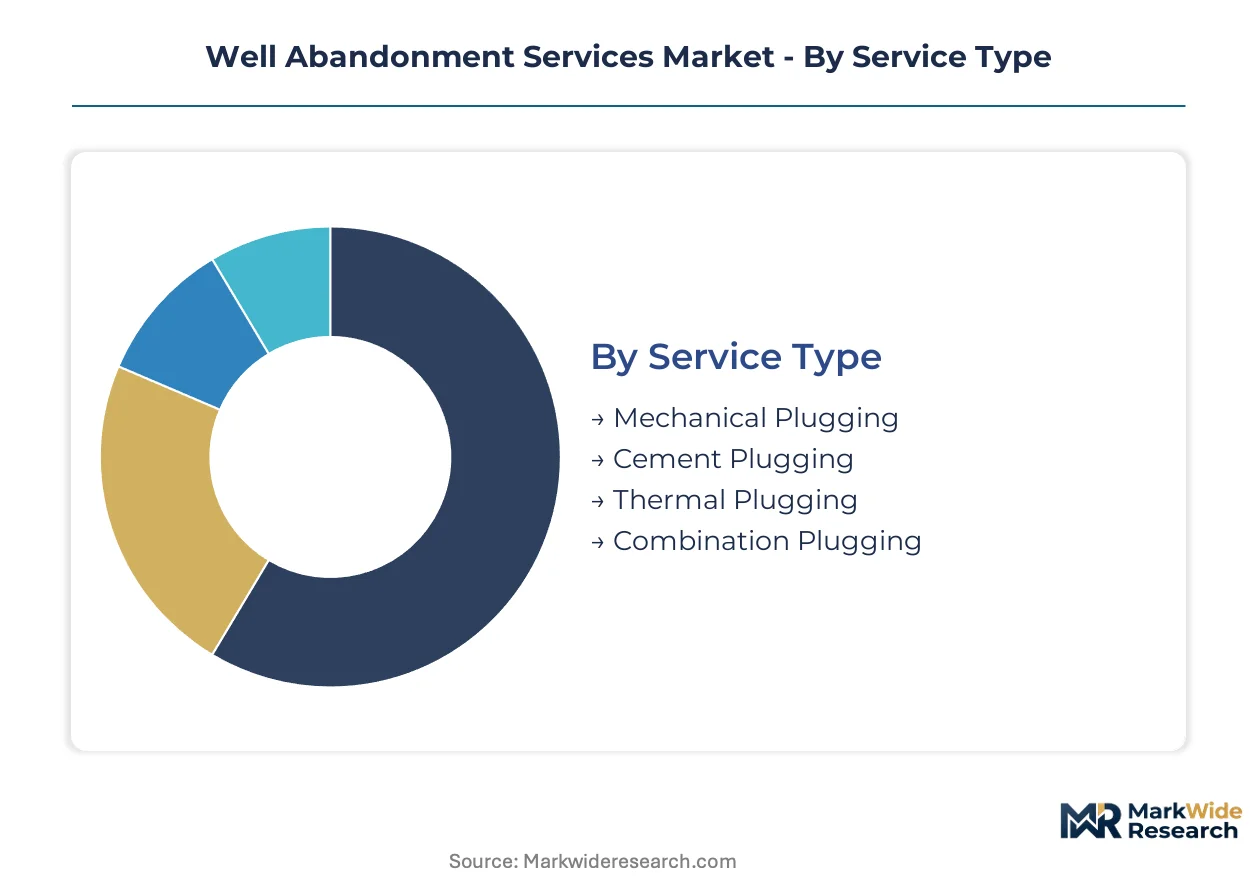
Well abandonment services fragment across technical methodologies, operational environments, and client procurement structures. Each segmentation dimension carries distinct margin profiles and capability requirements that reshape contractor positioning.
Service Type:
Engineered barrier solutions span mechanical isolation, cement placement, and thermal methods selected by downhole pressure and temperature profiles.
- Mechanical Plugging:Deploys expandable tubular barriers and bridge plugs to create metal-to-metal seals without cement curing delays. Gulf of Mexico independents now specify mechanical systems for multi-zone campaigns, compressing rig time from days to hours and forcing cementing-centric contractors to diversify capabilities.
- Cement Plugging:Places engineered cement slurries across production zones and cap rock formations at depths exceeding 3,000 meters. The US Bureau of Safety and Environmental Enforcement mandates drive predictable procurement cycles for standard zonal isolation, though input price volatility from energy-intensive clinker production squeezes margins.
- Thermal Plugging:Applies heat-activated sealing compounds for high-temperature reservoir conditions.
- Combination Plugging:Integrates mechanical and cement barriers for complex offshore wells with corroded casing strings, gaining traction in deepwater decommissioning.
Established volume favors mechanical plugging; emerging adoption favors combination plugging.
Technique:
Operational methods diverge by well temperature, pressure, and structural integrity requirements.
- Cold Abandonment:Executes plugging without wellbore heating, dominating shallow onshore work where standard cement integrity suffices. The technique commands lowest unit cost but faces margin pressure from tool standardization.
- Hot Abandonment:Applies controlled heating to maintain cement slurry properties in high-temperature formations, commanding premium pricing in deepwater contexts. Brazil's pre-salt fields and West African offshore assets reaching end-of-life drive specialized hot abandonment demand.
- Reverse Circulation:Pumps cement through annular pathways rather than conventional drill pipe delivery.
- Section Milling:Removes casing sections to enable rock-to-rock cement seals in corroded wellbores.
Cold abandonment anchors onshore volume; hot abandonment captures offshore value concentration.
Application:
Well environment and hydrocarbon type determine regulatory urgency and technical complexity.
- Onshore Wells:Encompasses conventional and unconventional terrestrial assets requiring permanent closure. The US Environmental Protection Agency and state regulators enforce orphan well programs that convert methane venting liability into preventive abandonment spending.
- Offshore Wells:Subsea and platform-based assets in marine environments face stricter security obligations. The UK North Sea Transition Authority's revised decommissioning arrangements require upfront financial guarantees based on third-party cost estimates, accelerating procurement timelines.
- Oil Production:Targets liquid hydrocarbon wells with specific fluid migration risks.
- Gas Production:Addresses methane-bearing formations where venting penalties under the US Inflation Reduction Act's Waste Emissions Charge drive proactive investment.
Offshore applications concentrate value per well; onshore scale dominates total addressable volume.
Client Type:
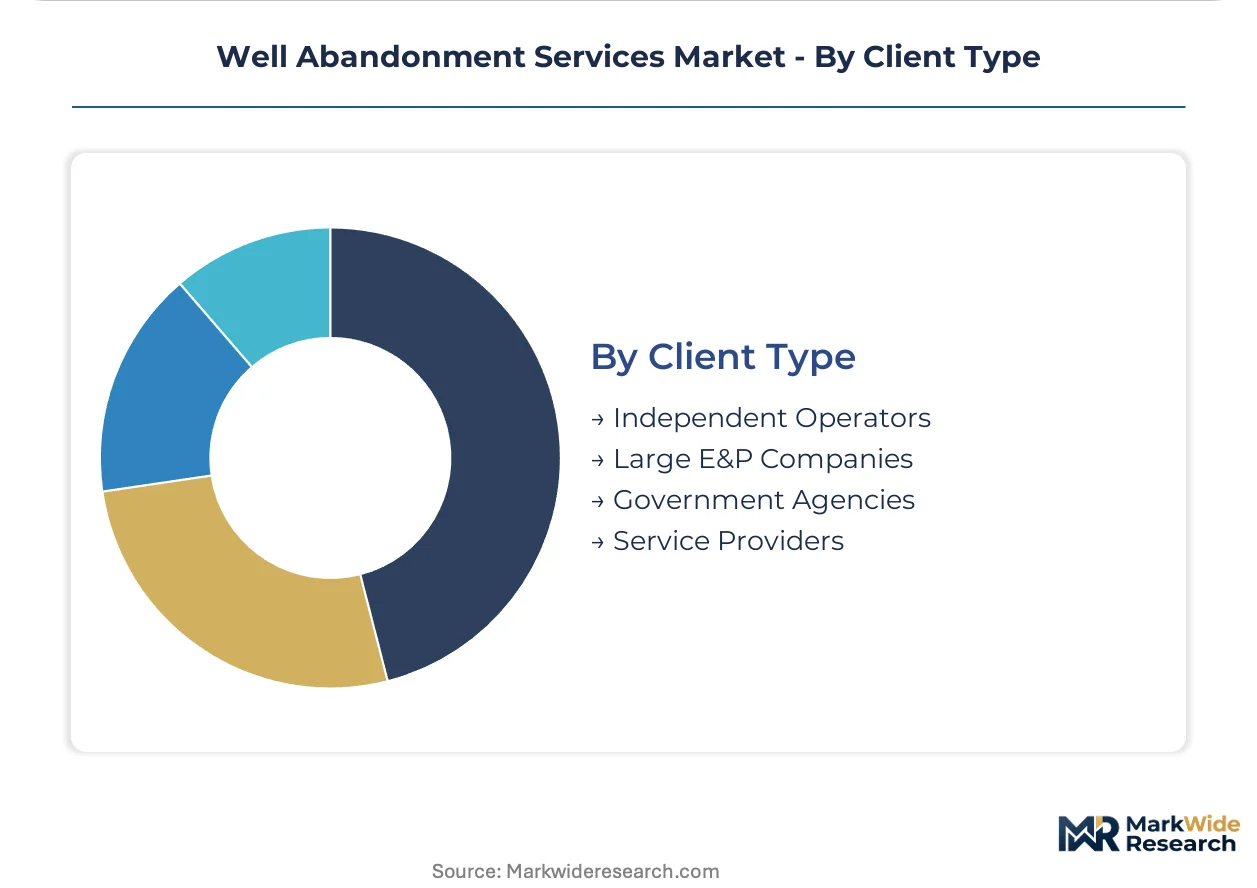
Procurement authority sits with asset owners, regulators, and specialized intermediaries.
- Independent Operators:Mid-cap and small-cap E&P companies with concentrated asset portfolios. Small-cap North Sea operators pre-negotiate fixed-price abandonment contracts to lock in service costs and reduce guarantee exposure under tightened security arrangements.
- Large E&P Companies:Integrated majors and supermajors bundling subsurface diagnostics, plugging engineering, and site restoration under single accountability contracts. US Gulf of Mexico majors have consolidated vendor panels to three or four integrated providers per basin.
- Government Agencies:State and federal entities funding orphan well remediation programs.
- Service Providers:Oilfield services contractors subcontracting specialized abandonment capabilities.
Large E&P companies drive integrated procurement; independents generate discrete service demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in mature North Sea basins exhibit lowest price sensitivity due to regulatory guarantee requirements, while Southeast Asian operators face acute cost pressure from limited local abandonment capacity and vessel scarcity.
United States
The Gulf of Mexico hosts thousands of aging subsea wells reaching end-of-life, with independents and majors accelerating procurement timelines. The US Bureau of Safety and Environmental Enforcement enforces idle iron regulations compelling non-producing well plugging within three years. Houston anchors the world's largest concentration of plug-and-abandonment contractors and heavy-lift decommissioning vessel operators.
United Kingdom
North Sea decommissioning security obligations have tightened under revised arrangements requiring upfront financial guarantees based on third-party cost estimates. The UK North Sea Transition Authority mandates accelerated security posting timelines that increase total guarantee volumes substantially. Aberdeen remains the primary service hub where small-cap operators pre-negotiate fixed-price contracts to reduce guarantee exposure.
Brazil
Pre-salt fields installed during the 1990s are entering decommissioning phase, driving specialized hot abandonment and section milling demand. The country's national petroleum regulator imposes strict well integrity verification standards for permanent closure. Rio de Janeiro concentrates deepwater service capabilities where contractors deploy combination plugging for high-pressure formations.
Norway
Mature offshore assets in the North Sea and Norwegian Sea generate sustained procurement for complex abandonment campaigns. The Petroleum Safety Authority mandates parallel decommissioning security obligations with stringent financial guarantee requirements. Stavanger hosts integrated project management specialists bundling subsurface diagnostics with plugging engineering.
Malaysia
Sarawak and Sabah offshore fields hold thousands of aging wells with limited local abandonment capacity creating supply bottlenecks. The country's national oil company procurement frameworks increasingly favor integrated service providers over discrete phase tendering. Kuala Lumpur serves as the regional coordination center where international contractors establish first-mover positioning.
Well Abandonment Services Market Competitive Environment
Integrated energy service conglomerates and specialized plugging contractors split the market between bundled accountability contracts and discrete technical service provision. The vendor base concentrates around three capability tiers: full-cycle integrated providers, cementing technology specialists, and mechanical barrier innovators. Consolidation pressure intensifies as large E&P companies reduce vendor panels to three or four integrated providers per basin. Competitive moves center on portfolio diversification into expandable plug systems and strategic partnerships for CCUS site repurposing.
Within the integrated tier, Schlumberger and Halliburton occupy positions exemplifying bundled project management capabilities, while Weatherford International anchors the mechanical barrier specialization vector. These three entities represent contrasting strategic postures: Schlumberger leverages subsurface diagnostics integration, Halliburton emphasizes cementing technology leadership, and Weatherford competes through expandable plug systems reducing rig time for multi-zone barriers.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| TechnipFMC |
| Weatherford International |
| Oceaneering International |
| Expro Group Holdings |
| Acteon Group |
| Calfrac Well Services |
| Petrofac |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Southeast Asian abandonment vessel fleets compresses procurement timelines while elevating day-rate premiums for operators facing regulatory deadlines. Gulf of Mexico rig utilization above 85 percent tightens contractor availability and strengthens pricing power for integrated providers with captive heavy-lift assets.
Pricing Analysis
After-sales cement evaluation and plug integrity monitoring contracts drive lifetime value beyond initial plugging execution. Project-based pricing dominates multi-well abandonment campaigns, with differentiation anchored in certification tier (API 10D wellbore integrity standards) and volume scale (campaigns above 50 wells command 12-18 percent unit cost reduction). Cost compression in standard mechanical plugging intensifies as tool standardization erodes technical differentiation. Small-cap independents in the North Sea exhibit highest price sensitivity due to decommissioning security guarantee burdens, while US Gulf majors prioritize schedule certainty over unit cost.
Supply Chain Analysis
Export control restrictions on high-pressure cementing equipment limit technology transfer to Russian Federation operators and their joint venture partners. Manufacturing concentrates in the United States, Norway, and Singapore, with specialized plugging fluids and expandable tubular systems drawing from energy-intensive clinker production in China and specialty alloy forging in Germany. Single-source vulnerability sits with heavy-lift decommissioning vessel operators concentrated in the US Gulf and North Sea. Distribution runs through integrated project management contracts rather than discrete service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across mature basins creates niche positioning opportunities for specialized contractors. The shift toward bundled accountability contracts favors providers with end-to-end capability stacks.
For Market Incumbents: Build switching-cost moats through embedded cement evaluation diagnostics and long-term plug integrity monitoring subscriptions. Consolidate regional vessel capacity in the US Gulf of Mexico to defend share against emerging integrated entrants. Secure backward integration into specialty alloy forging for expandable plug systems to reduce input cost volatility. For New Entrants and Emerging Players: Pursue first-mover positioning in Malaysia's Sarawak and Sabah offshore fields where local abandonment capacity remains underdeveloped. Target fixed-price contract structures for small-cap North Sea operators seeking guarantee exposure reduction. Deploy CCUS site repurposing capabilities as a differentiated entry wedge into established plugging markets. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compounding play because decommissioning security obligations tighten predictably across mature basins. Acquisition targets should display integrated project management capabilities with established relationships with national oil company procurement frameworks. Monitor US Bureau of Safety and Environmental Enforcement idle iron enforcement variance as the signal for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Expandable Plug System Development | Reduces rig time from days to hours for multi-zone barriers in Gulf of Mexico campaigns. |
| CCUS Site Repurposing Partnership | Leverages shared wellbore integrity verification tools for carbon capture utilization and storage markets. |
| Fixed-Price Contract Pre-Negotiation | Locks in service costs for small-cap North Sea operators under tightened UK decommissioning security arrangements. |
| Regional Vessel Capacity Addition | Addresses supply bottlenecks in Southeast Asian basins with limited local abandonment infrastructure. |
| Cement Evaluation Diagnostics Integration | Creates recurring revenue streams through long-term plug integrity monitoring subscriptions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plugging engineering directors, decommissioning project managers, national oil company procurement leads, and cementing technology specialists. Secondary validation drew from US Bureau of Safety and Environmental Enforcement enforcement data, UK North Sea Transition Authority decommissioning security filings, Norwegian Petroleum Safety Authority well integrity reports, and customs records for oilwell cement and specialty plugging fluid imports. Bottom-up well count analysis by basin and maturity profile triangulated against top-down contractor revenue estimates.
Calibration against historical procurement cycles and regulatory mandate implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type (mechanical, cement, thermal, combination), technique (cold abandonment, hot abandonment, section milling), application (onshore, offshore), and client procurement structure (integrated, discrete). CAGRs derived from basin-specific well population decline curves and regulatory compliance obligation schedules. Industry-specific inputs incorporated heavy-lift vessel day-rate trajectories and cement formulation cost indices.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility and offshore drilling activity levels would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and vessel availability normalization. Material shifts in US Inflation Reduction Act methane fee implementation or UK decommissioning security guarantee calculation methodologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Crown Block Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Downhole Tractor Market
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Frac Services Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Sidetracking Market
Oil & Gas
Global Artificial Lift Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
Coal Mining Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
Fracking Fluid Market