
 Well Logging Tools Market | 2026-2036
Well Logging Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Well Logging Tools Market Analysis
Buyer concentration among national oil companies and supermajors is rebalancing as independent shale operators and specialized geothermal developers fragment procurement across smaller, technology-focused contracts. Schlumberger Limited leverages its integrated drilling and evaluation portfolio to anchor premium wireline deployments in complex carbonate reservoirs. Baker Hughes competes through sustained R&D intensity in resistivity sensor miniaturization for high-temperature environments. Halliburton dominates North American onshore markets with manufacturing scale that controls regional service pricing.
Well logging tools comprise downhole instrumentation systems that measure formation properties including gamma ray emission, electrical resistivity, acoustic transit time, and nuclear magnetic response to characterize subsurface geology. These systems operate at pressures exceeding 20,000 psi and temperatures above 175°C, delivering real-time data streams that guide drilling decisions and completion designs. Wireline logging retains the largest installed base due to its established reliability in post-drilling formation evaluation, though logging-while-drilling technology captures the fastest expansion as operators prioritize geosteering accuracy in extended-reach laterals. Resistivity technology leads margin pools because of its critical role in identifying hydrocarbon-bearing zones and justifying premium pricing for high-definition array tools.
The US Bureau of Safety and Environmental Enforcement mandates comprehensive wellbore integrity documentation that directly expands demand for cased hole logging services. API Specification Q2 and ISO 9001 quality frameworks govern tool calibration protocols, creating compliance barriers for uncertified entrants. China's GB standards and National Energy Administration directives impose domestic content requirements that reshape competitive access across Asia-Pacific onshore blocks. Stakeholders must monitor how regulatory divergence between North American performance-based rules and prescriptive Asian standards affects product development roadmaps and certification investments.
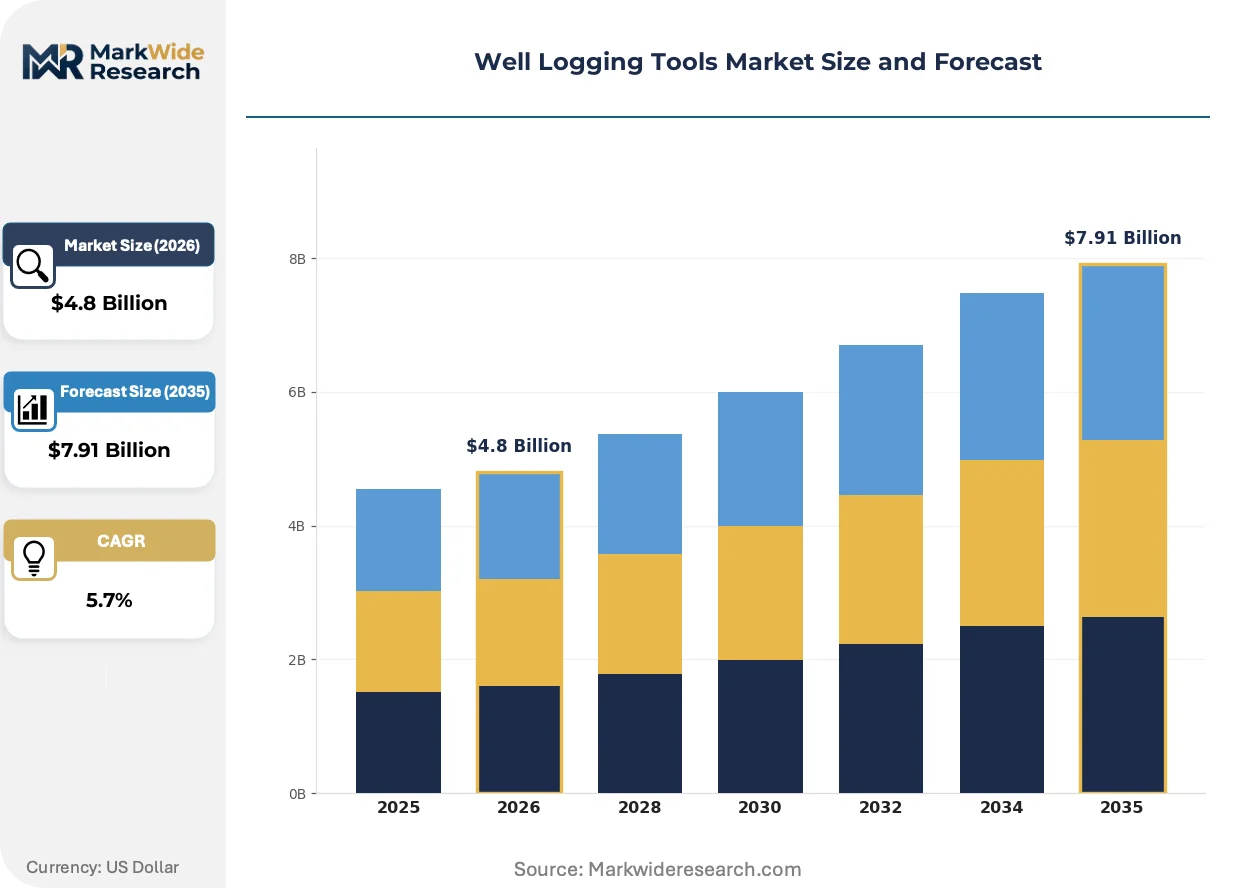
Market Dynamics
Logging-while-drilling systems are compressing the traditional wireline service cycle as operators prioritize real-time geosteering precision in extended-reach laterals, fundamentally restructuring capital allocation between pre-drilling and post-drilling evaluation phases.
Growth Catalysts
- US Bureau of Safety and Environmental Enforcement mandates:Well integrity documentation requirements expand cased hole logging service contracts across Gulf of Mexico deepwater assets.
- Permian Basin horizontal drilling density:Continuous tool deployment cycles in West Texas and southeastern New Mexico sustain replacement demand for resistivity and gamma ray sensors.
- Carbonate reservoir complexity:Middle Eastern and Caspian operators deploy premium array tools to resolve dual-porosity systems that conventional measurements mischaracterize.
Market Restraints
- Tungsten and cobalt supply concentration:High-density logging tool components face input cost volatility from Democratic Republic of Congo and Chinese refining dominance.
- API Specification Q2 calibration barriers:Quality framework compliance creates capital intensity thresholds that exclude uncertified regional service entrants.
- Electronics thermal degradation:Resistivity sensors face fundamental material science limits above 200°C that constrain high-pressure high-temperature reservoir access.
Strategic Opportunities
- Geothermal reservoir characterization:Enhanced geothermal systems in Nevada and Utah create demand for temperature-hardened acoustic and nuclear magnetic tools originally developed for oil and gas.
- China's GB standards domestic content requirements:National Energy Administration directives force joint venture structures that transfer manufacturing capability to local partners.
- AI-driven real-time interpretation:Machine learning convergence with downhole telemetry compresses decision cycles from hours to minutes during geosteering operations.
Industry Challenges
- Petrophysicist talent scarcity:Specialized interpretation expertise for complex lithology evaluation concentrates at major service companies, constraining independent operator capability.
- ISO 9001 certification timelines:Tool recertification cycles following design modifications delay field deployment and compress revenue recognition windows.
- Legacy system integration friction:Digital telemetry protocols from 1990s-era wireline fleets resist interoperability with modern cloud-based data platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Logging Tools Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireline Logging, MWD, LWD, Cased Hole Logging Technology: Gamma Ray, Resistivity, Sonic, Nuclear End User: Oil & Gas Companies, Service Providers, Research Institutions, Environmental Agencies Application: Formation Evaluation, Reservoir Characterization, Fluid Identification, Well Completion |
| Companies Covered | Weatherford International, National Oilwell Varco, Schlumberger Limited, Century Geophysical, Mount Sopris Instruments, Halliburton, China National Petroleum Corporation, Horizon Well Logging, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Logging Tools Market Emerging Trajectories
Downhole instrumentation is absorbing computational workloads that previously required surface processing, compressing the latency between measurement and drilling decision while elevating thermal and vibration tolerance requirements for embedded electronics.
Resistivity sensor miniaturization is absorbing power constraints and thermal management challenges that previously limited tool deployment duration. Shale operators in the Permian and Bakken formations adopt these compact arrays for extended lateral sections where tool retrieval costs exceed sensor replacement economics. The technology is absorbing market share from conventional induction tools by enabling longer downhole residence without telemetry interruption.
The EU F-Gas Regulation and analogous EPA phase-down schedules for hydrofluorocarbon coolants are forcing redesign of thermal management systems in surface logging units. Tool manufacturers substitute synthetic dielectric fluids and passive cooling architectures to maintain electronics stability. European North Sea operators face accelerated compliance timelines that compress product development cycles for service companies with significant North Sea exposure.
Buyer consolidation among national oil companies fragments into specialized technology contracts with independent shale operators and geothermal developers. Small-scale procurement teams now source logging services through digital platforms that unbundle interpretation from raw data delivery. This pattern concentrates in Texas and Oklahoma where private equity-backed drillers prioritize variable cost structures over integrated service relationships.
Well Logging Tools Market Segmentation
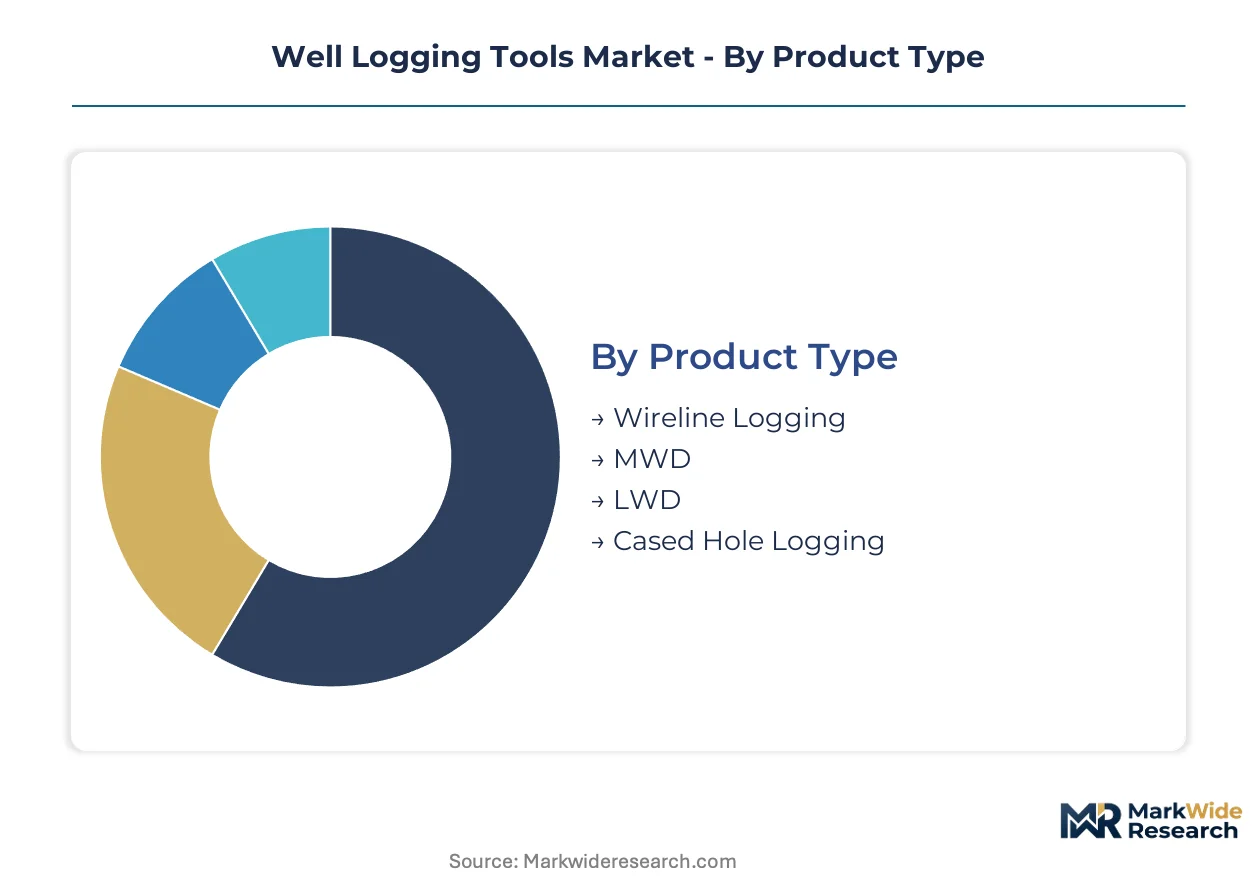
Well logging tools fragment across four intersecting dimensions that reshape competitive strategy. Product type determines capital intensity and service cycle timing. Technology selection drives margin pools through sensor complexity and environmental tolerance.
Product Type:
Volume concentration sits with established wireline fleets, while premium expansion flows toward real-time drilling integration.
- Wireline Logging:Post-drilling measurement systems deploy on conductive cable for comprehensive formation evaluation. Permian Basin operators sustain replacement demand through continuous horizontal well programs where reliability trumps speed. Established calibration protocols and API Specification Q2 compliance create defensible incumbent positions.
- LWD:Logging-while-drilling systems transmit resistivity and gamma data via mud pulse or electromagnetic telemetry during bit rotation. Extended-reach laterals in West Texas and New Mexico demand geosteering precision that compresses decision cycles from hours to minutes. Thermal and vibration tolerance requirements elevate embedded electronics specifications above wireline equivalents.
- MWD:Measurement-while-drilling tools focus on directional and drilling parameter telemetry rather than formation evaluation. Directional drilling contractors in Oklahoma's SCOOP and STACK plays standardize these packages for wellbore placement accuracy.
- Cased Hole Logging:Through-tubing evaluation services verify cement integrity and production profiling in mature wells. US Bureau of Safety and Environmental Enforcement mandates expand contract volumes across Gulf of Mexico deepwater assets.
Today's leader: Wireline Logging. Tomorrow's challenger: LWD.
Technology:
Margin stratification follows sensor physics complexity and environmental hardening requirements.
- Resistivity:Array induction and laterolog tools measure formation electrical properties to distinguish hydrocarbon from water zones. High-definition azimuthal sensors command premium pricing in Middle Eastern carbonate reservoirs where dual-porosity systems challenge conventional interpretation. Cobalt and tungsten supply concentration in Democratic Republic of Congo and Chinese refining channels creates input cost volatility.
- Gamma Ray:Natural gamma radiation detectors identify shale content and stratigraphic correlation markers. Permian Basin density sustains sensor deployment volumes where gamma signatures distinguish landing zones in stacked pay intervals.
- Sonic:Acoustic transit time measurements determine porosity and mechanical properties for completion design. Temperature-hardened variants find geothermal application in Nevada and Utah enhanced geothermal systems.
- Nuclear:Neutron porosity and density tools require radioactive source management protocols that elevate operational compliance costs. Formation evaluation complexity justifies deployment in deepwater Gulf of Mexico wells where porosity accuracy determines reserve booking.
Resistivity commands the steepest expansion trajectory through premium array adoption.
End User:
Procurement authority is dispersing from integrated majors toward specialized independents and emerging geothermal developers.
- Oil & Gas Companies:Supermajors and national oil companies anchor long-term integrated service contracts with bundled interpretation and raw data delivery. Saudi Aramco and ADNOC sustain premium wireline deployment in complex carbonate reservoirs.
- Service Providers:Directional drilling and completions specialists unbundle logging procurement through digital platforms. Texas and Oklahoma private equity-backed operators prioritize variable cost structures over captive technical staff.
- Research Institutions:Academic and government geology programs deploy slim-hole tools for experimental reservoir characterization. Limited procurement scale constrains vendor customization responsiveness.
- Environmental Agencies:Regulators mandate cased hole logging for well integrity verification in abandoned well programs. EPA and state environmental departments in California and Pennsylvania expand contract scope for methane emissions reduction.
Service Providers are gaining procurement influence fastest through digital platform adoption.
Application:
Workflow timing determines tool specification—real-time drilling decisions versus post-drilling reserve quantification.
- Formation Evaluation:Comprehensive petrophysical analysis combines multiple sensor measurements for lithology, porosity, and fluid saturation determination. Wireline logging retains dominance where post-drilling data quality exceeds real-time telemetry constraints.
- Reservoir Characterization:Static and dynamic property mapping guides field development planning. Middle Eastern operators deploy premium array tools to resolve fracture networks and dual-porosity systems in carbonate formations.
- Fluid Identification:Resistivity and nuclear magnetic resonance tools distinguish movable hydrocarbon from bound water and residual oil. Bakken shale operators optimize completion staging through fluid typing accuracy.
- Well Completion:Perforation and stimulation design relies on cased hole logging for cement evaluation and production profiling. Permian Basin infill drilling sustains continuous tool deployment cycles.
Formation Evaluation anchors current revenue. Reservoir Characterization is climbing fastest through AI-driven interpretation convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys more logging-while-drilling systems than any other single market, while China's domestic content mandates are reshaping competitive access across Asia-Pacific onshore blocks. Regulatory divergence between performance-based North American rules and prescriptive Asian standards creates distinct certification investment pathways.
United States
The Permian Basin sustains the densest horizontal drilling activity globally, with West Texas and southeastern New Mexico operators running continuous tool deployment cycles. The US Bureau of Safety and Environmental Enforcement mandates comprehensive wellbore integrity documentation that directly expands cased hole logging contracts across Gulf of Mexico deepwater assets. Houston anchors the largest concentration of wireline service company headquarters and manufacturing facilities.
China
National Energy Administration directives impose domestic content requirements that force joint venture structures transferring manufacturing capability to local partners. GB standards and MIIT regulations govern tool calibration protocols, creating compliance barriers for uncertified foreign entrants. Sichuan Basin shale operators are expanding adoption of temperature-hardened acoustic tools for complex reservoir characterization.
Saudi Arabia
Saudi Aramco sustains premium wireline deployment in complex carbonate reservoirs where dual-porosity systems challenge conventional interpretation. The national oil company's long-term integrated service contracts anchor demand for high-definition array resistivity tools. Dhahran and the Eastern Province concentrate technical service centers and equipment staging yards.
Brazil
Pre-salt deepwater exploration programs by Petrobras and international partners expand demand for high-pressure high-temperature logging systems. ANP regulatory frameworks mandate comprehensive formation evaluation for reserve booking in ultra-deepwater wells. Rio de Janeiro serves as the primary logistics hub for offshore tool deployment across the Santos and Campos basins.
Norway
North Sea operators face accelerated EU F-Gas Regulation compliance timelines that compress product development cycles for thermal management system redesigns. The Norwegian Petroleum Directorate enforces stringent well integrity verification requirements for mature field redevelopment. Stavanger and Bergen anchor the largest concentration of subsea logging service specialists in Europe.
Well Logging Tools Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven manufacturing dominance clashes with niche sensor innovation. The vendor base organizes around three strategic archetypes: integrated oilfield service conglomerates with full drilling-evaluation portfolios, specialized wireline contractors with regional density, and technology-focused instrument manufacturers with proprietary sensor platforms. Dominant competitive moves include backward integration into high-density component manufacturing and strategic partnerships for AI-driven real-time interpretation capabilities.
Among Houston-based integrated service providers, Schlumberger Limited, Halliburton, and Baker Hughes occupy positions exemplifying the conglomerate archetype through their combined drilling, evaluation, and completion portfolios. Weatherford International and National Oilwell Varco represent the specialized contractor tier with focused equipment manufacturing and regional service density. China National Petroleum Corporation anchors the state-backed national champion model, while Century Geophysical and Mount Sopris Instruments exemplify technology-focused specialists with concentrated instrument platforms.
| Leading Market Players |
|---|
| Weatherford International |
| National Oilwell Varco |
| Schlumberger Limited |
| Century Geophysical |
| Mount Sopris Instruments |
| Halliburton |
| China National Petroleum Corporation |
| Horizon Well Logging |
| Baker Hughes |
| Others |
Supply Flow & Price Mechanics
Supermajor procurement concentration in integrated drilling-evaluation contracts anchors premium pricing for wireline and logging-while-drilling bundles, while independent shale operators fragment purchasing through digital platforms that unbundle interpretation from raw data delivery. This buyer bifurcation sustains dual pricing structures: long-term contract stability at the top and spot-market variability below.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard wireline tools as domestic manufacturing joint ventures transfer production capability to local partners under GB standards compliance. Three-tier pricing structure across premium array resistivity, standard induction tools, and economy gamma ray sensors reflects certification grade and thermal tolerance specifications. Cost compression in the economy tier is intensifying because National Energy Administration domestic content requirements force foreign entrants into margin-sharing partnerships. National oil companies exhibit lowest price sensitivity due to reserve booking accuracy requirements, while private equity-backed Permian independents prioritize variable cost structures and drive spot-market negotiation.
Supply Chain Analysis
Freight costs for high-density logging tool components from Democratic Republic of Congo and Chinese refining channels elevate landed costs for tungsten and cobalt-dependent sensor arrays. Manufacturing concentrates in the United States for North American onshore service fleets, China for Asia-Pacific domestic content compliance, and Germany for EU F-Gas Regulation-aligned thermal management systems. Electronics supply draws from Taiwan for high-temperature semiconductors and Japan for precision acoustic transducers. Single-source vulnerability in rare earth processing creates exposure to export restriction shocks. Distribution runs through Houston-based service company hubs for North American deployment, Dubai for Middle Eastern carbonate reservoir projects, and Singapore for Asia-Pacific offshore logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturing joint ventures in China undercut US and European cost structures by fifteen to twenty percent on standard tool categories, while regulatory divergence between API Specification Q2 and GB standards creates compliance-cost asymmetries that favor localized production strategies.
For Market Incumbents: Extend manufacturing scale advantages in North America through backward integration into high-density component production, capturing cobalt and tungsten supply channels that independent entrants cannot access. Anchor premium positioning by embedding AI-driven real-time interpretation capabilities that compress geosteering decision cycles, defending against technology-focused specialists with proprietary sensor platforms. Prioritize certification investments for EU F-Gas Regulation compliance to maintain North Sea access as accelerated thermal management redesign timelines exclude slower-moving competitors. For New Entrants and Emerging Players: Temperature-hardened acoustic and nuclear magnetic tools originally developed for oil and gas applications offer a technology-first wedge into Nevada and Utah enhanced geothermal systems where incumbent service companies lack dedicated sales coverage. Target environmental agency cased hole logging contracts for abandoned well integrity verification in California and Pennsylvania, where EPA methane emissions reduction mandates expand procurement scope outside traditional oil and gas channels. Pursue digital platform partnerships with private equity-backed Permian operators that prioritize unbundled data delivery over integrated service relationships. For Investors and Strategic Acquirers: Integrated oilfield service conglomerates are the most active acquirer in this space, seeking proprietary sensor platforms that fill technology gaps in high-pressure high-temperature capabilities. Long-term viability hinges on exposure to geothermal reservoir characterization and carbon capture monitoring applications that extend tool relevance beyond hydrocarbon extraction cycles. Monitor US Bureau of Safety and Environmental Enforcement rulemaking on well integrity documentation requirements as the signal indicating expansion or contraction in cased hole logging service contract volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Density Components | Captive supply of tungsten and cobalt reduces input cost volatility from DRC and Chinese refining channels. |
| AI-Driven Real-Time Interpretation Partnership | Machine learning convergence with downhole telemetry compresses geosteering decision cycles for Permian operators. |
| Geothermal Tool Adaptation Program | Temperature-hardened acoustic and nuclear magnetic tools access Nevada and Utah enhanced geothermal demand. |
| EU F-Gas Regulation Compliance Certification | Synthetic dielectric fluid and passive cooling architectures maintain North Sea market access against accelerated timelines. |
| Digital Platform Integration for Unbundled Services | Raw data delivery without interpretation captures private equity-backed operator procurement in Texas and Oklahoma. |
Methodological Framework
Bottom-up operator deployment modeling reconciled against top-down service company capacity tracking forms the analytical core of this study. Primary interviews with directional drilling contractors, petrophysicist interpretation leads, wireline service operations managers, and geothermal project developers combined with secondary validation from API Specification Q2 filings, US Bureau of Safety and Environmental Enforcement compliance records, National Energy Administration domestic content directives, and SEC 10-K equipment revenue disclosures. Triangulation across these sources ensures segmentation integrity for wireline logging, logging-while-drilling, measurement-while-drilling, and cased hole logging product categories.
Input-output matrices map tool deployment intensity against horizontal drilling permits, deepwater exploration commitments, and geothermal well stimulation programs across the analysis window. Segmentation dimensions include product type, technology physics, end-user procurement authority, and application workflow timing, with regional regulatory framework clusters as an additional modeling layer. CAGRs derive from fitted growth curves calibrated to historical replacement cycles and projected exploration capital allocation shifts. Forecast inputs incorporate Permian Basin drilling density trajectories and Middle Eastern carbonate reservoir complexity indices.
The model holds under sustained hydrocarbon exploration capital commitment and regulatory enforcement continuity; deviation in geothermal subsidy expansion or accelerated well integrity mandate phase-ins would shift growth trajectories between technology segments. Stakeholders should weight assumptions against their own operating context and sensitivity to rare earth supply disruption or regional regulatory divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Slickline Services Market
Oil & Gas
Frac Stack Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Vietnam Oil and Gas Market