
 Oil Water Separator Market | 2026-2036
Oil Water Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Water Separator Market Intelligence
The gap between premium and commodity tiers is expanding as API standards tighten and offshore operators demand corrosion-resistant alloys while municipal buyers prioritize carbon steel units. Alfa Laval leverages its marine centrifuge heritage to dominate offshore platform installations. Veolia anchors its position through integrated service contracts that bundle separator hardware with long-term effluent compliance management.
An oil water separator is a pressure vessel or gravity-based system that removes petroleum hydrocarbons from wastewater streams, typically achieving effluent concentrations below 15 ppm oil-in-water through coalescing media, centrifugal force, or dissolved air flotation. Its primary purpose is to prevent hydrocarbon discharge into waterways, protect downstream biological treatment processes, and recover valuable oil fractions for reuse or resale. Coalescing separators lead the type category due to their compact footprint and predictable performance across variable inlet conditions. Centrifugal separators capture the fastest growth as offshore operators seek high-G-force solutions for space-constrained platforms. Filtration systems occupy the mature, price-sensitive tier where replacement media sales sustain margin pools.
The US EPA enforces Clean Water Act effluent guidelines that mandate oil-in-water limits for refinery and petrochemical discharges, directly shaping separator specification requirements. The EU's Industrial Emissions Directive and REACH chemical registration framework impose parallel compliance burdens on European manufacturing plants and shipyards. Stakeholders must monitor how emerging per- and polyfluoroalkyl substance restrictions affect coalescing media chemistry and replacement part sourcing strategies.
Market Dynamics
The US EPA's tightening effluent limitation guidelines are compressing discharge thresholds for oily wastewater, forcing refinery and petrochemical operators to accelerate separator replacement cycles and upgrade to higher-performance coalescing systems.
Growth Catalysts
- Marine retrofit mandates:International Maritime Organization discharge standards are compelling shipping fleets to install compliant separators, driving sustained demand for compact centrifugal units.
- REACH chemical registration:The EU's framework is restricting legacy coalescing media chemistries, creating replacement demand for compliant synthetic materials in European manufacturing plants.
- Gulf Coast refinery expansion:Concentrated petrochemical capacity additions along the Texas-Louisiana corridor are generating clustered procurement of high-capacity gravity separators.
Market Restraints
- Specialized alloy input costs:Corrosion-resistant stainless steel and duplex alloys for offshore platforms face volatile pricing from concentrated Nordic and Japanese mill suppliers.
- Coalescing media supply concentration:Polypropylene and fluoropolymer fiber production clusters in Germany and China create single-source vulnerability for replacement cartridge procurement.
- Centrifugal separator technical ceiling:High-G-force systems above 5,000 rpm encounter bearing longevity limitations in heavy crude applications, constraining deployment scope.
Strategic Opportunities
- India's industrial wastewater rules:The Central Pollution Control Board's tightening standards for petroleum refineries create first-mover advantage for coalescing system suppliers in the Gujarat-Maharashtra belt.
- Produced water treatment:Shale operators in the Permian Basin are expanding secondary treatment trains, opening demand for compact flotation units that complement primary separators.
- Digital twin integration:Convergence of IoT sensors with predictive maintenance software is enabling performance-based service contracts that bundle hardware with remote monitoring.
Industry Challenges
- API 421 certification timelines:Third-party verification for refinery-grade separators extends 14-18 months, compressing project delivery windows and straining engineering resources.
- Legacy system integration:Brownfield installations must reconcile new separator controls with existing distributed control systems from disparate vintages, multiplying commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Water Separator Market |
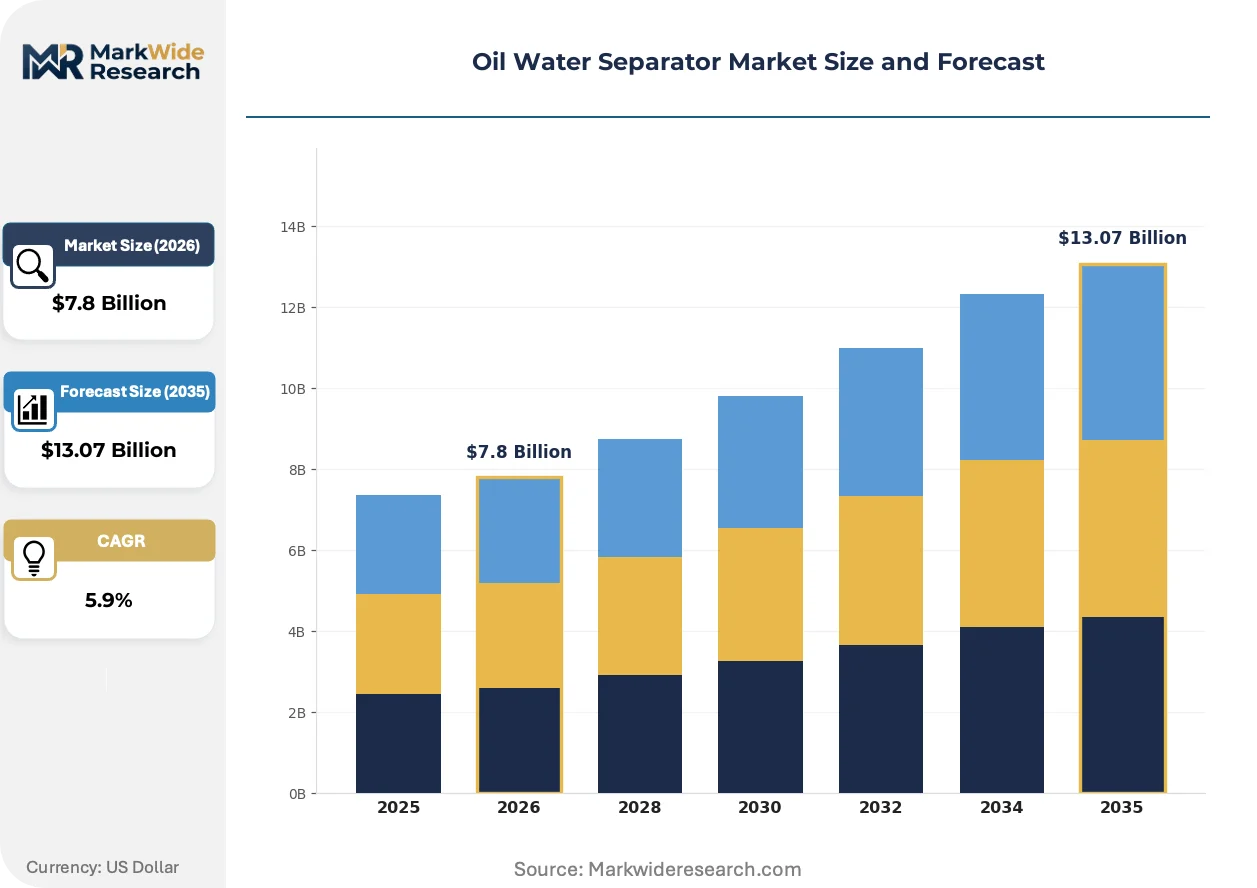
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.07 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gravity Separators, Centrifugal Separators, Coalescing Separators, Filtration Systems, Dissolved Air Flotation Application: Refinery Effluent, Marine Discharge, Petrochemical Plants, Food Processing, Metal Finishing Installation: Onshore Facilities, Offshore Platforms, Industrial Plants, Municipal Treatment Plants End User: Oil & Energy Producers, Manufacturing Plants, Shipyards, Wastewater Treatment Operators |
| Companies Covered | Alfa Laval, Ecolab, Veolia, GEA Group, Sulzer Ltd, Parker Hannifin Corporation, Wärtsilä Oyj Abp, Andritz AG, Hydro International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Water Separator Market Strategic Shifts & Innovations
Separator technology is converging around intelligent monitoring and modular construction, compressing footprint requirements while extending predictive maintenance capabilities across dispersed asset bases.
Hybrid coalescing-flotation systems are unifying gravity separation with dissolved air flotation in single-vessel configurations. Offshore platform operators in the North Sea are adopting these units to eliminate redundant skids. The technology is unifying what were separate procurement decisions into integrated vessel specifications, reducing engineering contractor scope fragmentation.
REACH per- and polyfluoroalkyl substance restrictions are phasing out fluoropolymer-based coalescing media by 2027. European chemical manufacturers must reformulate separator cartridges with silicone or polyolefin alternatives. German automotive paint shops and Belgian steel mills are accelerating media replacement cycles to preempt compliance deadlines.
Service unbundling is fragmenting traditional bundled maintenance contracts. Municipal wastewater authorities and independent refineries are separating separator hardware procurement from aftermarket service, driving spot-market competition for cartridge replacement and sludge hauling. This pattern is most pronounced in Texas and California where specialized service providers have captured aftermarket revenue pools from original equipment manufacturers.
Oil Water Separator Market Segmentation
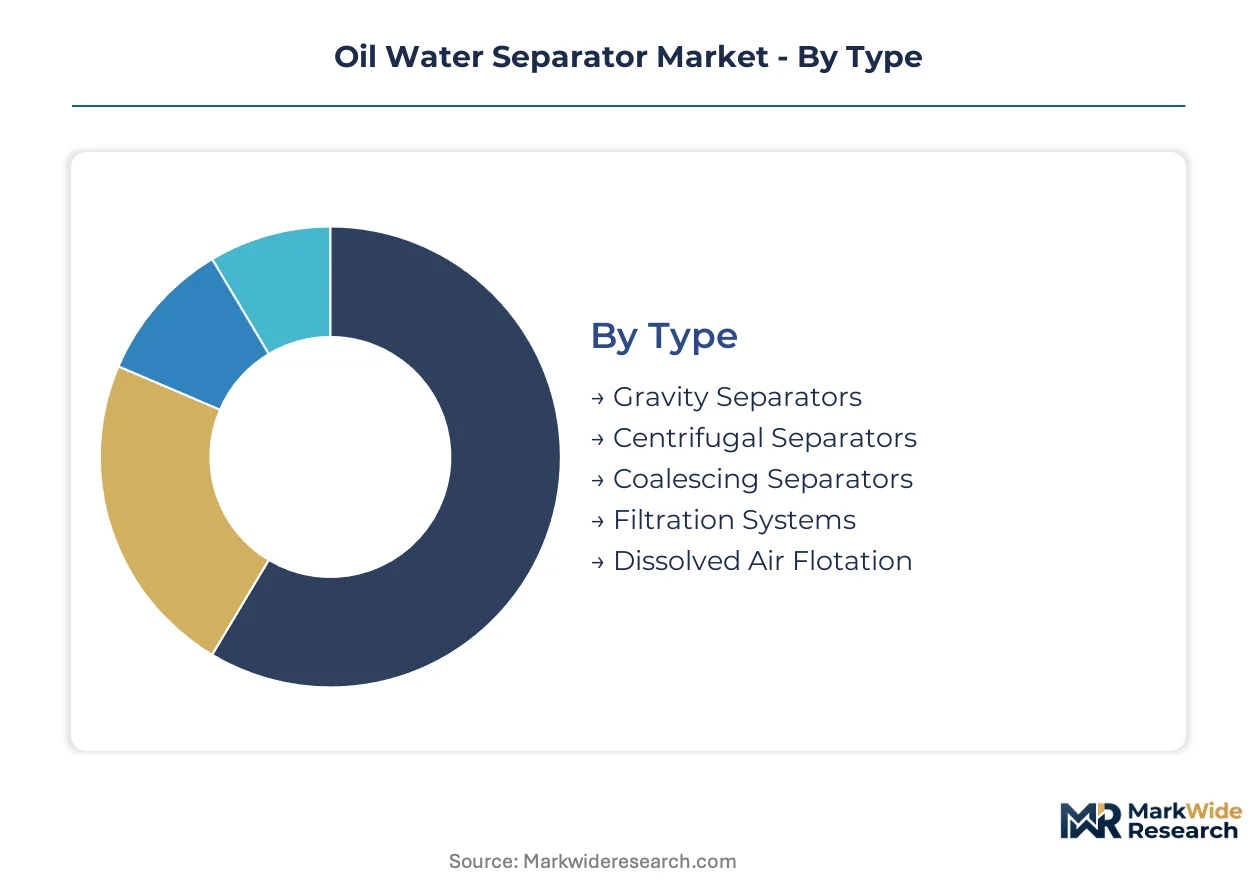
Separator specification varies sharply across installation environments and effluent chemistry. Procurement decisions hinge on discharge thresholds, footprint constraints, and integration complexity with existing treatment trains.
Type:
Capital intensity escalates from gravity-based vessels through high-G-force centrifugal systems requiring precision bearings and exotic alloys.
- Coalescing Separators:These systems pass wastewater through oleophilic media packs that agglomerate dispersed oil droplets into buoyant masses. Refinery operators along the US Gulf Coast specify these units for their predictable 10-15 ppm effluent performance across variable inlet loads. REACH chemical restrictions are forcing media reformulation toward silicone-based alternatives.
- Centrifugal Separators:Spinning bowl architectures generate gravitational forces exceeding 5,000 G to separate immiscible fluids. North Sea platform engineers select these where deck space commands premium valuations, though bearing longevity limits deployment in heavy crude service.
- Gravity Separators:API 421-compliant rectangular tanks with parallel plate coalescers dominate municipal and legacy industrial procurement.
- Filtration Systems:Disposable cartridge configurations serve as polishing stages downstream of primary separation.
- Dissolved Air Flotation:Microbubble injection systems target emulsified oils in food processing and metal finishing effluent.
Coalescing separators absorb the bulk of installed capacity; centrifugal separators are expanding most quickly.
Application:
Regulatory stringency varies dramatically across discharge pathways, with marine and refinery effluent facing the most aggressive enforcement.
- Refinery Effluent:Catalytic cracking and coking operations generate wastewater streams with oil concentrations exceeding 1,000 ppm. US EPA effluent guidelines mandate continuous monitoring and documented compliance, driving specification toward redundant separator trains.
- Marine Discharge:Bilge and ballast water treatment aboard commercial vessels must satisfy MARPOL Annex I 15 ppm standards. Shipowners retrofitting existing fleets prioritize compact skid-mounted units that fit confined engine room envelopes.
- Petrochemical Plants:Olefins and aromatics production yields complex aqueous streams requiring staged treatment.
- Food Processing:Vegetable oil and animal fat recovery applications emphasize hygiene-grade stainless construction.
- Metal Finishing:Coolant and cutting oil separation from aqueous wash waters demands high turndown ratio capability.
Refinery effluent commands the largest installed base; marine discharge applications are climbing the fastest.
Installation:
Site logistics dictate vessel geometry, with offshore constraints rewarding vertical cylindrical designs over horizontal rectangular configurations.
- Offshore Platforms:Weight and footprint restrictions on floating production facilities favor compact centrifugal units with minimal foundation requirements. North Sea operators specify duplex stainless steel for corrosion resistance in salt spray environments.
- Onshore Facilities:Texas and Louisiana refinery expansions deploy large-capacity gravity separators with concrete containment basins and extensive piping galleries.
- Industrial Plants:Brownfield manufacturing sites face space constraints that favor modular skids over field-erected vessels.
- Municipal Treatment Plants:Public procurement emphasizes lowest life-cycle cost over capital expenditure minimization.
Onshore facilities hold the dominant share; offshore platforms are gaining share fastest.
End User:
Technical sophistication and service integration expectations diverge sharply between integrated energy majors and fragmented municipal operators.
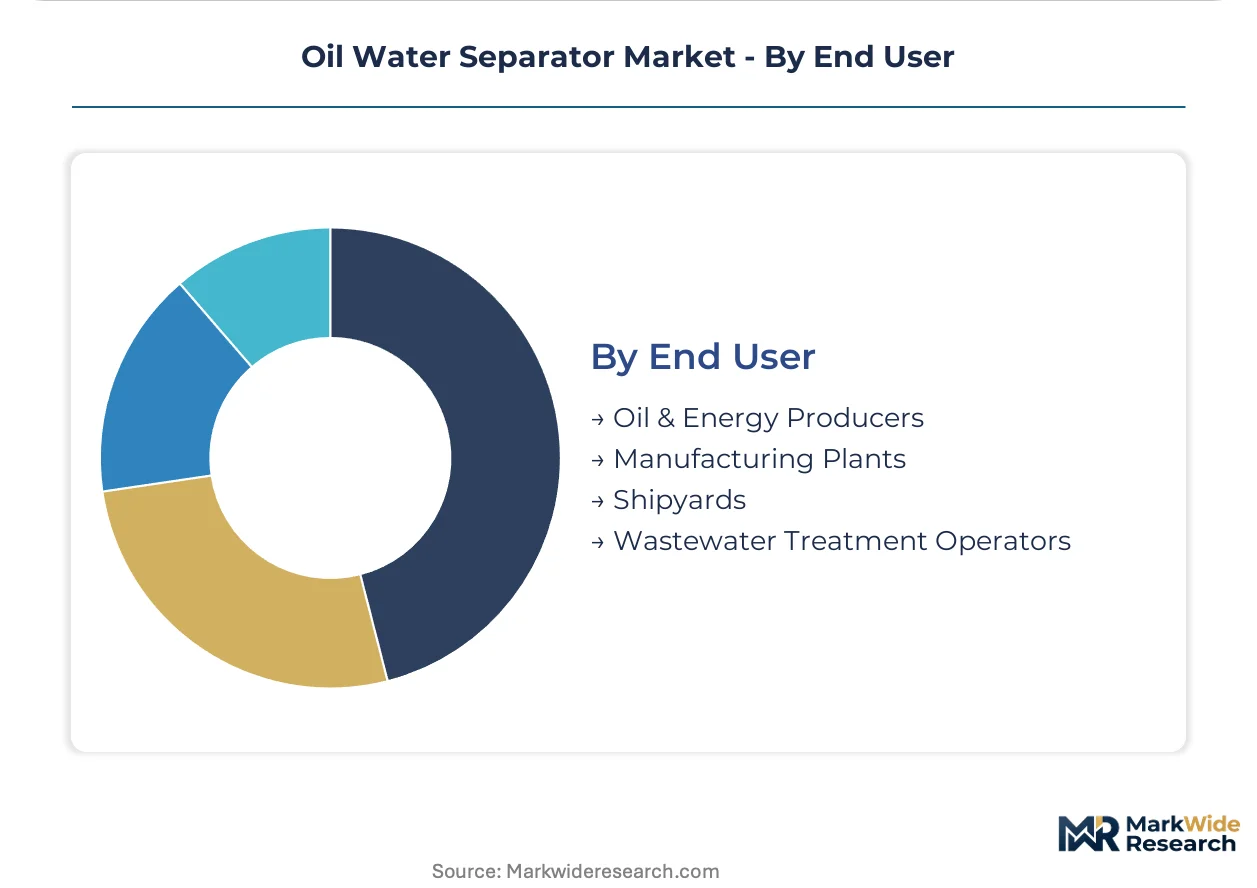
- Oil & Energy Producers:Supermajors and national oil companies specify API-certified separators with comprehensive automation packages. Permian Basin shale operators are expanding produced water treatment capacity with compact flotation units.
- Wastewater Treatment Operators:Municipal authorities unbundle hardware procurement from aftermarket service, creating spot-market competition for cartridge replacement.
- Manufacturing Plants:Automotive and steel mills prioritize compliance documentation over performance optimization.
- Shipyards:Newbuild contracts specify separators as part of integrated engine room packages.
Oil and energy producers account for the majority of capital deployment; wastewater treatment operators are expanding their share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor spanning Texas and Louisiana concentrates the heaviest procurement activity, with refinery expansions and EPA enforcement intersecting to drive separator demand.
United States
Texas and Louisiana host the densest cluster of refinery and petrochemical capacity additions. The US EPA's tightening effluent limitation guidelines under the Clean Water Act mandate oil-in-water discharge thresholds below 15 ppm. The Beaumont-Port Arthur-Orange triangle along the Texas Gulf Coast is seeing accelerated replacement cycles for aging gravity separators with higher-performance coalescing systems.
China
Shandong Province and the Yangtze River Delta industrial belt generate substantial demand from petrochemical complexes and port facilities. The Ministry of Ecology and Environment enforces stricter wastewater discharge standards for petroleum refining operations. Qingdao and Ningbo port authorities are retrofitting marine reception facilities with compliant bilge water treatment systems.
Germany
The Rhine-Ruhr industrial region and Bavarian manufacturing belt sustain steady replacement demand for coalescing media. The ECHA's REACH framework restricts per- and polyfluoroalkyl substances in separator cartridges, forcing reformulation toward silicone-based alternatives. Stuttgart automotive paint shops and Düsseldorf-area steel mills are preemptively accelerating media replacement cycles ahead of 2027 deadlines.
India
Gujarat and Maharashtra industrial corridors present first-mover opportunities as refinery capacity expands. The Central Pollution Control Board is tightening petroleum refinery wastewater standards under revised environmental norms. The Jamnagar refinery complex and Mumbai-Pune manufacturing belt are procuring API-compliant separator trains with integrated automation packages.
Norway
North Sea offshore platforms drive premium demand for compact centrifugal units with corrosion-resistant alloys. The Norwegian Environment Agency enforces strict oil-in-water discharge limits for produced water and drilling fluids. Stavanger and Bergen supply bases are specifying duplex stainless steel separators for floating production facilities facing weight and footprint constraints.
Oil Water Separator Market Key Industry Players
Premium-margin players sit above commodity-margin players across the certification-grade dimension, with API 421-certified refinery systems commanding price multiples over standard municipal units. The vendor base clusters around three strategic archetypes: integrated process technology conglomerates with centrifuge heritage, environmental service specialists bundling hardware with compliance management, and regional fabrication houses serving price-sensitive aftermarket demand. Dominant competitive moves include vertical integration into coalescing media manufacturing and geographic expansion through local fabrication partnerships.
Among European-based environmental technology groups, Veolia exemplifies the integrated service archetype through bundled separator hardware and long-term effluent compliance contracts. Alfa Laval anchors the premium centrifugal tier, leveraging marine heritage for offshore platform specifications. Ecolab occupies a position bridging industrial water treatment and regulatory compliance services. These three represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Alfa Laval |
| Ecolab |
| Veolia |
| GEA Group |
| Sulzer Ltd |
| Parker Hannifin Corporation |
| Wärtsilä Oyj Abp |
| Andritz AG |
| Hydro International |
| Others |
Cost & Logistics Intelligence
Welding-certified fabricators in the US Gulf Coast corridor command wage premiums that compress margins on carbon steel gravity separators while offshore alloy specialists in Norway and Japan sustain pricing power for duplex stainless centrifugal units. Labor-cost differentials between these regional skill pools widen the spread between commodity municipal procurement and premium platform specifications.
Pricing Analysis
Outcome-based contracts tied to guaranteed effluent compliance anchor pricing for integrated service bundles. Pricing stratifies across API 421-certified refinery systems, standard industrial skids, and economy-grade municipal units. Cost compression in the carbon steel tier intensifies because Chinese mill overcapacity floods spot markets. Municipal wastewater authorities exhibit highest price sensitivity; supermajors prioritize uptime guarantees over capital minimization.
Supply Chain Analysis
Corrosion-resistant alloy supply rests on concentrated Nordic and Japanese specialty steel producers. Duplex stainless steel, polypropylene fiber media, and precision bearing assemblies constitute critical input dependencies. Single-source vulnerability for fluoropolymer cartridge chemistry creates exposure to REACH restriction timelines. Distribution runs through authorized fabricator networks for certified systems and direct OEM channels for replacement media.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API certification timelines and REACH chemical restrictions are forcing sub-scale fabricators toward exit or acquisition, consolidating procurement influence among integrated service providers.
For Market Incumbents: Acquire captive coalescing media manufacturing capacity to secure supply continuity ahead of fluoropolymer phase-outs. Deepen automation engineering resources to compress 14-18 month API 421 verification windows. Control aftermarket service revenue through predictive maintenance platform deployment before municipal unbundling fragments traditional contract structures. For New Entrants and Emerging Players: Compact IoT-enabled separator monitoring systems offer technology-first entry into brownfield industrial retrofit demand. India's Gujarat-Maharashtra refinery corridor presents the most penetrable geography given tightening CPCB enforcement and limited incumbent service infrastructure. Pursue local fabrication partnerships to bypass capital-intensive alloy machining capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated environmental service platforms given bundled contract expansion and recurring media replacement revenue streams. Five-to-ten year viability favors operators with in-house REACH-compliant chemistry reformulation capabilities. Monitor ECHA restriction enforcement velocity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coalescing Media Manufacturing | Captures margin pools from cartridge replacement cycles while insulating against REACH supply disruption. |
| Digital Twin Integration with Predictive Maintenance | Enables performance-based service contracts that lock in long-term revenue from Permian Basin shale operators. |
| Local Fabrication Partnerships in India | Positions suppliers for Jamnagar refinery expansion without bearing full capital burden of greenfield facilities. |
| REACH-Compliant Chemistry Reformulation | Preempts 2027 fluoropolymer restrictions and captures accelerated European media replacement demand. |
| Hybrid Coalescing-Flotation System Development | Consolidates separate procurement decisions into single-vessel specifications for North Sea platform operators. |
Research Approach
Independent corroboration across plant engineers at US Gulf Coast refineries, procurement leads at European automotive paint shops, and aftermarket service heads at marine equipment distributors underwrites the qualitative findings. Secondary validation draws from EPA effluent guideline dockets, ECHA REACH restriction proposals, and customs records tracking alloy steel import flows. Bottom-up equipment shipment tallies triangulate against top-down petrochemical capacity expansion announcements.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions modeled include separator type, installation environment, end-user sophistication tier, and regional regulatory enforcement intensity. CAGRs derive from equipment replacement cycle analysis and capacity addition pipelines. Shale produced water treatment train expansion and marine retrofit mandate compliance curves constitute industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA guideline acceleration or ECHA restriction timeline advancement. A small set of named triggers warrants ongoing watch: REACH per- and polyfluoroalkyl substance restriction finalization, US Gulf Coast hurricane disruption to fabrication capacity, and IMO marine discharge standard enforcement variance across flag registries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market