
 Digital Oilfield Services Market | 2026-2036
Digital Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Oilfield Services Market Analysis
Subscription-based predictive maintenance is consolidating around software-defined service bundles that bundle edge analytics with remote diagnostics. Schlumberger Limited leverages its integrated digital platform to anchor deepwater contracts across multiple basins. Halliburton Company competes through specialized drilling optimization modules that sustain higher-margin recurring revenue. Baker Hughes Company differentiates via turbine-to-tip digital twins that extend equipment lifecycle value for production firms.
Digital oilfield services encompass the application of IoT sensors, cloud infrastructure, and artificial intelligence to automate reservoir characterization, production optimization, and equipment reliability across upstream operations. These systems typically process sub-surface telemetry at millisecond latency while integrating SCADA historians with machine learning pipelines to reduce non-productive time. Predictive analytics and artificial intelligence command the fastest expansion as operators prioritize automated well intervention and reservoir simulation accuracy. Cloud computing deployments are maturing fastest among supermajors, though hybrid architectures dominate mid-cap exploration companies seeking data sovereignty. Edge computing represents the emerging margin pool where real-time drilling automation commands premium pricing.
The US EPA enforces methane monitoring mandates that shape sensor procurement standards for Permian and Gulf of Mexico operators. OSHA process safety management requirements drive adoption of integrated control systems for hazardous environment monitoring. The EU Green Deal and F-Gas Regulation are redirecting European offshore investment toward digital leak detection platforms. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting deployment architectures.
Market Dynamics
Integrated digital platforms are compressing decision cycles across upstream operations as operators consolidate vendor relationships around end-to-end automation stacks rather than point solutions.
Growth Catalysts
- EPA Methane Regulations:The US EPA mandates continuous emissions monitoring systems for Permian Basin and Gulf of Mexico facilities, forcing sensor deployment at wellheads and compressor stations.
- Edge Analytics Convergence:Real-time drilling automation combines sub-surface telemetry with machine learning pipelines to reduce non-productive time during well intervention.
- Permian Basin Concentration:Texas and New Mexico operators are expanding integrated platform adoption faster than other North American shale regions due to scale economics.
Market Restraints
- Silicon Supply Concentration:Semiconductor fabrication for ruggedized edge devices concentrates in East Asian foundries, creating procurement vulnerability for sensor OEMs.
- Cloud Latency Limitations:Millisecond-level reservoir simulation requirements exceed public cloud response times, forcing hybrid architecture investments.
- Legacy SCADA Integration Friction:Brownfield sites with 1990s-era historians face protocol translation costs that extend deployment timelines.
Strategic Opportunities
- EU F-Gas Regulation Tailwind:European offshore operators are redirecting capital toward digital leak detection platforms to comply with phased refrigerant restrictions.
- AI-Physics Convergence:Reservoir simulation accuracy improves when neural networks integrate with finite-element models, opening premium pricing for hybrid software modules.
- Subscription Service Channels:Predictive maintenance contracts are unbundling from equipment sales through software-defined service bundles with remote diagnostics.
Industry Challenges
- Petroleum Data Science Talent Scarcity:Upstream automation requires geoscientists with Python and cloud architecture skills that traditional petroleum engineering programs underproduce.
- OSHA Process Safety Certification Timelines:Hazardous environment monitoring systems face extended validation cycles for integrated control system approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Oilfield Services Market |
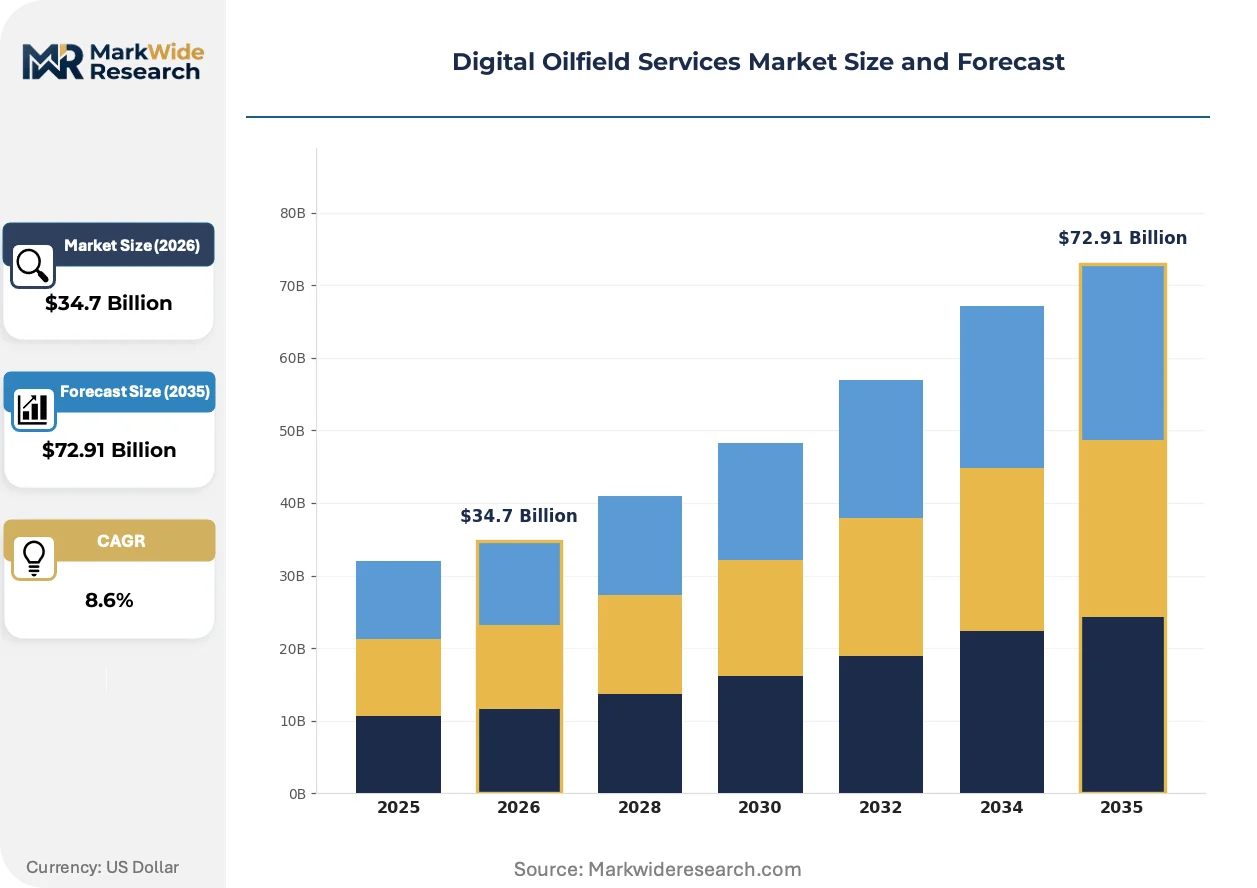
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Management, Asset Optimization, Remote Monitoring, Predictive Analytics Technology: IoT, Cloud Computing, Big Data Analytics, Artificial Intelligence End User: Exploration Companies, Production Firms, Service Providers, Drilling Contractors Deployment: On-Premise, Cloud-Based, Hybrid, Edge |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International plc, NOV Inc., Emerson Electric Co., Pason Systems Corp., National Oilwell Varco, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Oilfield Services Market Emerging Trajectories
Real-time automation is displacing batch-mode reservoir analysis as operators prioritize continuous optimization over episodic engineering studies.
Digital twin technology is automating turbine-to-tip equipment lifecycle management for production firms. Supermajors deploy these virtual replicas across entire offshore platforms while mid-cap operators pilot them on critical rotating machinery first. The technology is automating maintenance scheduling and compressing spare parts inventory requirements.
The EU Green Deal and F-Gas Regulation are redirecting European offshore investment toward methane and refrigerant leak detection platforms. Operators in the North Sea and Norwegian Continental Shelf face accelerated compliance timelines. Digital sensor networks with satellite uplink are replacing manual inspection rounds for platform emissions monitoring.
Service contract unbundling is fragmenting the vendor-customer relationship across upstream operations. Exploration firms now procure edge analytics separately from hardware, forcing equipment manufacturers to defend recurring revenue through software attach rates. This pattern is most visible among Permian Basin independents with lean engineering organizations.
Digital Oilfield Services Market Segmentation
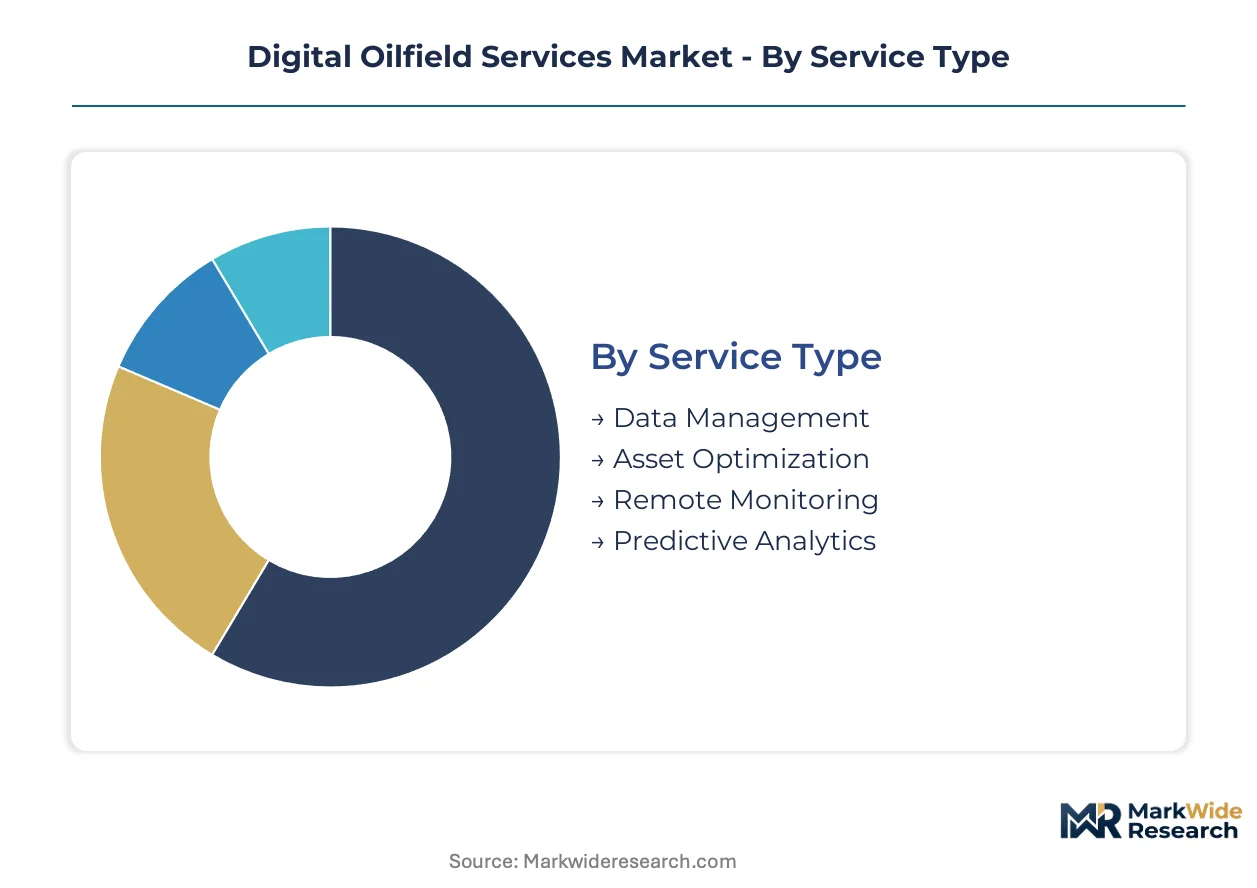
Digital oilfield services fragment across four structural dimensions that determine procurement patterns and vendor selection criteria. Each segmentation axis carries distinct margin profiles and integration requirements that shape operator technology roadmaps.
Service Type:
Supply concentrates around bundled offerings that combine hardware deployment with recurring software layers.
- Predictive Analytics:Neural network models process sub-surface telemetry to forecast equipment failures and optimize intervention timing. Permian Basin operators deploy these systems at wellheads and compressor stations to satisfy EPA methane monitoring mandates while reducing non-productive time.
- Asset Optimization:Reservoir simulation software integrates SCADA historians with machine learning pipelines to automate production scheduling. Supermajors deploy these platforms across entire offshore platforms while mid-cap operators pilot on critical rotating machinery first.
- Data Management:Cloud-native architectures consolidate multi-source telemetry streams from drilling, completion, and production operations.
- Remote Monitoring:Satellite-linked sensor networks replace manual inspection rounds for platform emissions monitoring in the Gulf of Mexico.
Asset optimization absorbs the bulk of installed capacity; predictive analytics is expanding most quickly.
Technology:
Cost tiers separate mature infrastructure deployments from emerging edge-native architectures commanding premium pricing.
- Artificial Intelligence:Reservoir simulation accuracy improves when neural networks integrate with finite-element models, opening premium pricing for hybrid software modules. European offshore operators redirect capital toward AI-enabled leak detection platforms to comply with EU F-Gas Regulation phased refrigerant restrictions.
- IoT:Ruggedized sensor networks at wellheads and compressor stations feed real-time emissions data to regulatory compliance dashboards. Semiconductor fabrication concentration in East Asian foundries creates procurement vulnerability for sensor OEMs serving Permian Basin demand.
- Cloud Computing:Supermajors mature fastest here, though millisecond-level reservoir simulation requirements exceed public cloud response times.
- Big Data Analytics:Batch-mode processing of historical drilling data supports episodic engineering studies.
IoT captures the greatest deployment volume; artificial intelligence climbs the fastest as operators prioritize automated well intervention.
End User:
Customer type determines contract structure, with production firms favoring subscription models and drilling contractors seeking per-well pricing.
- Production Firms:These operators deploy turbine-to-tip digital twins across entire offshore platforms to automate maintenance scheduling and compress spare parts inventory requirements. Texas and New Mexico independents with lean engineering organizations unbundle edge analytics from hardware procurement.
- Exploration Companies:Mid-cap operators pilot digital twin technology on critical rotating machinery first before platform-wide deployment.
- Service Providers:These firms bundle edge analytics with remote diagnostics to defend recurring revenue through software attach rates.
- Drilling Contractors:Real-time drilling automation combines sub-surface telemetry with machine learning pipelines to reduce non-productive time during well intervention.
Production firms dominate current spending; service providers are gaining share fastest through software-defined bundles.
Deployment:
Architecture maturity separates brownfield integration challenges from greenfield edge-native deployments.
- Hybrid:Mid-cap exploration companies favor this architecture to maintain data sovereignty while accessing cloud-scale compute. Brownfield sites with 1990s-era SCADA historians face protocol translation costs that extend deployment timelines.
- Edge:Real-time drilling automation commands premium pricing where millisecond latency requirements exceed public cloud capabilities. This emerging margin pool concentrates in deepwater contracts across multiple basins.
- Cloud-Based:Supermajors mature fastest here, deploying integrated digital platforms across global portfolios.
- On-Premise:Legacy installations persist where regulatory data residency requirements or air-gapped security policies apply.
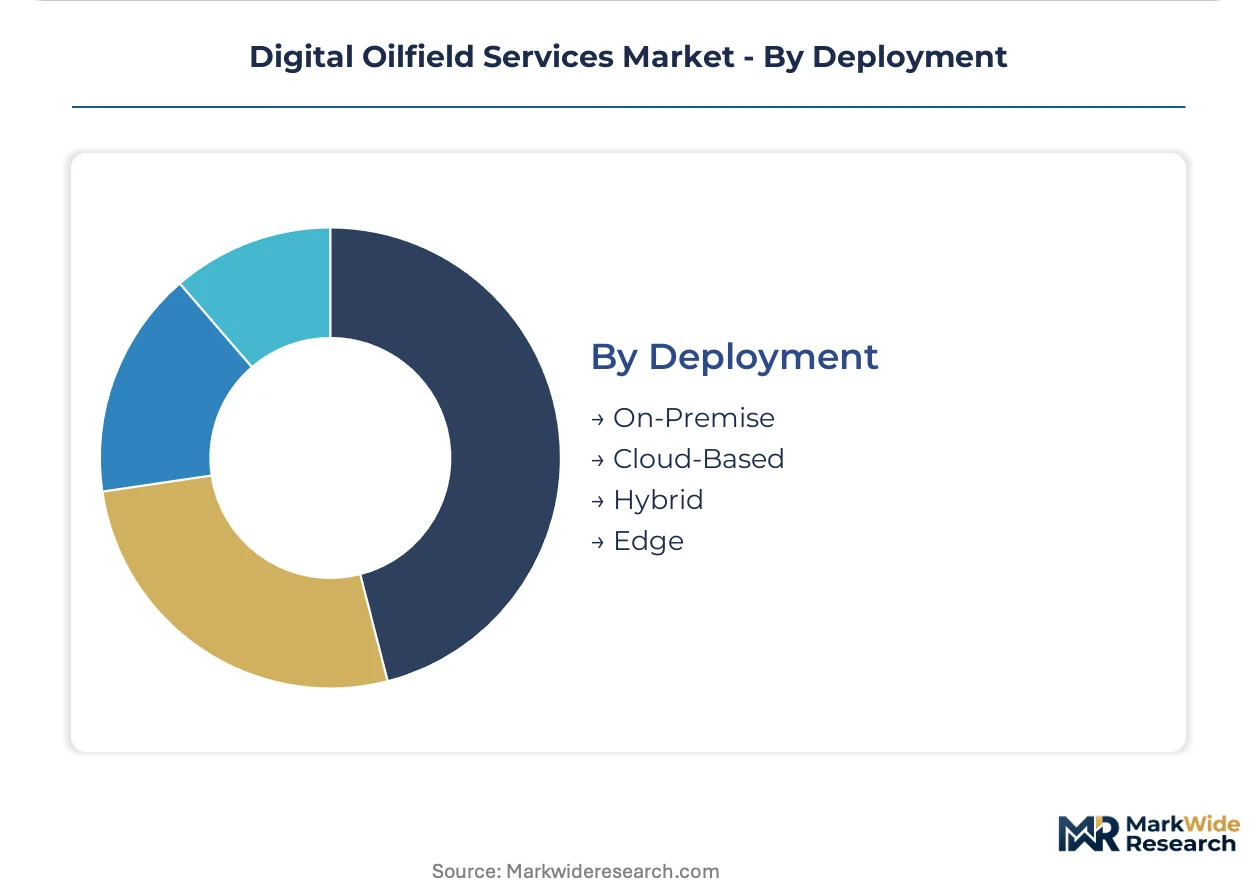
Hybrid architectures anchor current installed base; edge deployment shows the steepest expansion trajectory as operators prioritize real-time automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors upstream digitalization investment through its concentration of supermajor headquarters and oilfield service engineering centers. The Permian Basin drives sensor deployment velocity across Texas and New Mexico. North Sea operators accelerate platform automation under EU regulatory timelines.
United States
EPA methane monitoring mandates force continuous emissions system installation at Permian Basin wellheads and Gulf of Mexico compressor stations. OSHA process safety management requirements drive integrated control system adoption for hazardous environment monitoring. Houston engineering clusters concentrate vendor R&D facilities and supermajor digital transformation programs.
Norway
North Sea electrification targets accelerate offshore platform sensor network deployment for emissions reduction verification. The country's petroleum regulator enforces digital twin integration for subsea infrastructure lifecycle management. Stavanger-based engineering centers pilot turbine-to-tip virtual replicas across Equinor-operated installations.
United Kingdom
North Sea decommissioning timelines drive predictive maintenance adoption to extend productive asset life. The Health and Safety Executive mandates enhanced process safety monitoring for aging offshore infrastructure. Aberdeen technology clusters concentrate leak detection platform development for export to European markets.
Brazil
Pre-salt deepwater development scales integrated digital platform procurement for sub-surface telemetry and drilling automation. ANP production sharing contracts incentivize operational efficiency gains through real-time reservoir optimization. Rio de Janeiro engineering bases anchor Schlumberger and Halliburton Latin American digital service delivery.
Saudi Arabia
Aramco maximum sustainable capacity targets accelerate AI-enabled reservoir simulation deployment across Ghawar and Safaniya fields. The national hydrocarbon regulator mandates digital well intervention systems for gas-oil separation plant optimization. Dhahran technology clusters concentrate domestic engineering talent development for autonomous drilling programs.
Digital Oilfield Services Market Vendor Landscape
Capital-heavy integrated platform providers compete with asset-light specialized analytics firms across upstream technology procurement. The vendor base organizes around three tiers: full-stack automation providers, modular software specialists, and hardware-centric sensor OEMs seeking recurring revenue attachment. Dominant competitive moves include strategic partnerships between supermajors and technology vendors, plus portfolio diversification through predictive maintenance service unbundling.
Within the integrated platform tier, Schlumberger Limited and Halliburton Company exemplify end-to-end automation stack providers. Baker Hughes Company occupies a position emphasizing equipment lifecycle value through digital twin differentiation. These three anchors represent contrasting strategic postures: bundled platform depth, modular optimization specialization, and rotating machinery lifecycle extension.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| NOV Inc. |
| Emerson Electric Co. |
| Pason Systems Corp. |
| National Oilwell Varco |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Edge-native computing architectures for real-time drilling automation are simultaneously compressing cost economics for millisecond-latency processing and concentrating procurement leverage among East Asian semiconductor foundries serving ruggedized sensor OEMs. This dual transformation rewards operators with hybrid deployment flexibility while exposing vendor margins to silicon supply volatility.
Pricing Analysis
Outcome-based pricing tied to non-productive time reduction anchors vendor-customer contracts across upstream automation. Subscription SaaS tiers for predictive maintenance separate premium neural-network modules from standard SCADA integration packages. Price differentiation rests on EPA certification grade for methane monitoring compliance and after-sales diagnostic bundling. Margins are tightening in standard-tier hardware as Permian Basin independents unbundle software procurement from equipment sales. Mid-cap exploration companies exhibit highest price sensitivity due to lean engineering organizations; supermajors prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Saudi Arabia's domestic-content mandates for Aramco vendor qualification are redirecting sensor assembly toward Dhahran technology clusters and away from pure East Asian sourcing. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan for ruggedized edge devices. Raw material dependencies include rare-earth magnets for downhole drilling motors, high-grade silicon carbide substrates, and corrosion-resistant alloys for subsea housings. Single-source vulnerability concentrates in advanced node chip fabrication for AI inference accelerators. Distribution runs through Houston engineering clusters anchoring supermajor procurement and Stavanger-based North Sea logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream digitalization is becoming a vertical-integration race as equipment manufacturers defend recurring revenue through software attach rates and cloud providers deepen control over edge analytics infrastructure.
For Market Incumbents: Anchor deepwater contract renewals through integrated platform bundling that combines sub-surface telemetry with machine learning pipelines. Incumbents should consolidate sensor OEM partnerships to secure semiconductor allocation priority against East Asian supply concentration. Defensive investments in EPA-certified methane monitoring modules will preempt regulatory displacement by specialized emissions analytics entrants.
For New Entrants and Emerging Players: Lean Permian Basin independents with unbundled procurement preferences represent the most penetrable buyer archetype for modular edge analytics vendors. New entrants should target brownfield SCADA integration services where protocol translation costs extend deployment timelines for full-stack providers. A channel partnership strategy with regional drilling contractors offers faster revenue traction than direct supermajor sales cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-physics convergence specialists given accelerating demand for hybrid reservoir simulation modules combining neural networks with finite-element models. Long-term viability favors vendors with demonstrated EPA compliance certification and recurring software revenue exceeding hardware attach rates. The signal to watch is supermajor RFP language shifting from point-solution procurement to end-to-end automation stack requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Schlumberger's bundled digital platform anchors multi-basin deepwater contracts against modular competitors. |
| Backward Integration into Edge Silicon | Halliburton's captive sensor design capabilities reduce vulnerability to Taiwan foundry allocation constraints. |
| Regulatory Certification Investment | Baker Hughes EPA-certified methane monitoring modules capture Permian Basin compliance-driven replacement cycles. |
| Software-Defined Service Unbundling | Weatherford's predictive maintenance subscriptions defend recurring revenue as hardware sales commoditize. |
| Geographic Expansion to Norway | NOV's Stavanger engineering base captures North Sea digital twin deployment under EU F-Gas timelines. |
Methodological Framework
SEC filings from Schlumberger, Halliburton, and Baker Hughes, EPA regulatory dockets for methane monitoring rulemakings, and IHS Markit upstream capital expenditure databases formed the secondary backbone of this analysis. Primary interviews with digital transformation officers at Permian Basin independents, reservoir simulation engineers at supermajors, and procurement leads at Gulf of Mexico drilling contractors validated secondary findings. Bottom-up and top-down triangulation reconciled sensor deployment counts with vendor-reported software revenue segmentation.
Bottom-up modeling of edge device shipments and cloud service subscriptions across deployment architectures, end-user categories, and technology layers anchored the forecast framework. Segmentation dimensions included service type, technology tier, customer archetype, and deployment architecture across the analysis window. CAGRs derived from vendor revenue disclosures and operator capex guidance were stress-tested against regulatory compliance timeline acceleration. Industry-specific inputs incorporated EPA enforcement schedule certainty and EU F-Gas Regulation phase-out milestones.
Revisions become necessary when semiconductor supply disruptions extend sensor OEM delivery timelines or when OSHA process safety certification delays stall integrated control system deployments. Forecasts reflect assumptions regarding regulatory enforcement consistency and supermajor platform consolidation preferences. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Proppant Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Romania Oil and Gas Market