
 Middle-East Enhanced Oil Recovery Market | 2026-2036
Middle-East Enhanced Oil Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Enhanced Oil Recovery Market Foresight
Abu Dhabi National Oil Company's In-Country Value program is shifting procurement rules for EOR service contracts, requiring foreign vendors to establish local manufacturing and engineering centers. Schlumberger leverages its integrated project management model to anchor long-term chemical flooding contracts across UAE and Qatar fields. Halliburton competes through proprietary polymer gel systems that sustain injection profiles in high-temperature carbonate reservoirs. Baker Hughes differentiates via advanced reservoir characterization tools that optimize gas injection patterns in mature Saudi fields.
Middle-East Enhanced Oil Recovery encompasses tertiary extraction techniques deployed after primary depletion and secondary waterflooding, including thermal methods using steam at 150-300°C, miscible gas injection with CO2 or hydrocarbon solvents, chemical flooding with polymer and surfactant formulations, and microbial stimulation using indigenous bacteria to alter rock wettability. Gas Injection technology dominates current installation bases across Saudi Arabia and Qatar due to available sour gas supplies from upstream processing, while Chemical EOR represents the fastest-growing technology segment as polymer flooding pilots expand in Kuwaiti heavy oil fields. Thermal Recovery occupies a mature position limited to shallow heavy oil zones in Oman, where margin pools concentrate around steam generation efficiency and water treatment integration.
Saudi Arabia's Ministry of Energy and Abu Dhabi National Oil Company's local content mandates reshape supplier qualification criteria, while Oman's national oil company enforces field development plans requiring EOR deployment for license renewal. The UAE's Supreme Petroleum Council regulates gas utilization priorities that directly constrain CO2 availability for miscible flooding projects. Stakeholders must monitor how carbon capture integration policies across Gulf national oil companies redefine feedstock economics for gas injection schemes.
Market Dynamics
Gas injection economics across Saudi Arabia and Qatar are rewriting project feasibility calculations as sour gas processing capacity expands and carbon capture integration creates dual-revenue streams for miscible flooding operations.
Growth Catalysts
- Maximum Sustainable Capacity mandates:Saudi Arabia's Ministry of Energy directives compel national oil companies to deploy tertiary recovery methods at mature onshore fields to maintain plateau production rates.
- Polymer flooding pilots:Kuwait Oil Company's heavy oil field trials demonstrate viscosity reduction capabilities that unlock incremental reserves previously classified as uneconomic.
- Carbon utilization frameworks:UAE Supreme Petroleum Council regulations prioritizing CO2 sequestration create captive feedstock supplies for miscible gas injection schemes.
Market Restraints
- Specialized chemical supply concentration:Polymer and surfactant formulations for high-temperature carbonate reservoirs depend on limited European and Asian specialty chemical manufacturers.
- Water treatment integration costs:Produced water handling requirements for thermal recovery methods in Oman's shallow heavy oil zones impose capital intensity thresholds that marginalize smaller field operators.
- Reservoir characterization uncertainty:Heterogeneous carbonate pore structures across UAE and Qatar fields create technical barriers to predicting chemical flood sweep efficiency.
Strategic Opportunities
- Microbial EOR underpenetration:Oman's mature heavy oil fields present untapped potential for indigenous bacteria stimulation programs that alter wettability without thermal energy inputs.
- Local content manufacturing:ADNOC's In-Country Value program mandates create procurement pathways for foreign vendors establishing polymer gel production facilities within UAE industrial zones.
- Gas injection-carbon capture convergence:Kuwait's upstream processing expansion generates sour gas volumes suitable for simultaneous enhanced recovery and emissions reduction credit generation.
Industry Challenges
- Reservoir engineer scarcity:Specialized expertise in chemical flooding design for high-salinity carbonate environments remains concentrated among aging technical cohorts at national oil companies.
- Pilot-to-commercial scaling timelines:Kuwaiti heavy oil polymer projects face multi-year validation periods before field-wide deployment authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Enhanced Oil Recovery Market |
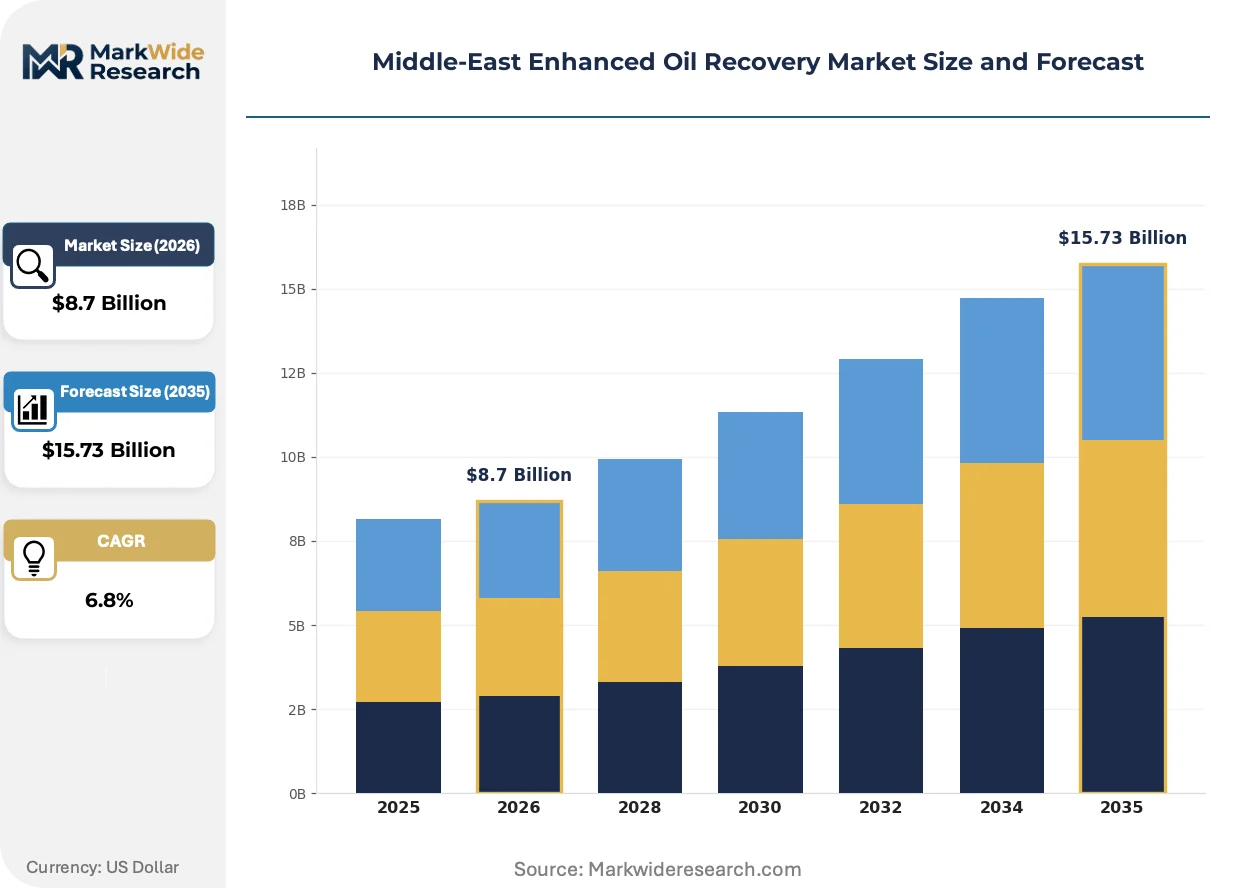
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal Recovery, Gas Injection, Chemical EOR, Microbial EOR End User: Oil Producers, Independent Operators, National Oil Companies, Service Providers Application: Oil Sands, Mature Fields, Offshore Fields, Heavy Oil Recovery Installation: Onshore, Offshore, Floating Platforms, Subsurface |
| Companies Covered | ADNOC, Saudi Aramco, Petroleum Development Oman, Kuwait Oil Company, Dubai Petroleum, QatarEnergy, Halliburton, Schlumberger, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Enhanced Oil Recovery Market Shifts & Advancements
Digital reservoir surveillance and automated injection control systems are compressing response times between production anomalies and operational adjustments across Middle East tertiary recovery operations.
Low-salinity waterflooding preceding chemical injection is rewriting recovery factor assumptions for Saudi Arabia's carbonate reservoirs. Saudi Aramco's laboratory validation programs demonstrate incremental oil mobilization beyond conventional seawater flooding baselines. The technique is enabling polymer flood front stability in fields previously deemed too heterogeneous for chemical EOR economics.
ADNOC's In-Country Value certification requirements now govern service contract eligibility for EOR vendors operating across Abu Dhabi onshore concessions. The framework mandates local engineering centers and manufacturing partnerships as preconditions for pilot project participation. Foreign technology providers are restructuring Middle East organizations to meet procurement gate criteria.
Performance-based chemical supply contracts are displacing traditional unit-price procurement at Kuwait Oil Company heavy oil developments. Vendors assume formulation optimization risk against guaranteed incremental barrel targets. The model concentrates vendor selection among integrated service providers with reservoir characterization and chemical manufacturing capabilities.
Middle-East Enhanced Oil Recovery Market Segmentation
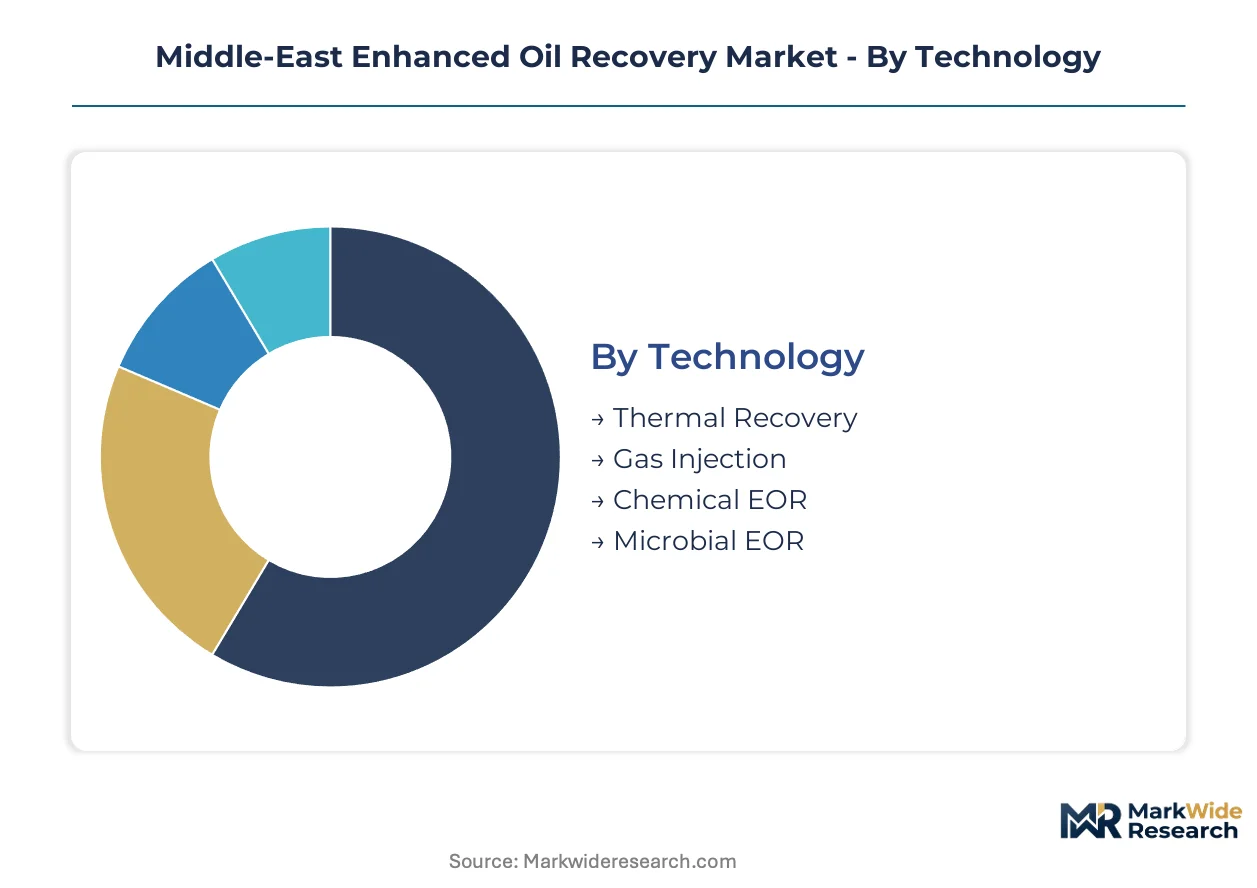
Technology selection in Middle East tertiary recovery hinges on reservoir depth, crude viscosity, and feedstock availability. End-user procurement power and application geology further stratify vendor opportunity windows across the Gulf Cooperation Council.
Technology:
Gas Injection commands the largest installed base, while Chemical EOR carries the steepest expansion trajectory as polymer flooding pilots multiply.
- Gas Injection:Miscible and immiscible flooding using CO2 or hydrocarbon solvents dominates Saudi Arabia and Qatar due to abundant sour gas from upstream processing. ADNOC and Saudi Aramco fields rely on this method for carbonate reservoirs with declining natural pressure.
- Chemical EOR:Polymer and surfactant formulations reduce viscosity in heavy oil zones. Kuwait Oil Company's heavy oil pilots are validating field-wide deployment economics for this segment.
- Thermal Recovery:Steam injection at 150-300°C serves shallow heavy oil zones in Oman where margin pools concentrate around steam generation efficiency.
- Microbial EOR:Indigenous bacteria stimulation alters rock wettability without thermal inputs, presenting underpenetrated potential in Oman's mature heavy oil fields.
Mature deployment sits with Gas Injection. Newer deployment is concentrated in Chemical EOR.
End User:
National oil companies control capital allocation, while service providers absorb execution risk through integrated project management contracts.
- National Oil Companies:Saudi Aramco, ADNOC, Kuwait Oil Company, and QatarEnergy direct EOR strategy through maximum sustainable capacity mandates and local content requirements. Their procurement rules reshape vendor qualification criteria.
- Oil Producers:International oil companies operating under production-sharing contracts face license renewal conditions requiring tertiary recovery deployment in Oman's mature concessions.
- Independent Operators:Smaller field developers in UAE's onshore concessions select modular chemical EOR packages for marginal carbonate reservoirs.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes anchor long-term contracts through performance-based chemical supply agreements and reservoir characterization capabilities.
Capital commitment authority rests with National Oil Companies. Technical execution risk concentrates with Service Providers.
Application:
Reservoir maturity and crude gravity determine method selection, with heavy oil recovery commanding premium chemical formulation costs.
- Mature Fields:Depleted carbonate reservoirs across Saudi Arabia's Ghawar and UAE's onshore concessions require tertiary methods to sustain plateau production rates.
- Heavy Oil Recovery:Kuwait's Ratqa and Oman fields with API gravity below 20 drive polymer flooding demand and thermal recovery pilots.
- Oil Sands:Limited to shallow deposits in Oman where steam-assisted gravity drainage competes with mining economics.
- Offshore Fields:Qatar's North Field and UAE offshore concessions apply gas injection where platform infrastructure supports compression and processing.
Established production bases center on Mature Fields. Incremental reserve growth depends on Heavy Oil Recovery.
Installation:
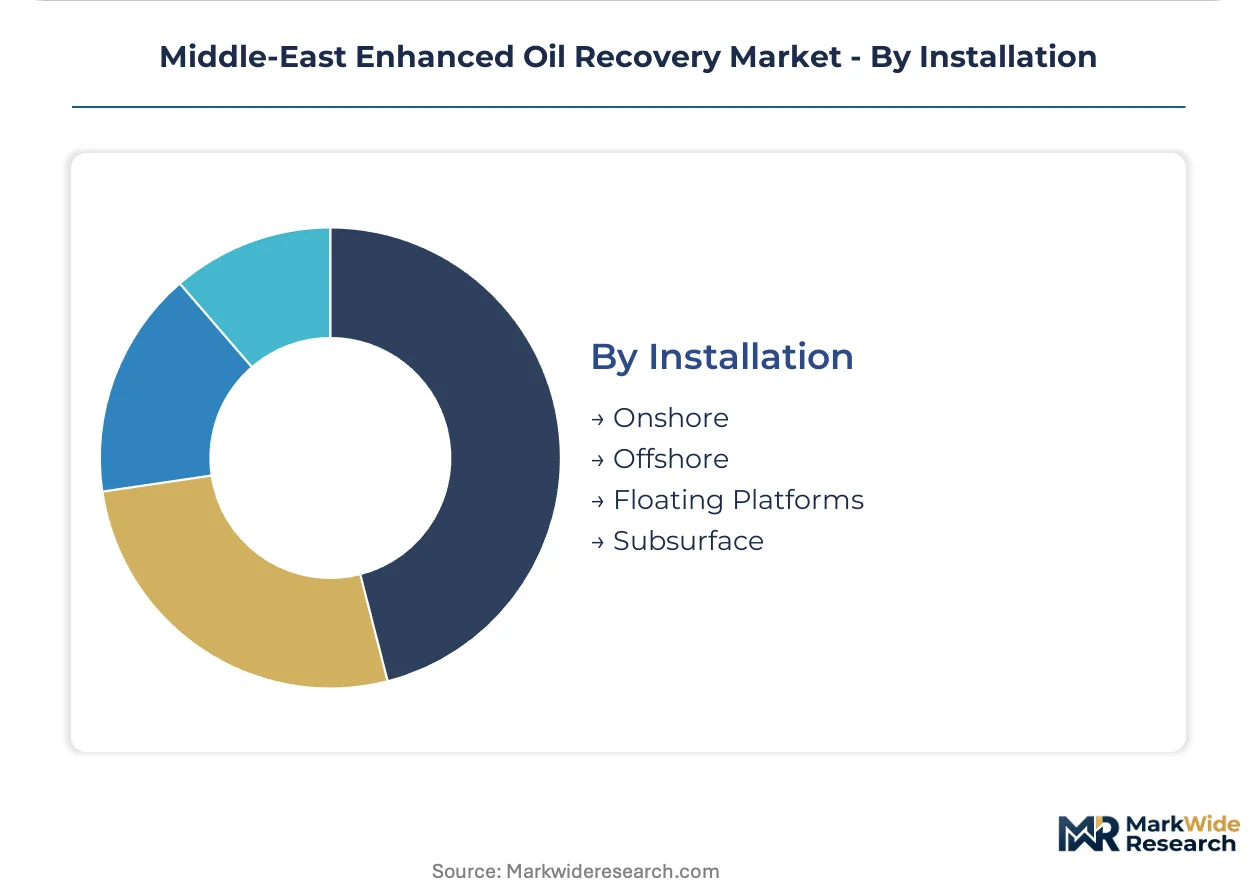
Surface constraints and water depth dictate equipment configuration, with onshore installations offering lowest unit capital intensity.
- Onshore:Saudi Arabia's mature onshore fields and UAE's Bab and Bu Hasa concessions host the majority of chemical flooding pilots and gas injection facilities.
- Offshore:Qatar's North Field and UAE offshore platforms deploy gas injection where pipeline infrastructure connects to onshore processing.
- Subsurface:Intelligent well completions and automated injection control systems enable real-time profile management in heterogeneous carbonate reservoirs.
- Floating Platforms:Limited deployment for early-production systems in UAE offshore concessions awaiting permanent platform installation.
Operational scale favors Onshore. Technical complexity concentrates in Subsurface completions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Khalifa Industrial Zone Abu Dhabi (KIZAD) concentrates polymer formulation manufacturing for EOR chemical supply contracts, anchoring regional procurement gravity for tertiary recovery service providers.
Saudi Arabia
Ghawar and Safaniya mature field depletion drives gas injection capacity expansion. The Ministry of Energy's maximum sustainable capacity directives mandate tertiary recovery deployment at plateauing onshore concessions. Dhahran's Saudi Aramco research complex validates low-salinity waterflooding preceding polymer flood pilots.
United Arab Emirates
ADNOC's Bab and Bu Hasa concessions host chemical flooding pilots targeting heterogeneous carbonate reservoirs. The Supreme Petroleum Council's gas utilization priorities constrain CO2 feedstock allocation for miscible flooding schemes. Ruwais industrial corridor polymer gel production facilities satisfy In-Country Value procurement mandates.
Kuwait
Ratqa heavy oil field viscosity reduction trials validate polymer flooding economics for API gravity below 20 reserves. Kuwait Oil Company's field development plans enforce EOR deployment for license renewal conditions. Ahmadi headquarters directs performance-based chemical supply contract negotiations with integrated service providers.
Qatar
North Field offshore platform infrastructure supports gas injection compression systems for declining pressure carbonate reservoirs. QatarEnergy's sour gas processing expansion generates miscible flooding feedstock volumes. Ras Laffan industrial city anchors carbon capture integration pilots for dual-revenue stream recovery operations.
Oman
Petroleum Development Oman's mature heavy oil zones concentrate thermal recovery steam generation efficiency optimization. License renewal conditions mandate tertiary recovery deployment at depleted concessions. Marmul cluster margin pools compete on water treatment integration capital intensity thresholds.
Middle-East Enhanced Oil Recovery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Middle East tertiary recovery service procurement. National oil companies retain capital allocation authority while integrated project management contracts concentrate execution risk with international service providers. Three archetypes dominate: reservoir characterization specialists, chemical formulation manufacturers, and integrated project managers. Competitive positioning hinges on local content certification attainment and performance-based supply contract structuring.
Among integrated service providers, Schlumberger, Halliburton, and Baker Hughes occupy positions spanning reservoir characterization through chemical supply chain management. These entities exemplify the project-manager archetype that anchors long-term EOR contracts through combined technical and procurement capabilities. Their market presence reflects the procurement rule shifts favoring vendors with established regional engineering centers and manufacturing partnerships.
| Leading Market Players |
|---|
| ADNOC |
| Saudi Aramco |
| Petroleum Development Oman |
| Kuwait Oil Company |
| Dubai Petroleum |
| QatarEnergy |
| Halliburton |
| Schlumberger |
| Baker Hughes |
| Others |
Supply & Pricing Matrix
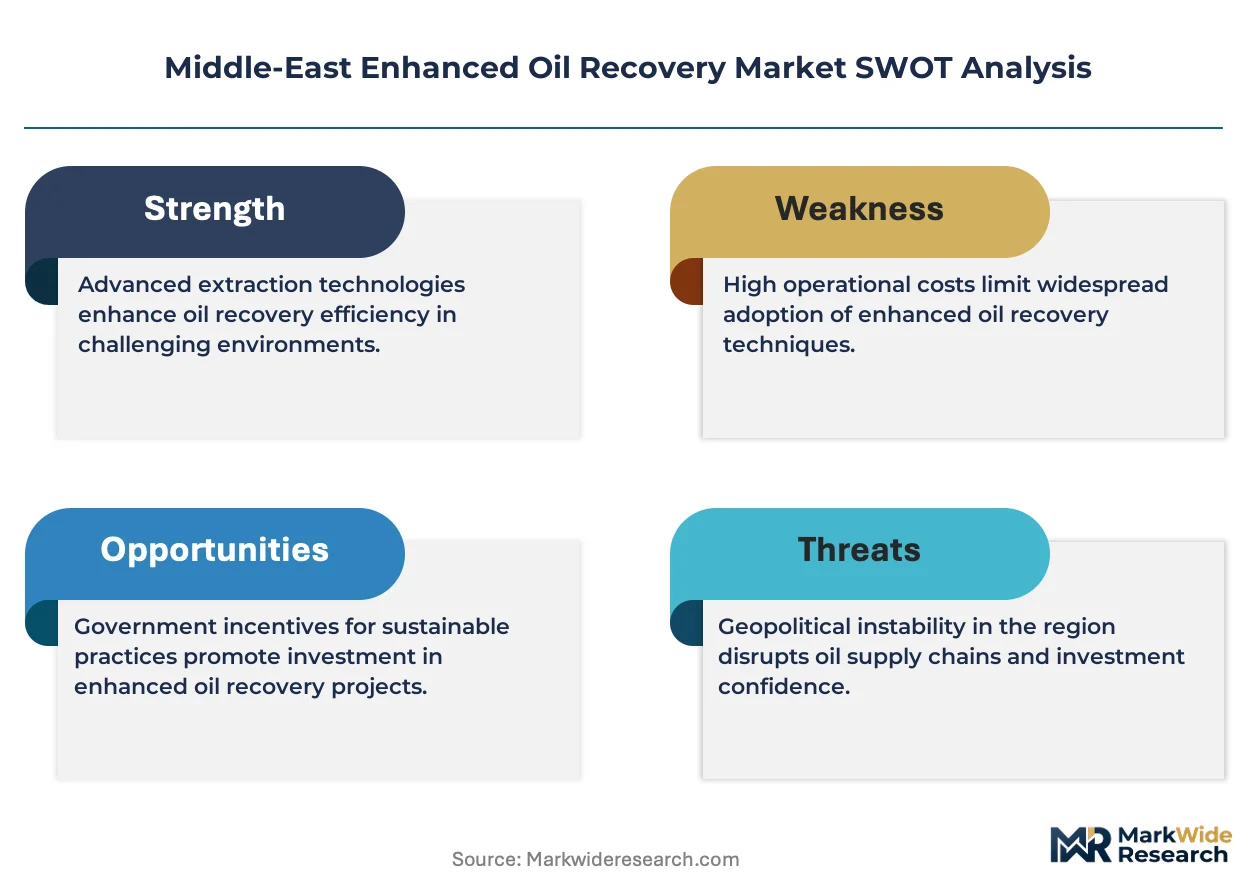
Performance-guaranteed chemical supply contracts versus unit-price procurement bifurcation splits vendor economics across Middle East EOR markets, with polymer formulation premiums commanding 40-60% markups over commodity gel products while ADNOC's In-Country Value mandates force supply chain localization investments that reshape landed cost structures.
Pricing Analysis
Short lead-time premiums for polymer gel systems command 25-35% uplifts over standard delivery windows in Saudi Aramco's Ghawar field tenders. Project-based pricing with performance guarantees dominates Kuwait Oil Company's heavy oil contracts, where vendors absorb formulation optimization risk against incremental barrel targets. Price differentiation hinges on reservoir characterization bundled services and local manufacturing certification under ADNOC's ICV framework. Cost compression in commodity gas injection equipment is intensifying because Chinese compressor manufacturers are qualifying for QatarEnergy's sour gas processing expansion tenders. Independent operators in UAE's marginal carbonate concessions exhibit highest price sensitivity, while Saudi Aramco's integrated project management contracts show lowest sensitivity due to total-cost-of-ownership evaluation criteria.
Supply Chain Analysis
Dual-sourcing requirements for high-temperature polymer formulations mandate European and Asian specialty chemical manufacturer qualification alongside emerging UAE-based production at Ruwais industrial corridor. Geographic supply concentration draws from Germany, Japan, and South Korea for advanced reservoir characterization tools and intelligent well completion systems. Raw material dependencies rest on acrylamide monomer feedstocks, sulfonated polymer precursors, and corrosion-resistant alloy components for high-pressure injection systems. Single-source vulnerability concentrates in proprietary surfactant formulations for high-salinity carbonate reservoirs. Distribution runs through ADNOC's KIZAD polymer formulation hub and Schlumberger's Dhahran integrated project management centers for field deployment logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East EOR market sits in a technology-transition phase as chemical flooding displaces gas injection dominance in heavy oil applications, with polymer pilot-to-commercial scaling timelines compressing from decade-long validation cycles toward five-year deployment windows.
For Market Incumbents: Deepen backward integration into polymer gel manufacturing within Khalifa Industrial Zone Abu Dhabi to secure ADNOC ICV certification eligibility and defend against emerging Chinese equipment suppliers capturing Qatar's sour gas processing expansion tenders. Anchor long-term contracts through bundled reservoir characterization and automated injection control system offerings that raise switching costs for national oil companies.
For New Entrants and Emerging Players: The premium-to-economy service tier gap in Oman's microbial EOR segment offers white-space entry for biotech specialists with indigenous bacteria stimulation capabilities untapped by integrated service providers. Target Petroleum Development Oman's Marmul cluster margin pools with modular water treatment-integrated thermal recovery packages. Pursue joint venture structures with European specialty chemical manufacturers to bypass qualification barriers for high-temperature carbonate reservoir formulations.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated service provider acquisitions by national oil companies seeking captive EOR capabilities. Long-term viability favors vendors with simultaneous polymer manufacturing, reservoir characterization, and digital surveillance competencies. Watch Kuwait Oil Company's Ratqa field polymer flood commercialization authorization as the inflection indicator for chemical EOR segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Manufacturing Certification | ADNOC's ICV mandates require UAE-based polymer gel production for contract eligibility. |
| Performance-Based Supply Contracts | Kuwait Oil Company's guaranteed incremental barrel model transfers formulation risk to vendors. |
| Carbon Capture Integration | QatarEnergy's Ras Laffan pilots create dual-revenue streams for miscible gas injection operations. |
| Digital Reservoir Surveillance | Automated injection control systems compress response times at Saudi Aramco's Ghawar field. |
| Low-Salinity Waterflooding Validation | Saudi Aramco's Dhahran research complex enables polymer flood front stability in heterogeneous carbonates. |
Research Methodology
Independent corroboration across reservoir engineering directors at national oil companies, procurement leads at integrated service providers, and specialty chemical manufacturing executives underwrites the qualitative findings in this analysis. Primary interviews with EOR project managers, carbonate reservoir specialists, and polymer formulation chemists combined with secondary validation from SEC filings of listed service providers, OPEC field development plan disclosures, and Gulf national oil company tender documentation. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume effects from price-mix shifts across technology segments including gas injection, chemical EOR, thermal recovery, and microbial stimulation. Segmentation dimensions model deployment method, reservoir maturity tier, crude gravity classification, and installation configuration. CAGRs derive from polynomial trend fitting of historical deployment data and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporate Saudi Arabia's maximum sustainable capacity mandate compliance schedules and ADNOC's In-Country Value procurement rule implementation timelines.
Inputs from national oil company field development plans and service provider contract disclosure filings were available through the study window; gaps in proprietary reservoir performance data from pilot-to-commercial transitions introduce uncertainty bands around chemical EOR adoption trajectories. Forecasts reflect documented assumptions regarding polymer flooding validation timelines and carbon capture integration policy stability. A model refresh is warranted upon material change in Saudi Arabia's plateau production mandate enforcement or Kuwait Oil Company's heavy oil field authorization decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Drill Collar Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Whipstocks Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Well Cementing Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Rotary Steerable System Market