
 Crude Oil Assay Testing Services Market | 2026-2036
Crude Oil Assay Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Oil Assay Testing Services Market Outlook
North American shale producers is realigning assay testing requirements as Permian Basin output shifts toward lighter, sweeter crude profiles. Core Laboratories leverages its Houston technical center to anchor comprehensive crude characterization programs for major refiners. Intertek Group plc competes through its extended laboratory network across US coastal refining corridors. SGS SA differentiates by controlling specialized heavy crude assay capabilities that serve Canadian oil sands clients.
Crude Oil Assay Testing Services encompass laboratory procedures that determine physical properties, chemical composition, and refining behavior of petroleum feedstocks through parameters including API gravity, sulfur content, distillation curves, and metals concentration. These services enable refiners to optimize crude slate selection, predict product yields, and manage processing constraints before committing to cargo purchases. Quality Testing and Composition Analysis segments dominate current service revenue as traders and refiners require precise molecular characterization for spot-market valuation. Chromatography and Mass Spectrometry methods are gaining service share where complex crude blends demand higher-resolution hydrocarbon fingerprinting than traditional distillation-based approaches.
EPA regulations under the Clean Air Act mandate detailed sulfur and benzene reporting that directly expands assay testing scope for domestic refiners. API standards and ASTM protocols establish the methodological baseline that laboratories must maintain for results to be contractually valid in crude transactions. Stakeholders must monitor how IMO 2020 marine fuel sulfur limits continue to ripple backward into crude valuation models and testing intensity.
Market Dynamics
Refinery crude slate diversification is compressing testing cycles as facilities blend heavier feedstocks with lighter domestic streams, forcing laboratories to validate compatibility matrices faster than traditional turnaround protocols allow.
Growth Catalysts
- EPA Tier 3 sulfur mandates:Gasoline sulfur limits of 10 parts per million require pre-purchase assay verification for every cargo bound for US refiners, expanding mandatory testing scope.
- IMO marine fuel regulations:VLSFO blending complexity demands precise crude characterization to predict cutter stock requirements and sulfur equilibrium in finished bunker fuels.
- Permian Basin output shifts:Lighter API gravity profiles from West Texas drilling require updated distillation curve databases that legacy assay libraries cannot reference accurately.
Market Restraints
- Specialized consumables volatility:High-purity chromatography columns and certified reference standards for metals analysis face supply bottlenecks from limited ISO 17034-accredited producers.
- Geographic concentration risk:Gulf Coast hurricanes disrupt Houston and Corpus Christi laboratory operations, creating regional testing backlogs that cannot be absorbed by inland facilities.
- Distillation method obsolescence:ASTM D2892 procedures require large sample volumes and extended run times that conflict with spot-market decision windows.
Strategic Opportunities
- Canadian oil sands expansion:Heavy crude upgraders in Alberta require dedicated metals and Conradson carbon testing capacity that generalist laboratories underserve.
- Digital assay platforms:Cloud-based crude property databases enable traders to access historical characterization data without physical sample submission.
- Biocrude integration:Co-processing renewable feedstocks with petroleum streams creates demand for oxygenate and nitrogen compound quantification beyond standard hydrocarbon panels.
Industry Challenges
- Mass spectrometry specialist scarcity:Interpretation of high-resolution hydrocarbon fingerprints requires chemists with petroleum systems biology training that university programs rarely produce.
- API standard revision lag:New crude blends from stacked pay zones lack established ASTM protocols, forcing laboratories to defend proprietary methods during contract negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Oil Assay Testing Services Market |
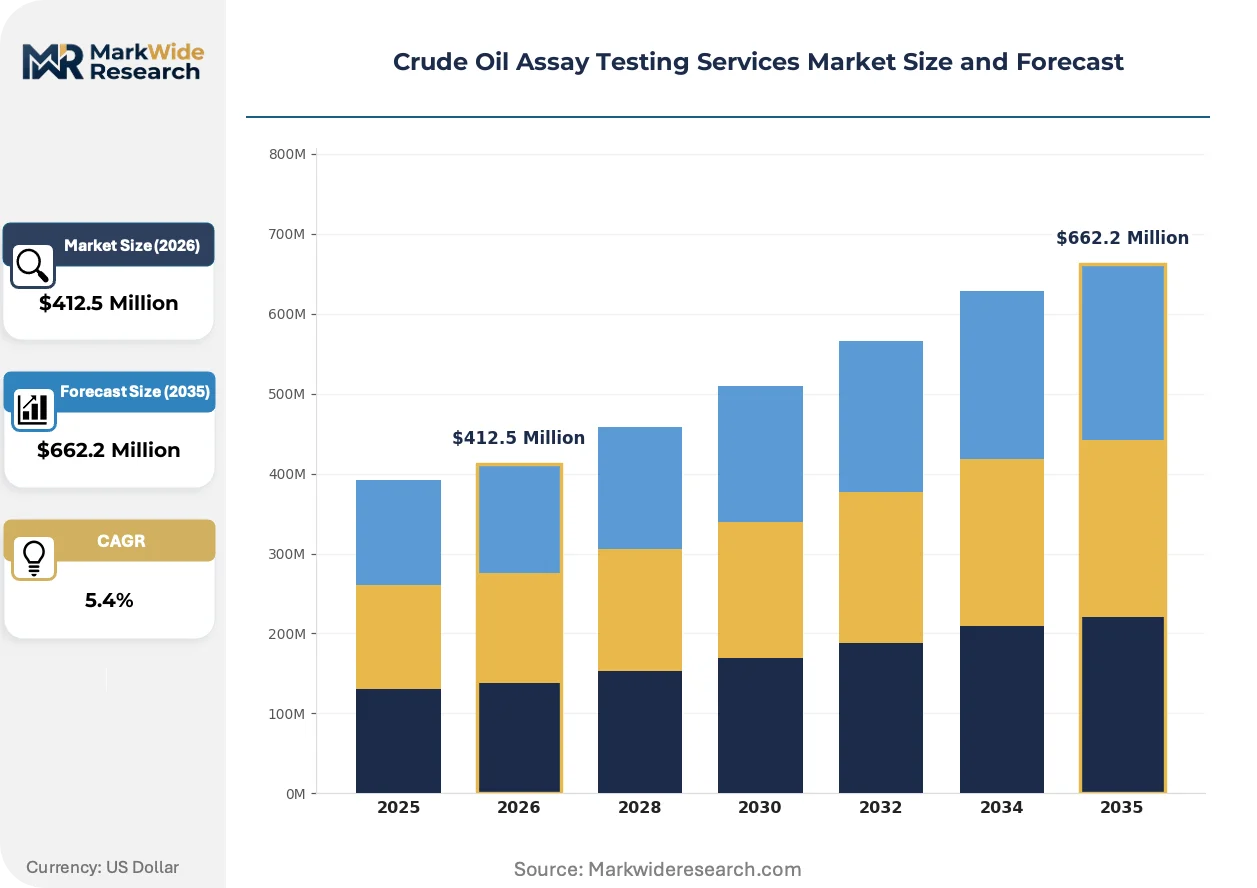
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Testing, Composition Analysis, Performance Evaluation, Certification End User: Refineries, Oilfield Services, Petrochemical Companies, Traders Sample Type: Crude Oil, Feedstock, By-products, Blends Testing Method: Spectroscopy, Chromatography, Mass Spectrometry, Gravity Testing |
| Companies Covered | Core Laboratories, AmSpec, Intertek Group plc, FOI Laboratories, Agilent Technologies, Bureau Veritas, ALS Limited, Akshar Analytical Laboratory & Research Centre, SGS SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Oil Assay Testing Services Market Strategic Shifts
Chromatographic resolution advances and regulatory sulfur tracking are redefining what constitutes acceptable crude characterization depth, with digital integration now separating premium laboratories from commodity testing providers.
Two-dimensional gas chromatography paired with time-of-flight mass spectrometry is rewriting the resolution standards for complex crude fingerprints. Integrated refiners in the US Gulf Coast are adopting these systems to distinguish chemically similar crude grades that traditional boiling-point methods conflate. The technology is compressing the value of legacy distillation-based laboratories that cannot resolve saturates from aromatics at the molecular level.
REACH chemical registration requirements in Europe are extending disclosure obligations to crude-derived process oils and lubricant base stocks. Refiners exporting to EU markets must now document polycyclic aromatic hydrocarbon content through standardized IP 346 methods. This regulatory layer is diverting testing volume toward laboratories with dual EPA-REACH accreditation capabilities.
Spot-market traders are unbundling assay testing from long-term laboratory contracts, instead purchasing single-cargo characterization through digital procurement platforms. This behavioral shift is fragmenting revenue concentration among incumbent service providers. The disintermediation is most visible in Texas, where midstream operators now compare real-time quotes from five or more laboratories before pipeline injection decisions.
Crude Oil Assay Testing Services Market Segmentation
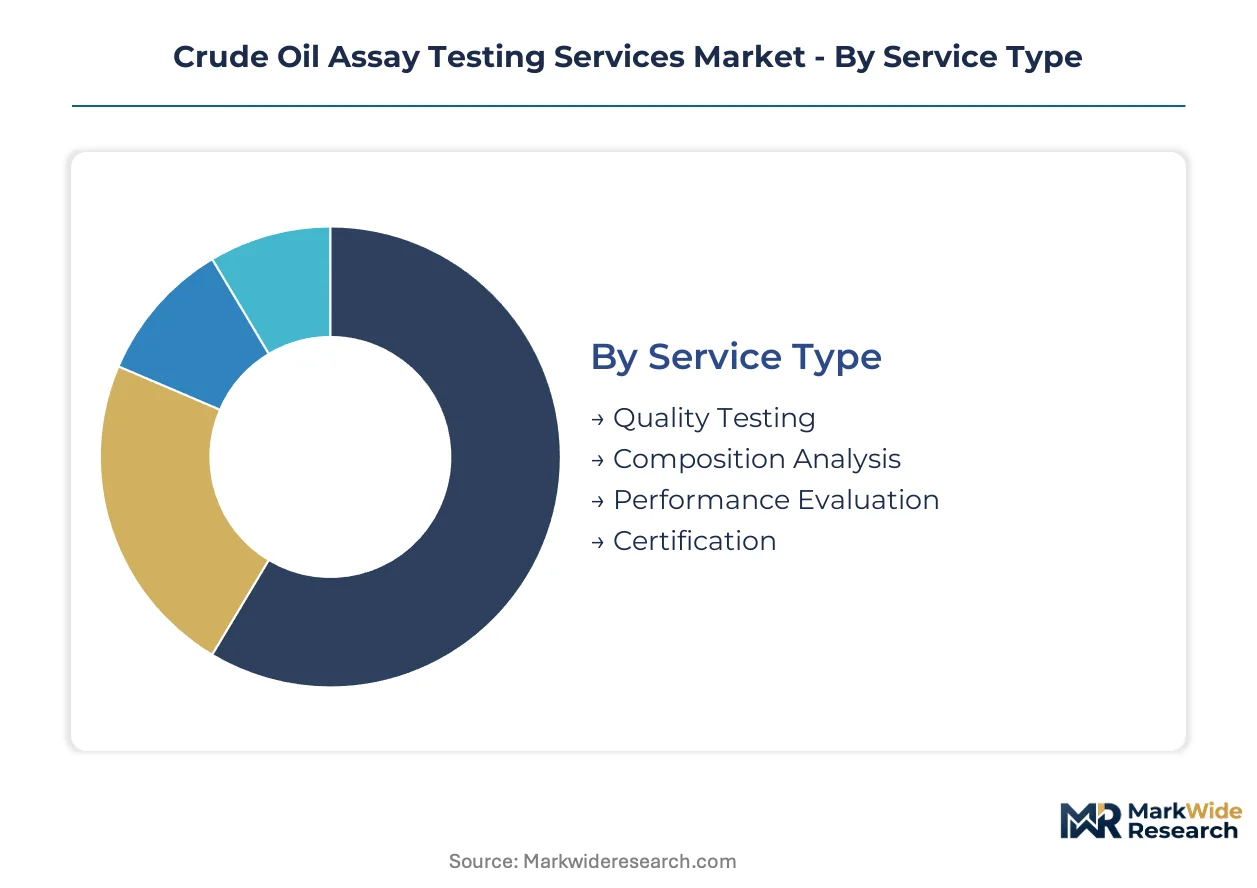
Crude oil assay testing services fragment across service type, end user, sample origin, and analytical methodology. Each dimension shapes procurement patterns and laboratory capability investments differently.
Service Type:
Refinery procurement teams prioritize service tiers based on cargo value and processing complexity, with sulfur verification commanding premium pricing over basic certification.
- Quality Testing:Determines API gravity, sulfur content, pour point, and basic physical properties that traders use for initial cargo valuation. US Gulf Coast refineries contract these services on per-cargo spot terms before committing to heavy sour crude purchases from Latin American suppliers.
- Composition Analysis:Delivers molecular-level characterization through hydrocarbon group-type separation and metals quantification. Integrated refiners in Texas and Louisiana require these panels for compatibility testing when blending domestic light sweet crudes with imported heavy feedstocks.
- Performance Evaluation:Predicts product yields and processing constraints through simulated distillation and pilot-scale cracking assessments.
- Certification:Generates documentation for regulatory compliance and custody transfer under ASTM and API protocols.
Quality Testing leads on scale; Composition Analysis leads on momentum.
End User:
Customer sophistication varies sharply, with integrated refiners demanding full analytical suites while traders minimize testing scope to accelerate deal velocity.
- Refineries:Drive the majority of contract laboratory revenue through annual service agreements covering crude slate optimization and pre-purchase verification. Complex coastal facilities in Texas require continuous metals monitoring for catalyst protection in hydroprocessing units.
- Traders:Purchase rapid-turnaround spot testing to validate cargo specifications before closing arbitrage positions. Houston-based commodity houses now source single-assay quotes through digital procurement platforms rather than maintaining exclusive laboratory relationships.
- Oilfield Services:Require reservoir fluid characterization for production allocation and enhanced recovery design.
- Petrochemical Companies:Focus on naphtha and gas oil fraction analysis for steam cracker feedstock selection.
Refineries dominate absolute volume; Traders are expanding most quickly.
Sample Type:
Sample origin determines testing protocol complexity, with blended streams requiring compatibility matrices that single-origin crudes do not.
- Crude Oil:Unprocessed petroleum requiring full assay panels from exploration wellheads through export terminals. Permian Basin producers submit West Texas Intermediate samples for updated distillation curve databases as drilling shifts toward lighter zones.
- Blends:Intentionally mixed streams from pipeline injection points or storage commingling operations. Midstream operators in Louisiana mandate pre-blend compatibility testing to prevent asphaltene precipitation and pipeline fouling.
- Feedstock:Intermediate streams destined for specific refinery process units.
- By-products:Residual streams and waste oils requiring characterization for disposal or reprocessing pathways.
Crude Oil anchors revenue concentration; Blends show steepest expansion trajectory.
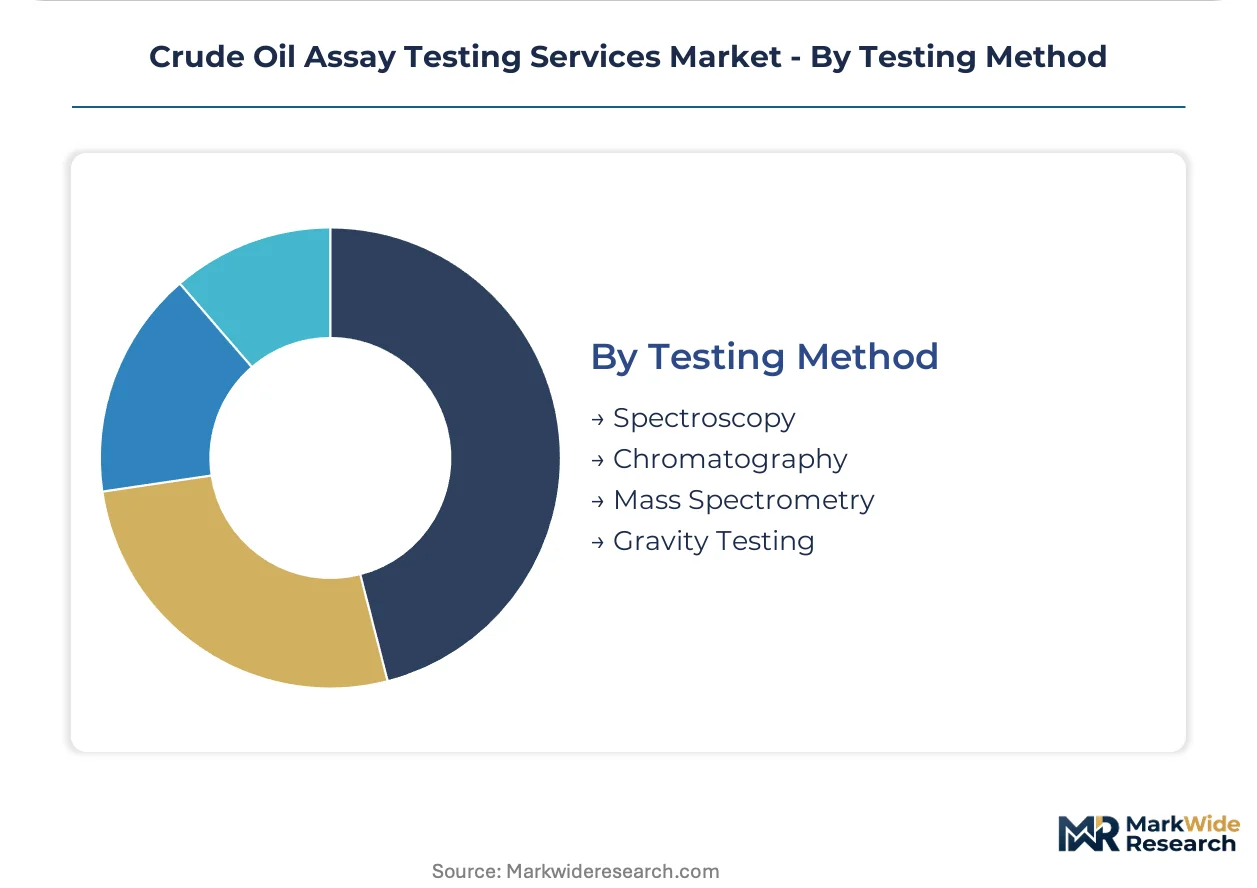
Testing Method:
Laboratory capital allocation tilts toward resolution capabilities that distinguish chemically similar crude grades for spot-market valuation.
- Chromatography:Separates hydrocarbon fractions through gas and liquid phase systems to quantify saturates, aromatics, resins, and asphaltenes. Two-dimensional gas chromatography paired with time-of-flight detection is displacing legacy distillation methods in US Gulf Coast facilities seeking molecular fingerprinting for complex blends.
- Mass Spectrometry:Identifies individual hydrocarbon species through high-resolution molecular weight determination. Specialist chemists with petroleum systems biology training operate these systems for integrated refiners distinguishing Permian Basin grades with similar boiling curves but divergent paraffin content.
- Spectroscopy:Delivers rapid elemental analysis for sulfur and metals screening at lower capital intensity.
- Gravity Testing:Measures API gravity through hydrometer or digital density methods as a baseline physical property.
Chromatography leads on installed base; Mass Spectrometry gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where refiners source assay validation, as sulfur-compliance costs diverge sharply between jurisdictions with Tier 3-equivalent mandates and those with legacy standards. Laboratories in low-regulation zones attract spot-testing volume from traders seeking faster turnaround, while integrated refiners in stringent markets lock in multi-year service contracts.
United States
EPA Tier 3 gasoline sulfur limits and evolving IMO marine fuel rules are compressing testing cycles for Gulf Coast refineries blending heavier Latin American feedstocks with domestic light sweet streams. Houston and Corpus Christi host the densest laboratory clusters, where Core Laboratories and Intertek Group plc anchor comprehensive characterization programs for major refiners.
Canada
Alberta oil sands upgraders require dedicated metals and Conradson carbon testing capacity that generalist laboratories underserve, creating procurement bottlenecks for heavy crude producers. The country's national energy regulator mandates detailed compositional reporting for pipeline exports to US refineries. Calgary and Edmonton house specialized facilities serving Suncor and Canadian Natural Resources.
Brazil
Pre-salt crude development is expanding assay demand for ultra-deepwater production characterization before floating production storage and offloading vessel commissioning. ANVISA chemical registration requirements extend disclosure obligations to crude-derived process oils bound for pharmaceutical applications. Rio de Janeiro laboratories serve Petrobras and international operators in the Santos Basin.
Saudi Arabia
Saudi Aramco's crude slate diversification into heavier grades is forcing laboratories to validate compatibility matrices for Asian refinery customers blending Kingdom exports with domestic streams. The Saudi Food and Drug Authority and national standards body enforce metals and sulfur documentation for refined product exports. Dhahran and Jubail clusters specialize in high-throughput certification for term-contract cargoes.
Germany
REACH chemical registration requirements are extending disclosure obligations to crude-derived process oils and lubricant base stocks exported to EU markets. Refiners must document polycyclic aromatic hydrocarbon content through standardized IP 346 methods. Hamburg and Rotterdam-adjacent laboratories leverage dual EPA-REACH accreditation to capture transshipment testing volume.
Crude Oil Assay Testing Services Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital assay platforms and biocrude integration capabilities. The market structures around three tiers: integrated multinational laboratories with coastal refining corridor presence, regional specialists in heavy crude or oil sands geographies, and technology-forward players investing in chromatography resolution advances. Dominant competitive moves include strategic partnerships with midstream operators for pre-pipeline injection testing and portfolio diversification into renewable feedstock characterization.
Within the integrated multinational tier, Core Laboratories, Intertek Group plc, and SGS SA exemplify contrasting geographic and technical specializations. Core Laboratories leverages its Houston technical center to anchor comprehensive crude characterization programs for US Gulf Coast refiners. Intertek Group plc competes through its extended laboratory network across coastal refining corridors. SGS SA differentiates by controlling specialized heavy crude assay capabilities that serve Canadian oil sands clients. These three represent how scale, location, and technical depth create defensible positioning against commodity testing providers.
| Leading Market Players |
|---|
| Core Laboratories |
| AmSpec |
| Intertek Group plc |
| FOI Laboratories |
| Agilent Technologies |
| Bureau Veritas |
| ALS Limited |
| Akshar Analytical Laboratory & Research Centre |
| SGS SA |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EPA-REACH dual-accredited laboratories and commodity distillation providers manifests in both pricing power and supply chain resilience. Premium-tier facilities command multi-year service contracts from integrated refiners while spot-market traders fragment procurement across digital platforms, compressing margins for generalist operators.
Pricing Analysis
Distributor margins on chromatography consumables and certified reference standards absorb 15-25% of laboratory operating costs before end-user pricing. Three-tier pricing structure across premium, standard, and economy levels separates molecular fingerprinting services from basic API gravity certification, with sulfur verification panels occupying the mid-tier. Pricing pressure stems from spot-market traders unbundling assays from long-term contracts and soliciting real-time quotes through procurement platforms. Traders exhibit highest price sensitivity due to cargo velocity requirements, while integrated refiners prioritize technical depth over per-sample cost.
Supply Chain Analysis
Dual-sourcing requirements for high-purity chromatography columns and ISO 17034-accredited reference standards force laboratories to qualify multiple suppliers despite limited accredited producers. Geographic supply concentration centers on Germany, Japan, and the United States for precision instrumentation, while helium and high-purity solvents draw from Qatar, Algeria, and domestic extraction. Single-source vulnerability persists for time-of-flight mass spectrometry components sourced from specialized German and Japanese manufacturers. Distribution runs through Houston and Corpus Christi laboratory clusters serving Gulf Coast refining corridors, with inland facilities unable to absorb hurricane-related disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in digital assay platforms and biocrude integration capabilities, as automation reduces per-sample labor costs while renewable feedstock characterization commands premium pricing.
For Market Incumbents: Cement defensible positioning through backward integration into chromatography consumables production and captive helium recovery systems. Core Laboratories and Intertek Group plc should expand metals testing capacity in Alberta to capture Canadian oil sands volume currently underserved by generalist laboratories. Digital platform investments must accelerate to match spot-market trader procurement behavior. For New Entrants and Emerging Players: Begin with biocrude co-processing characterization services where oxygenate and nitrogen compound quantification exceeds standard hydrocarbon panels. The most penetrable segment lies in Permian Basin light sweet crude distillation curve databases, as legacy assay libraries misreference newer drilling zones. A direct-to-trader digital procurement interface bypasses incumbent laboratory relationship advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized heavy crude assay providers serving Canadian oil sands and pre-salt Brazilian development. Long-term viability favors laboratories with dual EPA-REACH accreditation positioning for EU export documentation requirements. Watch for inflection when IMO marine fuel regulations tighten cutter stock specification protocols, forcing sulfur equilibrium testing intensity higher.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Assay Platform Development | Cloud-based crude property databases enable traders to access historical characterization without physical sample submission. |
| Biocrude Integration Capability | Co-processing renewable feedstocks creates demand for oxygenate quantification beyond standard hydrocarbon panels. |
| Canadian Oil Sands Expansion | Alberta upgraders require dedicated metals and Conradson carbon testing capacity that generalist laboratories underserve. |
| Chromatography Resolution Advancement | Two-dimensional gas chromatography paired with time-of-flight detection displaces legacy distillation methods in Gulf Coast facilities. |
| Dual Accreditation Investment | Laboratories with EPA-REACH capabilities capture transshipment testing volume for EU-bound crude-derived process oils. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery laboratory managers, crude traders, chromatography equipment specialists, and regulatory compliance officers with secondary validation. Secondary sources included EPA enforcement databases, ASTM protocol revision records, IMO marine fuel implementation guidelines, and customs trade data on chromatography instrument imports. Bottom-up service revenue estimates and top-down crude throughput projections were triangulated to anchor market sizing.
Historical reference periods spanning pre-IMO 2020 implementation through current Tier 3 enforcement established baseline testing intensity patterns across the projection horizon. Segmentation modeling incorporated service type tiers, end-user sophistication levels, sample origin complexity, and analytical methodology resolution capabilities. CAGRs were derived from regression analysis against crude slate diversification indices and regulatory compliance cost trajectories. Forecast inputs included Permian Basin API gravity shift timelines and Canadian oil sands production expansion schedules.
Several conditions sit outside the modeled scope, including abrupt EPA standard revisions, Gulf Coast hurricane frequency exceeding historical patterns, and breakthrough spectroscopy technologies displacing chromatography entirely. Forecasts reflect assumptions about regulatory enforcement continuity and laboratory accreditation maintenance rates. Deviation in IMO marine fuel sulfur limit stringency or biocrude co-processing adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Copper Mining Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Canada Oil and Gas Upstream Market