
 Frac Services Market | 2026-2036
Frac Services Market Size, Share, and Industry Trends Forecast 2026-2036
Frac Services Market Analysis
Buyer concentration among independent shale operators is shifting as private equity-backed producers consolidate acreage positions while majors divest non-core assets. Halliburton leverages its integrated well construction portfolio to capture bundled completion contracts. Liberty Oilfield Services anchors its position through electric frac fleet deployment and sand mine vertical integration. Schlumberger competes via digital frac design platforms that optimize stage-level proppant placement.
Frac services encompass the engineered delivery of high-pressure fluid systems to create conductive fracture networks in hydrocarbon-bearing formations, typically operating at surface pressures exceeding 10,000 psi with proppant loads of 1,500-3,000 pounds per lateral foot. Hydraulic fracturing dominates revenue contribution due to its centrality in unconventional resource development, while gel-based and hybrid fluid systems command premium pricing in high-temperature basins where crosslinked polymer stability determines EUR outcomes. Acidizing maintains steady demand in carbonate-rich plays where matrix stimulation bypasses formation damage without proppant placement.
The EPA enforces methane performance standards under Clean Air Act Section 111 that mandate leak detection and repair protocols at well sites, while OSHA regulates silica exposure limits during proppant handling operations. State regulators in Texas and New Mexico impose groundwater protection rules through casing and cementing requirements that dictate completion design parameters. Stakeholders must weigh capital allocation between diesel-to-electric fleet conversion and next-generation low-emission frac technologies as regulatory thresholds tighten.
Market Dynamics
Electric frac fleet conversion is compressing diesel demand across the Permian Basin as operators face tightening EPA methane performance standards under Clean Air Act Section 111. Capital allocation now pivots between emission-reduction technologies and traditional horsepower expansion.
Growth Catalysts
- EPA Methane Rules:Leak detection and repair mandates under Section 111 are forcing equipment upgrades that sustain service demand through retrofit cycles.
- Pad Drilling Intensification:Multi-well zipper fracs in Texas are extending lateral lengths and proppant loads per wellbore, driving recurring fleet utilization.
- Proppant Handling Automation:Silica exposure limits enforced by OSHA are accelerating robotic transfer system deployment at well sites.
Market Restraints
- Proppant Supply Concentration:Northern White sand dominance from Wisconsin and Minnesota mines creates logistics vulnerability to rail bottlenecks.
- Diesel Price Volatility:Fuel represents 35-45% of variable operating costs for conventional fleets, compressing margin predictability.
- Groundwater Protection Friction:State-level casing and cementing requirements in New Mexico add nonproductive time to completion schedules.
Strategic Opportunities
- Appalachian Basin Expansion:Marcellus and Utica operators are adopting higher-stage counts per well, opening underpenetrated service corridors.
- Carbon Capture Integration:Post-combustion capture systems at turbine-powered frac sites align with emerging state emission credit frameworks.
- Real-time Diagnostics Convergence:Fiber-optic distributed acoustic sensing combined with pressure transient analysis enables stage-level optimization.
Industry Challenges
- Electrician and Controls Technician Scarcity:Grid-connected fleet deployment outpaces qualified personnel supply for high-voltage system maintenance.
- Dual Certification Complexity:API Q2 and ISO 9001 compliance timelines for new sand mine acquisitions extend integration periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frac Services Market |
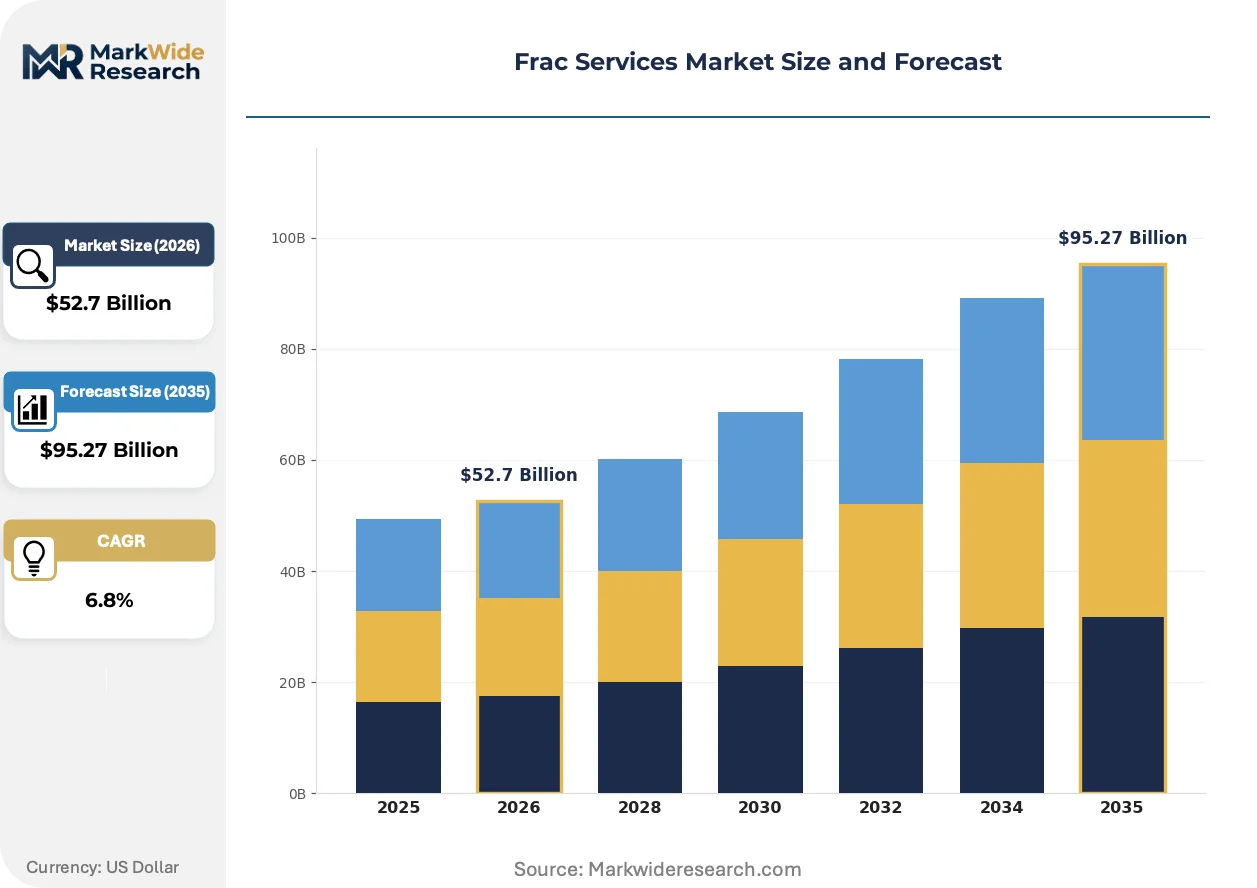
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hydraulic Fracturing, Acidizing, Cementing, Stimulation Technology: Water-Based, Gel-Based, Foam-Based, Hybrid Systems End User: Independent Operators, Majors, Service Companies, Oilfield Contractors Application: Onshore, Offshore, Conventional, Unconventional |
| Companies Covered | Liberty Oilfield Services, Trican Well Service, Halliburton, Profrac Holding Corp., Weatherford, Schlumberger, Calfrac Well Services, Patterson-UTI Energy, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frac Services Market Emerging Trajectories
Digital frac design platforms are rewiring how operators optimize stage-level proppant placement, compressing the engineering-to-execution cycle. Three developments are defining this transition.
Electric turbine drive systems are absorbing market share from conventional diesel-powered frac pumps across high-activity basins. Permian operators with sustained pad drilling programs are deploying these fleets at scale to secure emission reduction credits. The technology is absorbing capital that previously flowed to Tier 4 final diesel engine upgrades, reshaping manufacturer order books.
EPA enforcement of methane performance standards under Clean Air Act Section 111 is mandating optical gas imaging surveys and pneumatic controller replacements at well sites. This regulatory pressure is extending service contracts to include continuous monitoring hardware installation. Completion providers in Texas and New Mexico are bundling LDAR protocols into integrated packages to maintain contract renewals.
Zipper frac sequencing is altering how independent shale operators schedule crew rotations and equipment redeployment. Multi-well pad development in the Delaware Basin is replacing single-well contracts with 6-12 month dedicated crew arrangements. This pattern is most pronounced among private equity-backed producers consolidating contiguous acreage positions in Reeves and Loving counties.
Frac Services Market Segmentation
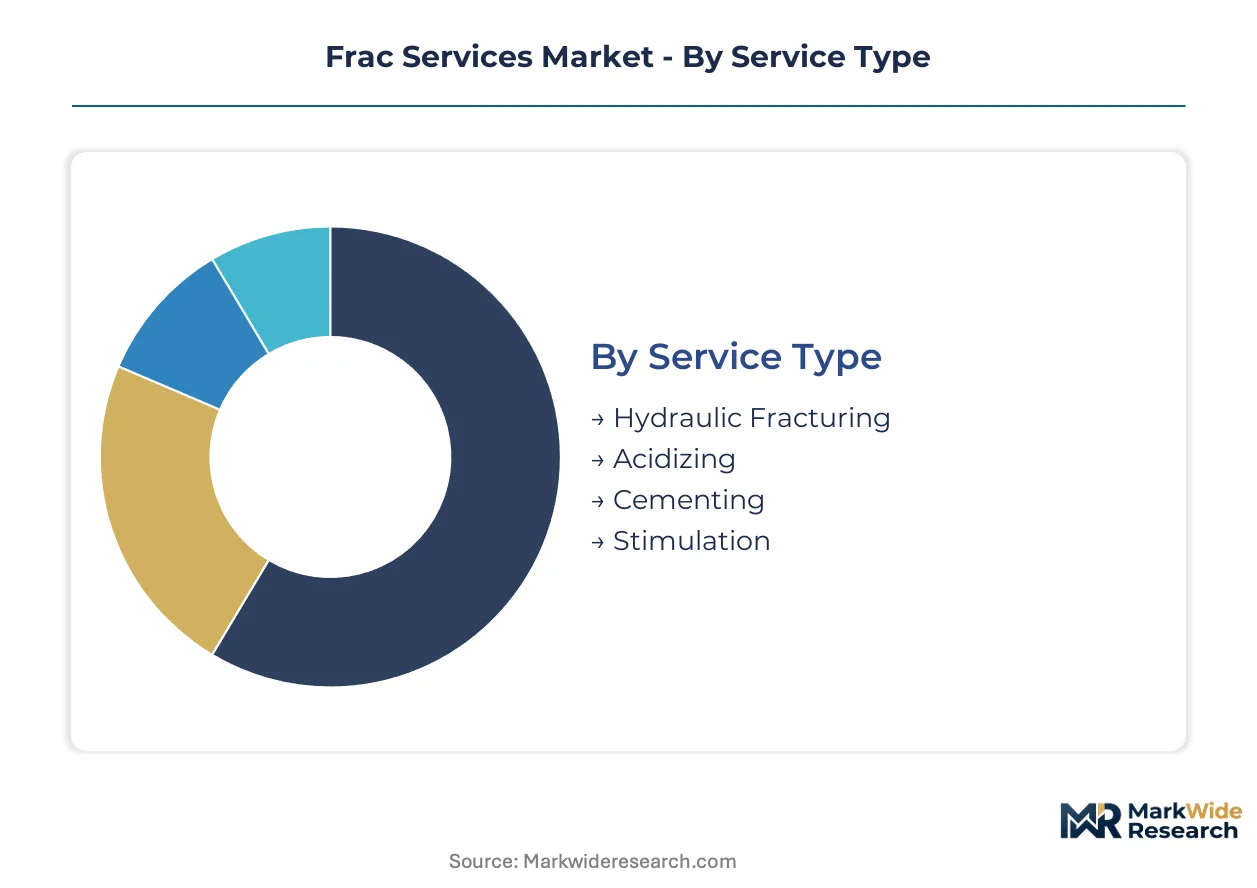
Frac services segmentation reveals how completion economics fragment across fluid chemistry, pressure delivery methods, and reservoir geology. Service providers configure equipment fleets and chemical supply chains around these divisions, with each segment demanding distinct capital intensity and technical specialization.
Service Type:
Supply concentration in hydraulic fracturing equipment creates asymmetric margin structures across this category, with high-spec pressure pumping fleets commanding premium utilization rates in tight-gas basins.
- Hydraulic Fracturing:High-pressure fluid injection at surface pressures exceeding 10,000 psi creates conductive fracture networks in unconventional formations. Demand concentrates in the Permian Basin and Appalachian regions where multi-well pad development sustains fleet utilization through zipper-frac sequencing and extended lateral lengths.
- Acidizing:Matrix stimulation using hydrochloric or organic acid systems dissolves formation damage in carbonate reservoirs without proppant placement. Operators in the Anadarko Basin and Mid-Continent region deploy these treatments to restore permeability in mature conventional wells where fracturing risks formation breakdown.
- Cementing:Zonal isolation services ensure casing integrity through precise slurry density control and displacement engineering.
- Stimulation:Broad category encompassing chemical and mechanical techniques to enhance hydrocarbon flow beyond primary fracturing.
Today's leader: Hydraulic Fracturing. Tomorrow's challenger: Acidizing.
Technology:
Cost tier differentiation separates commodity water-based systems from premium chemistries that withstand high-temperature reservoir conditions.
- Gel-Based:Crosslinked polymer systems deliver viscosity stability above 300°F in deep Gulf Coast and Anadarko wells where linear gels degrade prematurely. Majors operating in the Haynesville Shale specify these fluids for extended-reach laterals where proppant suspension determines stimulated rock volume.
- Hybrid Systems:Sequential application of slickwater and gel stages optimizes near-wellbore conductivity with far-field proppant transport. Permian independent operators deploy this approach in the Delaware Basin to balance cost per stage against estimated ultimate recovery targets in heterogeneous Wolfcamp formations.
- Water-Based:Slickwater formulations dominate volume through low chemical cost and minimal formation damage.
- Foam-Based:Energized systems using nitrogen or carbon dioxide reduce water consumption in water-sensitive formations.
Hybrid Systems are expanding most quickly as operators seek to optimize the trade-off between stage cost and fracture complexity.
End User:
Customer type fragmentation reflects divergent procurement strategies between capital-constrained independents and integrated majors with captive engineering capabilities.
- Independent Operators:Privately held shale producers in the Permian and Appalachian basins drive spot-market demand for tier-one frac fleets. These operators prioritize pumping capacity availability over long-term contracts, creating volatile pricing swings during seasonal activity surges.
- Majors:ExxonMobil and Chevron negotiate integrated well construction packages bundling drilling, completion, and artificial lift services. Their procurement leverage extracts volume discounts while demanding real-time operational data transparency through digital frac platforms.
- Service Companies:Third-party providers subcontract specialized pressure pumping or coiled tubing units to primary completion contractors.
- Oilfield Contractors:Mid-tier operators with bundled service capabilities serve marginal acreage positions.
Independents dominate current contract volume. Majors are consolidating procurement power fastest.
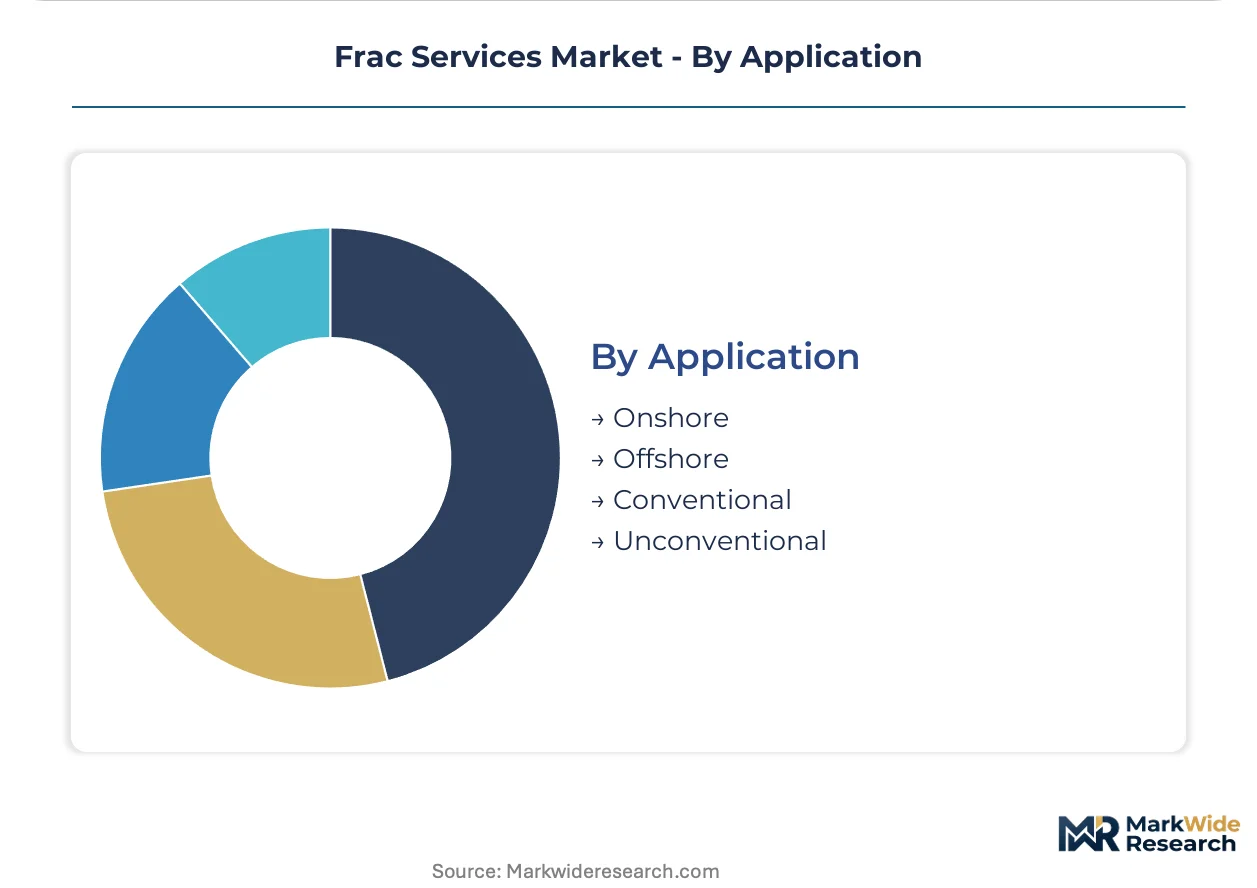
Application:
Geography and reservoir type combine to determine equipment specifications, with unconventional onshore development absorbing the majority of horsepower deployment.
- Unconventional:Horizontal wells in tight oil and shale gas formations require staged fracturing with proppant loads of 1,500-3,000 pounds per lateral foot. The Permian Basin's Delaware and Midland sub-basins anchor global demand for electric frac fleets as operators pursue emission reduction credits under tightening EPA methane standards.
- Onshore:Land-based operations span conventional and unconventional reservoirs across Texas, New Mexico, North Dakota, and Pennsylvania. Pad drilling infrastructure in these states enables multi-well zipper fracs that maximize equipment efficiency and minimize mobilization costs between wellbores.
- Offshore:Deepwater completions in the Gulf of Mexico demand specialized stimulation vessels and subsea intervention systems.
- Conventional:Vertical well maintenance and workover activity persists in mature basins with established infrastructure.
Unconventional applications command the steepest expansion trajectory. Onshore conventional work provides stable baseline demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frac services demand in the United States outpaces Canadian activity by roughly four-to-one in fleet deployment, though both markets face divergent regulatory trajectories on methane emissions enforcement.
United States
Texas and New Mexico absorb the majority of electric frac fleet orders as Permian Basin operators pursue EPA methane reduction credits. The EPA's Clean Air Act Section 111 mandates optical gas imaging surveys and pneumatic controller replacements at well sites. Reeves and Loving counties in West Texas concentrate multi-well pad development where private equity-backed producers deploy 6-12 month dedicated crew arrangements.
Canada
Alberta's Montney and Duvernay formations sustain demand for high-horsepower pumping capacity in tight-gas development. Health Canada and Environment Canada enforce methane regulations under the Pan-Canadian Framework that align with provincial flaring restrictions. Grande Prairie and Fort St. John anchor service company staging areas where winter drilling windows compress operational schedules.
Saudi Arabia
Unconventional gas targets in the Jafurah Basin are drawing pressure pumping investment as Aramco expands shale exploration. The Ministry of Energy's gas development program prioritizes domestic supply security over export commitments. Eastern Province clusters near Dhahran host integrated service bases where Halliburton and Schlumberger maintain long-term contracts.
China
Sichuan Basin shale gas development in the Fuling and Weirong blocks requires staged fracturing in complex mountain terrain. The Ministry of Ecology and Environment enforces water disposal regulations that constrain completion fluid recycling. Chongqing municipality anchors domestic equipment manufacturing where state-owned oilfield service companies expand captive fleet capacity.
Argentina
Vaca Muerta formation development in Neuquén Province sustains the only significant unconventional activity in Latin America. The national petroleum regulator enforces well integrity standards through casing and cementing requirements that extend completion timelines. Loma Campana and La Amarga Chica fields concentrate international operator joint ventures where YPF partners with Chevron and Shell.
Frac Services Market Vendor Landscape
United States-based operators anchor the premium tier through integrated service portfolios; Canadian specialists hold contract positions in cold-weather basins. Market structure splits between consolidated majors with bundled well construction capabilities and fragmented regional pumpers competing on spot availability. Three archetypes dominate: full-service integrators, electric fleet pure-plays, and proppant-integrated specialists. Competitive moves center on diesel-to-electric fleet conversion and sand mine acquisitions for supply security.
Within the full-service integrator tier, Halliburton and Schlumberger exemplify bundled completion contracting that combines drilling, pressure pumping, and digital design platforms. Liberty Oilfield Services anchors the electric fleet pure-play archetype through grid-connected turbine deployment. These three companies represent the strategic spectrum from diversified engineering integration to specialized emission-reduction technology.
| Leading Market Players |
|---|
| Liberty Oilfield Services |
| Trican Well Service |
| Halliburton |
| Profrac Holding Corp. |
| Weatherford |
| Schlumberger |
| Calfrac Well Services |
| Patterson-UTI Energy |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Proppant freight costs from Wisconsin and Minnesota mines cascade through three pricing tiers as rail logistics determine landed cost differentials across the Permian Basin. Diesel fuel consumption for conventional frac fleets anchors variable cost structures, compressing margins when spot prices spike and accelerating electric fleet conversion decisions among price-sensitive independents.
Pricing Analysis
Capacity additions in Texas and New Mexico are reshaping price floors for pressure pumping services as electric fleet deployment creates bifurcation between emission-credit-eligible and conventional diesel offerings. Contract pricing stratifies across premium electric turbine, standard Tier 4 diesel, and economy legacy fleet tiers, with differentiation driven by EPA methane compliance certification and bundled LDAR service inclusion. Pricing pressure stems from private equity-backed operators consolidating acreage positions and extracting volume discounts through dedicated crew arrangements. Independent shale producers in the Delaware Basin exhibit highest price sensitivity, while majors negotiating integrated well construction packages prioritize real-time data transparency over per-stage cost minimization.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia and Argentina are reshaping sourcing patterns as Aramco and YPF prioritize local equipment manufacturing partnerships over imported pressure pumping units. Supply concentration centers on the United States, Canada, and China, with high-horsepower pump manufacturing anchored in Houston and Oklahoma City, cold-weather fleet specialization in Alberta, and turbine drive system components sourced from Chongqing. Raw material dependencies include Northern White frac sand from Wisconsin mines, high-grade steel forgings for pump fluid ends, and rare earth elements for electric motor assemblies. Single-source vulnerability concentrates in rail-sand logistics corridors where BNSF and Union Pacific bottlenecks disrupt proppant delivery schedules. Distribution runs through regional equipment yards in Midland, Pecos, and Odessa that stage fleets for rapid pad deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frac services represent a late-cycle quality story as EPA methane enforcement and emission credit frameworks shift procurement criteria toward certified low-carbon completion packages. Demand is concentrating among operators willing to pay premium rates for electric fleet availability and integrated digital design platforms that optimize stage-level economics.
For Market Incumbents: Acquire captive sand mine assets in Wisconsin and Minnesota to secure proppant supply continuity against rail logistics disruptions. Expand electric fleet capacity in the Permian Basin to capture emission reduction credit demand from majors and private equity-backed consolidators. Defensive positioning requires countering Liberty Oilfield Services' grid-connected turbine deployment with comparable high-voltage infrastructure investments.
For New Entrants and Emerging Players: Mid-tier independents operating marginal acreage positions in the Anadarko Basin and Mid-Continent region represent underserved demand for acidizing and workover services outside premium unconventional corridors. White-space entry points concentrate in robotic proppant handling systems that address OSHA silica exposure mandates, and in real-time diagnostics convergence combining fiber-optic sensing with pressure transient analysis. Go-to-market positioning should emphasize emission-compliant service bundling for operators facing tightening state-level flaring restrictions.
For Investors and Strategic Acquirers: Consolidation pressure builds where diesel-to-electric conversion capital requirements exceed standalone operator balance sheet capacity, creating rollup opportunities for fleet modernization platforms. Long-term viability favors service providers with backward integration into sand mining and forward integration into continuous methane monitoring hardware. Acquisition target archetypes include regional pumpers with established pad drilling relationships in Reeves and Loving counties. The signal to watch is EPA enforcement intensity under Clean Air Act Section 111, which determines the velocity of retrofit-driven service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | Grid-connected turbine deployment captures EPA methane credit demand in Texas and New Mexico. |
| Sand Mine Acquisition | Captive Northern White supply insulates against BNSF rail corridor bottlenecks and spot price volatility. |
| Digital Platform Integration | Real-time frac design convergence with fiber-optic diagnostics enables stage-level EUR optimization. |
| LDAR Service Bundling | Continuous methane monitoring hardware installation extends contract renewal cycles under Section 111. |
| Appalachian Basin Expansion | Higher-stage-count adoption in Marcellus and Utica opens underpenetrated service corridors for dedicated crews. |
Methodological Framework
Direct dialogue with pressure pumping operations managers, proppant procurement leads at independent shale producers, EPA regulatory compliance officers, and electric fleet controls technicians grounded qualitative assessment in execution realities. Secondary validation drew from EIA drilling productivity reports, Railroad Commission of Texas completion filings, SEC 10-K disclosures from listed service companies, and OSHA enforcement data on silica exposure violations. Bottom-up equipment fleet counts and top-down regional expenditure estimates were triangulated to anchor volume projections.
Bottom-up modeling aggregated individual basin activity levels by horsepower deployment and fleet technology mix, while top-down analysis cross-checked against operator capital expenditure guidance and pressure pumping revenue disclosures. Segmentation dimensions included service type, fluid chemistry tier, end-user procurement archetype, and application geology across unconventional, conventional, onshore, and offshore categories. CAGRs were derived from regression analysis of historical fleet utilization against drilling permit trajectories, with electric fleet penetration curves and EPA compliance cost pass-through rates as industry-specific forecast inputs.
Underlying measurement precision varies by segment; electric fleet deployment data and EPA enforcement statistics carry tighter precision than private operator well economics assumptions. Forecasts reflect documented assumptions on methane regulation stringency, diesel-electric cost parity timelines, and proppant rail logistics capacity. Unconventional completion intensity trends and state-level groundwater protection rule changes represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Sand Control Screens Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
LNG Terminal Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Subsea Multiphase Flowmeter Market