
 Seawater Battery Market | 2026-2036
Seawater Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Seawater Battery Market Insights
Marine-to-grid supply chains is fragmenting as seawater battery developers bypass conventional lithium-ion distributors and forge direct partnerships with offshore energy operators. Blue Energy Co., Ltd. anchors South Korea's coastal demonstration projects through proprietary redox flow architectures. SK Innovation Co., Ltd. leverages its electrolyte research infrastructure to pilot sodium-based cathode formulations for saltwater environments. Samsung SDI Co., Ltd. competes by extending its solid-state battery roadmap toward corrosion-resistant marine housings.
Seawater batteries electrochemically harness dissolved sodium ions from ocean water as charge carriers, replacing mined lithium with an abundant electrolyte feedstock that eliminates thermal runaway risks inherent in conventional chemistries. Their primary purpose centers on stationary maritime energy storage where freshwater scarcity and salinity tolerance render standard lithium-ion systems uneconomical or unsafe. Redox flow architectures dominate current deployments due to scalable capacity decoupled from power rating, while solid-state variants attract the fastest-growing R&D allocation because of their potential to halve system weight for floating platform integration. Marine Applications command the deepest margin pools among end users, as offshore wind developers pay premiums for submersible storage that withstands pressure cycling at depth.
ISO 13628 subsea equipment standards and South Korea's Ministry of Trade, Industry and Energy (METI-aligned) marine energy certification frameworks govern product qualification timelines and cathode material purity thresholds. China's Ministry of Ecology and Environment (MEE) coastal water quality regulations constrain electrolyte discharge protocols, while Japan's METI sets feed-in tariff eligibility rules that favor seawater-coupled storage over conventional chemistries. Stakeholders must track how evolving subsea safety mandates and carbon-border adjustment mechanisms reshape the cost calculus between mined and ocean-sourced battery materials.
Market Dynamics
Marine-to-grid supply chains are fragmenting as seawater battery developers bypass conventional lithium-ion distributors and forge direct partnerships with offshore energy operators, fundamentally altering how stationary storage reaches maritime installations.
Growth Catalysts
- Offshore Wind Expansion:Floating wind platforms in the North Sea and East Asia require submersible storage systems that withstand pressure cycling at depth. METI's feed-in tariff rules in Japan explicitly favor seawater-coupled storage chemistries over conventional alternatives.
- ISO 13628 Certification Alignment:Subsea equipment standards now incorporate electrochemical storage safety protocols. Equipment manufacturers in South Korea accelerate qualification timelines by pre-certifying redox flow architectures against these frameworks.
- Sodium-Ion Cathode Maturation:Solid-state sodium formulations eliminate thermal runaway risks while leveraging abundant ocean-sourced electrolytes. Research consortia in coastal China report breakthroughs in corrosion-resistant marine housings that halve system weight.
Market Restraints
- Electrolyte Purification Costs:Seawater preprocessing to remove biological contaminants and heavy metals adds capex layers that compress margins against land-based lithium-ion benchmarks.
- Cathode Material Supply Concentration:High-purity sodium compounds and specialized membranes concentrate among Japanese and South Korean chemical suppliers, creating single-source vulnerabilities.
- Subsea Installation Complexity:Pressure-rated electrical penetrations and cathodic protection systems require vessel-deployed maintenance protocols that extend commissioning timelines versus surface-mounted alternatives.
Strategic Opportunities
- Floating Solar-Storage Hybrids:Coastal China and Southeast Asian markets present untapped demand for integrated platforms where photovoltaic generation couples directly with saltwater batteries, eliminating freshwater logistics.
- EU Green Deal Maritime Decarbonization:The European Union's carbon-border adjustment mechanisms and port electrification mandates create regulatory tailwinds for ocean-sourced battery materials over mined lithium supply chains.
- Redox Flow-Solid State Convergence:Hybrid architectures combining scalable flow battery capacity with solid-state power density are attracting R&D allocation for next-generation floating platform integration.
Industry Challenges
- Subsea Certification Timelines:ISO 13628 qualification protocols and METI-aligned marine energy frameworks impose multi-year validation cycles that delay revenue recognition for new entrants.
- Electrochemical Talent Scarcity:The intersection of marine engineering, corrosion science, and sodium-ion chemistry creates recruitment bottlenecks in coastal manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seawater Battery Market |
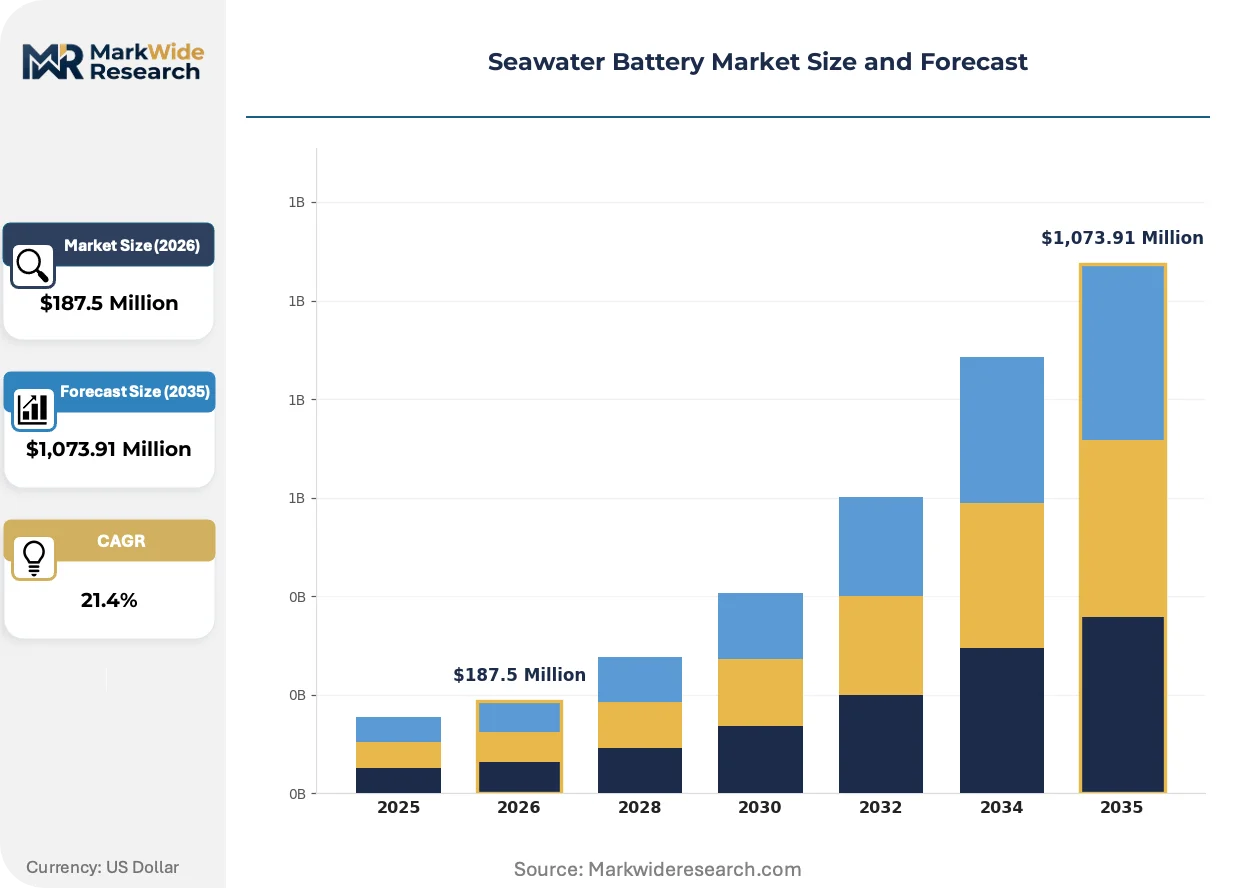
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $1,073.91 Million |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Redox Flow, Lithium-Ion, Solid-State, Lead-Acid End User: Marine Applications, Renewable Energy, Grid Storage, Portable Devices Component: Electrolyte, Anode, Cathode, Separator Technology: Charge Storage, Energy Conversion, Thermal Management, Power Management |
| Companies Covered | Blue Energy Co., Ltd., Korea Electric Power Corporation, SK Innovation Co., Ltd., POSCO Holdings Inc., Samsung SDI Co., Ltd., LG Energy Solution Ltd., Bluesky Energy, Shenzhen Sea Energy Power Holding, Aquion Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seawater Battery Market Trends and Innovations
Seawater battery architectures are diverging from land-based storage conventions as developers prioritize pressure tolerance and salinity immunity over energy density optimization.
Solid-state sodium-ion cells are hybridizing with conventional redox flow systems to create dual-mode storage that switches between high-power discharge and long-duration capacity. Offshore wind developers in the North Sea and East Asian waters pilot these configurations for floating substations. The hybridization is compressing the addressable market for pure flow batteries while opening premium pricing tiers for integrated platforms.
Japan's METI has revised feed-in tariff eligibility rules to weight carbon intensity in storage procurement scoring. This industrial consequence redirects utility-scale tenders toward ocean-sourced sodium chemistries. South Korean and Chinese developers respond by accelerating sodium cathode purity certifications to capture tariff-adjusted revenue pools.
Direct procurement relationships between offshore energy operators and battery system integrators are displacing conventional distributor networks. Marine engineering contractors in South Korea and coastal China now specify storage systems in early-stage platform design rather than deferring to secondary equipment vendors. This channel compression is most visible in floating wind tenders where integrated storage-performance guarantees determine contract awards.
Seawater Battery Market Segmentation
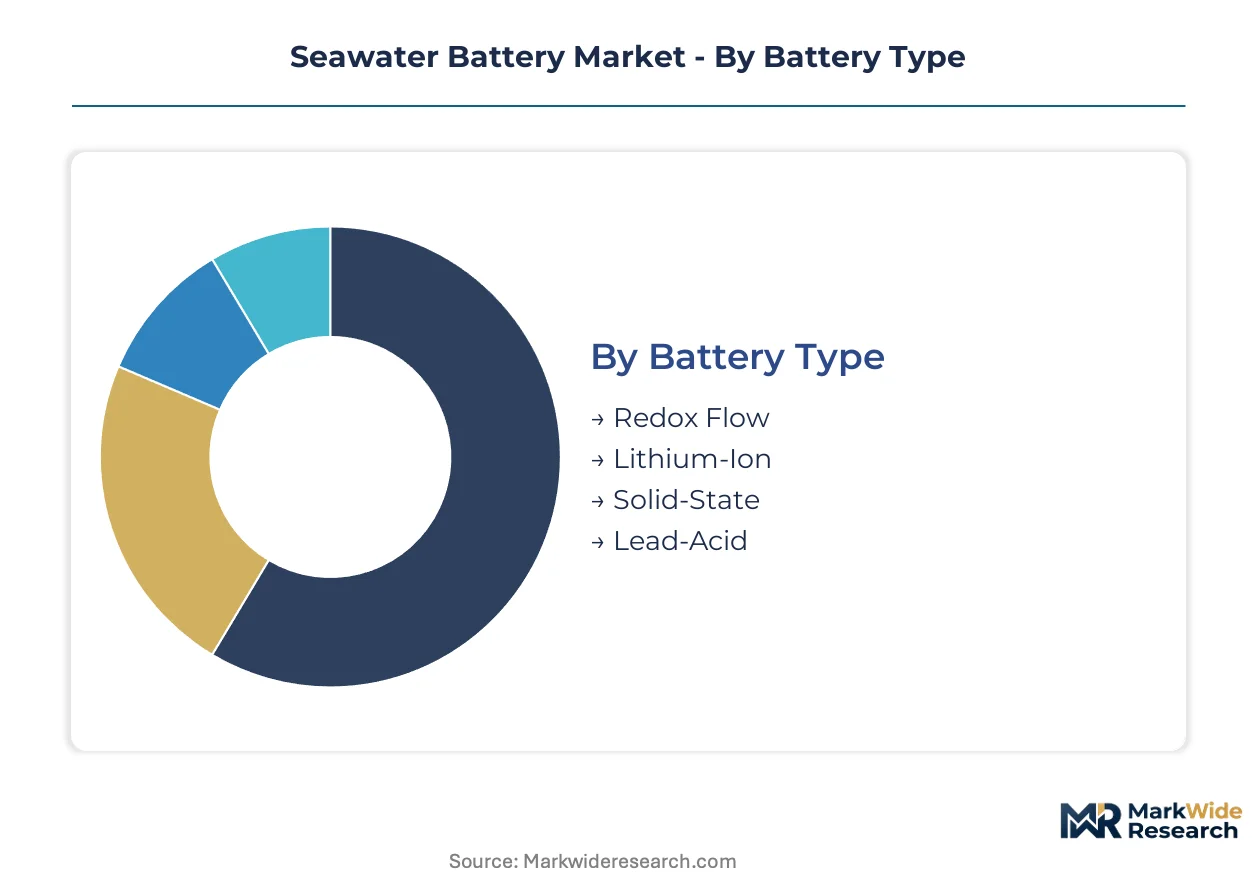
Seawater battery architectures diverge sharply from terrestrial storage across electrochemical design, deployment environment, and integration complexity. Segment boundaries reflect how pressure tolerance, salinity immunity, and marine certification requirements reshape conventional battery economics.
Battery Type:
Use-case spectrum spans submersible grid storage through portable marine electronics, with each chemistry trading energy density against depth rating and maintenance access.
- Redox Flow:Scalable capacity decoupled from power rating suits floating wind substations and offshore grid buffering. North Sea developers specify these systems for 20-year service intervals without dry-dock maintenance.
- Solid-State:Sodium-ion formulations eliminate thermal runaway while halving system weight for floating platform integration. Coastal China research consortia prioritize corrosion-resistant marine housings for this architecture.
- Lithium-Ion:Conventional chemistries require pressure-compensated enclosures that add 40% mass penalty; limited to surface-mounted auxiliary power in port electrification projects.
- Lead-Acid:Mature recycling infrastructure supports shallow-water navigation aids and backup systems where energy density penalties are acceptable.
The dominant share belongs to Redox Flow, while Solid-State is closing the gap fastest.
End User:
Customer procurement patterns split between capital-intensive offshore infrastructure and distributed marine equipment replacement cycles.
- Marine Applications:Submersible storage for floating wind platforms commands premium pricing due to pressure cycling requirements and cathodic protection integration. Japanese METI feed-in tariff rules explicitly favor seawater-coupled chemistries for these installations.
- Renewable Energy:Offshore wind developers in South Korea and coastal China specify storage-performance guarantees in early-stage platform design rather than deferring to secondary vendors.
- Grid Storage:Maritime grid stabilization projects leverage abundant ocean-sourced electrolytes to bypass lithium supply chain constraints.
- Portable Devices:Dive computers, autonomous underwater vehicles, and marine sensors drive demand for compact sodium-ion cells with saltwater immersion tolerance.
Marine Applications holds the revenue concentration, though Renewable Energy shows the steepest expansion trajectory.
Component:
Supply concentration for specialized membranes and high-purity sodium compounds creates single-source vulnerabilities across the stack.
- Electrolyte:Direct ocean sourcing eliminates mined material costs but requires preprocessing to remove biological contaminants and heavy metals. China's MEE coastal water quality regulations constrain discharge protocols for spent electrolyte.
- Cathode:Sodium-ion formulations from South Korean and Japanese chemical suppliers dominate qualification timelines for marine energy certification frameworks.
- Anode:Corrosion-resistant alloys and carbon-based structures must withstand chloride exposure at depth without cathodic protection system interference.
- Separator:Specialized ion-exchange membranes concentrate among Japanese suppliers, creating procurement bottlenecks for redox flow system integrators.
Cathode materials claim the deepest margin pool, with Electrolyte sourcing gaining strategic priority as developers seek supply chain autonomy.
Technology:
Functional layers differentiate between electrochemical conversion efficiency and system-level thermal and power conditioning.
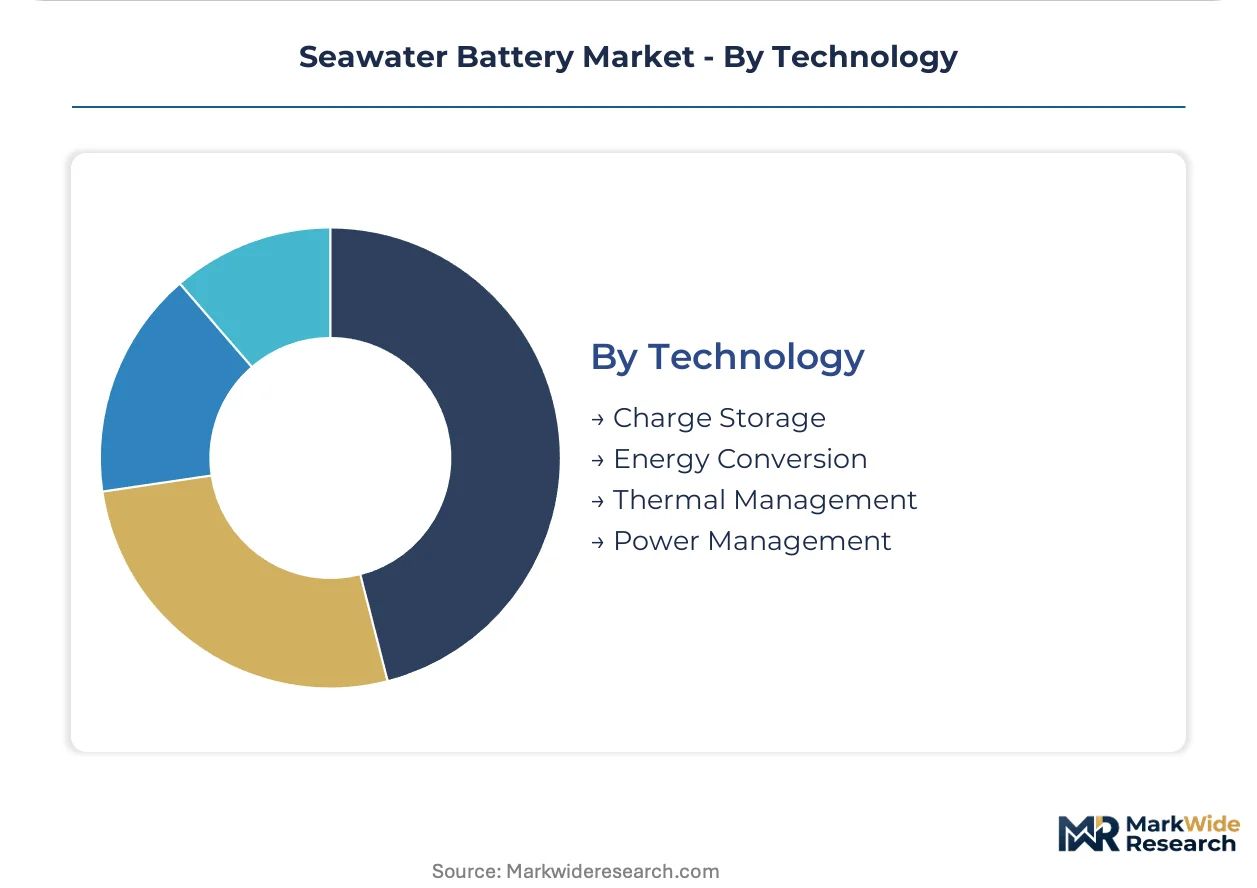
- Charge Storage:Redox flow architectures dominate through scalable tank configurations that decouple energy capacity from power rating. South Korean demonstration projects anchor coastal deployments through proprietary flow system designs.
- Energy Conversion:Solid-state sodium-ion cells achieve higher round-trip efficiency but face pressure-compensation challenges for deep-water integration.
- Thermal Management:Passive cooling via seawater heat exchange eliminates active HVAC systems that fail in salt spray environments.
- Power Management:Subsea electrical penetrations and pressure-rated converters extend commissioning timelines versus surface-mounted alternatives.
Charge Storage commands the installed base, while Energy Conversion attracts the fastest-growing R&D allocation for hybrid flow-solid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East Asia undersea cable network and North Sea offshore grid interconnects anchor seawater battery deployment corridors. Floating wind substations in South Korean, Japanese, and Chinese waters drive installation density, while European port electrification projects create secondary demand clusters.
South Korea
Floating wind platforms in the Yellow Sea and Korea Strait require submersible storage systems. METI-aligned marine energy certification frameworks govern cathode material purity thresholds and qualification timelines. The Busan-Ulsan industrial corridor hosts redox flow architecture demonstration projects led by domestic chemical suppliers.
Japan
Offshore wind developers in the Sea of Japan and Pacific coastal waters pay premiums for pressure-rated storage. METI feed-in tariff rules explicitly favor seawater-coupled chemistries over conventional lithium-ion alternatives. The Chubu/Nagoya manufacturing belt concentrates sodium-ion cathode research consortia targeting corrosion-resistant marine housings.
China
Coastal provinces in the Yangtze River Delta and Pearl River Delta integrate seawater batteries into floating solar-storage hybrid platforms. MEE coastal water quality regulations constrain electrolyte discharge protocols for spent ocean-sourced materials. Shenzhen and Shanghai host system integrators forging direct procurement relationships with offshore energy operators.
Germany
North Sea floating wind installations drive demand for ISO 13628-certified subsea storage systems. EU Green Deal maritime decarbonization mandates and carbon-border adjustment mechanisms favor ocean-sourced battery materials. The Hamburg and Bremerhaven port clusters anchor vessel-deployed maintenance protocols for pressure-rated electrical penetrations.
United States
Atlantic Coast floating wind lease areas in Massachusetts and California waters pilot saltwater battery integration for grid stabilization. FERC interconnection rules and state-level offshore wind procurement standards shape storage performance guarantee requirements. The Pacific Northwest and Northeast Corridor host marine engineering contractors specifying storage systems in early-stage platform design.
Seawater Battery Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated conglomerates with electrolyte research infrastructure, specialized redox flow developers with proprietary marine architectures, and solid-state battery manufacturers extending corrosion-resistant roadmaps. Competitive positioning hinges on cathode material purity certifications and direct partnerships with offshore energy operators. Capacity expansion into sodium compound production and strategic technology licensing for pressure-rated housings represent the dominant competitive moves.
Within the integrated conglomerate tier, SK Innovation Co., Ltd. and Samsung SDI Co., Ltd. exemplify South Korean players leveraging existing battery manufacturing ecosystems. Blue Energy Co., Ltd. occupies a distinct position as a specialized developer with proprietary redox flow architectures purpose-built for marine environments. These three entities collectively represent how geographic clustering in East Asian coastal manufacturing belts shapes competitive formation.
| Leading Market Players |
|---|
| Blue Energy Co., Ltd. |
| Korea Electric Power Corporation |
| SK Innovation Co., Ltd. |
| POSCO Holdings Inc. |
| Samsung SDI Co., Ltd. |
| LG Energy Solution Ltd. |
| Bluesky Energy |
| Shenzhen Sea Energy Power Holding |
| Aquion Energy |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese ion-exchange membrane suppliers compresses pricing power for redox flow system integrators while forcing procurement teams toward multi-year cathode material offtake contracts that lock in tier spreads between ISO 13628-certified premium systems and uncertified economy alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs seawater battery procurement. Premium tiers attach to METI-aligned marine energy certification and subsea pressure ratings, while economy tiers serve port electrification surface-mount installations. Price differentiation hinges on cathode material purity grades and cathodic protection system integration depth. Pricing pressure stems from electrolyte preprocessing capex layers that erode margins against land-based lithium-ion benchmarks. Floating wind developers show least price sensitivity due to performance-guarantee contract structures, whereas grid stabilization utilities drive hardest bargain on per-kWh economics.
Supply Chain Analysis
Supplier-financing facilities from South Korean chemical conglomerates extend payment terms for sodium compound procurement, easing working capital strain for redox flow system integrators. Manufacturing concentrates in South Korea, Japan, and coastal China where maritime industrial infrastructure converges with battery research ecosystems. Raw material dependencies center on high-purity sodium compounds, specialized ion-exchange membranes, and corrosion-resistant marine alloys. Single-source vulnerability concentrates in Japanese membrane suppliers. Distribution runs through direct partnerships between offshore energy operators and system integrators, bypassing conventional lithium-ion distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seawater battery market sits in early-cycle expansion as floating wind deployment accelerates through East Asian and North Sea waters, creating procurement pull-through for submersible storage systems before manufacturing scale economies mature.
For Market Incumbents: Build certification moats through accelerated ISO 13628 qualification timelines and METI-aligned marine energy framework pre-approval. Anchor position by securing captive sodium compound production in the Busan-Ulsan corridor. Defend against solid-state sodium-ion substitution threats by integrating corrosion-resistant marine housing R&D with existing redox flow architectures.
For New Entrants and Emerging Players: Establish a beachhead in floating solar-storage hybrid platforms across coastal China and Southeast Asian markets where freshwater logistics elimination creates immediate value capture. Target the portable marine electronics segment for dive computers and autonomous underwater vehicles where sodium-ion saltwater tolerance commands design-win premiums. Pursue direct procurement relationships with marine engineering contractors specifying storage in early-stage platform design.
For Investors and Strategic Acquirers: EU carbon-border adjustment mechanism implementation reshapes the acquisition landscape toward ocean-sourced battery material specialists over mined lithium supply chain exposure. Frame five-to-ten-year viability around regulatory preference durability for seawater-coupled chemistries in maritime decarbonization procurement scoring. Target acquisition candidates with proprietary redox flow architectures and existing METI feed-in tariff eligibility. Watch for FERC interconnection rule revisions in Atlantic Coast floating wind lease areas as signal for US market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Compound Production | Captive supply of high-purity cathode materials insulates against Japanese and South Korean chemical supplier concentration. |
| ISO 13628 Pre-Certification Investment | Accelerated subsea equipment qualification timelines compress revenue recognition delays for North Sea and East Asian deployments. |
| Direct Partnership with Floating Wind Developers | Channel compression bypasses lithium-ion distributors and locks in storage-performance guarantee contract structures. |
| Solid-State Sodium-Ion R&D Allocation | Corrosion-resistant marine housing breakthroughs halve system weight for floating platform integration against pure flow battery alternatives. |
| Electrolyte Preprocessing Technology Licensing | Biological contaminant and heavy metal removal IP addresses China's MEE coastal water quality regulatory constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with offshore wind project developers, marine engineering contractors, redox flow system integrators, sodium-ion cathode research directors, and subsea certification specialists. Secondary validation drew from FERC interconnection filings, METI marine energy framework documentation, ISO 13628 subsea equipment standards, China's MEE coastal water quality regulations, and EU Green Deal maritime decarbonization policy texts. Bottom-up installation forecasts triangulated against top-down addressable market sizing across battery type, end user, and regional deployment corridors.
Calibration anchored on historical deployment trajectories in South Korean and Japanese coastal demonstration projects. Segmentation modeling spanned battery architecture, end-use application, component supply tier, and technology functional layer across the projection horizon. CAGRs derived from slope analysis of patent filing velocity, electrolyte research consortium formation rates, and floating wind tender award patterns. Industry-specific forecast inputs incorporated cathode material purity certification timelines and pressure-rated electrical penetration commissioning duration benchmarks.
Sensitivities concentrate around METI feed-in tariff rule durability, ISO 13628 qualification protocol evolution, and EU carbon-border adjustment mechanism implementation timing. Forecasts embed assumptions regarding sodium-ion cathode maturation curves and subsea installation cost reduction trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Silicon Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Europe Battery Cell Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Wireless Power Bank Market
Batteries
Battery Maintainer Market
Batteries
Military Battery Market
Batteries
Alkaline Secondary Battery Market
Batteries
Southeast Asia Battery Market
Batteries
West Africa Battery Market
Batteries
Power Battery Sealant Market
Batteries
48 Volt Battery System Market
Batteries
India SLI Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market