
 Global Artificial Lift Market | 2026-2036
Global Artificial Lift Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Lift Market Analysis
Multi-source procurement for artificial lift components is expanding as operators reduce dependency on single vendors for critical downhole equipment. Baker Hughes Company leverages its integrated digital monitoring platforms to sustain recurring service revenue across major basins. Halliburton anchors its position through proprietary real-time diagnostics that optimize gas lift performance in unconventional wells. NOV Inc. competes with modular rod pumping systems designed for rapid deployment in North American shale operations.
Artificial lift encompasses mechanical, electrical, and gas-assisted technologies that reduce bottom-hole pressure to sustain or increase hydrocarbon flow from producing wells. Electric submersible pumps operate at depths exceeding 12,000 feet with power ratings up to 5,000 horsepower, enabling high-volume crude extraction from deep reservoirs. Rod pumping retains the largest installed base among lift technologies due to its mechanical simplicity and suitability for stripper wells with marginal production rates. Progressive cavity pump adoption is accelerating in heavy oil applications where viscosity challenges render centrifugal designs ineffective. Offshore installations command premium service margins despite representing a smaller addressable base, given the complexity of subsea deployment and maintenance logistics.
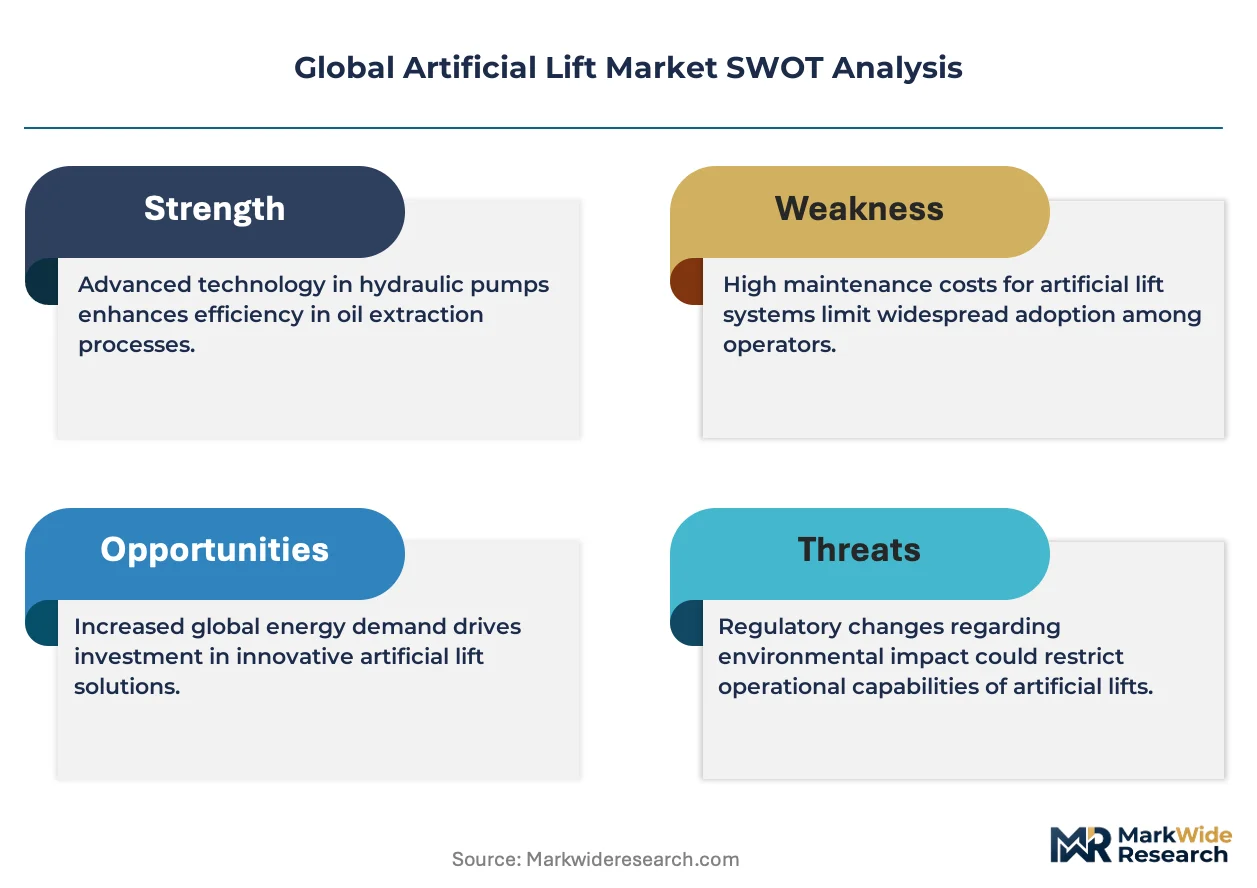
The EPA enforces methane performance standards that compel operators to replace pneumatic controllers with electrified artificial lift systems, tightening equipment compliance requirements. API specification 11AX governs subsurface pump dimensions and materials, creating certification barriers for non-standard suppliers entering North American markets. The EU F-Gas Regulation restricts fluorinated gas use in certain gas lift applications, redirecting investment toward alternative lift technologies in European offshore fields. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating R&D portfolios toward electrification and emissions containment capabilities.
Market Dynamics
Electrification mandates from the EPA and EU F-Gas Regulation are forcing operators to retire pneumatic artificial lift systems, compressing replacement cycles and reshaping vendor competitive positions around emissions-compliant equipment portfolios.
Growth Catalysts
- EPA methane performance standards:Operators in the United States must replace pneumatic controllers with electrified rod pump systems, creating mandatory equipment refresh cycles.
- Permian Basin concentration:Unconventional well operators in Texas and New Mexico prioritize artificial lift optimization to sustain production from depleting shale reservoirs.
- Progressive cavity pump technology:Heavy oil producers in Canada and Venezuela adopt these systems where viscosity challenges render centrifugal designs ineffective.
Market Restraints
- Specialized alloy supply concentration:High-nickel steels for downhole pump components face supply bottlenecks from limited specialty steel producers.
- Deepwater deployment costs:Subsea artificial lift installations require vessel-supported intervention, constraining offshore adoption outside premium-margin fields.
- EU F-Gas Regulation restrictions:Fluorinated gas limitations in European offshore fields redirect investment toward alternative lift technologies with higher capital intensity.
Strategic Opportunities
- Brazil pre-salt development:Petrobras-led deepwater projects create demand for high-horsepower electric submersible pumps in ultra-deep reservoirs.
- Digital twin convergence:Integration of physics-based modeling with real-time sensor streams enables predictive failure avoidance and optimized production scheduling.
- Saudi Arabia gas lift conversion:The country's national oil company is retrofitting aging fields with gas lift systems to extend plateau production.
Industry Challenges
- Subsea electrical technician scarcity:Offshore electrification outpaces training pipeline capacity for high-voltage subsea system maintenance.
- API 11AX certification timelines:Non-standard suppliers face 18-24 month approval cycles for subsurface pump dimensional compliance.
- Legacy SCADA integration friction:Intelligent lift systems require protocol translation layers to communicate with decades-old wellsite control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Lift Market |
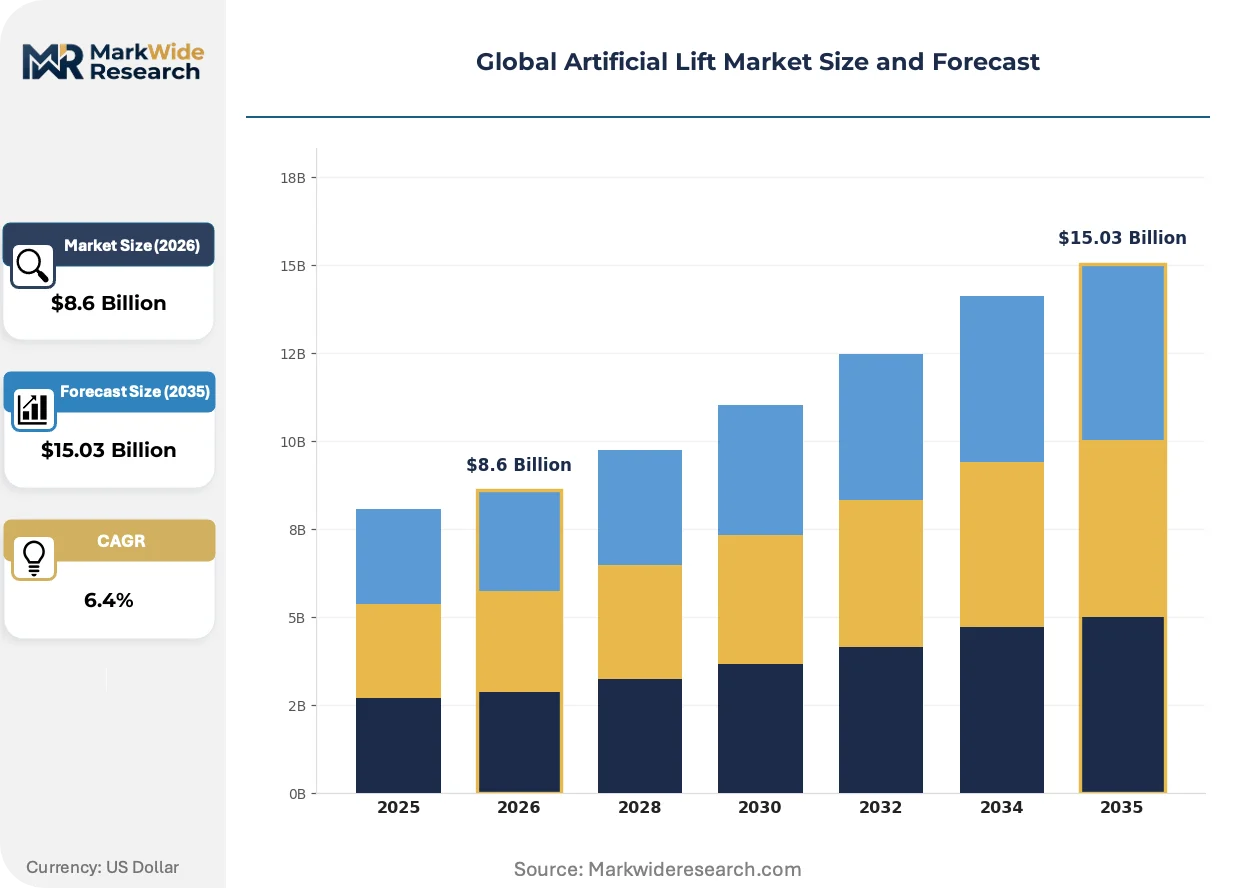
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $15.03 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Rod Pumping, Electric Submersible Pump, Gas Lift, Progressive Cavity Pump End User: Oil & Gas Producers, Service Companies, Petrochemicals, Offshore Facilities Installation Type: Onshore, Offshore, Greenfield, Brownfield Application: Heavy Oil Production, Natural Gas Recovery, Enhanced Oil Recovery, Well Stimulation |
| Companies Covered | SLB, Baker Hughes Company, Halliburton, Weatherford, ChampionX, NOV Inc., Schlumberger Limited, GE Oil & Gas, Borets International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Lift Market Emerging Trajectories
Digitalization is collapsing the latency between downhole condition detection and surface response, enabling autonomous lift optimization that was previously constrained by manual intervention cycles.
Edge computing architectures are decentralizing artificial lift control from centralized SCADA systems to wellsite nodes. Independent producers in the Permian Basin deploy these systems to compress response times from minutes to milliseconds. This topology is decentralizing maintenance scheduling and reducing dependency on continuous connectivity.
The EU F-Gas Regulation is restricting fluorinated gas use in offshore gas lift applications. European operators in the North Sea and Norwegian Continental Shelf face equipment replacement deadlines. This pressure is redirecting capital toward electric submersible pump retrofits and closed-loop gas lift alternatives.
Performance-based service contracting is displacing traditional equipment procurement in North American shale operations. Operators in the Eagle Ford and Bakken formations now pay per barrel lifted rather than capitalizing hardware. This shift concentrates vendor risk while transferring operational accountability to equipment suppliers.
Global Artificial Lift Market Segmentation
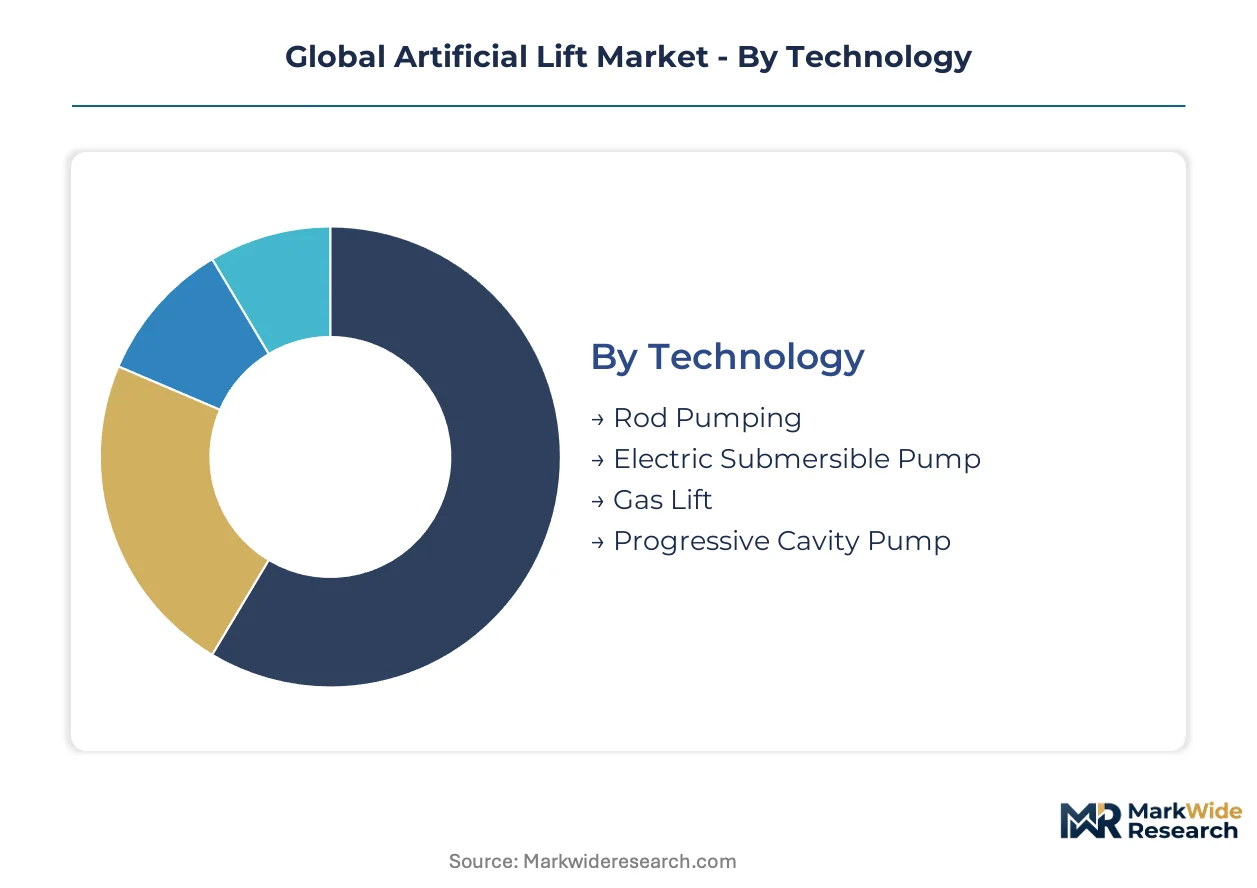
Artificial lift procurement decisions cascade through multiple technical and commercial dimensions. Operators select lift technology based on reservoir depth, fluid properties, and regulatory constraints. Installation type and application context further narrow equipment specifications and vendor selection criteria.
Technology:
Capital intensity and reservoir depth drive technology selection among operators with heterogeneous well portfolios.
- Rod Pumping:Beam and surface-drive systems deploy mechanical force through sucker rods to actuate subsurface pumps. Stripper well operators in Texas and Oklahoma favor these units for marginal production rates where electrical infrastructure is sparse. The EPA's methane performance standards are accelerating electrified rod pump retrofits across the Permian Basin.
- Electric Submersible Pump:Centrifugal multistage assemblies operate at depths exceeding 12,000 feet with power ratings up to 5,000 horsepower. Petrobras deploys these systems in Brazil's pre-salt formations where ultra-deep reservoirs demand high-volume extraction capability.
- Gas Lift:Injected gas reduces hydrostatic column density to stimulate flow from depleted reservoirs. Saudi Aramco is retrofitting aging fields with these systems to extend plateau production.
- Progressive Cavity Pump:Helical rotor-stator pairs handle viscous crude where centrifugal designs lose efficiency. Canadian heavy oil producers around Fort McMurray deploy these units for bitumen extraction.
Rod pumping leads on scale; progressive cavity pump adoption is expanding most quickly in heavy oil basins.
End User:
Procurement authority varies sharply across the value chain, with integrated operators and independent producers maintaining distinct specification standards.
- Oil & Gas Producers:Majors and independents specify equipment directly for operated wells. US shale operators in the Eagle Ford and Bakken formations now favor performance-based contracting over capital procurement.
- Service Companies:Schlumberger and Halliburton maintain rental fleets and integrated service packages. These firms aggregate demand across multiple operator clients.
- Petrochemicals:Downstream-integrated operators deploy artificial lift for feedstock security rather than commodity margin optimization.
- Offshore Facilities:Platform and FPSO operators face subsea intervention constraints that elevate equipment reliability specifications.
Oil and gas producers dominate procurement volume; service companies are gaining share fastest through integrated offerings.
Installation Type:
Site conditions determine deployment complexity and maintenance accessibility, with offshore and brownfield environments commanding premium engineering.
- Onshore:Land-based installations permit rapid rig mobilization and lower intervention costs. Permian Basin operators concentrate activity here.
- Offshore:Platform and subsea deployments require vessel-supported maintenance and specialized electrical technicians. North Sea operators face escalating labor scarcity.
- Greenfield:New well construction allows optimized artificial lift specification during drilling design. Brazil's pre-salt developments exemplify this category.
- Brownfield:Retrofit installations must integrate with legacy SCADA infrastructure and existing wellbore geometries. Mature US fields require extensive brownfield work.
Onshore installations anchor volume; offshore projects claim the steepest margin premiums.
Application:
Fluid characteristics and recovery objectives shape equipment selection, with viscosity and gas-oil ratio as primary technical filters.
- Heavy Oil Production:Viscous crude above 10,000 centipoise demands positive displacement pumping. Venezuela's Orinoco Belt and Canada's oil sands drive this segment.
- Natural Gas Recovery:Gas lift and plunger lift systems handle dewatering and liquid loading in gas wells. US shale gas operators deploy these for marginal well economics.
- Enhanced Oil Recovery:Artificial lift sustains production during waterflood and CO2 injection operations. Permian CO2 floods require specialized corrosion-resistant metallurgy.
- Well Stimulation:Temporary lift systems clear wellbore fluids post-fracturing to enable flowback. Permian and Appalachian operators cycle these units rapidly.
Heavy oil production commands specialized equipment premiums; enhanced oil recovery is climbing fastest as mature fields exhaust primary drive mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors artificial lift procurement intensity, with EPA methane regulations and unconventional depletion cycles compressing equipment replacement timelines across major producing regions.
United States
Permian Basin operators in Texas and New Mexico deploy electrified rod pump retrofits to comply with EPA methane performance standards. The EPA mandates pneumatic controller replacement, accelerating capital refresh cycles. Midland-Odessa clusters concentrate service company infrastructure for rapid deployment.
Brazil
Petrobras pre-salt developments in the Santos Basin drive demand for high-horsepower electric submersible pumps at depths exceeding 20,000 feet. ANP regulatory frameworks govern subsea equipment certification. Rio de Janeiro anchors engineering centers for deepwater artificial lift specification.
Saudi Arabia
Saudi Aramco gas lift conversion programs target aging Ghawar and Safaniya fields to extend plateau production. The national oil company's domestic content requirements shape vendor selection criteria. Dhahran-based engineering clusters coordinate field retrofit scheduling.
Canada
Alberta oil sands operators around Fort McMurray deploy progressive cavity pumps for bitumen extraction where viscosity exceeds 10,000 centipoise. Alberta Energy Regulator directives govern thermal production emissions. Calgary headquarters concentrate equipment procurement authority for oil sands developments.
Norway
Equinor and Aker BP face EU F-Gas Regulation deadlines restricting fluorinated gas use in North Sea gas lift applications. The Norwegian Petroleum Directorate enforces subsea equipment reliability standards. Stavanger clusters specialize in offshore electrification engineering for platform retrofits.
Global Artificial Lift Market Vendor Landscape
Global majors compete with regional champions across technology integration and service bundling, producing a tiered structure where scale-driven suppliers anchor premium segments while specialized fabricators capture basin-specific maintenance contracts. Strategic archetypes divide into integrated oilfield service conglomerates, pure-play artificial lift specialists, and national oil company captive suppliers. Competitive moves concentrate on portfolio electrification and performance-based contracting structures that transfer operational risk to equipment vendors.
Within the integrated services tier, Baker Hughes Company, Halliburton, and Schlumberger occupy positions defined by recurring revenue platforms and real-time diagnostics capabilities. These entities exemplify the shift toward outcome-based commercial models in North American shale basins. Regional specialists including Borets International and ChampionX represent focused engineering approaches targeting specific lift technologies or geographic markets. The competitive terrain rewards vendors with proprietary monitoring architectures and rapid-deployment modular systems.
| Leading Market Players |
|---|
| SLB |
| Baker Hughes Company |
| Halliburton |
| Weatherford |
| ChampionX |
| NOV Inc. |
| Schlumberger Limited |
| GE Oil & Gas |
| Borets International |
| Others |
Supply Flow & Price Mechanics
EPA methane performance standards gate qualified supply for electrified rod pump systems while reserving premium-tier pricing access for vendors with certified emissions-compliant portfolios. Equipment buyers face tiered qualification barriers where regulatory compliance separates premium suppliers from commodity competitors.
Pricing Analysis
Input-cost pass-through from high-nickel specialty steels flows directly into rod pump and electric submersible pump pricing structures. Three-tier pricing structure across premium, standard, and economy levels separates API 11AX-certified vendors from non-standard suppliers facing 18-24 month approval cycles. Cost compression in standard-tier equipment is intensifying because of alloy supply bottlenecks from limited specialty steel producers. Independent producers in the Permian Basin exhibit highest price sensitivity due to marginal well economics, while Petrobras pre-salt projects demonstrate lowest sensitivity given ultra-deep reservoir complexity.
Supply Chain Analysis
Freight costs for oversized downhole pump assemblies and high-horsepower surface equipment constrain procurement radius from manufacturing centers. Supply concentrates in the United States, Germany, and China for precision-machined pump components and power electronics. Raw material dependencies center on high-nickel steels, rare-earth magnets for permanent magnet motors, and fluoropolymer seals. Single-source vulnerability persists for API-certified foundries capable of producing subsurface pump housings. Distribution runs through integrated oilfield service rental fleets and direct OEM sales to national oil companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA electrification mandates in the United States compress replacement cycles faster than EU F-Gas Regulation timelines, creating divergent equipment demand intensity across Atlantic basin markets.
For Market Incumbents: Extend digital monitoring platform penetration into Permian Basin independent producer accounts before modular competitors capture share. Deepen backward integration into high-nickel alloy supply through captive foundry relationships or long-term offtake agreements with certified suppliers. The threat of performance-based contracting transferring operational risk to vendors demands preemptive service bundling. For New Entrants and Emerging Players: Launch via direct sales to Canadian heavy oil operators around Fort McMurray where progressive cavity pump specialization gaps persist outside ChampionX and Borets strongholds. Target Brazil pre-salt service opportunities through Rio de Janeiro engineering partnerships rather than competing head-to-head with Schlumberger rental fleets. White-space concentration in subsea electrical technician training services offers defensible entry. For Investors and Strategic Acquirers: Roll-up economics work for regional artificial lift maintenance specialists because customer switching costs embed through SCADA integration and well-specific equipment histories. The 5-10 year viability window favors platform consolidation around digital twin capabilities and predictive maintenance IP. Watch for inflection when Saudi Aramco gas lift conversion program volume crosses threshold sufficient to justify dedicated manufacturing capacity in Dhahran corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Program | EPA methane compliance mandates compress replacement cycles for pneumatic systems across Permian Basin operations. |
| Digital Twin Platform Integration | Physics-based modeling with real-time sensor streams enables predictive failure avoidance for unconventional wells. |
| High-Nickel Alloy Backward Integration | Captive supply of API 11AX-certified foundry capacity defends margin position against specialty steel bottlenecks. |
| Subsea Electrical Technician Training | Offshore electrification outpaces labor pipeline capacity, creating service premium capture in North Sea markets. |
| Performance-Based Contracting Structure | Per-barrel pricing transfers operational accountability from Eagle Ford operators to equipment vendors. |
Methodological Framework
Multiple input streams — field interviews with artificial lift engineering directors, maintenance supervisors at Permian Basin operators, and procurement leads at national oil companies — were reconciled against secondary validation from EPA regulatory filings, ANP certification databases, and SEC 10-K equipment revenue disclosures. Bottom-up well-count modeling across shale basins and top-down vendor revenue aggregation were cross-checked for consistency. Primary fieldwork captured specification trends for electrified rod pump retrofits and gas lift conversion programs.
Data-stream reconciliation anchored volume projections to documented replacement cycles under EPA methane performance standards and EU F-Gas Regulation deadlines. The analytical framework segmented across technology type, installation context, and application fluid characteristics, with additional modeling for regulatory compliance tier. CAGRs were derived from equipment procurement intensity mapped to mature field decline curves and unconventional well completion schedules. Forecast inputs incorporated Permian Basin depletion rates and Brazil pre-salt development timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price collapse scenarios that delay discretionary brownfield retrofits. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Desalter Market
Oil & Gas
Frac Stack Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Proppant Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Smart Well Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Middle East Natural Gas Market