
 Mexico Wireline Services Market | 2026-2036
Mexico Wireline Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Wireline Services Market Foresight
Maintenance-layer contracting is hardening into the core revenue stream for wireline providers across Mexico's mature hydrocarbon basins. Schlumberger Limited leverages its integrated logging-while-drilling portfolio to anchor long-term service agreements with national operators. Baker Hughes Company competes through specialized slickline intervention units positioned near PEMEX's southern production clusters. Halliburton Company sustains geographic dominance in northern Mexico through permanent field camps and localized equipment refurbishment capabilities.
Wireline services encompass the deployment of electric cables or mechanical lines into wellbores to perform logging, perforating, sampling, and mechanical intervention operations, typically utilizing single-conductor or multi-conductor cables rated for pressures exceeding 20,000 psi and temperatures above 350°F. These services enable real-time downhole data acquisition and wellbore remediation critical to maximizing hydrocarbon recovery and ensuring structural integrity across completions and workovers. Logging services occupy the deepest margin pools due to proprietary sensor technology and interpretation software barriers, while E-line capabilities represent the fastest-expanding technology segment as operators demand real-time telemetry over conventional slickline methods. Well completion applications generate the most stable demand cycle, though inspection services are gaining share as aging infrastructure mandates intensify across Mexico's decades-old production fields.
CNH licensing rounds and SENER's operational guidelines shape contractor qualification requirements, while NOM standards govern equipment certification and personnel safety protocols for downhole operations. Mexico's federal environmental regulator imposes waste management and spill contingency rules that elevate compliance costs for wireline fluid handling and perforating charge disposal. Stakeholders must monitor how evolving local content mandates and energy sovereignty policies reshape partnership structures between international service firms and domestic suppliers.
Market Dynamics
PEMEX's capital allocation toward mature field rejuvenation is concentrating demand for intervention services around aging wellbores in Veracruz and Tabasco. This operator-driven spending pattern is compressing contract cycles and elevating technical qualification barriers for wireline vendors seeking recurring revenue streams.
Growth Catalysts
- Reservoir characterization mandates:CNH licensing requirements for detailed formation evaluation are expanding logging service procurement across offshore blocks in the Sureste Basin.
- E-line telemetry adoption:Real-time data transmission capabilities are displacing conventional slickline methods in high-temperature completions where immediate decision-making reduces non-productive time.
- Chicontepec tight oil development:Complex fracture diagnostics and multi-stage perforation programs in this northern basin are sustaining demand for specialized cased-hole wireline units.
Market Restraints
- Import-dependent equipment supply:Downhole cables, logging sensors, and perforating hardware originate primarily from US manufacturing clusters, exposing service providers to cross-border tariff volatility and extended lead times.
- CNH contractor qualification rigidity:The national hydrocarbons commission's technical and financial pre-qualification protocols create 12-18 month entry barriers for new international service entrants.
- PEMEX payment cycle elongation:State-operator receivables stretching beyond 180 days strain working capital for wireline contractors operating on asset-heavy business models.
Strategic Opportunities
- Tabasco deepwater frontier:Untapped reservoirs in this southern sub-basin present greenfield logging and completion service requirements as international consortiums advance exploration drilling.
- SENER local content incentives:Domestic partnership mandates for equipment maintenance and personnel training create structural advantages for service providers with established Mexican operational footprints.
- Digital twin integration:Convergence of wireline sensor data with predictive analytics platforms is opening subscription-based revenue models for continuous well integrity monitoring.
Industry Challenges
- Specialized logging engineer scarcity:Interpretation of complex resistivity and acoustic measurements requires personnel with 5+ years of formation evaluation experience, a talent pool concentrated among legacy PEMEX-trained specialists.
- NOM certification timelines:Equipment recertification under Mexican standards for pressure-rated cables and explosive perforating charges creates operational downtime during mandatory inspection windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Wireline Services Market |
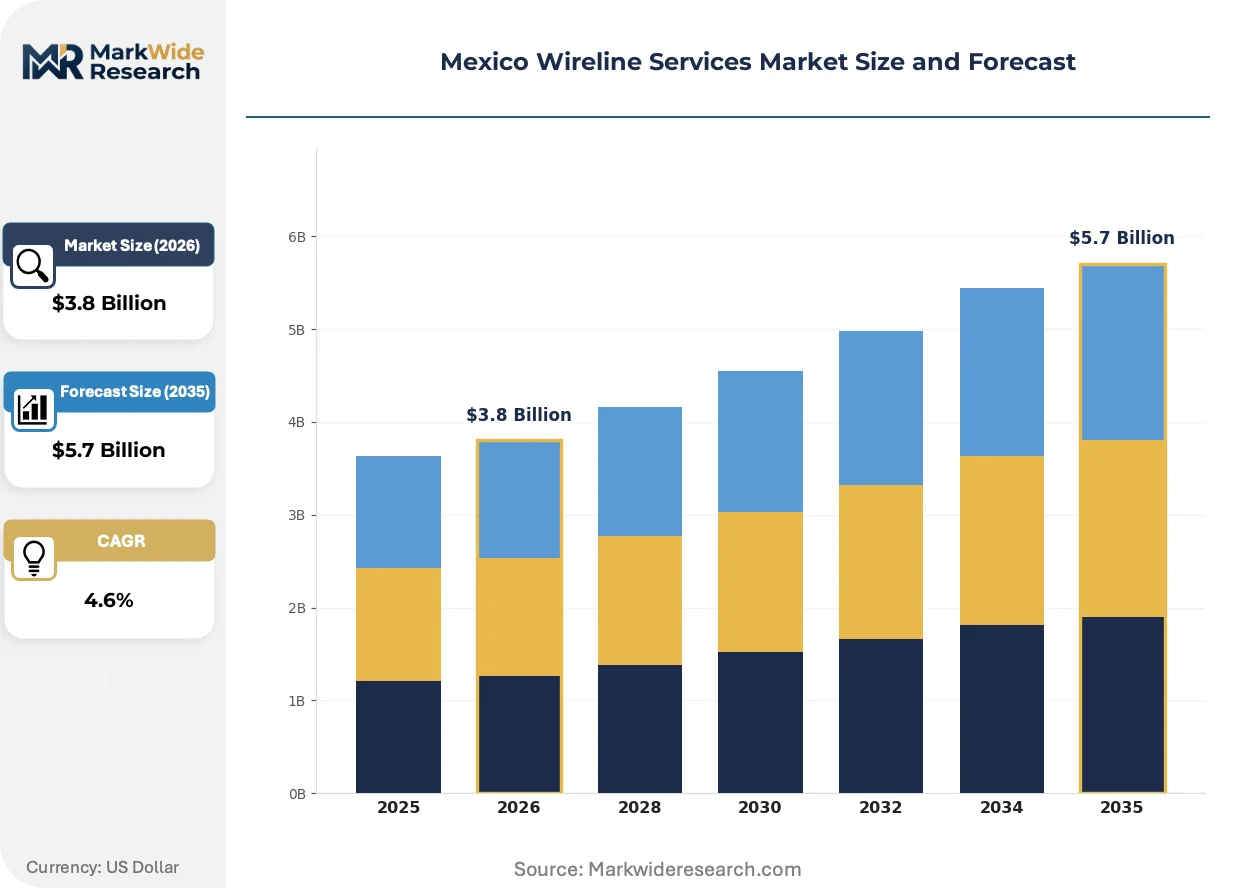
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Testing, Logging, Well Completion Application: Oil Extraction, Natural Gas, Water Utilities, Mining End User: Oil & Gas Operators, Utility Companies, Mining Firms, Environmental Agencies Technology: Conventional Wireline, Slickline, E-line, Fiber Optic |
| Companies Covered | Weatherford International plc, Superior Energy Services, Schlumberger Limited, Grupo R, PEMEX, Halliburton Company, Expro Group, Perfolat, Baker Hughes Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Wireline Services Market Shifts & Advancements
Technology substitution and regulatory recalibration are actively restructuring competitive positioning across Mexico's wireline sector. Vendors are repositioning around telemetry capabilities and environmental compliance to capture preference shifts among national and international operators.
High-temperature fiber-optic distributed sensing is rewriting how operators monitor wellbore conditions across Mexico's mature southern fields. PEMEX and private consortiums operating in the Sureste Basin are deploying these systems for continuous temperature and strain profiling. The technology is compressing the interval between diagnostic interventions and enabling predictive maintenance scheduling that reduces unplanned shut-ins.
SENER's evolving environmental contingency protocols are tightening waste handling requirements for wireline fluid recovery and perforating charge disposal. Service providers must now demonstrate closed-loop containment systems and third-party disposal certifications to maintain operational permits. Offshore contractors in Campeche Bay face the steepest compliance cost escalations as marine spill liability thresholds tighten.
Integrated service bundling is displacing discrete wireline procurement as operators seek single-accountability contracts spanning logging, perforating, and remediation. PEMEX's southern production clusters are consolidating vendor relationships around full-intervention packages. This pattern concentrates contract value among providers with in-house slickline, E-line, and coiled tubing capabilities rather than standalone wireline specialists.
Mexico Wireline Services Market Segmentation
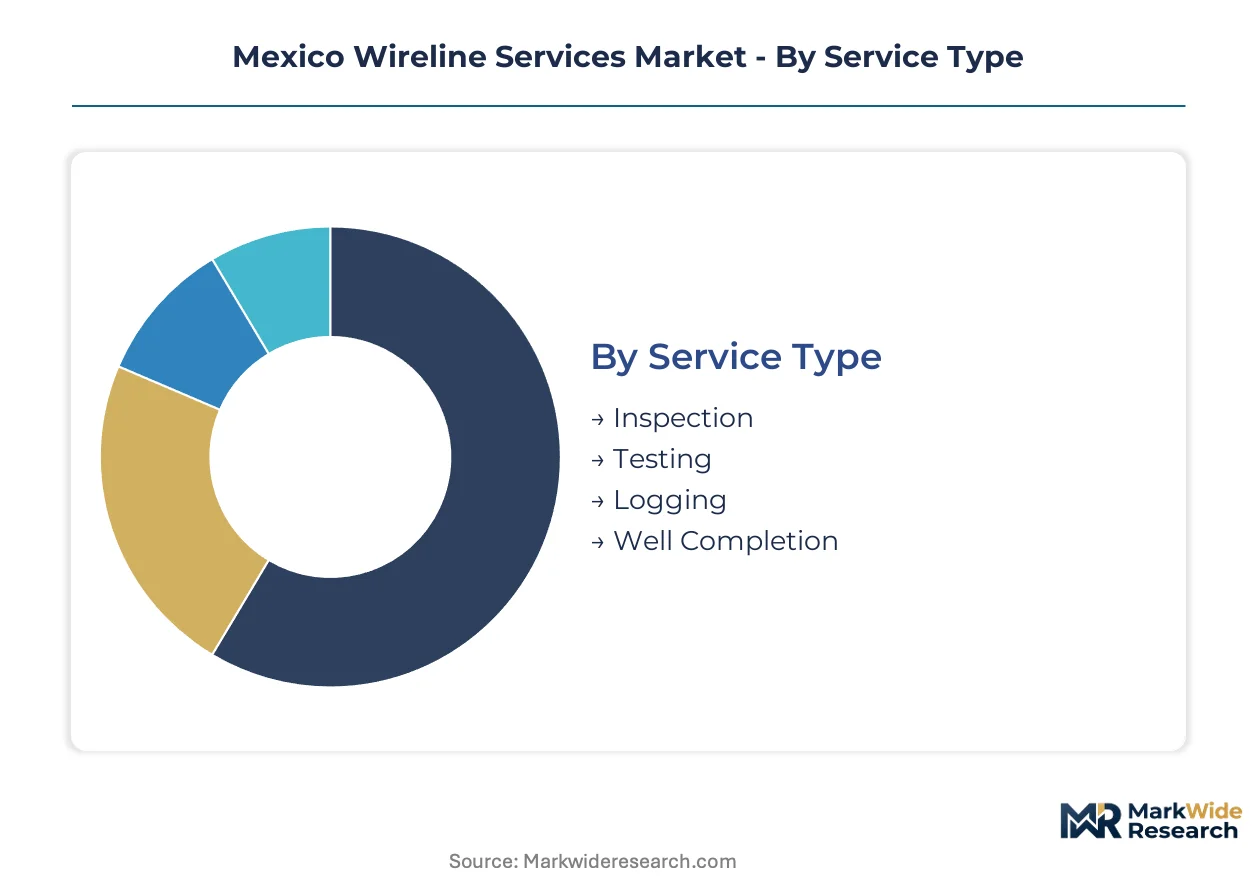
Segmentation in Mexico's wireline services market reveals how operator requirements fragment across technical complexity, regulatory exposure, and asset maturity. Understanding these divides explains why certain service configurations dominate specific basins while others remain niche.
Service Type:
Supply concentration among integrated oilfield service providers has concentrated logging and completion capacity around PEMEX's southern production clusters, while inspection services remain more geographically dispersed.
- Logging:Multi-conductor cable systems deploy gamma ray, resistivity, and acoustic sensors to characterize formation properties in real time. Demand clusters in the Sureste Basin where CNH licensing mandates detailed petrophysical evaluation for offshore blocks.
- Well Completion:Perforating guns, bridge plugs, and packer setting operations finalize wellbore architecture for production. Recurring demand from Chicontepec tight oil development in northern Mexico sustains dedicated cased-hole unit deployment.
- Inspection:Mechanical integrity verification using calipers and corrosion logging tools. Aging infrastructure in Veracruz and Tabasco drives preventive maintenance scheduling.
- Testing:Formation pressure and fluid sampling via wireline-conveyed tools. Limited adoption outside deepwater exploration campaigns.
Well Completion absorbs the bulk of installed capacity; Logging is expanding most quickly.
Application:
Cost tier differentiation separates commodity wireline work from specialized intervention requiring proprietary telemetry systems and certified personnel.
- Oil Extraction:Primary revenue source encompassing reservoir monitoring, stimulation diagnostics, and artificial lift optimization. Burgos Basin shale operators and Sureste Basin conventional producers sustain the highest service intensity.
- Natural Gas:Dry gas developments in northern Mexico require specialized corrosion monitoring and hydrate management. SENER's domestic gas production targets are elevating investment in dedicated wireline programs.
- Water Utilities:Downhole camera inspection and flow profiling for aquifer management. Municipal procurement cycles create lumpy demand compared to hydrocarbon sector continuity.
- Mining:Borehole geophysics and geotechnical logging for mineral exploration. Limited penetration outside precious metals districts in Sonora and Zacatecas.
Oil Extraction commands premium pricing tiers; Natural Gas is climbing the fastest on policy-driven investment.
End User:
Customer type determines contract structure, with national operators favoring long-term framework agreements and private firms preferring project-based procurement.
- Oil & Gas Operators:PEMEX dominates procurement volume through integrated service contracts spanning multiple well intervention disciplines. International consortiums operating CNH-licensed blocks drive technology upgrade requirements.
- Utility Companies:CFE and state water authorities deploy wireline for geothermal well maintenance and aquifer characterization. Budget constraints limit service sophistication compared to hydrocarbon sector standards.
- Mining Firms:Junior exploration companies and major producers alike use wireline for resource definition drilling. Cyclical commodity prices compress contract durations during downturns.
- Environmental Agencies:Regulator-mandated groundwater monitoring and abandoned well plugging. NOM certification requirements for explosive tools create vendor qualification barriers.
Oil & Gas Operators generate the dominant share of contract value; Utility Companies are gaining procurement sophistication.
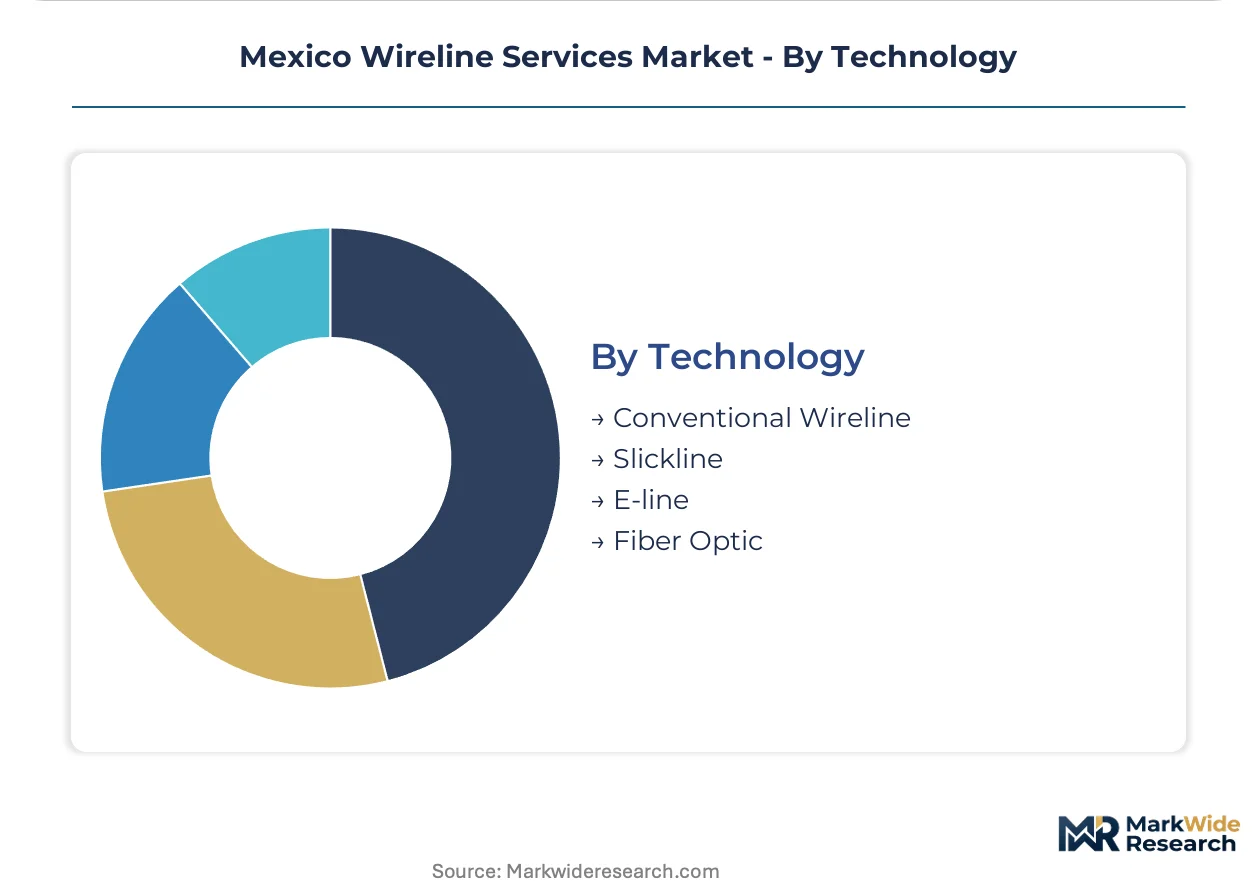
Technology:
Technology maturity curves separate established mechanical systems from digital telemetry platforms requiring specialized engineering support.
- E-line:Real-time data transmission via multi-conductor cables enables immediate operational decisions during high-risk interventions. PEMEX's deepwater campaigns in Campeche Bay mandate E-line for pressure control operations.
- Slickline:Mechanical wireline without electrical conductors for basic wellbore intervention. Mature well workovers in Tabasco sustain substantial slickline deployment for plug retrieval and gauge cutting.
- Conventional Wireline:Single-conductor electric line for standard logging and perforating. Still prevalent in shallow onshore fields with limited telemetry requirements.
- Fiber Optic:Distributed temperature and strain sensing for continuous wellbore monitoring. Pilot deployments in Sureste Basin thermal recovery projects.
Slickline retains the largest active fleet; E-line is gaining share fastest on real-time data requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's wireline services market operates where domestic hydrocarbon production outpaces local equipment manufacturing, creating persistent import dependency for downhole cables and logging sensors from U.S. suppliers.
Burgos Basin
Shale operators in this northern gas province deploy cased-hole wireline units for fracture diagnostics and multi-stage perforations. SENER's domestic gas production targets channel investment toward tight oil development programs. Reynosa and Piedras Negras field camps sustain dedicated service fleets for Chicontepec formation workovers.
Sureste Basin
Offshore exploration blocks licensed under CNH rounds mandate detailed formation evaluation via E-line telemetry systems. Federal environmental contingency protocols impose closed-loop containment requirements on Campeche Bay contractors. Ciudad del Carmen serves as the logistics hub for deepwater logging campaigns.
Veracruz Production Cluster
Mature well intervention requirements dominate procurement as PEMEX prioritizes rejuvenation over greenfield drilling. NOM certification timelines for pressure-rated equipment create operational scheduling constraints. Coatzacoalcos and Poza Rica host permanent refurbishment facilities for localized cable maintenance.
Tabasco Deepwater Frontier
Untapped reservoirs in this southern sub-basin attract international consortiums advancing exploration drilling with integrated logging-while-drilling packages. CNH technical pre-qualification protocols extend vendor onboarding to 12-18 months. Villahermosa anchors onshore support infrastructure for offshore campaign mobilization.
Nuevo León Industrial Corridor
Equipment import logistics concentrate through Monterrey distribution nodes serving northern basin operators. Cross-border tariff exposure from U.S. manufacturing clusters elevates working capital requirements for cable inventory. Saltillo maintains specialized machining capacity for downhole tool component fabrication.
Mexico Wireline Services Market Competitive Landscape
Capital-heavy integrated service providers compete with asset-light regional specialists for contract awards across Mexico's mature basins. The vendor base stratifies into three tiers: global oilfield service conglomerates with permanent field infrastructure, mid-size intervention specialists deploying mobile units, and domestic maintenance contractors capturing localized workover demand. Market consolidation proceeds through integrated service bundling rather than pure-play acquisition, as operators consolidate vendor relationships around full-intervention accountability. Geographic expansion via permanent camp establishment and strategic partnerships with domestic suppliers represent the dominant competitive vectors.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify capital-intensive positioning through permanent northern Mexico field camps and localized equipment refurbishment capabilities. These entities anchor long-term framework agreements with PEMEX by combining logging, perforating, and remediation disciplines under single-accountability contracts. Regional specialists including Weatherford International plc and Superior Energy Services occupy positions emphasizing mobile deployment flexibility and project-based procurement responsiveness. Domestic entities such as Grupo R and Perfolat represent local-content advantaged archetypes, leveraging SENER partnership mandates for equipment maintenance and personnel training to secure recurring service awards in southern production clusters.
| Leading Market Players |
|---|
| Weatherford International plc |
| Superior Energy Services |
| Schlumberger Limited |
| Grupo R |
| PEMEX |
| Halliburton Company |
| Expro Group |
| Perfolat |
| Baker Hughes Company |
| Others |
Supply & Pricing Matrix
SENER's closed-loop containment mandates for wireline fluid recovery and perforating charge disposal gate both qualified supply access and premium-tier pricing eligibility for service providers operating across Mexico's mature hydrocarbon basins. Operators lacking third-party disposal certifications face exclusion from PEMEX framework agreements, compressing the vendor pool and elevating contract values for compliant incumbents.
Pricing Analysis
Margin tightening in standard-tier wireline services reflects PEMEX's elongated payment cycles stretching beyond 180 days, forcing asset-heavy contractors to absorb working capital costs. Three-tier pricing structure across premium, standard, and economy levels separates integrated logging-while-drilling packages from discrete slickline interventions and basic mechanical workovers. Price differentiation hinges on NOM certification status and real-time telemetry capability, with E-line commands commanding substantial premiums over conventional methods. International consortiums in CNH-licensed blocks exhibit lowest price sensitivity; domestic maintenance contractors face acute cost-down pressure.
Supply Chain Analysis
Dual-sourcing requirements embedded in CNH contractor qualification protocols mandate redundant supplier relationships for pressure-rated cables and logging sensors. Manufacturing concentration rests on the United States, Germany, and Japan for downhole cables, gamma ray detectors, and acoustic measurement tools. Raw material dependencies center on specialty steel alloys for cable armoring, rare-earth elements for sensor components, and high-temperature polymers for insulation systems. Single-source vulnerability persists for fiber-optic distributed sensing systems. Distribution runs through Monterrey logistics nodes serving northern basins and Ciudad del Carmen hubs for Campeche Bay offshore campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's wireline services market occupies a technology-transition phase as E-line telemetry displaces conventional slickline methods across high-temperature completions and deepwater interventions. Real-time data transmission capabilities now determine contract awards in CNH-licensed offshore blocks.
For Market Incumbents: Cement long-term service agreements with PEMEX by bundling logging, perforating, and remediation capabilities under single-accountability contracts. Establish permanent field camps in Veracruz and Tabasco to reduce mobilization costs and capture recurring maintenance-layer revenue. Invest in NOM certification pipelines to defend against emerging domestic competitors leveraging SENER local content incentives. For New Entrants and Emerging Players: Fiber-optic distributed sensing capabilities offer a technology-first wedge into Sureste Basin thermal recovery projects where continuous monitoring replaces periodic wireline interventions. Target Tabasco deepwater frontier exploration campaigns where 12-18 month CNH qualification timelines have delayed incumbent saturation. Pursue partnership structures with established Mexican suppliers to satisfy domestic content mandates and accelerate permit acquisition. For Investors and Strategic Acquirers: SENER's escalating environmental contingency protocols tightening waste handling requirements is the leading indicator that compliance infrastructure will separate acquisition targets from stranded assets. Focus on mid-size intervention specialists with mobile deployment flexibility and existing NOM certifications. Watch for PEMEX capital allocation shifts toward mature field rejuvenation as the signal for intervention service demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| E-line Capability Buildout | Real-time telemetry mandates in CNH offshore licensing rounds displace conventional slickline procurement. |
| Domestic Partnership Formation | SENER local content requirements create structural advantages for service providers with Mexican operational footprints. |
| NOM Certification Investment | Equipment recertification timelines determine operational uptime and contract eligibility for pressure-rated interventions. |
| Digital Twin Integration | Convergence of wireline sensor data with predictive analytics opens subscription-based continuous monitoring revenue. |
| Permanent Field Camp Establishment | Localized refurbishment capabilities in Coatzacoalcos and Poza Rica reduce cross-border logistics exposure. |
Research Methodology
Multi-period observation of PEMEX capital allocation patterns, CNH licensing round outcomes, and SENER regulatory amendments anchored the trend analysis, supplemented by interviews with wireline operations managers, CNH technical qualification officers, PEMEX procurement leads, and equipment refurbishment specialists. Secondary validation drew from SEC 10-K filings of integrated service providers, Mexican federal environmental contingency protocol updates, NOM certification registries, and customs import data for downhole cable shipments. Bottom-up service deployment counts across Burgos and Sureste Basins were triangulated against top-down operator expenditure disclosures.
The input-output matrix framed projections across service type, technology maturity, application intensity, and basin-specific regulatory exposure. Modeled segmentation spanned logging, completion, inspection, and testing services; E-line, slickline, conventional wireline, and fiber-optic technologies; oil extraction, natural gas, water utility, and mining applications; plus end-user contract structures distinguishing national operators from international consortiums. CAGRs were derived from deployment intensity curves and operator expenditure trajectories. Forecast inputs included CNH block award timelines, PEMEX field rejuvenation program announcements, and SENER local content mandate evolution.
Several conditions sit outside the modeled scope, including abrupt shifts in Mexico's energy sovereignty policy, cross-border tariff restructuring affecting cable imports, and PEMEX liquidity crises extending payment cycles beyond operational viability thresholds. Deviation in SENER environmental protocol enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Sidetracking Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Global Shale Gas Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
North America Shale Market
Oil & Gas
Coal Mining Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
North America Oil Storage Market