
 Russian Federation Oil and Gas Midstream Market | 2026-2036
Russian Federation Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Russian Federation Oil and Gas Midstream Market Analytics
Unbundling of midstream service contracts is hardening buyer choice across the Russian Federation. Transneft PJSC dominates trunk pipeline ownership and tariff-setting across the national network. Gazprom PAO anchors gas transmission capacity through its Unified Gas Supply System. NK Rosneft PAO leverages proprietary terminal access to secure export scheduling priority.
The Russian Federation Oil and Gas Midstream encompasses the transportation, storage, and wholesale distribution of crude oil and natural gas between upstream production fields and downstream refineries or export points, typically operating pipelines exceeding 1,000 mm in diameter with operating pressures of 75-100 atmospheres and incorporating cathodic protection systems to prevent corrosion over 10,000+ kilometer networks. Pipelines constitute the backbone infrastructure, with margin pools concentrated in tariff-regulated trunk lines crossing multiple federal districts. Smart Monitoring technology is gaining traction as operators retrofit legacy segments with fiber-optic sensing and SCADA integration to reduce unplanned downtime. Storage Tanks represent mature capacity around key hubs like Novorossiysk and Primorsk, where utilization rates track export schedule volatility.
Rostekhnadzor enforces industrial safety rules for hazardous production facilities, mandating integrity management programs that elevate maintenance spending across pipeline operators. Technical Regulation of the Customs Union TR TS 032/2013 governs pressure equipment design standards, shaping procurement specifications for new compressor stations and storage vessels. Stakeholders must monitor how sanctions-adjusted equipment sourcing strategies affect long-term modernization timelines and spare parts availability for cryogenic and automation systems.
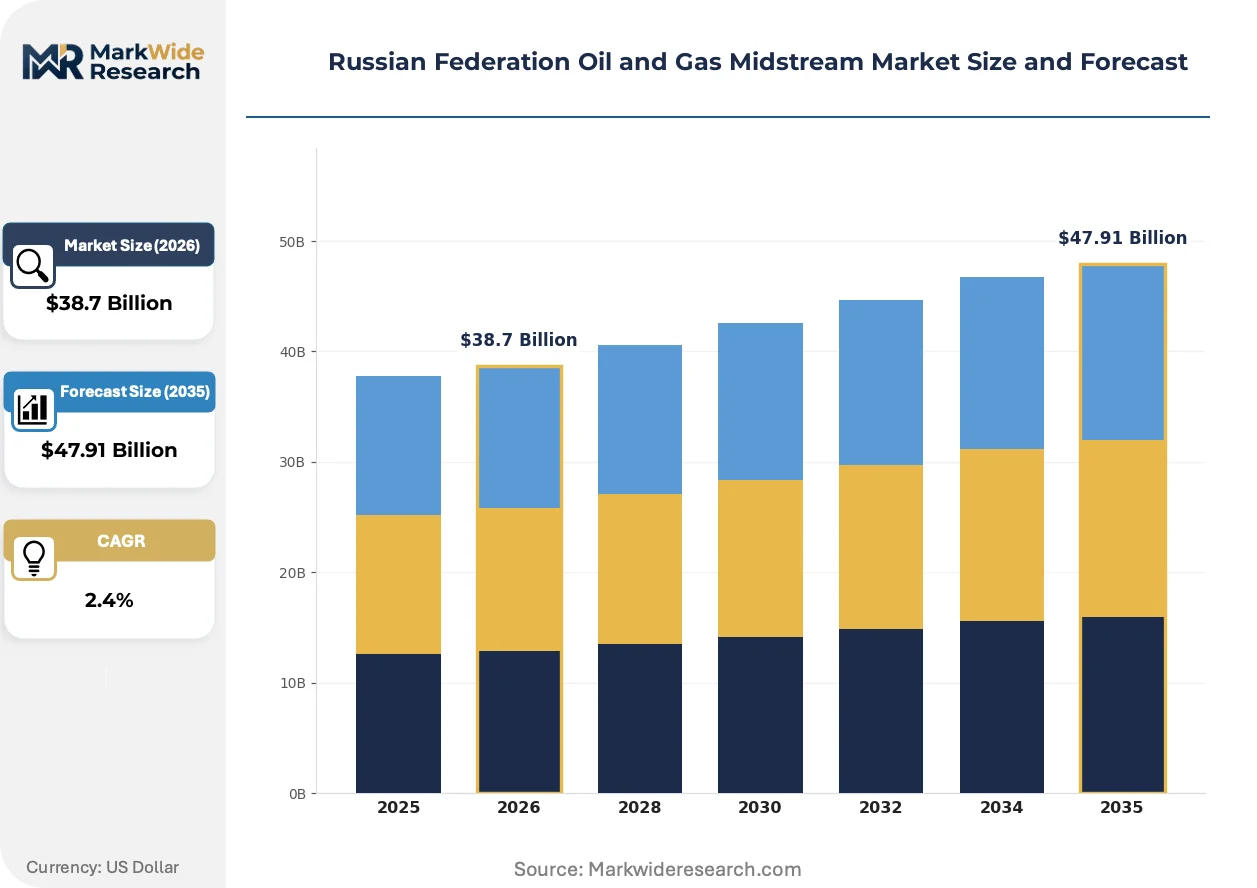
Market Dynamics
Rostekhnadzor's integrity management mandates are forcing wholesale retrofit of legacy pipeline segments across the Russian Federation, compressing maintenance schedules and elevating capital deployment into cathodic protection and fiber-optic monitoring systems.
Growth Catalysts
- Domestic refinery modernization:Upgraded processing units in the Volga-Ural region are expanding offtake requirements from trunk pipeline networks. Tariff-regulated throughput volumes are climbing as capacity utilization rises at key refining clusters.
- Unified Gas Supply System expansion:Gazprom PAO's transmission backbone is absorbing incremental East Siberian production volumes. Compression station additions are extending reach into underdeveloped extraction zones.
- Smart Monitoring retrofit programs:Fiber-optic sensing integration with legacy SCADA infrastructure is reducing unplanned downtime on trunk lines exceeding 1,000 mm diameter. Operators are prioritizing segments with highest corrosion risk profiles.
Market Restraints
- Sanctions-adjusted equipment sourcing:Cryogenic valve and automation component procurement is migrating to non-traditional supplier bases. Spare parts availability timelines are elongating for critical compressor station systems.
- Technical Regulation TR TS 032/2013 compliance costs:Pressure equipment certification requirements are elevating procurement specifications for new storage vessels. Design standard harmonization with Customs Union norms is extending project approval cycles.
- Export corridor concentration:Terminal access at Novorossiysk and Primorsk is scheduling-constrained during peak loading windows. Tank farm utilization volatility tracks crude blend specification changes for Baltic and Black Sea destinations.
Strategic Opportunities
- Volga-Ural legacy infrastructure leverage:Existing pipeline corridors connecting mature fields to upgraded export routes offer lowest-cost capacity expansion pathways. Brownfield optimization is displacing greenfield trunk line construction in capital planning.
- Cathodic protection system convergence:Integration of impressed current systems with real-time corrosion monitoring is extending asset life on 10,000+ kilometer networks. Maintenance interval extension is improving unit economics on aged segments.
- Rostekhnadzor-mandated integrity programs:Regulatory-driven maintenance spending is creating service contract opportunities for specialized inspection and repair contractors. Inline inspection tool deployment is accelerating across hazardous production facilities.
Industry Challenges
- SCADA-legacy system integration:Fiber-optic retrofitting into 1970s-era control architectures is requiring custom protocol bridging. Cybersecurity hardening of operational technology networks is complicating remote monitoring deployment.
- Specialized welding technician scarcity:High-pressure pipeline repair certification requirements are constraining maintenance crew availability. Rostekhnadzor-qualified inspection personnel command premium labor rates across the sector.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russian Federation Oil and Gas Midstream Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipelines, Storage Tanks, Compressors, Terminals Technology: Smart Monitoring, Automation, Leak Detection, Cryogenic Systems End User: Refineries, Industrial Users, Power Plants, Export Markets Service Type: Transportation, Installation, Maintenance, Consulting |
| Companies Covered | Transneft PJSC, Gazprom PAO, NK Rosneft PAO, Novatek PAO, PJSC Lukoil Oil Company, PJSC ANK Bashneft, Surgutneftegas, Tatneft, Sovcomflot, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russian Federation Oil and Gas Midstream Market Evolving Landscape
Digital infrastructure retrofit is compressing maintenance response times across the Russian Federation's aged pipeline network. Automation convergence with legacy mechanical systems is redefining operational staffing models.
Modular compressor station design is modularizing deployment timelines for capacity expansion projects. Independent operators in East Siberia are adopting skid-mounted units to accelerate tie-in schedules. This approach is modularizing project finance structures and reducing site construction labor requirements.
Rostekhnadzor's 2023 amendments to industrial safety rules for hazardous production facilities are mandating predictive maintenance data retention. Pipeline operators must now archive fiber-optic strain monitoring records for decade-long periods. Midstream service providers are responding with cloud-architected data lake solutions purpose-built for regulatory audit trails.
Buyer consolidation among domestic refiners is concentrating offtake negotiation leverage. Large processing groups are unbundling transportation contracts from crude supply agreements. This pattern is most visible in the Volga-Ural region, where integrated refining complexes are securing dedicated pipeline capacity through volume commitment structures.
Russian Federation Oil and Gas Midstream Market Segmentation
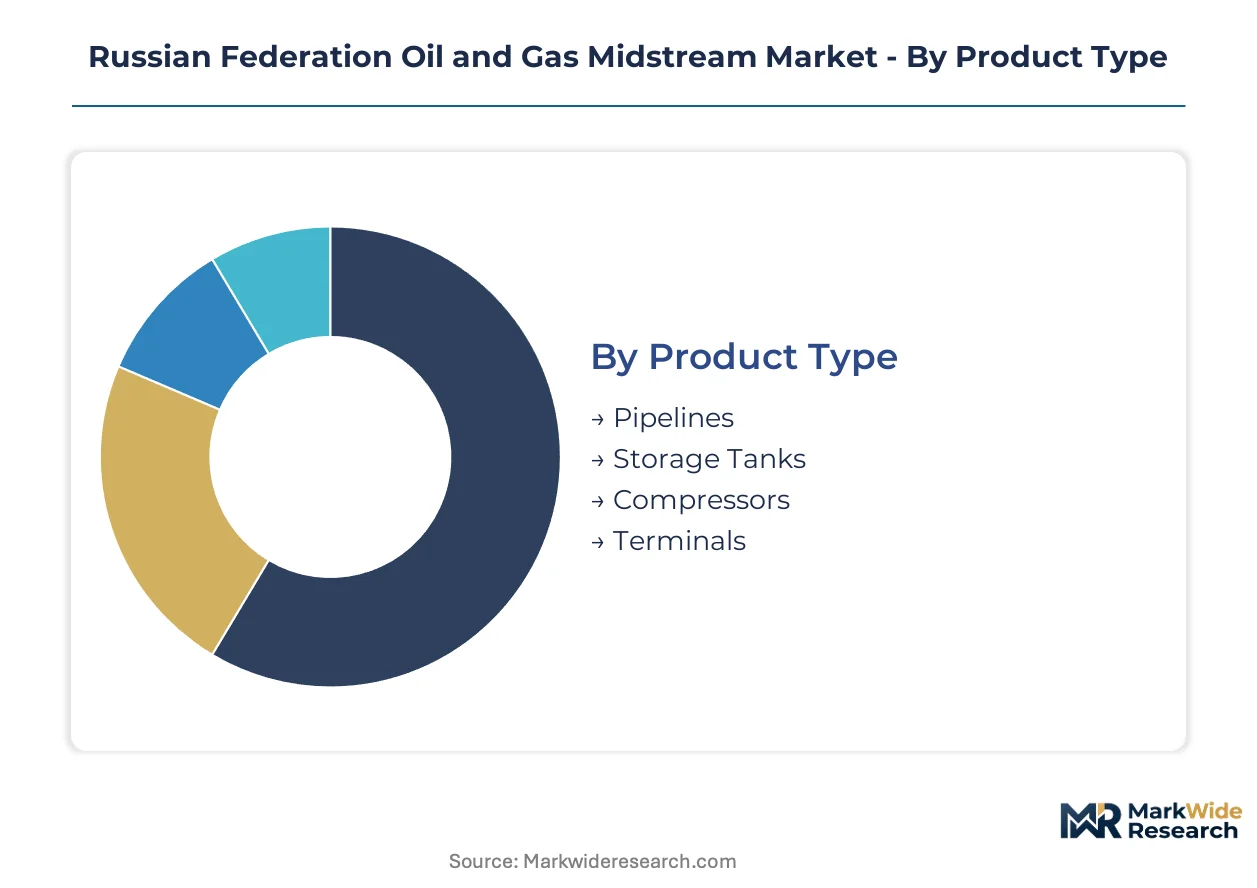
Midstream asset segmentation in the Russian Federation reflects divergent capital intensity profiles and regulatory exposure levels. Infrastructure owners prioritize segments offering tariff-regulated revenue stability, while service providers target integrity management mandates.
Product Type:
Buyers in this category differentiate by throughput scale and connection to export corridors.
- Pipelines:Trunk lines exceeding 1,000 mm diameter operate at 75-100 atmospheres across 10,000+ kilometer networks with cathodic protection systems. Tariff-regulated throughput volumes are climbing at Volga-Ural refining clusters as domestic processing capacity modernizes.
- Storage Tanks:Above-ground and underground vessels at key hubs like Novorossiysk and Primorsk handle crude blend specification changes for Baltic and Black Sea destinations. Utilization rates track export schedule volatility and Rostekhnadzor-mandated inspection cycles.
- Compressors:Station additions extend Unified Gas Supply System reach into East Siberian extraction zones.
- Terminals:Marine loading facilities at Novorossiysk and Primorsk face scheduling constraints during peak windows.
Volume sits with Pipelines; growth tilts toward Storage Tanks.
Technology:
Technology selection correlates with asset age and regulatory compliance pressure.
- Smart Monitoring:Fiber-optic sensing integration with SCADA infrastructure reduces unplanned downtime on corrosion-risk segments. Rostekhnadzor's 2023 amendments mandate predictive maintenance data retention for decade-long archive periods.
- Automation:Protocol bridging between 1970s-era control architectures and modern systems complicates cybersecurity hardening. Custom integration requirements elevate deployment costs on legacy mechanical systems.
- Leak Detection:Real-time pressure anomaly identification supports hazardous production facility safety rules.
- Cryogenic Systems:Valve and component procurement is migrating to non-traditional supplier bases under sanctions-adjusted sourcing strategies.
Deployment concentrates on Smart Monitoring; Automation claims the steepest expansion trajectory.
End User:
End-user concentration varies by connection to domestic processing versus export infrastructure.
- Refineries:Upgraded processing units in the Volga-Ural region are expanding offtake requirements from trunk pipeline networks. Large processing groups unbundle transportation contracts from crude supply agreements.
- Export Markets:Baltic and Black Sea destinations drive tank farm utilization volatility through crude blend specification changes. Terminal access scheduling constraints concentrate during peak loading windows.
- Industrial Users:Petrochemical and manufacturing facilities draw from regional distribution networks.
- Power Plants:Gas-fired generation facilities connect to Gazprom's Unified Gas Supply System backbone.
Throughput volume concentrates at Refineries; contract unbundling favors Export Markets.
Service Type:
Service procurement patterns track regulatory-driven maintenance cycles versus greenfield construction.
- Maintenance:Rostekhnadzor-mandated integrity programs create specialized inspection and repair contract opportunities. Inline inspection tool deployment accelerates across hazardous production facilities with qualified personnel commanding premium labor rates.
- Transportation:Tariff-regulated trunk line access dominates crude and gas movement between production fields and downstream facilities.
- Installation:Modular compressor station design reduces site construction labor requirements in East Siberia.
- Consulting:Regulatory audit trail solutions address fiber-optic strain monitoring data retention requirements.
Revenue stability favors Transportation; margin expansion tilts toward Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's midstream infrastructure spans eleven time zones with production concentrated in West Siberia and East Siberia while consumption clusters in European Russia's industrial belt. This geographic divide shapes pipeline routing priorities and storage hub placement across federal districts.
West Siberia
West Siberian fields feed the bulk of crude exports through the Transneft trunk network. Rostekhnadzor mandates integrity management programs across hazardous production facilities spanning Tyumen and Khanty-Mansi Autonomous Okrug. Surgut and Nizhnevartovsk anchor compression station clusters serving the Unified Gas Supply System.
Volga-Ural
Legacy pipeline corridors from the Volga-Ural region connect mature fields to upgraded Baltic export routes. Technical Regulation TR TS 032/2013 governs pressure equipment standards for refinery offtake infrastructure. Samara and Ufa refining complexes drive tariff-regulated throughput volume growth as domestic processing capacity modernizes.
East Siberia
East Siberian production volumes flow through the Eastern Siberia-Pacific Ocean pipeline system toward Asian markets. Gazprom PAO extends transmission backbone reach through compression station additions in Irkutsk and Yakutia. Skid-mounted modular units accelerate tie-in schedules for independent operators developing remote extraction zones.
Northwest
Primorsk and Ust-Luga terminals handle Baltic Sea crude exports with tank farm utilization tracking blend specification changes. The Northwestern Federal District concentrates marine loading capacity subject to peak window scheduling constraints. Saint Petersburg anchors specialized inspection and repair contractor clusters serving Rostekhnadzor-mandated maintenance programs.
South
Novorossiysk terminal access shapes Black Sea export corridor economics for Caspian and Volga-Ural crude streams. Krasnodar Krai storage capacity faces utilization volatility during refinery maintenance cycles. Rostov-on-Don distribution networks connect to regional petrochemical and manufacturing facilities drawing from pipeline distribution systems.
Russian Federation Oil and Gas Midstream Market Competitive Landscape
The competitive structure tilts toward state-controlled trunk pipeline operators with tariff-regulated revenue stability. Market concentration reflects strategic asset ownership rather than product differentiation. Two archetypes dominate: integrated oil companies leveraging proprietary terminal access and specialized service contractors capturing regulatory-driven maintenance spending. Competitive moves center on brownfield optimization displacing greenfield construction and fiber-optic retrofit programs extending asset life.
Within the state-controlled infrastructure tier, Transneft PJSC and Gazprom PAO occupy positions defining national network access economics. NK Rosneft PAO represents integrated oil company archetypes securing export scheduling priority through captive terminal relationships. These three entities exemplify how asset ownership concentration shapes contract unbundling negotiations with domestic refiners.
| Leading Market Players |
|---|
| Transneft PJSC |
| Gazprom PAO |
| NK Rosneft PAO |
| Novatek PAO |
| PJSC Lukoil Oil Company |
| PJSC ANK Bashneft |
| Surgutneftegas |
| Tatneft |
| Sovcomflot |
| Others |
Value Network & Pricing Analysis
Specialized welding labor costs cascade through maintenance contract tiers as Rostekhnadzor-qualified technicians command premium rates, compressing margins for inspection and repair service providers while elevating tariff-regulated trunk line operating expenditures.
Pricing Analysis
Margin tightening in maintenance services reflects sanctions-adjusted equipment sourcing elongating spare parts timelines. Tariff-regulated throughput pricing dominates crude and gas movement, with volume commitment structures differentiating large refining groups from independent processors. Cost compression intensifies in cryogenic valve procurement as operators migrate to non-traditional supplier bases. Domestic refiners unbundling transportation contracts exhibit highest price sensitivity; state-controlled trunk pipeline operators face lowest.
Supply Chain Analysis
Dual-sourcing mandates for compressor station components now require qualification of domestic and Asian suppliers alongside traditional European sources. Equipment procurement draws from China, South Korea, and India for automation systems and pressure vessels. High-pressure pipeline steel and fiber-optic sensing cables remain critical dependencies. Single-source vulnerability concentrates in legacy SCADA protocol bridging technology. Distribution runs through Transneft's national trunk network and Gazprom's Unified Gas Supply System.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russian Federation midstream operators are accelerating vertical-integration into specialized inspection and repair capabilities to capture regulatory-driven maintenance spending.
For Market Incumbents: To counter sanctions-adjusted equipment sourcing delays, Transneft and Gazprom should deepen backward integration into domestic compressor manufacturing and expand in-house fiber-optic monitoring system production. Securing captive supply of cryogenic valves and automation components mitigates spare parts availability risk. For New Entrants and Emerging Players: The price-point gap between premium Rostekhnadzor-certified maintenance crews and economy-tier general contractors creates entry opportunity in East Siberia's modular compressor station market. Independent operators developing remote extraction zones offer most penetrable demand for skid-mounted unit deployment and specialized welding services. For Investors and Strategic Acquirers: Acceleration in fiber-optic strain monitoring data retention mandates is the leading indicator that cloud-architected regulatory audit trail solutions will command sustained contract flow. Target service providers with decade-long data lake infrastructure and qualified inspection personnel rosters. Watch for Rostekhnadzor amendments expanding predictive maintenance archive requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Cathodic Protection System Convergence | Integration of impressed current with real-time corrosion monitoring extends asset life on 10,000+ kilometer networks. |
| Smart Monitoring Retrofit Programs | Fiber-optic sensing deployment reduces unplanned downtime on high-risk trunk line segments. |
| Modular Compressor Station Design | Skid-mounted units accelerate tie-in schedules for East Siberian independent operators. |
| Integrity Management Service Expansion | Rostekhnadzor-mandated programs create specialized inspection contract opportunities. |
| Domestic Equipment Manufacturing Scale-Up | Backward integration into valve and automation component production mitigates sourcing risk. |
Research Methodology
Document review covered pipeline operator annual disclosures, Rostekhnadzor regulatory filings, and Customs Union technical regulations, complemented by interviews with trunk line maintenance directors, compressor station procurement leads, and specialized inspection contractors. Secondary validation drew from Transneft tariff submissions, Gazprom transmission capacity reports, and federal district energy statistics. Bottom-up segment sizing triangulated against top-down infrastructure capacity assessments.
Cross-referencing historical throughput trends with panel input from Volga-Ural refining cluster managers anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, technology deployment stage, end-user concentration, and regional federal district. CAGRs derived from tariff-regulated revenue stability patterns and brownfield optimization capital deployment trajectories. Integrity management spending curves and export corridor utilization volatility informed forecast boundaries.
Inputs from Rostekhnadzor enforcement records and pipeline operator maintenance disclosures were available through the study window; gaps in sanctions-adjusted supplier migration timelines introduce uncertainty bands around equipment procurement cost assumptions. Forecasts reflect documented integrity program mandates and brownfield investment priorities. Deviation in Customs Union technical regulation harmonization schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
China Oil and Gas Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market