
 Oil and Gas Digital Rock Analysis Market | 2026-2036
Oil and Gas Digital Rock Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Digital Rock Analysis Market Analytics
North America's shale corridor is rewriting competitive dynamics for digital rock laboratories. Schlumberger Limited leverages proprietary imaging workflows to anchor its position in Permian basin core analysis. Core Laboratories N.V. sustains technical credibility through specialized reservoir characterization protocols. Thermo Fisher Scientific Inc. competes on instrument precision across scanning electron microscopy platforms.
Oil and Gas Digital Rock Analysis encompasses high-resolution imaging and computational modeling of reservoir rock samples to derive porosity, permeability, and fluid distribution properties, typically employing micro-CT scanners achieving sub-micron voxel resolution and digital image processing algorithms for three-dimensional pore network reconstruction. Computed Tomography systems dominate capital expenditure allocation due to throughput advantages in commercial core flooding facilities. Scanning Electron Microscopy segments command premium pricing where clay mineralogy and diagenetic fabric interpretation determine completion design. Software Solutions within the service type dimension accumulate recurring revenue as operators integrate digital twin architectures with legacy petrophysical databases.
EPA underground injection control regulations shape data retention requirements for CO2-enhanced recovery projects, while NHTSA pipeline safety standards indirectly pressure upstream operators toward more granular rock mechanics documentation. ISO 17025 accreditation frameworks govern laboratory quality management for core analysis providers seeking international operator contracts. Stakeholders must weigh instrument refresh cycles against cloud-based analysis outsourcing as artificial intelligence training datasets reshape technical staffing models.
Market Dynamics
Permian basin operators are consolidating digital rock analysis contracts under long-term framework agreements, compressing vendor margins while demanding integrated micro-CT and SEM workflows that span exploration through completion design.
Growth Catalysts
- EPA Class VI well permitting:Carbon sequestration projects in Texas and Louisiana require quantitative mineralogy and caprock integrity assessments that digital rock laboratories provide.
- Machine learning training datasets:Operators in the Bakken formation are commissioning high-resolution pore network models to populate reservoir simulation algorithms.
- Horizontal well density:Pad drilling in the Delaware sub-basin multiplies core sample throughput requirements for commercial laboratories.
Market Restraints
- Helium supply concentration:SEM-EDS microanalysis depends on cryogenic cooling systems vulnerable to Qatar and Russia supply disruptions.
- Micro-CT detector lead times:German and Japanese sensor manufacturers maintain 14-18 month order backlogs that constrain laboratory expansion.
- Substitution by wireline logging:Dielectric and nuclear magnetic resonance tools capture some porosity-permeability workflows without core extraction.
Strategic Opportunities
- Methane emissions accounting:EPA greenhouse gas reporting rules create demand for kerogen maturity and gas-in-place quantification in the Powder River basin.
- Digital twin integration:Convergence of cloud-based visualization platforms with legacy petrophysical databases enables recurring software revenue streams.
- Geothermal reservoir characterization:Hot dry rock projects in Nevada and Utah require high-temperature capillary pressure analysis that extends service portfolios.
Industry Challenges
- Petrophysicist specialization gap:Image processing and computational geoscience skill sets command salary premiums that strain mid-size laboratory staffing models.
- ISO 17025 accreditation timelines:New market entrants face 18-24 month quality management system implementation before securing operator contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Digital Rock Analysis Market |
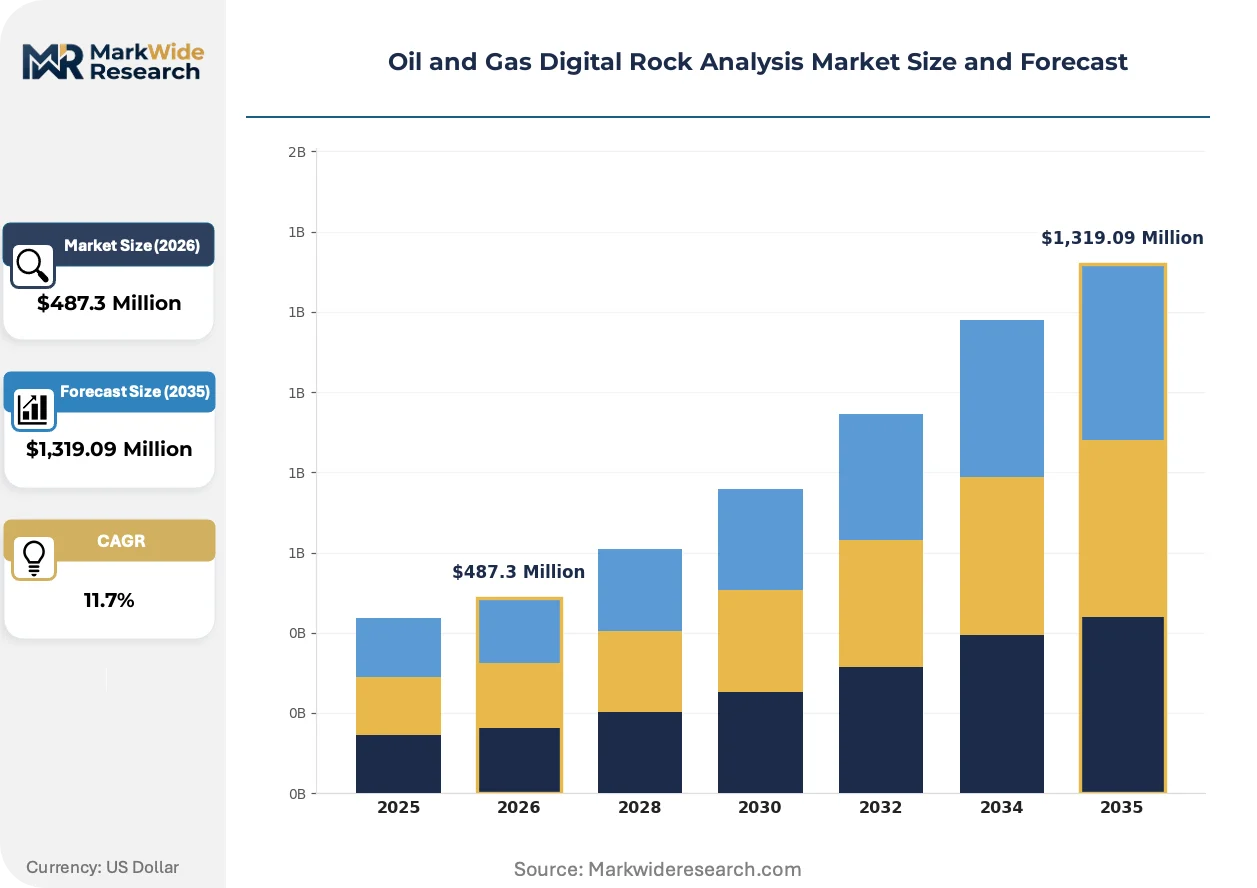
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computed Tomography, Scanning Electron Microscopy, Micro-CT, Digital Image Processing Application: Reservoir Characterization, Well Log Analysis, Production Optimization, Enhanced Oil Recovery End User: Oil Producers, Research Institutions, Service Providers, Academia Service Type: Consulting, Data Acquisition, Analysis Services, Software Solutions |
| Companies Covered | Schlumberger Limited, Halliburton Company, Core Laboratories N.V., Baker Hughes Co., Thermo Fisher Scientific Inc., Intertek Group plc, CGG SA, iRock Technologies Co. Ltd., Math2Market GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Digital Rock Analysis Market Evolving Landscape
Artificial intelligence is compressing interpretation timelines while regulatory pressure on carbon accountability expands the addressable market for quantitative mineralogy services.
Time-of-flight secondary ion mass spectrometry is collapsing the resolution gap between SEM-based mineral maps and bulk geochemical assays. Unconventional operators in the Midland basin are adopting this technology to fingerprint organic matter heterogeneity across lateral well sections. The resulting spatial datasets are collapsing the number of laboratory tests required to characterize a single pad development.
EPA methane performance standards are mandating more granular documentation of gas saturation and caprock seal capacity for new well completions. This regulatory pressure is redirecting capital toward laboratories with accredited CO2-brine-rock interaction protocols. Service providers in Texas and New Mexico are responding by expanding high-pressure mercury injection capabilities.
Subscription-based software licensing is displacing perpetual license sales across digital rock analysis platforms. Independent operators in the DJ basin are consolidating vendor relationships under enterprise agreements that bundle cloud storage, image processing, and technical support. This procurement consolidation is most visible among Permian-focused private equity-backed producers seeking to standardize reporting formats across portfolio companies.
Oil and Gas Digital Rock Analysis Market Segmentation
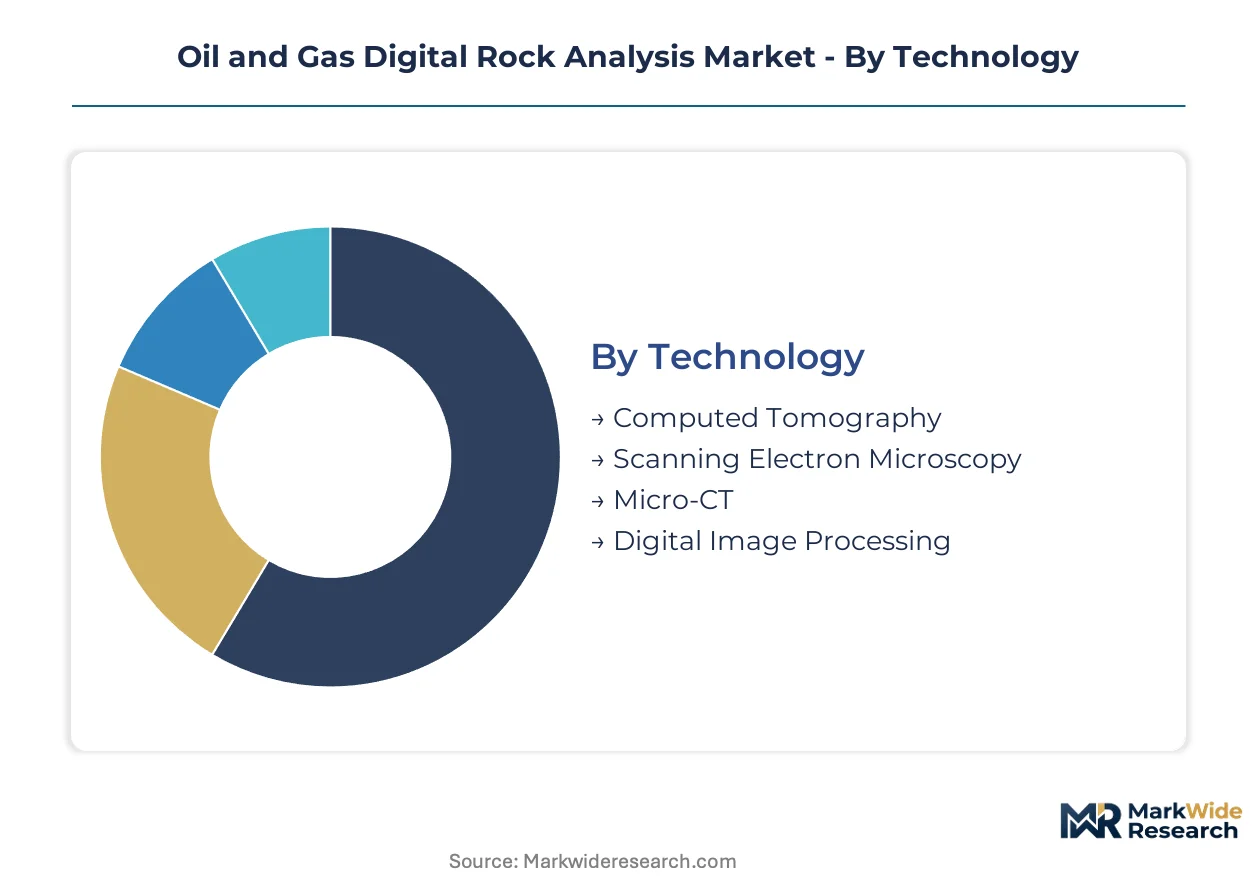
Digital rock analysis procurement splits across four dimensions that determine contract structure and margin capture. Technology choices lock in capital intensity for laboratories. Service type selection shapes whether revenue recurs or remains project-based.
Technology:
Cycle times vary sharply: micro-CT scanners refresh every 5-7 years while software algorithms update quarterly.
- Computed Tomography:Industrial CT systems with sub-micron resolution anchor commercial core flooding facilities. Permian basin operators specify CT throughput rates that favor German detector manufacturers with 14-month order backlogs.
- Scanning Electron Microscopy:Field emission SEM platforms resolve clay mineralogy and diagenetic fabric at nanometer scale. Bakken formation completion designs depend on SEM-EDS quantification of brittle-ductile transition zones.
- Micro-CT:Benchtop systems serve research institutions with lower throughput requirements. University core repositories in Texas and Oklahoma deploy these for student training workflows.
- Digital Image Processing:Pore network reconstruction algorithms run on GPU clusters. Cloud-based processing is displacing on-premise installations among mid-size operators.
Computed Tomography dominates installed base. Digital Image Processing is where expansion concentrates.
Application:
Cost tiers separate exploration budgets from production optimization spend.
- Reservoir Characterization:Integrated static models combining core-derived porosity-permeability with seismic inversion. Delaware sub-basin appraisals require hundreds of samples per pad development.
- Well Log Analysis:Core-to-log calibration for dielectric and nuclear magnetic resonance tool validation. Midland basin operators use this to reduce core extraction frequency.
- Production Optimization:Real-time fracture network modeling based on initial core characterization. Refracturing candidates in the Eagle Ford formation select targets using archived digital rock data.
- Enhanced Oil Recovery:CO2-brine-rock interaction protocols for carbon sequestration projects. EPA Class VI permitting in Louisiana drives accredited laboratory demand.
Reservoir Characterization commands the largest absolute spend. Enhanced Oil Recovery is climbing the fastest.
End User:
Customer type determines pricing power and contract duration.
- Oil Producers:Integrated majors and independents commission multi-year framework agreements. Permian-focused private equity-backed producers standardize reporting formats across portfolio companies.
- Research Institutions:National laboratories maintain core repositories with legacy sample archives. Strategic Petroleum Reserve characterization projects generate steady contract flow.
- Service Providers:Wireline logging companies outsource specialized imaging to accredited laboratories. Third-party validation requirements support ISO 17025-certified vendors.
- Academia:University consortia pool funding for shared instrument access. Society of Petroleum Engineers student chapters drive training-oriented demand.
Oil Producers dominate contract value. Service Providers are where expansion concentrates.
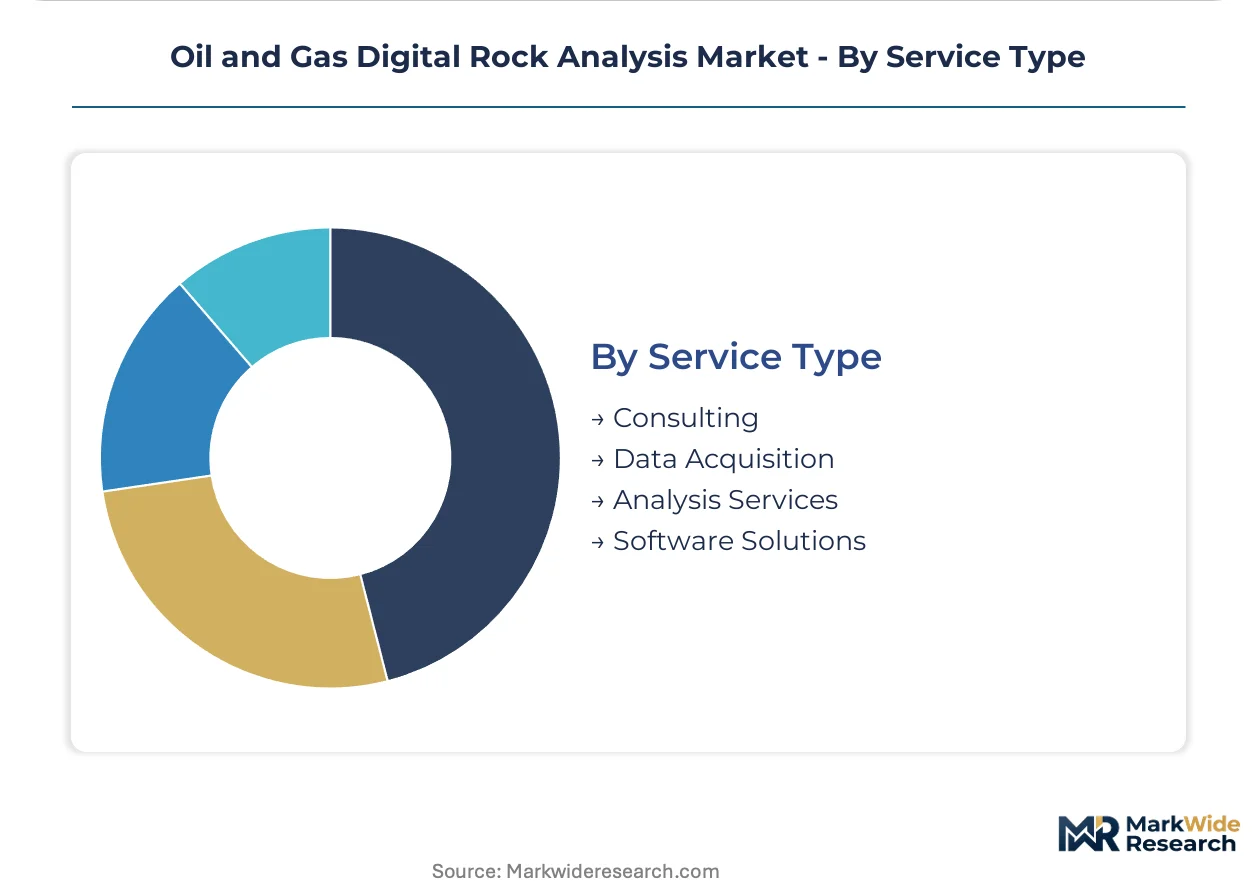
Service Type:
Margin structure separates labor-intensive fieldwork from scalable software licensing.
- Consulting:Petrophysicist-led interpretation of complex diagenetic fabrics. Image processing and computational geoscience skill sets command salary premiums that strain mid-size laboratory staffing.
- Data Acquisition:Core scanning and sample preparation workflows. Commercial laboratories in Houston and Denver compete on turnaround time for pad drilling programs.
- Analysis Services:Mercury injection capillary pressure and relative permeability derivation. High-pressure capabilities differentiate Texas and New Mexico service providers.
- Software Solutions:Cloud-based visualization platforms with subscription licensing. DJ basin independents consolidate vendor relationships under enterprise agreements bundling storage and support.
Analysis Services dominates current revenue. Software Solutions is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network underwrites United States dominance in digital rock analysis throughput. Core sample logistics from Midland to Houston laboratories depend on this infrastructure density.
United States
EPA Class VI well permitting for carbon sequestration in Texas and Louisiana drives quantitative mineralogy demand. The Bureau of Land Management's geothermal leasing expansion in Nevada requires high-temperature capillary pressure protocols. Houston's Energy Corridor hosts the densest concentration of commercial laboratories serving Permian and Bakken operators.
Canada
Montney formation tight gas appraisal in Alberta and British Columbia accelerates micro-CT scanning contracts. Natural Resources Canada's carbon capture tax credits redirect capital toward accredited CO2-brine-rock interaction facilities. Calgary's downtown core anchors service provider headquarters for Western Canada Sedimentary Basin characterization.
Norway
Equinor's Johan Sverdrup digital twin initiatives mandate pore network model integration with legacy petrophysical databases. The Norwegian Petroleum Directorate's reservoir data reporting standards enforce ISO 17025 laboratory accreditation for offshore core analysis. Stavanger's Forus industrial district concentrates specialized imaging service providers.
Saudi Arabia
Saudi Aramco's unconventional gas program in the Jafurah basin commissions high-resolution SEM workflows for shale brittleness assessment. The Ministry of Energy's local content requirements pressure international laboratories toward joint ventures with Saudi entities. Dhahran's King Abdulaziz Center for World Culture vicinity clusters emerging digital rock capabilities.
China
Sinopec's Fuling shale gas development in Sichuan province multiplies core sample throughput requirements for domestic laboratories. The Ministry of Natural Resources' geological data sharing regulations shape proprietary imaging workflow investments. Beijing's Zhongguancun technology corridor hosts software developers specializing in GPU-accelerated pore network reconstruction.
Oil and Gas Digital Rock Analysis Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the instrument supply chain. The vendor base organizes around three strata: full-service energy technology conglomerates, precision instrument manufacturers, and specialized reservoir characterization boutiques. Two strategic archetypes dominate competitive positioning—integrated workflow providers bundling hardware, software, and interpretation services versus pure-play laboratories competing on turnaround velocity. Capacity expansion in high-pressure mercury injection capabilities and strategic partnerships for cloud-based visualization licensing represent the dominant competitive moves.
Within the integrated energy technology tier, Schlumberger Limited and Halliburton Company exemplify platform-scale positioning. Core Laboratories N.V. occupies a position representing specialized reservoir characterization boutiques. Thermo Fisher Scientific Inc. anchors the precision instrument manufacturer archetype.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Core Laboratories N.V. |
| Baker Hughes Co. |
| Thermo Fisher Scientific Inc. |
| Intertek Group plc |
| CGG SA |
| iRock Technologies Co. Ltd. |
| Math2Market GmbH |
| Others |
Value Network & Pricing Analysis
Fourteen-month order backlogs for German and Japanese micro-CT detectors signal acute undercapacity in precision imaging hardware, compressing laboratory expansion timelines while emboldening incumbent service providers to extend contract durations and tighten pricing discipline on bundled interpretation workflows.
Pricing Analysis
ISO 17025 accreditation dictates the pricing tier structure across commercial laboratories, separating accredited providers commanding project premiums from uncertified competitors competing on turnaround velocity alone. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification status, instrument resolution specifications, and bundled software licensing terms. Cost compression in the standard tier is intensifying because pad-drilling operators in the Permian consolidate procurement under enterprise frameworks. Private equity-backed producers exhibit the sharpest price sensitivity, while national laboratories demonstrate the least.
Supply Chain Analysis
Export control regimes restricting semiconductor lithography equipment to China indirectly constrain detector manufacturing capacity for micro-CT systems, as sensor fabrication draws from the same specialized foundry networks. Supply concentrates in Germany, Japan, and the United States for precision detector arrays, helium cryogenic systems, and GPU clusters for pore network reconstruction. Single-source vulnerability runs through Qatar and Russia for helium supply to SEM-EDS cooling systems. Distribution runs through Houston's Energy Corridor for North American core logistics, with satellite facilities in Denver and Calgary serving regional shale basins.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EPA Class VI permitting for carbon sequestration projects creates first-mover advantages for laboratories with accredited CO2-brine-rock interaction protocols.
For Market Incumbents: Insulate core revenue streams by embedding proprietary imaging workflows into operator digital twin architectures, creating switching costs that resist substitution by wireline logging technologies. Accelerate backward integration into cloud-based visualization platforms to capture recurring software revenue and defend margin position against pure-play laboratories competing on turnaround velocity alone.
For New Entrants and Emerging Players: Geothermal reservoir characterization projects in Nevada and Utah represent the most penetrable entry point, as established competitors underinvest in high-temperature capillary pressure capabilities. Mid-size operators in the DJ basin seeking to consolidate vendor relationships under enterprise agreements offer a secondary beachhead. Lead with subscription-based software licensing bundled with technical support to bypass capital-intensive instrument acquisition barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-centric service providers as cloud-based processing displaces on-premise GPU clusters. The five-to-ten-year viability window favors acquisition targets with ISO 17025 accreditation and established relationships with Permian-focused private equity-backed producers. Watch helium supply diversification efforts as an inflection indicator for SEM-dependent laboratory valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | EPA Class VI permitting requirements in Texas and Louisiana mandate accredited laboratory protocols for carbon sequestration projects. |
| Cloud-Based Visualization Platform Launch | Subscription licensing models in the DJ basin displace perpetual sales and generate recurring revenue from independent operators. |
| Helium Supply Diversification Partnership | Qatar and Russia supply concentration for SEM-EDS cooling systems creates vulnerability that strategic sourcing agreements mitigate. |
| Geothermal Capability Expansion | Bureau of Land Management leasing expansion in Nevada requires high-temperature capillary pressure analysis extending service portfolios. |
| Digital Twin Integration Agreement | Equinor's Johan Sverdrup initiatives in Norway mandate pore network model integration with legacy petrophysical databases. |
Research Methodology
Operator-level perspectives from reservoir engineers, petrophysicists, laboratory operations directors, and procurement managers at integrated majors anchored the qualitative base. Primary interviews combined with secondary validation from EPA underground injection control filings, Bureau of Land Management geothermal leasing records, and Society of Petroleum Engineers technical papers. Bottom-up segmentation modeling triangulated against top-down energy expenditure forecasts across the analysis window.
Scenario-bracketing framed the analytical approach, modeling technology adoption curves across Computed Tomography, Scanning Electron Microscopy, and Digital Image Processing segments. Deployment model, operator scale, and regional regulatory framework shaped segmentation dimensions. CAGRs derived from instrument refresh cycles, software update frequencies, and regulatory compliance timelines. Forecast inputs incorporated micro-CT detector order backlogs and helium supply concentration risks.
Macroeconomic conditions sit as an overlay; deviation in oil price volatility and capital expenditure cycles at unconventional operators would shift the trajectory. Forecasts reflect assumptions about EPA methane performance standard enforcement and carbon sequestration project approval velocity. Material shifts in export control regimes for precision sensor technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Smart Well Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Swellable Packers Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Africa Oil Refining Market