
 Latin America Hydraulic Filtration Market | 2026-2036
Latin America Hydraulic Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Hydraulic Filtration Market Foresight
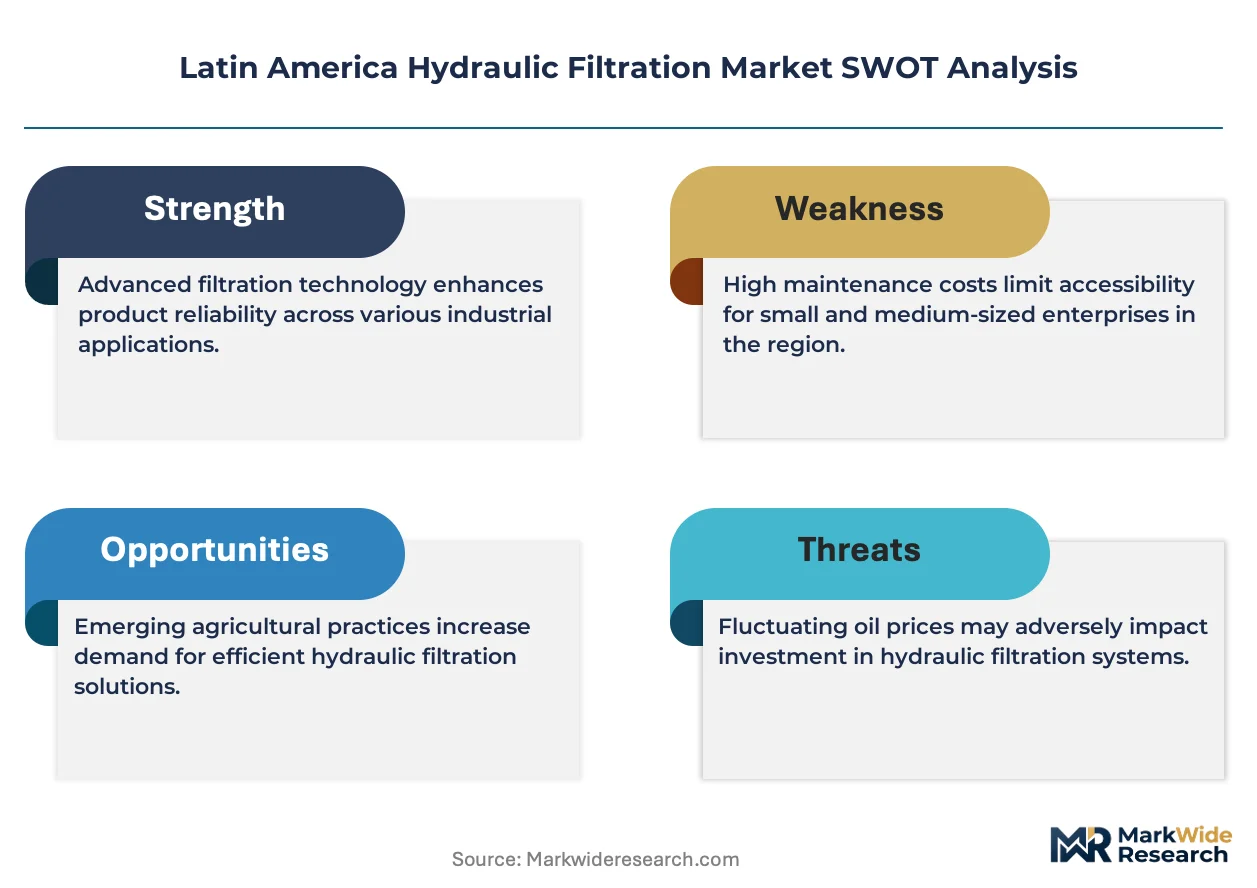
Asset-light leasing models for construction and agricultural machinery are tilting procurement decisions toward lifecycle filtration contracts rather than spot purchases. Parker Hannifin Corporation leverages its regional distribution network to secure multi-year service agreements with Brazilian rental fleets. MANN+HUMMEL Group anchors its position through backward integration into filter media production, cutting lead times for cartridge replacements. Eaton Corporation competes on hydraulic system integration, bundling filtration with valve and pump packages for Mexican industrial customers.
Latin America hydraulic filtration encompasses pressure, return, and offline filter assemblies designed to remove particulate contamination from hydraulic circuits, typically rated between 3 and 25 microns absolute depending on system criticality. These components protect pumps, actuators, and control valves from abrasive wear in high-pressure environments spanning 3,000 to 6,000 PSI operational ranges. Spin-on filters dominate aftermarket volume due to standardized thread forms and quick-change protocols favored by mobile equipment operators, while pleated filters capture margin pools in stationary industrial installations where extended service intervals justify higher unit costs. Tank-mounted breathers and suction strainers represent mature categories with limited growth upside across the region's aging sugar mill and pulp machinery base.
Brazil's ANP regulates hydraulic fluid specifications for offshore oil platforms, forcing filter suppliers to certify salt corrosion resistance and high-viscosity cold-start performance. Mexico's PROFEPA enforcement of industrial wastewater standards pushes manufacturing plants toward closed-loop hydraulic systems with enhanced offline kidney-loop filtration. Argentina's INTI quality marks create non-tariff barriers for unverified import brands. Stakeholders must weigh localization investments against currency volatility when sizing inventory for Andean mining corridors.
Market Dynamics
Asset-light machinery leasing across Brazil's construction and agricultural sectors is consolidating procurement power into fleet operators, forcing filter suppliers to abandon spot sales in favor of multi-year lifecycle service contracts with embedded replacement scheduling.
Growth Catalysts
- ANP biofuel blending mandates:Brazil's petroleum regulator is pushing OEMs to redesign hydraulic filter compatibility for alternative fluid chemistries, creating replacement demand across existing installed bases.
- Chilean mining fleet expansion:Copper and lithium operators in the Atacama are extending hydraulic system maintenance intervals through premium filtration upgrades.
- Closed-loop kidney-loop systems:Mexican manufacturing plants are retrofitting offline filtration to meet PROFEPA wastewater enforcement, driving aftermarket assembly sales.
Market Restraints
- Steel and cellulose media cost volatility:Pleated filter manufacturers face margin compression from fluctuating pulp and specialty alloy input prices.
- Import dependency for high-efficiency media:Brazilian producers rely on Asian suppliers for sub-10 micron glass fiber substrates, exposing lead times to shipping bottlenecks.
- Argentina's INTI certification delays:Unverified import brands face non-tariff barriers as quality mark processing stretches to eight months.
Strategic Opportunities
- Colombian Andean mining corridors:Gold and emerald extraction operations remain underpenetrated by premium filtration service networks.
- IoT-enabled condition monitoring:Sensor-integrated filter heads that transmit differential pressure data are converging with predictive maintenance platforms.
- Peruvian government infrastructure stimulus:Public works contracts specify extended equipment warranties requiring OEM-specified filtration protocols.
Industry Challenges
- ISO 4406 cleanliness code certification timelines:Third-party validation for multi-pass testing extends product launch cycles by four to six months.
- Legacy sugar mill machinery integration:Tank-mounted breathers on aging Brazilian ethanol equipment require custom adapter fabrication.
- Cross-border inventory positioning:Currency volatility between real, peso, and sol complicates safety stock sizing for Andean distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Hydraulic Filtration Market |
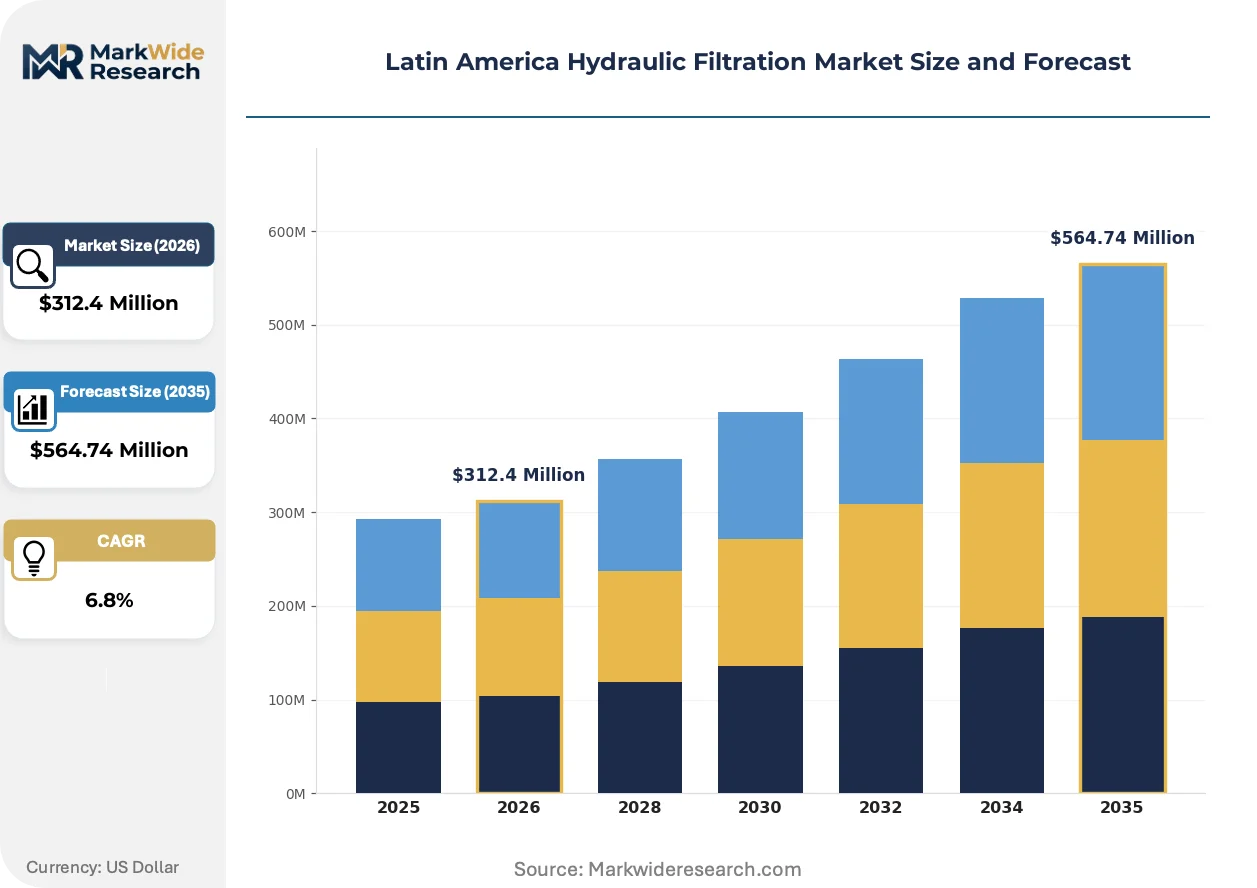
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin-On Filters, Cartridge Filters, Pleated Filters, Tank Filters Application: Construction Equipment, Agricultural Machinery, Automotive Systems, Industrial Machinery End User: Aerospace, Oil & Gas, Manufacturing, Energy Installation: Mobile Equipment, Stationary Equipment, Fixed Installations, Other |
| Companies Covered | Eaton Corporation, MANN+HUMMEL Group, Parker Hannifin Corporation, Filtration Group Industrial, HYDAC, Donaldson Company Inc, Bosch Rexroth Corporation, MP Filtri S.P.A., Pall Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Hydraulic Filtration Market Shifts & Advancements
Synthetic media formulations and smart monitoring systems are compressing replacement intervals while raising performance benchmarks across Latin America's mobile and stationary hydraulic equipment base.
Multilayer synthetic filter media is hybridizing glass fiber and melt-blown polymer layers to achieve beta ratings above 200 at 10 microns without the flow restriction of traditional cellulose. Brazilian sugar harvester fleets are adopting these elements to extend seasonal service windows. The technology is hybridizing cartridge designs previously split between economy cellulose and premium all-glass constructions.
Mexico's PROFEPA enforcement of industrial wastewater discharge standards is mandating closed-loop hydraulic systems with enhanced offline filtration in manufacturing plants. Metalworking and automotive stamping facilities face the steepest compliance deadlines. Assembly suppliers are responding with compact kidney-loop packages sized for existing reservoir footprints.
Fleet operators are consolidating aftermarket purchasing through integrated maintenance management platforms that automate filter replacement scheduling based on operating hours rather than calendar intervals. Brazilian rental companies are unbundling filtration from OEM service agreements to negotiate direct supplier contracts. This pattern concentrates procurement decisions in São Paulo state's machinery rebuild sector.
Latin America Hydraulic Filtration Market Segmentation
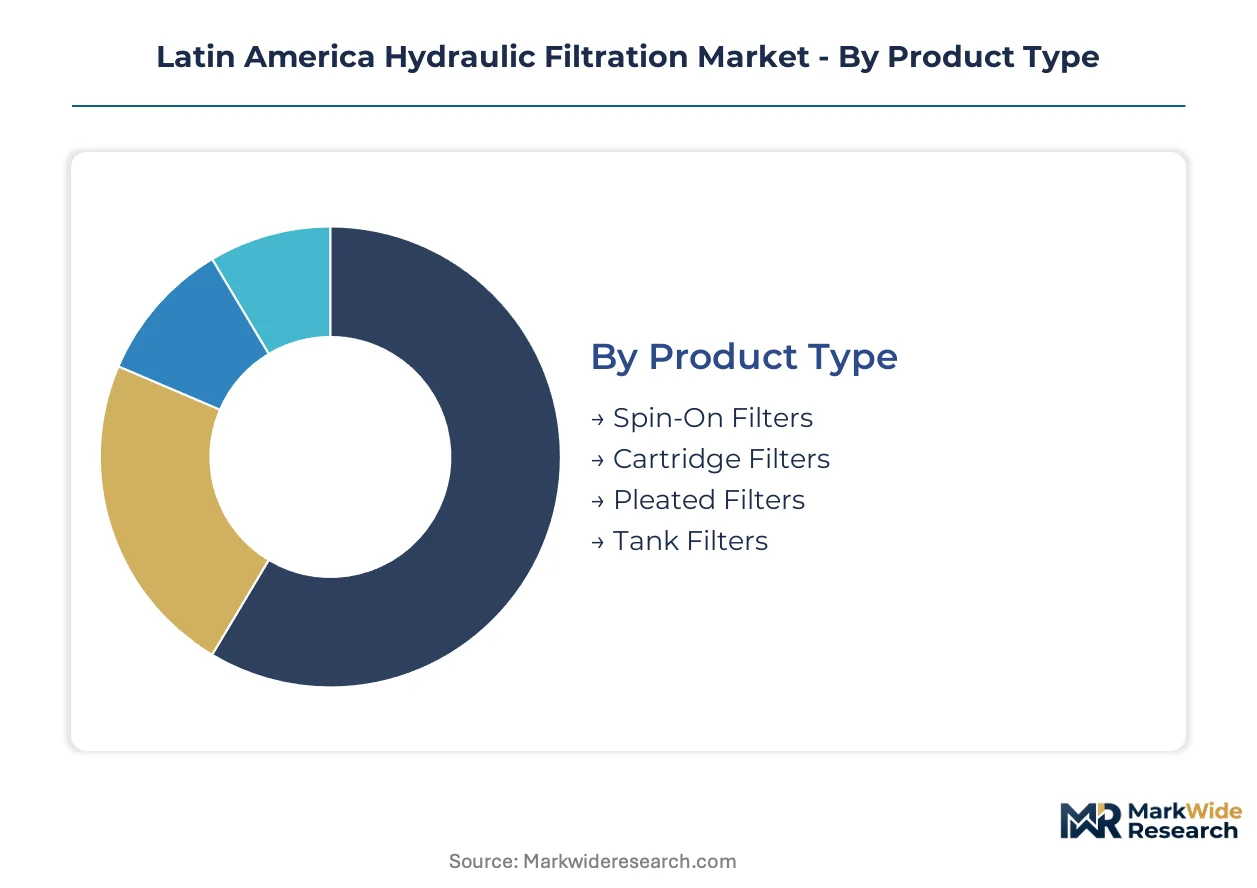
Hydraulic filtration procurement patterns diverge sharply between mobile equipment operators seeking rapid change-out protocols and stationary industrial buyers prioritizing extended service intervals. Segment boundaries increasingly blur as Brazilian rental fleets negotiate lifecycle contracts spanning multiple product categories.
Product Type:
Mature spin-on formats dominate aftermarket volume while synthetic media innovations reshape the emerging premium tier.
- Spin-On Filters:Standardized thread forms enable sub-five-minute replacement cycles critical to Chilean mining fleet uptime commitments. Brazilian construction rental operators specify these for their entire yellow iron fleets, consolidating procurement through São Paulo distributors.
- Cartridge Filters:Modular element designs allow media replacement without housing removal, reducing waste disposal costs for Mexican automotive stamping plants under PROFEPA scrutiny. Demand clusters in kidney-loop retrofit assemblies for closed-loop hydraulic systems.
- Pleated Filters:Achieve beta ratings above 200 at 10 microns through glass fiber substrates.
- Tank Filters:Aging Brazilian sugar mill infrastructure sustues modest replacement demand.
Spin-On Filters handles the majority of throughput; Cartridge Filters is the fastest mover on share.
Application:
Equipment utilization intensity and operating environment severity segment demand across mobile and stationary use cases.
- Construction Equipment:Excavator and loader hydraulic circuits operate at 3,000 to 6,000 PSI in abrasive conditions, driving premium filtration adoption. Chilean copper mine operators specify absolute ratings below 10 microns to extend pump rebuild intervals.
- Agricultural Machinery:Seasonal harvester fleets in Brazil's Center-West tolerate economy cellulose elements during peak operating windows.
- Automotive Systems:Power steering and transmission hydraulic loops require compact filter footprints.
- Industrial Machinery:Metalworking fluid power systems in Mexican manufacturing plants drive offline filtration assembly demand.
Construction Equipment anchors regional volume; Industrial Machinery is expanding most quickly as PROFEPA compliance deadlines approach.
End User:
Regulatory exposure and asset ownership structure determine filtration specification stringency across buyer categories.
- Aerospace:MRO facilities in Brazil service regional airline fleets with OEM-certified elements.
- Oil & Gas:ANP mandates for offshore platform hydraulic fluids force salt corrosion resistance certification.
- Manufacturing:Mexican automotive stamping and appliance plants retrofit kidney-loop filtration to meet wastewater discharge standards.
- Energy:Hydroelectric turbine governor systems in the Andes require cold-start viscosity compatibility.
Manufacturing captures the steepest expansion trajectory; Oil & Gas maintains specification leadership on technical requirements.
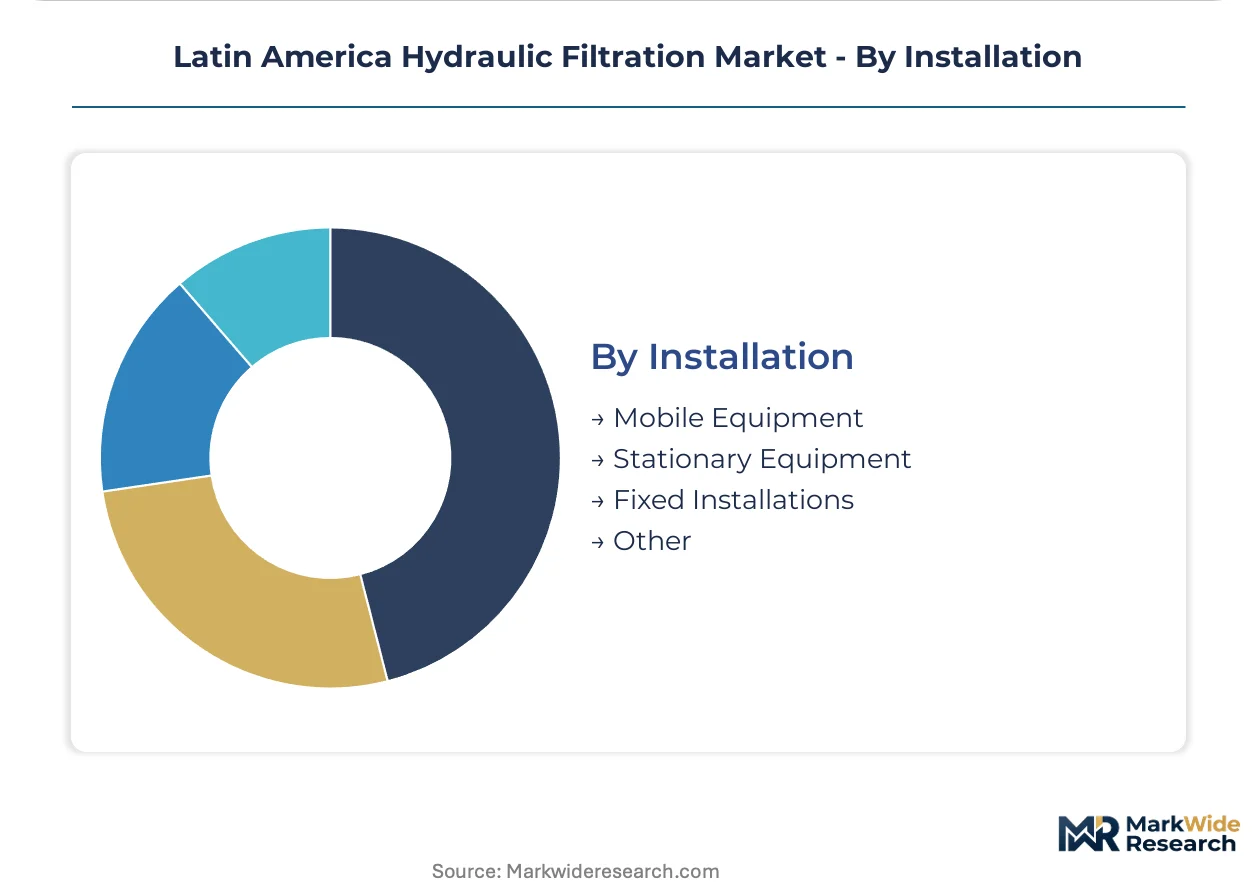
Installation:
Mobility requirements dictate filter housing durability and change-out protocol design.
- Mobile Equipment:Vibration-resistant spin-on housings with integral bypass valves protect against catastrophic pump failure during transport shock.
- Stationary Equipment:Reservoir-mounted duplex configurations enable continuous operation during element service.
- Fixed Installations:Steel mill and pulp processing hydraulic power units specify large-bore return line filters.
- Other:Specialized marine and aviation applications require custom adapter fabrications.
Mobile Equipment generates the highest unit volume; Fixed Installations commands premium pricing on extended-interval specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin America hydraulic filtration trade flows reveal import dependency for high-efficiency media substrates, with Brazilian distributors holding six-month safety stocks to buffer currency volatility against Asian supply chains.
Brazil
ANP biofuel mandates force OEM filter redesigns for alternative hydraulic fluid chemistries, triggering replacement waves across existing sugar harvester and construction fleets. São Paulo state's machinery rebuild sector concentrates procurement power through lifecycle service contracts. The southeastern manufacturing belt absorbs premium cartridge and spin-on volumes.
Mexico
PROFEPA wastewater enforcement drives kidney-loop filtration retrofits in automotive stamping and metalworking plants. Northern border states host maquiladora hydraulic power units requiring compact offline assemblies. Mexico City industrial corridors source duplex reservoir configurations for continuous operation during element service.
Chile
Atacama copper and lithium operators extend pump rebuild intervals through absolute-rated elements below 10 microns. The national mining regulator mandates contamination control protocols for fleet maintenance programs. Antofagasta equipment clusters specify rapid-change spin-on formats to minimize excavation downtime.
Argentina
INTI quality mark processing creates eight-month certification delays for unverified import brands, sheltering local fabricators. Pampas grain harvester fleets tolerate economy cellulose elements during compressed seasonal windows. Córdoba agricultural machinery rebuilders stock standardized thread-form cartridges.
Peru
Government infrastructure stimulus packages specify extended equipment warranties requiring OEM-specified filtration protocols. Andean mining corridors at altitude face cold-start viscosity compatibility requirements for hydroelectric turbine governors. Lima distributors position inventory to capture public works contract spillover.
Latin America Hydraulic Filtration Market Competitive Landscape
On the supply side, the industry is consolidating around multi-year service contracts rather than spot sales, with fleet operators leveraging procurement scale to unbundle filtration from OEM maintenance agreements. Three archetypes dominate: integrated system suppliers bundling filtration with valve and pump packages, media specialists controlling substrate production to compress lead times, and distribution-heavy players securing rental fleet agreements through geographic coverage. Competitive moves center on backward integration into filter media manufacturing and predictive maintenance platform partnerships.
Among the named participants, Parker Hannifin Corporation exemplifies the distribution-intensive archetype through regional network leverage, while MANN+HUMMEL Group anchors the upstream-integrated tier with captive media production. Eaton Corporation occupies a position as a system integrator bundling filtration with broader hydraulic component offerings.
| Leading Market Players |
|---|
| Eaton Corporation |
| MANN+HUMMEL Group |
| Parker Hannifin Corporation |
| Filtration Group Industrial |
| HYDAC |
| Donaldson Company Inc |
| Bosch Rexroth Corporation |
| MP Filtri S.P.A. |
| Pall Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on Asian glass fiber substrates determines both tiered pricing spreads and supply chain shape across Latin American hydraulic filtration. Brazilian distributors carry six-month safety stocks to buffer real volatility against shipping bottlenecks, compressing margins on economy cellulose tiers while insulating premium synthetic media pricing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO 4406 cleanliness code certification and backward integration into media production. Cost compression in standard tiers is intensifying because Brazilian rental fleets consolidate procurement through lifecycle contracts. Fleet operators exhibit the highest price sensitivity, while Chilean mining houses prioritize absolute filtration ratings over unit cost.
Supply Chain Analysis
Glass fiber and specialty alloy feedstock sourcing draws from China, Germany, and Japan for sub-10 micron substrates. Raw material dependencies center on cellulose pulp, borosilicate microfiber, and corrosion-resistant housing alloys. Single-source vulnerability concentrates in Asian glass fiber supply lanes subject to maritime chokepoint risk. Distribution runs through São Paulo state distributors serving the southeastern manufacturing belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light machinery leasing is accelerating filter commoditization, forcing incumbents to defend against unbundling of filtration from OEM service agreements.
For Market Incumbents: Pre-empt rental fleet consolidation by locking multi-year lifecycle contracts before procurement power concentrates further. Secure backward integration into synthetic media production to compress lead times against Asian supply volatility. ANP biofuel mandates threaten compatibility obsolescence across existing installed bases. For New Entrants and Emerging Players: Establish a beachhead in Colombia's underpenetrated Andean mining corridors where premium service networks remain sparse. Target kidney-loop retrofit assemblies for Mexican manufacturing plants facing PROFEPA compliance deadlines. Lead with IoT-enabled condition monitoring as a service differentiator against incumbent spot sales. For Investors and Strategic Acquirers: Brazil's ANP certification requirements for alternative hydraulic fluids reshape the acquisition landscape toward media-capable assets. Five-to-ten year viability favors suppliers with captive substrate production and rental fleet contract visibility. Watch for consolidation signals when currency volatility forces distributor distress sales.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive glass fiber production insulates Brazilian manufacturers from Asian shipping bottlenecks. |
| IoT-Enabled Condition Monitoring Partnerships | Sensor-integrated filter heads converge with predictive maintenance platforms for rental fleets. |
| Multi-Year Lifecycle Service Contracts | São Paulo distributors lock construction fleet procurement away from spot market competitors. |
| ANP Biofluid Compatibility Certification | Regulatory compliance creates replacement demand across sugar harvester installed bases. |
| Colombian Mining Corridor Distribution Buildout | Gold and emerald extraction operations lack premium filtration service network coverage. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads; and secondary validation through customs trade records, ANP regulatory filings, SEC 10-K disclosures from listed filtration suppliers, and Brazilian machinery production databases. Bottom-up equipment population estimates were triangulated against top-down market value assessments.
Forecast inputs span product type, application intensity, end-user regulatory exposure, and installation mobility requirements across the projection horizon. CAGRs were derived from segment-level growth rate blending. Modeled variables include ANP biofuel mandate implementation pace, Chilean mining fleet expansion trajectories, and PROFEPA enforcement intensity in Mexican manufacturing.
Stress conditions across real-peso-sol currency volatility bands, glass fiber supply disruption scenarios, and INTI certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against Brazilian machinery rebuild sector production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Automatic Tank Cleaning Systems Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Centrifugal Pump Market