
 Marine Fuel Injection System Market | 2026-2036
Marine Fuel Injection System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fuel Injection System Market Intelligence
Asian component foundries is recalibrating output schedules to match Tier III engine build rates at Hyundai Heavy and Daewoo yards. Robert Bosch GmbH leverages its common rail intellectual property to anchor high-pressure system supply for medium-speed marine engines. Cummins Inc. competes in the auxiliary power segment through electronically controlled distributor pumps. Yanmar Co. Ltd dominates compact unit injector production for fishing boat propulsion across East Asian waters.
A marine fuel injection system meters, pressurizes, and atomizes fuel into combustion chambers across two-stroke and four-stroke marine engines, operating at injection pressures exceeding 2,000 bar in modern common rail architectures to optimize thermal efficiency and particulate control. The technology serves commercial vessel operators seeking compliance with tightening exhaust emission boundaries while preserving fuel economy across long-haul routes. Common rail configurations command the largest value share among product types due to their enabling role in Tier III NOx reduction strategies. Electronic control technology is displacing mechanical governor systems as shipowners prioritize real-time combustion optimization and remote diagnostics capability. Commercial vessels represent the dominant application segment, though offshore support vessels are generating disproportionate technology upgrade intensity per hull.
The International Maritime Organization enforces MARPOL Annex VI emission standards that mandate sulfur oxide limits and nitrogen oxide tier reductions, directly conditioning fuel injection hardware specifications for newbuild engines. The EPA coordinates with the U.S. Coast Guard on engine certification protocols affecting imported marine powertrains. The EU Green Deal extends carbon pricing pressure into maritime transport through FuelEU Maritime regulations, tightening allowable greenhouse gas intensity per voyage. Stakeholders must monitor how regional enforcement divergence between IMO global standards and EU unilateral measures reshapes engine platform standardization decisions.
Market Dynamics
Container shipping lines are accelerating fleet renewal programs to comply with IMO 2020 sulfur caps and incoming Tier III NOx standards, concentrating procurement demand around South Korean shipyards and their captive engine supplier networks.
Growth Catalysts
- IMO Tier III NOx mandates:Newbuild two-stroke engines require high-pressure common rail architectures to achieve nitrogen oxide reduction targets in emission control areas.
- Container fleet renewal:Major shipping lines are replacing aging hulls with fuel-efficient vessels, creating sustained order backlogs at Hyundai Heavy and Daewoo yards.
- Dual-fuel engine proliferation:Methanol-ready and ammonia-capable propulsion systems demand upgraded injection hardware with multi-fuel compatibility.
Market Restraints
- High-pressure component scarcity:Precision machining capacity for common rail rails and injectors concentrates among German and Japanese specialist suppliers.
- Steel alloy price volatility:Specialized martensitic stainless grades for injector nozzles face input cost swings tied to nickel and chromium markets.
- Extended engine certification cycles:EPA and U.S. Coast Guard protocols for medium-speed marine powertrains add 12-18 months to new platform validation.
Strategic Opportunities
- Retrofit aftermarket expansion:Existing vessel fleets require Tier III-equivalent injection upgrades to extend operational licenses in ECAs, opening hardware conversion demand.
- FuelEU Maritime compliance:EU carbon intensity regulations create premium positioning for injection systems enabling alternative fuel combustion.
- Remote diagnostics integration:Real-time combustion monitoring via satellite-linked engine control modules enables predictive maintenance service contracts.
Industry Challenges
- Common rail IP licensing complexity:Bosch's patent portfolio for high-pressure marine architectures forces competitors into costly cross-licensing or design-around engineering.
- Calibration specialist shortage:Electronic control unit mapping for multi-fuel marine engines requires scarce combustion engineering expertise concentrated at engine OEMs.
- Legacy mechanical governor obsolescence:Shipyards face integration complexity when mating electronic injection systems with existing vessel automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fuel Injection System Market |
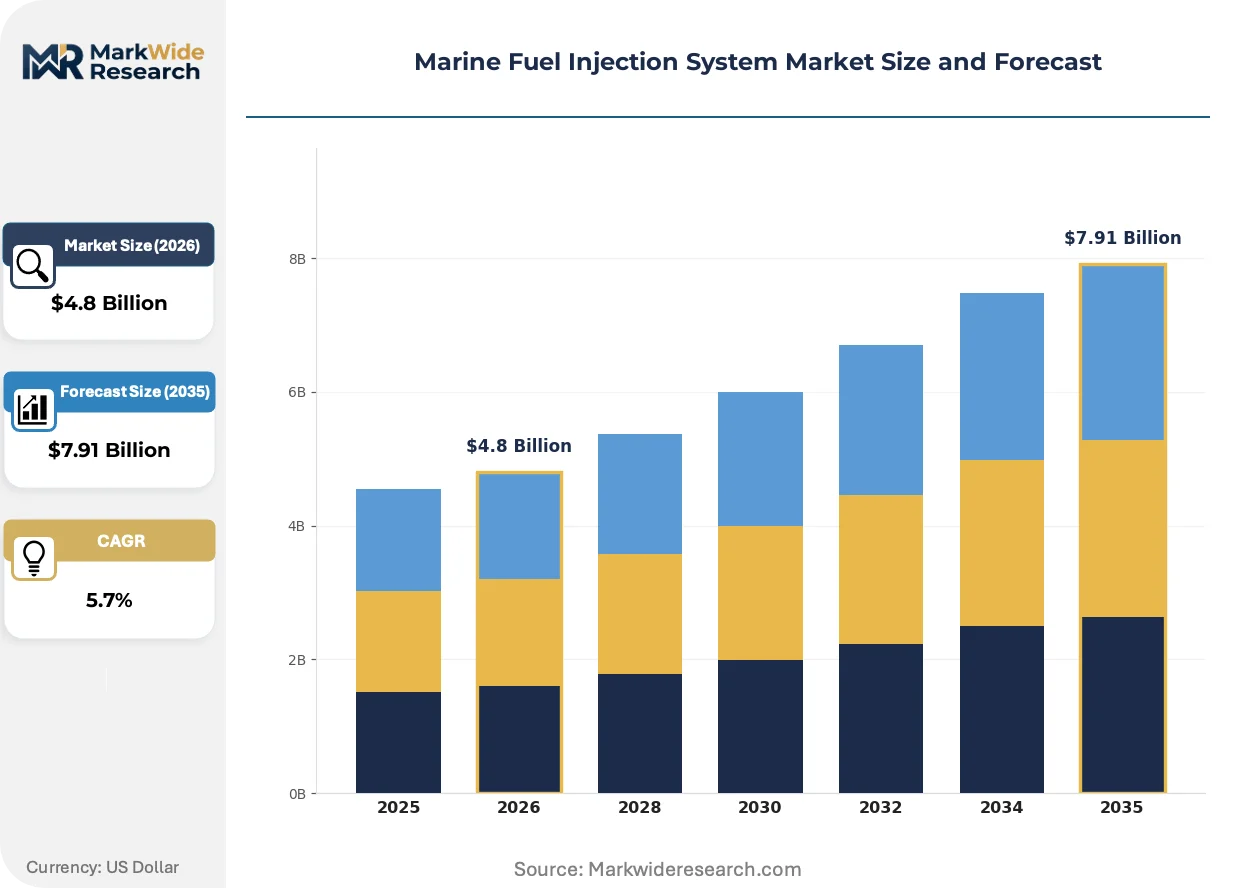
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Common Rail, Distributor Type, Unit Injector, Electronic, Mechanical, Pressure Pintle Technology: Direct Injection, Indirect Injection, Electronic Control, Hydraulic, Pneumatic, Electro-Mechanical Application: Commercial Vessels, Fishing Boats, Passenger Ships, Offshore Support, Research Vessels, Tugboats End User: Shipbuilders, Retrofit Providers, Marine Engine Manufacturers, Port Operators, Maritime Contractors, Vessel Owners |
| Companies Covered | Caterpillar Inc., Cummins Inc., Robert Bosch GmbH, Yanmar Co. Ltd, Liebherr International AG, DENSO Corporation, MAN SE, Rolls-Royce Holding PLC., Woodward, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fuel Injection System Market Strategic Shifts & Innovations
Digital combustion optimization and alternative fuel readiness are restructuring hardware specifications across newbuild programs, with electronic control architectures displacing mechanical legacy systems.
Electronic unit injectors with integrated pressure generation and needle control are overtaking cam-driven jerk pump designs in four-stroke auxiliary engines. Cruise operators and offshore support vessel owners are specifying these architectures for their real-time trim adjustment capabilities. The technology is compressing maintenance intervals while enabling remote diagnostic access that reduces unplanned downtime.
The EU Green Deal's FuelEU Maritime regulation imposes well-to-wake greenhouse gas intensity limits on voyages calling at European ports. Shipowners must document fuel consumption and emission performance through certified monitoring systems. Container lines operating Asia-Europe routes are responding by specifying dual-fuel injection hardware compatible with bio-methanol and synthetic ammonia.
Shipowners are unbundling after-sales service contracts from original equipment procurement, selecting third-party specialists for injector refurbishment and control module recalibration. Independent service providers in Singapore and Rotterdam are capturing maintenance revenue previously retained by engine builders. This behavioral shift is most pronounced among mid-sized bulk carriers operating spot-market charters with thin operating margins.
Marine Fuel Injection System Market Segmentation
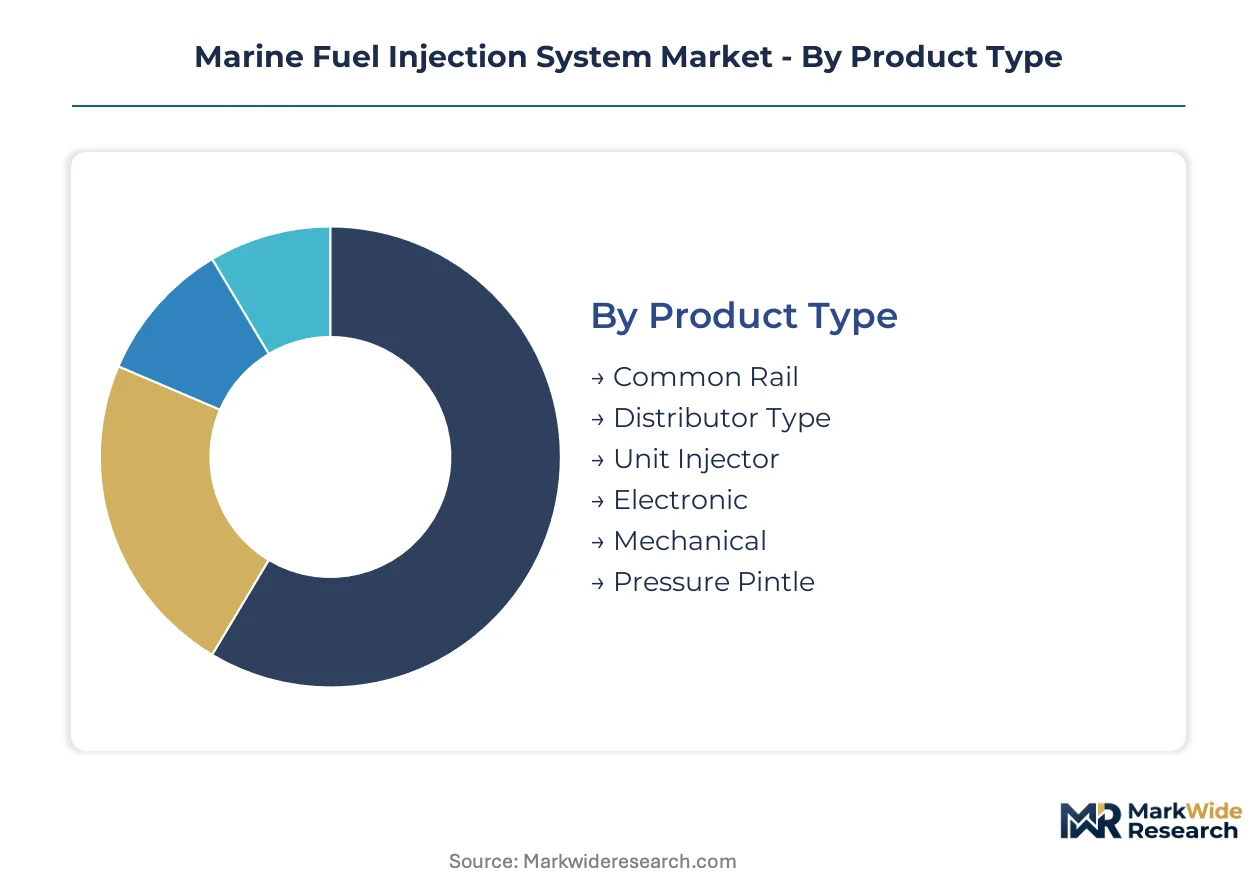
Marine fuel injection hardware varies sharply across pressure ratings, control architectures, and vessel duty cycles. Procurement patterns diverge between newbuild shipyards demanding Tier III-compliant common rail systems and aftermarket retrofitters seeking cost-effective mechanical upgrades for aging fleets.
Product Type:
Pressure architecture and control integration define competitive positioning across marine engine platforms.
- Common Rail:High-pressure accumulators distribute fuel to electronically controlled injectors at pressures exceeding 2,000 bar. Hyundai Heavy and Daewoo shipyards specify these architectures for newbuild container vessels serving emission control areas.
- Distributor Type:Rotating plunger mechanisms meter fuel to multiple cylinders through a single pumping element. The configuration dominates auxiliary power units on mid-sized bulk carriers where electronic control cost is prohibitive.
- Unit Injector:Integrated pump-and-nozzle assemblies eliminate high-pressure fuel lines. Yanmar leverages this design for fishing boat propulsion across East Asian waters.
- Electronic:Microprocessor-governed injection timing optimizes combustion across load variations. Cruise operators specify these systems for real-time trim adjustment capabilities.
- Mechanical:Cam-driven jerk pumps maintain injection pressure through governor-controlled rack positioning. Legacy tugboat fleets continue procurement for maintenance simplicity.
- Pressure Pintle:Spring-loaded needle valves achieve atomization through pintle geometry rather than orifice design. Specialized offshore support applications utilize these injectors for heavy fuel oil compatibility.
Common Rail leads on scale; Electronic systems lead on momentum as shipowners prioritize remote diagnostics capability.
Technology:
Combustion chamber access method and actuation mechanism determine emission compliance trajectories.
- Direct Injection:Fuel sprays directly into the combustion chamber without pre-chamber staging. Two-stroke marine engines at South Korean yards adopt this architecture for thermal efficiency maximization on long-haul routes.
- Indirect Injection:Pre-chamber turbulence chambers promote fuel-air mixing before main combustion. Smaller auxiliary engines retain this design for cold-start reliability in Arctic shipping lanes.
- Electronic Control:Solenoid or piezoelectric actuation enables multiple injection events per cycle. IMO Tier III mandates are accelerating displacement of hydraulic governor systems.
- Hydraulic:Pressurized oil circuits amplify mechanical force for needle valve actuation. Medium-speed engines continue limited procurement where electromagnetic interference risks exist.
- Pneumatic:Compressed air assists fuel atomization in heavy fuel oil applications. Research vessels operating extended idling periods specify these systems for carbon deposit mitigation.
- Electro-Mechanical:Hybrid actuation combines electronic timing with mechanical pressure generation. Port operators favor this technology for harbor craft requiring rapid load response.
Direct Injection dominates commercial vessel procurement; Electronic Control is climbing the fastest as FuelEU Maritime regulations tighten.
Application:
Vessel operational profile dictates injection hardware durability specifications and fuel flexibility requirements.
- Commercial Vessels:Container ships, bulk carriers, and tankers require continuous-duty injection systems rated for 8,000+ annual operating hours. Maersk and MSC fleet renewal programs concentrate demand at Hyundai Heavy.
- Fishing Boats:Compact engines with intermittent high-load operation demand unit injector simplicity. East Asian coastal fleets generate volume for sub-500 kW powertrains.
- Passenger Ships:Cruise vessels prioritize vibration attenuation and emission visibility to passengers. Carnival Corporation specifications emphasize common rail acoustic dampening.
- Offshore Support:Platform supply vessels and anchor handlers require rapid load acceptance for dynamic positioning. Tier III retrofit intensity runs highest in this segment per hull.
- Research Vessels:Scientific mission profiles demand extended low-load operation without coking degradation. Specialized injector cooling circuits address this requirement.
- Tugboats:Harbor assist and escort duties impose severe thermal cycling on injection hardware. Singapore port authorities are mandating emission upgrades for this fleet category.
Commercial Vessels anchor procurement volume; Offshore Support generates steepest expansion trajectory for Tier III retrofit hardware.
End User:
Procurement authority and technical integration responsibility vary across the vessel lifecycle value chain.
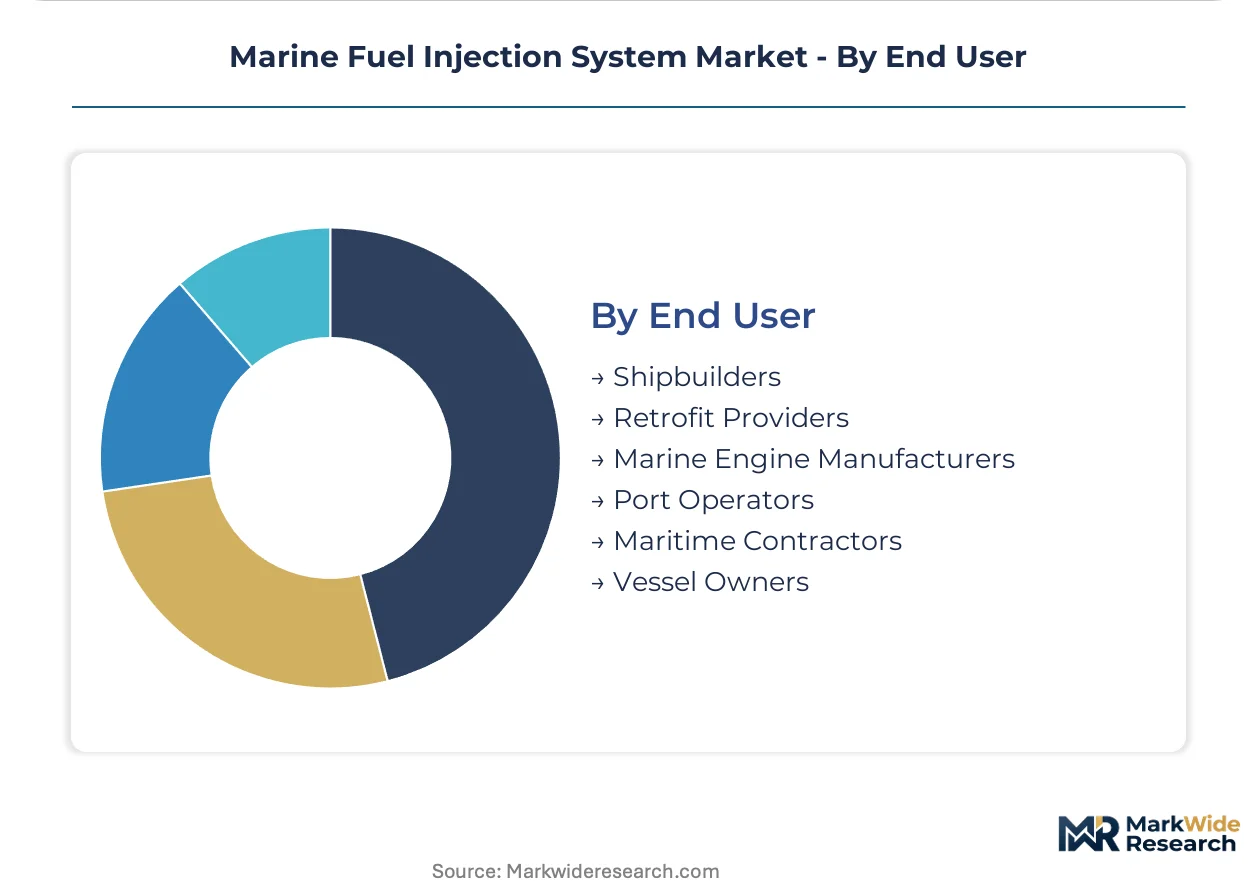
- Shipbuilders:Hyundai Heavy, Daewoo, and Imabari Shipyard integrate injection systems during hull construction. Their captive engine supplier relationships concentrate demand around approved vendor lists.
- Retrofit Providers:Independent specialists in Singapore and Rotterdam execute Tier III-equivalent upgrades for existing fleets. These operators are capturing maintenance revenue previously retained by engine builders.
- Marine Engine Manufacturers:Wärtsilä, MAN Energy Solutions, and Caterpillar Marine specify injection hardware for their powertrain platforms.
- Port Operators:Harbor authorities procuring tugboats and pilot vessels impose emission standards on contracted equipment.
- Maritime Contractors:Offshore service companies chartering specialized vessels influence injection specifications through bareboat charter requirements.
- Vessel Owners:Container lines and bulk operators with in-house technical teams direct retrofit decisions for owned fleets.
Shipbuilders command newbuild procurement scale; Retrofit Providers are gaining share fastest as vessel owners unbundle after-sales service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as Tier III compliance costs diverge across jurisdictions. South Korean shipyards capture premium newbuild contracts while European ports drive retrofit demand through unilateral carbon regulations. Component fabricators are relocating machining capacity toward these regulatory pressure points.
South Korea
Hyundai Heavy Industries and Daewoo Shipbuilding anchor global container vessel output, concentrating Tier III-compliant engine procurement within their captive supplier networks. The Ministry of Oceans and Fisheries coordinates domestic content requirements with IMO implementation timelines. Ulsan and Geoje industrial clusters host precision machining operations for high-pressure common rail components serving both domestic yards and export markets.
China
State-owned shipbuilders at Dalian and Shanghai are expanding dual-fuel vessel construction for methanol-ready container fleets. MIIT enforces domestic engine certification protocols that parallel IMO standards while favoring local injection system suppliers. The Yangtze River Delta concentration of marine equipment fabricators is scaling output for both indigenous shipyards and aftermarket retrofit channels across Southeast Asian ports.
Germany
Precision engineering specialists in Stuttgart and Munich supply high-pressure rail machining equipment to global engine builders. The KBA coordinates type-approval procedures for imported marine powertrains under EU MARPOL implementation rules. Bavarian component foundries are recalibrating capacity toward FuelEU Maritime-compliant hardware specifications demanded by Hamburg and Rotterdam terminal operators.
United States
Gulf Coast shipyards and Great Lakes engine rebuilders generate aftermarket demand for Tier III retrofit kits. EPA coordination with the U.S. Coast Guard extends certification cycles for medium-speed marine powertrains, creating compliance bottlenecks. Houston and New Orleans service hubs are capturing maintenance revenue from Latin American-flagged vessels seeking ECA-compliant injection upgrades.
Singapore
The Maritime and Port Authority mandates emission standards for harbor craft that accelerate tugboat fleet renewal. Independent injection specialists in Tuas and Jurong are unbundling after-sales service contracts from original equipment procurement. The port's position as Asia-Europe route interchange concentrates demand for real-time diagnostic capabilities and rapid component turnaround.
Marine Fuel Injection System Market Key Industry Players
German and Japanese producers anchor the premium tier through precision machining and patent-protected architectures; South Korean and Chinese fabricators hold scale-driven positions in mid-pressure auxiliary systems. Market structure concentrates around three strategic archetypes: intellectual property licensors controlling high-pressure common rail designs, vertically integrated engine builders with captive injection operations, and independent component specialists serving aftermarket channels. Competitive moves center on cross-licensing negotiations for Tier III-compliant architectures and geographic expansion of refurbishment networks toward major port clusters.
Within the intellectual property tier, Robert Bosch GmbH exemplifies the licensor archetype through its patent portfolio for marine common rail systems. Among engine-integrated suppliers, Caterpillar Inc. and Cummins Inc. occupy positions where captive injection development aligns with powertrain platform strategies. These three entities represent distinct competitive vectors: technology licensing leverage, vertical integration depth, and auxiliary segment specialization respectively.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Robert Bosch GmbH |
| Yanmar Co. Ltd |
| Liebherr International AG |
| DENSO Corporation |
| MAN SE |
| Rolls-Royce Holding PLC. |
| Woodward, Inc. |
| Others |
Cost & Logistics Intelligence
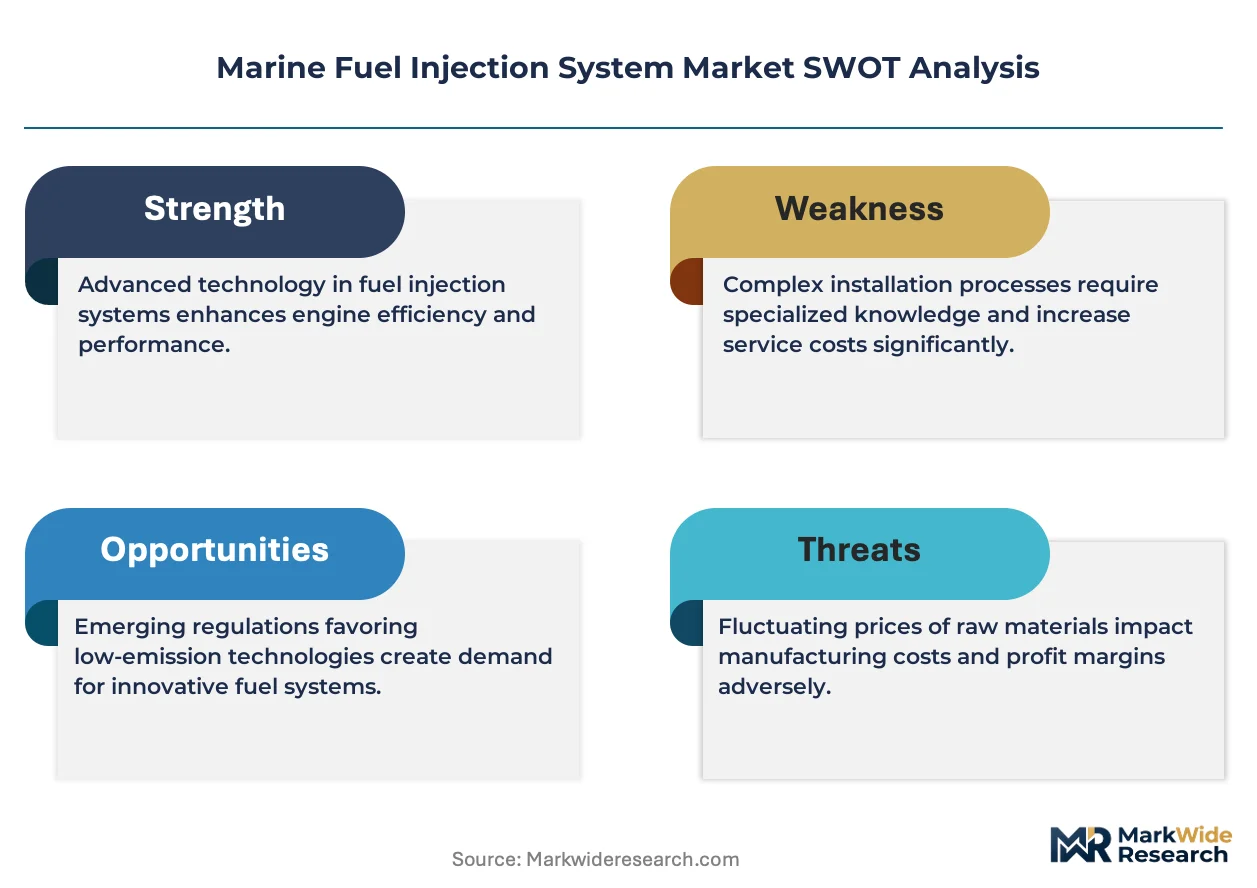
IMO Tier III NOx mandates for emission control areas are forcing shipyards to specify high-pressure common rail architectures, compelling component suppliers to absorb precision machining costs while engine OEMs extract volume discounts through captive procurement networks. This demand-side specification pressure concentrates pricing power among German and Japanese patent holders even as South Korean yards consolidate order books.
Pricing Analysis
Distributor markups for aftermarket injector refurbishment vary sharply between port hub specialists and authorized engine builder channels. Three-tier pricing structure across Tier III-certified, Tier II-equivalent, and legacy mechanical systems reflects compliance grade differentiation rather than performance alone. Cost compression in the auxiliary engine segment is intensifying because Chinese fabricators are scaling electronic unit injector output for methanol-ready powertrains. Mid-sized bulk carriers operating spot-market charters exhibit the highest price sensitivity, while cruise operators prioritizing emission visibility accept premium positioning for acoustic dampening specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Hyundai Heavy and Daewoo yards, while independent service providers in Singapore and Rotterdam capture unbundled aftermarket maintenance contracts. Precision machining capacity concentrates in Germany, Japan, and South Korea, with Ulsan and Geoje industrial clusters feeding both domestic shipbuilders and export markets. High-pressure rail production draws from specialized martensitic stainless grades whose nickel and chromium input costs swing with commodity markets. Single-source vulnerability persists for piezoelectric actuator elements sourced from Japanese ceramic specialists. Distribution runs through engine builder captive networks for newbuilds and third-party refurbishment hubs for retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine fuel injection system market functions as a regulatory compounder where MARPOL Annex VI tier reductions and FuelEU Maritime carbon intensity limits create sustained hardware replacement cycles across vessel lifecycles.
For Market Incumbents: Hedge patent exposure by cross-licensing common rail architectures with emerging dual-fuel engine platforms before ammonia-ready injection specifications solidify. Secure backward integration into high-pressure rail machining capacity in South Korea to defend margin position against Chinese fabricators scaling electronic unit injector output. Certification investment for EPA and U.S. Coast Guard protocols represents the critical lever for medium-speed engine market access. For New Entrants and Emerging Players: The price-point gap between Bosch-licensed premium common rail systems and economy-tier mechanical governor retrofits creates entry space for electro-mechanical hybrid architectures targeting harbor craft and tugboat fleets. Port operator procurement mandates in Singapore and Rotterdam offer the most penetrable immediate channel, with FuelEU Maritime compliance documentation serving as the essential go-to-market credential for European terminal access. For Investors and Strategic Acquirers: Asymmetric upside sits with independent refurbishment specialists capturing unbundled service contracts from engine builders in Asia-Europe route interchange ports. Long-term viability hinges on positioning for alternative fuel injection hardware as methanol and ammonia specifications mature. Watch for EPA certification backlog resolution as the inflection signal for medium-speed engine platform demand normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Injection Platform Development | MAN Energy Solutions and Wärtsilä specifications for methanol-ready engines drive hardware upgrade cycles. |
| Retrofit Refurbishment Network Expansion | Singapore and Rotterdam third-party specialists capture maintenance revenue previously retained by OEMs. |
| Precision Machining Capacity Addition | German and Japanese suppliers anchor high-pressure rail output for Tier III common rail architectures. |
| Remote Diagnostics Integration | Satellite-linked engine control modules enable predictive maintenance contracts for cruise and offshore operators. |
| Alternative Fuel Certification Investment | FuelEU Maritime compliance documentation opens premium positioning for ammonia-capable injection hardware. |
Research Approach
Coverage spans South Korea, China, Germany, the United States, and Singapore, with primary inputs from each market cluster. The research combines structured interviews with shipyard procurement directors, marine engine OEM platform engineers, port authority technical specifications leads, and independent retrofit service operators with secondary validation from IMO MARPOL implementation documents, EPA engine certification filings, EU FuelEU Maritime regulatory texts, and customs trade data for high-pressure fuel injection components. Bottom-up vessel order book analysis and top-down engine production estimates were triangulated to establish market sizing.
Rate-of-change decomposition across the analysis window separates newbuild procurement from aftermarket retrofit demand, with segmentation modeling across pressure architecture, control technology, vessel application, and end-user procurement authority. CAGRs were derived from shipyard output projections tied to container fleet renewal programs and ECA compliance deadlines. Industry-specific forecast inputs include Tier III engine build rates at South Korean yards and tugboat fleet renewal mandates from Singapore port authorities.
Caveats apply where EPA certification cycle extensions or steel alloy price volatility could materially shift the outlook for medium-speed engine platform launches. Forecasts reflect documented assumptions regarding IMO implementation timelines and shipowner fuel choice preferences. Periodic stress-testing of base assumptions against regulatory enforcement divergence and alternative fuel infrastructure buildout is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Airboats Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Marine Reciprocating Engine Market