
 Bass Boat Market | 2026-2036
Bass Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Bass Boat Market Analytics
Subscription-based boat leasing and shared-ownership programs is tilting capital requirements away from pure retail purchases. Ranger Boats leverages its established dealer network to sustain geographic dominance across the southern United States. Skeeter differentiates through fiberglass hull engineering and tournament-grade fitouts. Phoenix Bass Boats specializes in hand-built custom configurations that command premium positioning.
A bass boat denotes a shallow-draft fishing vessel optimized for freshwater angling, typically measuring 16 to 21 feet in length with a flat or modified-V hull, elevated casting decks, and livewell systems for fish preservation. Manufacturers construct hulls from hand-laid fiberglass or welded aluminum sheet, with outboard engine mounting rated between 150 and 300 horsepower for tournament performance. Fiberglass hulls anchor the premium tier due to ride quality and finish durability, while aluminum dominates entry-level and price-sensitive segments through lower material costs and dent resistance. Electric and hybrid engine configurations represent the fastest-growing structural category as lake jurisdictions restrict combustion emissions.
The EPA regulates marine engine emissions under Title 40 CFR standards, while the US Coast Guard enforces flotation and structural integrity requirements under 33 CFR. State-level wildlife agencies in Texas and Florida impose additional livewell capacity and invasive-species decontamination rules that shape hull and equipment specifications. Stakeholders must monitor evolving propulsion regulations and electrification infrastructure readiness across major tournament circuits.
Market Dynamics
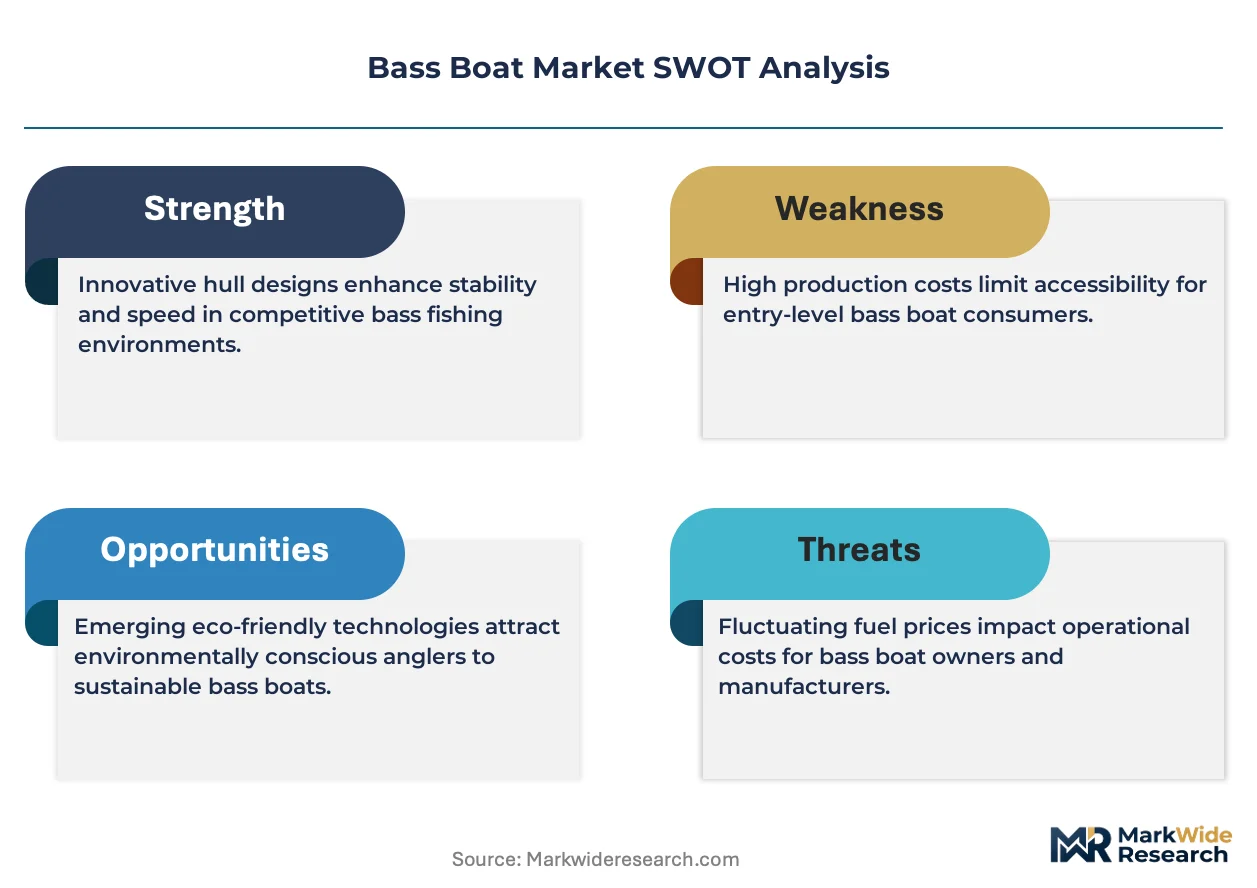
Tournament fishing circuits are expanding their geographic footprint across the United States, while EPA emissions standards for marine engines are tightening displacement and fuel-system requirements. These dual pressures are reshaping manufacturer R&D priorities and dealer inventory strategies simultaneously.
Growth Catalysts
- Tournament circuit expansion:Competitive fishing leagues are adding events across Tennessee and Texas lake corridors, driving replacement cycles for high-performance hulls and livewell systems.
- Electric propulsion mandates:Lake jurisdictions in the southeastern United States are restricting combustion emissions, accelerating demand for battery-powered outboard configurations.
- Subscription ownership models:Shared-access programs are lowering capital barriers for recreational anglers, expanding the addressable buyer base beyond traditional retail purchasers.
Market Restraints
- Aluminum sheet price volatility:Entry-level hull production faces margin compression from fluctuating raw material costs, constraining price competitiveness against fiberglass alternatives.
- Livewell capacity regulations:State wildlife agencies in Texas and Florida impose invasive-species decontamination rules that add compliance costs to hull and equipment specifications.
- Engine supplier concentration:Outboard motor manufacturing concentrates among a limited set of Tier 1 suppliers, creating vulnerability for boat builders dependent on 150-300 horsepower configurations.
Strategic Opportunities
- Electrification infrastructure gaps:Lake marinas across Alabama and Georgia lack charging station density, creating first-mover advantage for manufacturers bundling shore-power solutions.
- Hand-built customization premium:Custom-configured fiberglass hulls command pricing power in tournament-grade segments where anglers prioritize deck layout specificity.
- Dealer network digitization:Direct-to-consumer configuration tools are bypassing traditional showroom dependency, enabling geographic expansion into underpenetrated lake communities.
Industry Challenges
- Composite lamination skill scarcity:Hand-laid fiberglass hull production requires specialized technician training that outpaces vocational pipeline output in southern manufacturing clusters.
- Emissions certification timelines:EPA Title 40 CFR compliance testing for new engine platforms extends product development cycles, delaying model year launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bass Boat Market |
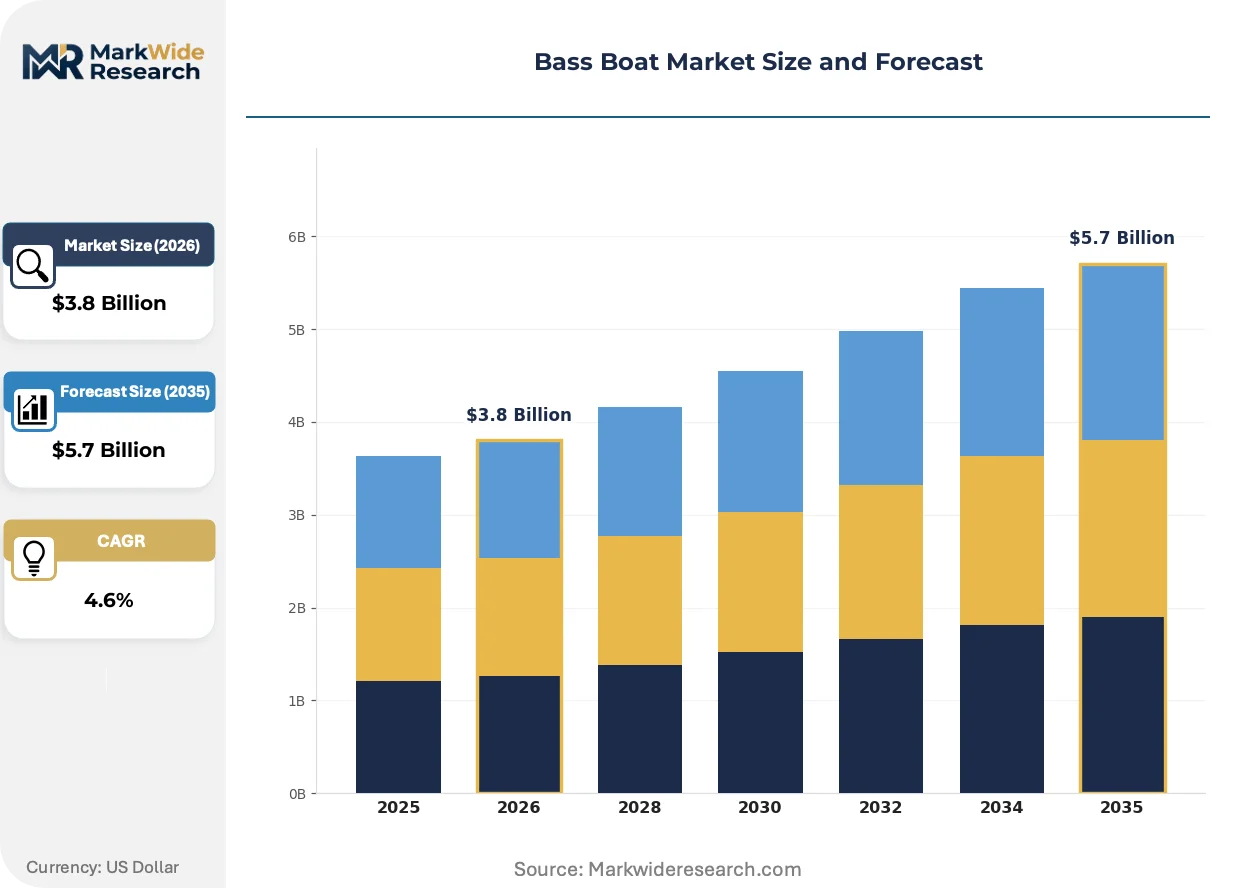
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boat Type: Fiberglass, Aluminum, Pontoon, Bass Tracker Engine Type: Outboard, Inboard, Electric, Hybrid Usage Scenario: Recreational Fishing, Tournament Fishing, Personal Leisure, Commercial Use Capacity: Single Passenger, Two Passengers, Four Passengers, Six Passengers |
| Companies Covered | Nitro, Vexus, Caymas Boats, Ranger Boats, Phoenix Bass Boats, Bass Cat, Skeeter, Lund, Bullet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bass Boat Market Evolving Landscape
Propulsion technology and ownership models are diverging simultaneously across the bass boat market. Manufacturers must balance electrification roadmaps against combustion engine refinement while adapting to non-traditional purchase structures.
Integrated battery-electric outboard systems are migrating from prototype demonstration to limited production runs. Tournament anglers in restricted lake zones are piloting 50-150 horsepower electric configurations during select events. This migration from combustion dominance is compressing the traditional 10-year platform lifecycle toward 5-year refresh cycles as battery chemistry improves.
EPA Title 40 CFR standards are tightening particulate and hydrocarbon limits for two-stroke and four-stroke marine engines. Manufacturers are responding with direct fuel injection and catalytic after-treatment systems that add cost and complexity. The southeastern United States tournament segment faces the steepest compliance burden due to concentrated event scheduling and engine utilization intensity.
Ownership models are fragmenting as subscription-based leasing programs capture younger demographic entry points. Traditional dealer finance departments are competing against third-party fleet operators offering seasonal access without equity buildup. Texas lake corridors exhibit the highest penetration of shared-ownership structures, driven by urban anglers seeking intermittent access without storage obligations.
Bass Boat Market Segmentation
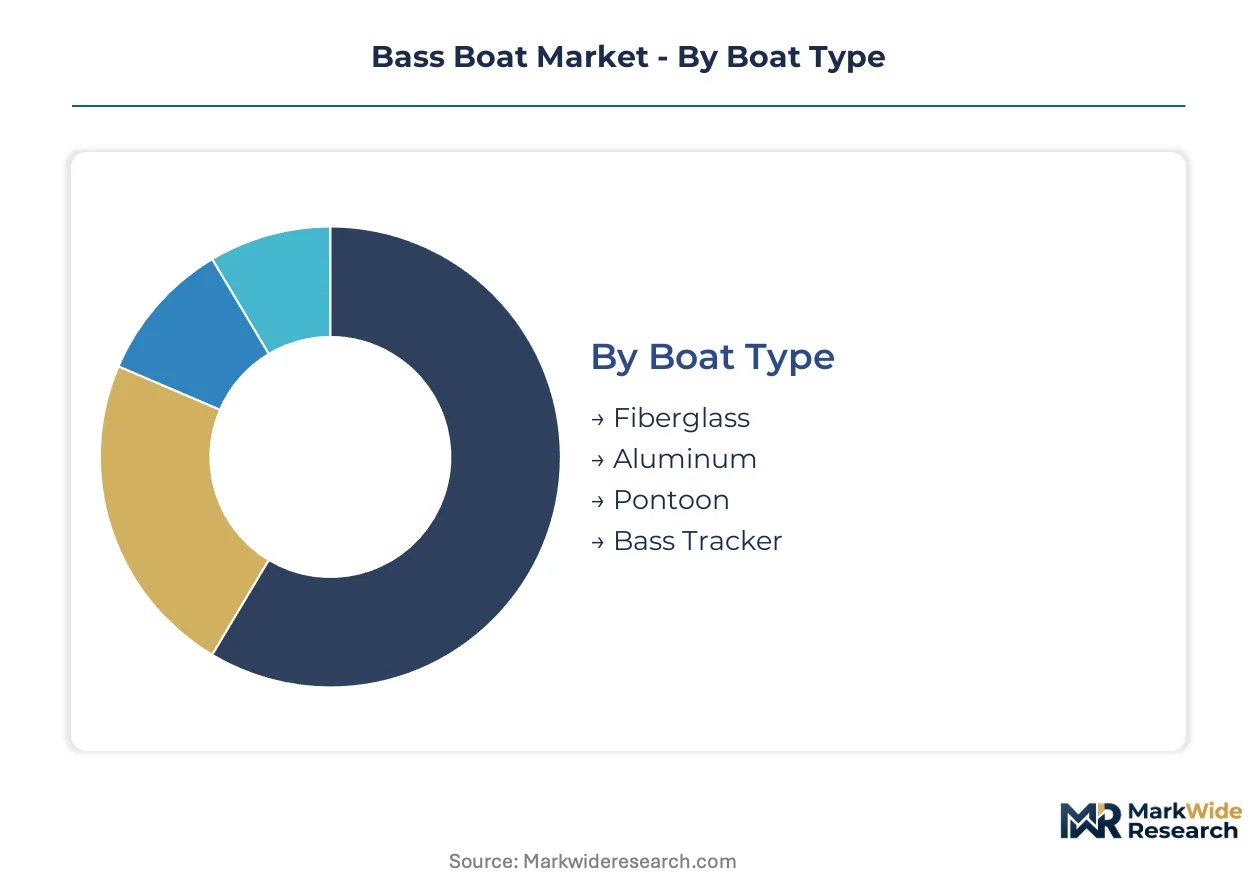
Segmentation in the bass boat market determines warranty exposure, service network density, and parts inventory requirements. Hull material and engine configuration drive radically different after-sales service intervals and technician specialization needs. Tournament operators and recreational anglers present distinct seasonal demand patterns that reshape dealer preparedness.
Boat Type:
After-sales service intensity varies dramatically across hull materials, with fiberglass requiring specialized gelcoat repair technicians and aluminum demanding weld-certified maintenance crews.
- Fiberglass:Hand-laid composite construction delivers superior ride quality and finish durability for tournament-grade applications. Demand concentrates in Tennessee and Texas lake corridors where competitive anglers prioritize hull performance over acquisition cost. Gelcoat oxidation repair and structural lamination work sustain elevated service revenue per unit.
- Aluminum:Welded sheet hulls dominate entry-level procurement through lower material costs and dent resistance. Price-sensitive buyers in rural lake communities favor aluminum for shallow-water durability and reduced insurance premiums. Weld repair and rivet maintenance require different technician certifications than fiberglass shops.
- Pontoon:Multi-hull platforms serve family fishing configurations with expanded deck space and stability.
- Bass Tracker:Value-oriented packaged boats combine hull, engine, and electronics at entry price points.
Fiberglass holds the largest share; momentum sits with aluminum as raw material cost pressures ease.
Engine Type:
Propulsion technology segmentation determines regulatory compliance pathways and technician training investments across dealer networks.
- Outboard:Transom-mounted configurations rated 150-300 horsepower anchor tournament performance standards. Demand concentrates in competitive fishing circuits across the southeastern United States where engine reliability affects tournament outcomes. Service intervals center on lower unit maintenance and seasonal winterization protocols.
- Electric:Battery-powered outboard systems are expanding most quickly as lake jurisdictions restrict combustion emissions. Alabama and Georgia marinas lack charging infrastructure, creating bundling opportunities for shore-power solutions. Technicians require electrical systems certification distinct from combustion engine training.
- Inboard:Stern-drive configurations occupy niche applications in larger hull formats.
- Hybrid:Dual-mode propulsion remains in limited demonstration phases for restricted-waterway compliance.
Outboard dominates installed base; electric configurations gain share fastest where emissions restrictions tighten.
Usage Scenario:
Application-based segmentation shapes hull specification, electronics fitout, and financing structure preferences.
- Tournament Fishing:Competitive circuits demand livewell capacity, precision electronics, and deck layout optimization. Texas and Tennessee lake corridors host the densest event scheduling, driving replacement cycles for high-performance configurations. Service contracts emphasize pre-event inspection protocols and emergency repair availability.
- Recreational Fishing:Weekend anglers prioritize reliability and storage convenience over tournament-grade specifications. Subscription-based leasing programs capture this demographic through reduced capital barriers and eliminated storage obligations.
- Personal Leisure:Multi-purpose usage blends fishing with family cruising requirements.
- Commercial Use:Guide services and rental fleets emphasize durability and standardized maintenance intervals.
Recreational fishing holds the largest share; tournament applications command premium pricing and service intensity.
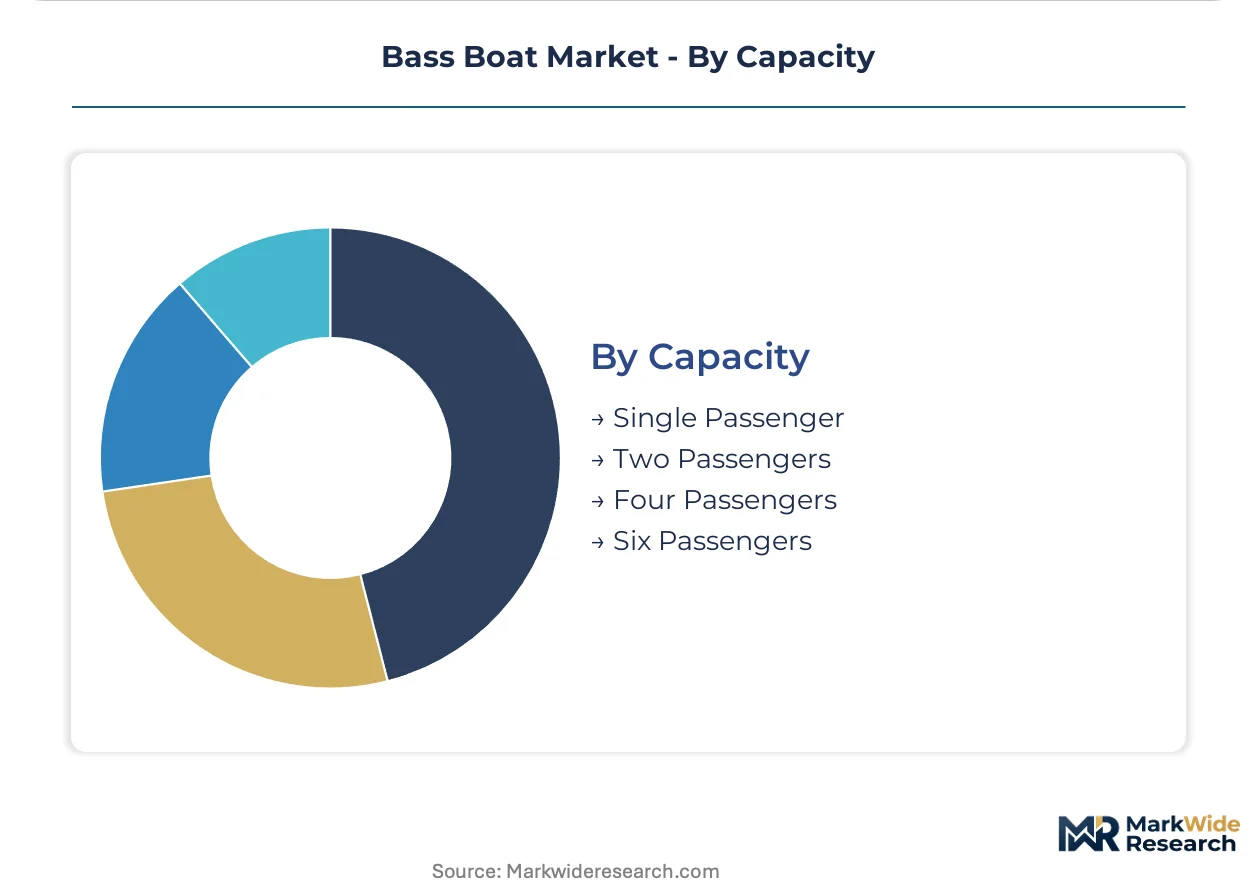
Capacity:
Passenger configuration segmentation determines hull sizing, livewell scaling, and trailer requirements.
- Two Passengers:Compact tournament formats optimize weight distribution and casting deck space for paired competitors. Demand concentrates in professional circuits where boat-motor-trailer combinations must meet trailering weight restrictions.
- Four Passengers:Family-oriented configurations balance fishing utility with passenger comfort. Weekend anglers in Texas lake corridors favor this format for combined adult and youth participation.
- Single Passenger:Solo operation configurations occupy minimal market presence.
- Six Passengers:Maximum-capacity layouts serve guide services and multi-generational family units.
Two-passenger configurations hold the largest share; four-passenger formats expand fastest as family participation broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tournament-grade anglers concentrate in the southeastern United States, with lake communities in Tennessee and Texas driving premium hull demand. Subscription-based ownership models are expanding the buyer base among urban professionals seeking intermittent access.
United States
Competitive fishing circuits across Tennessee and Texas lake corridors sustain replacement demand for high-performance fiberglass hulls. EPA Title 40 CFR emissions standards tighten particulate limits for marine engines, forcing manufacturers toward direct fuel injection systems. The Alabama-Georgia marina corridor lacks charging infrastructure, creating bundling opportunities for shore-power solutions.
Canada
Recreational anglers in Ontario and Quebec lake regions favor aluminum hulls for shallow-water durability and reduced insurance premiums. Transport Canada enforces flotation and structural integrity requirements parallel to US Coast Guard standards. The Prairie Provinces exhibit growing subscription-ownership penetration among urban millennials seeking seasonal access without storage obligations.
Australia
Freshwater tournament fishing in New South Wales and Victoria drives demand for livewell-equipped configurations. The Australian Maritime Safety Authority regulates vessel construction standards and outboard emissions compliance. Queensland's coastal lake communities increasingly restrict combustion emissions, accelerating electric propulsion trials.
Germany
Angling clubs in Bavaria and Baden-Württemberg sustain niche demand for precision-engineered hulls. The KBA enforces emissions certification for imported marine engines under EU standards. The North Rhine-Westphalia industrial corridor hosts specialized fiberglass lamination suppliers serving premium European boat builders.
Japan
Recreational bass fishing in Lake Biwa and Kasumigaura sustains steady hull replacement cycles. METI oversees marine equipment safety standards and environmental compliance for domestic waters. The Chubu/Nagoya manufacturing cluster supplies precision electronics and outboard components to regional boat assemblers.
Bass Boat Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: established dealer-network operators leveraging geographic density, fiberglass engineering specialists commanding premium positioning, and hand-built custom fabricators serving tournament-grade specifications. Competitive moves concentrate on electrification roadmaps and subscription-ownership platform partnerships.
Within the dealer-network tier, Ranger Boats exemplifies channel-control strategy through southern United States distribution density. Skeeter occupies the engineering-specialist position with fiberglass hull differentiation. Phoenix Bass Boats anchors the custom-fabrication segment through hand-built configurations. These three players represent distinct competitive vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| Nitro |
| Vexus |
| Caymas Boats |
| Ranger Boats |
| Phoenix Bass Boats |
| Bass Cat |
| Skeeter |
| Lund |
| Bullet |
| Others |
Value Network & Pricing Analysis
The Tennessee-Texas lake corridor freight network shapes cost dynamics across fiberglass hull shipments, concentrating supply leverage among hand-laid composite specialists while forcing price differentiation between tournament-grade and entry-level aluminum configurations. Aluminum sheet volatility feeds directly into margin compression for welded hull producers, amplifying the pricing power of vertically integrated fiberglass manufacturers who control resin and gelcoat sourcing.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange aluminum pricing dominate entry-level hull procurement, while fiberglass tournament configurations command fixed-price premiums tied to lamination labor scarcity. Price differentiation separates hand-built custom fitouts from mass-produced alternatives based on deck layout specificity and livewell engineering complexity. Pricing pressure stems from EPA Title 40 CFR compliance costs for direct fuel injection systems, compressing margins on 150-300 horsepower outboard bundles. Entry-level aluminum buyers exhibit highest price sensitivity, whereas competitive anglers absorbing tournament-grade fiberglass premiums show minimal elasticity.
Supply Chain Analysis
Contract manufacturing concentrates among specialized lamination shops across Tennessee, Arkansas, and northern Alabama, with hull assembly tethered to regional outboard motor distribution hubs. Raw material dependencies center on marine-grade aluminum sheet, fiberglass roving and resin systems, and EPA-certified engine blocks from consolidated Tier 1 suppliers. Single-source vulnerability runs through outboard motor manufacturing concentration, where limited 150-300 horsepower suppliers create bottleneck exposure for boat builders. Distribution runs through established dealer networks across southern lake corridors, with direct-to-consumer configuration tools emerging as alternative channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bass boat market faces high-growth disruption from electric propulsion mandates across southeastern lake jurisdictions, with EPA emissions standards compressing traditional combustion platform lifecycles toward accelerated refresh cycles.
For Market Incumbents: Insulate tournament-grade positioning by deepening captive supply of hand-laid lamination technicians through vocational partnerships across Tennessee manufacturing clusters. Secure exclusive shore-power bundling agreements with Alabama-Georgia marina operators before charging infrastructure gaps close. Vertical integration into gelcoat formulation protects margin erosion from specialty chemical cost volatility.
For New Entrants and Emerging Players: Pursue subscription-ownership platform partnerships targeting urban professionals in Texas lake corridors seeking intermittent access without storage obligations. Target recreational fishing segments where capital barriers exclude traditional retail purchasers. Deploy direct-to-consumer configuration tools bypassing established dealer network density requirements.
For Investors and Strategic Acquirers: Custom-fabrication specialists with hand-built tournament expertise represent compelling acquisition targets given lamination skill scarcity and premium pricing power. Long-term viability hinges on electrification roadmap execution and battery chemistry improvement trajectories. Monitor EPA certification timeline extensions as inflection indicators for product development cycle disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Roadmap Execution | Battery-electric outboard development secures compliance with lake jurisdiction emission restrictions across Alabama and Georgia. |
| Dealer Network Digitization | Direct-to-consumer configuration tools bypass showroom dependency and expand geographic reach into underpenetrated lake communities. |
| Shore-Power Infrastructure Partnership | Marina charging station bundling creates first-mover advantage where electric propulsion trials concentrate. |
| Custom Fabrication Capability Acquisition | Hand-built lamination expertise commands premium positioning as tournament-grade deck layout specificity intensifies. |
| Subscription Platform Integration | Shared-ownership program partnerships capture younger demographic entry points and reduce capital barriers for recreational anglers. |
Research Methodology
Operator-level perspectives from tournament circuit organizers, marina operators, hull lamination technicians, and outboard motor distribution managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA Title 40 CFR filings, US Coast Guard flotation standard updates, and state wildlife agency livewell regulation databases. Trade customs data, marine engine certification records, and tournament circuit expansion announcements provided quantitative triangulation alongside bottom-up hull production estimates and top-down market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling volume and value outputs through segmentation dimensions spanning hull material, engine configuration, usage scenario, and passenger capacity. CAGRs were derived from replacement cycle analysis, tournament circuit growth trajectories, and electrification adoption curves. Forecast inputs incorporated EPA compliance timeline assumptions, aluminum price index trajectories, and charging infrastructure buildout schedules across southeastern lake jurisdictions.
Sensitivities concentrate around EPA certification delays, aluminum sheet cost volatility, and electric propulsion technology maturation timelines. Forecasts reflect documented assumptions regarding tournament circuit expansion rates and lake jurisdiction emission restriction adoption patterns. Quarterly review of EPA Title 40 CFR update schedules, marina charging station deployment data, and lamination technician vocational program graduation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Airboats Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market