
 Airboats Market | 2026-2036
Airboats Market Size, Share, and Industry Trends Forecast 2026-2036
Airboats Market Analysis
Dealer networks serving state procurement offices is tilting toward direct manufacturer relationships as institutional buyers consolidate vendor lists. Panther Airboats leverages its specialization in shallow-draft hull designs to anchor contracts with government agencies across Louisiana and Texas. Diamondback Airboats competes through in-house fabrication of aluminum hulls and custom rigging systems, sustaining price control against regional assemblers.
An airboat is a flat-bottomed watercraft propelled by an aircraft-type propeller mounted above the stern, typically powered by an automotive or aircraft engine rated between 300 and 600 horsepower, enabling operation in water depths under six inches. The vessel serves commercial and institutional users requiring access to marshlands, flood zones, and ice-covered waterways inaccessible to conventional propeller-driven boats. Recreational airboats occupy the largest volume tier, though rescue airboats command premium pricing due to integrated thermal imaging and medical equipment configurations. Electric engines represent the fastest-growing engine type segment, with lithium-ion battery packs displacing gasoline powertrains in noise-restricted conservation zones.
EPA wetland access regulations and US Coast Guard small vessel safety standards shape hull design, noise emission thresholds, and operator certification requirements across domestic manufacturing. State environmental agencies in Florida and Louisiana enforce additional seasonal speed limits and no-wake zones that influence propeller specification and engine selection. Stakeholders must monitor pending electrification mandates from the EPA and evolving battery safety protocols from the Coast Guard to align R&D roadmaps with compliance timelines.
Market Dynamics
Electrification mandates from the EPA are compressing development timelines for gasoline-dependent hull manufacturers while lithium-ion battery pack suppliers scale production for shallow-draft conservation fleets.
Growth Catalysts
- EPA Wetland Access Rules:Tightened seasonal restrictions in Florida and Louisiana are forcing wildlife agencies to replace conventional vessels with shallow-draft alternatives, accelerating fleet turnover.
- Lithium-Ion Battery Density Improvements:Energy storage advances are extending operational range for electric airboats, opening noise-restricted conservation zones previously inaccessible to combustion engines.
- Flood Response Modernization:State emergency management offices across Texas and Mississippi are expanding airboat procurement for rapid deployment in hurricane-affected marshlands.
Market Restraints
- Aluminum Sheet Price Volatility:Hull fabricators face margin pressure from fluctuating raw material costs, with 5052 marine-grade aluminum representing the dominant structural input.
- Coast Guard Certification Bottlenecks:Small vessel safety standard updates are extending type-approval timelines, delaying commercial deliveries by multiple quarters.
- Skilled Welder Scarcity:Custom aluminum hull production concentrates in Gulf Coast fabrication shops facing acute labor shortages in specialized maritime welding.
Strategic Opportunities
- Texas Coastal Bend Eco-Tourism:Underdeveloped guided wetland tour operations present expansion potential for commercial airboat operators seeking to diversify beyond government contracts.
- US Coast Guard Battery Safety Protocols:Pending electrification standards will create first-mover advantages for manufacturers with certified electric propulsion systems.
- Direct-to-Agency Sales Channels:Institutional buyers are consolidating vendor lists, rewarding manufacturers who bypass dealer networks for state procurement relationships.
Industry Challenges
- Multi-Agency Certification Coordination:Manufacturers must synchronize EPA emission compliance, Coast Guard flotation standards, and state-level operator licensing, creating administrative complexity.
- Legacy Fleet Retrofit Integration:Existing gasoline-powered hulls require extensive structural modification to accommodate battery weight distribution, complicating upgrade paths for fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airboats Market |
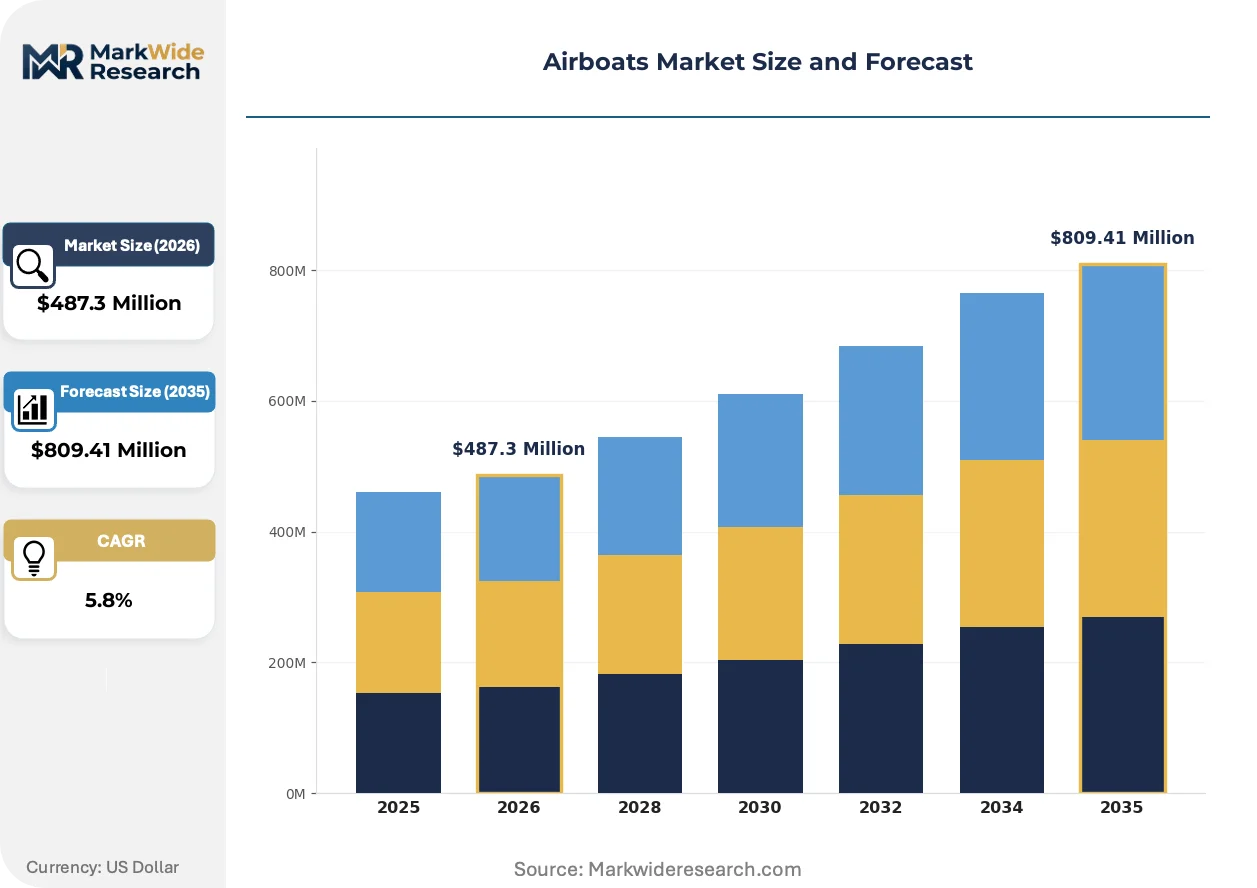
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
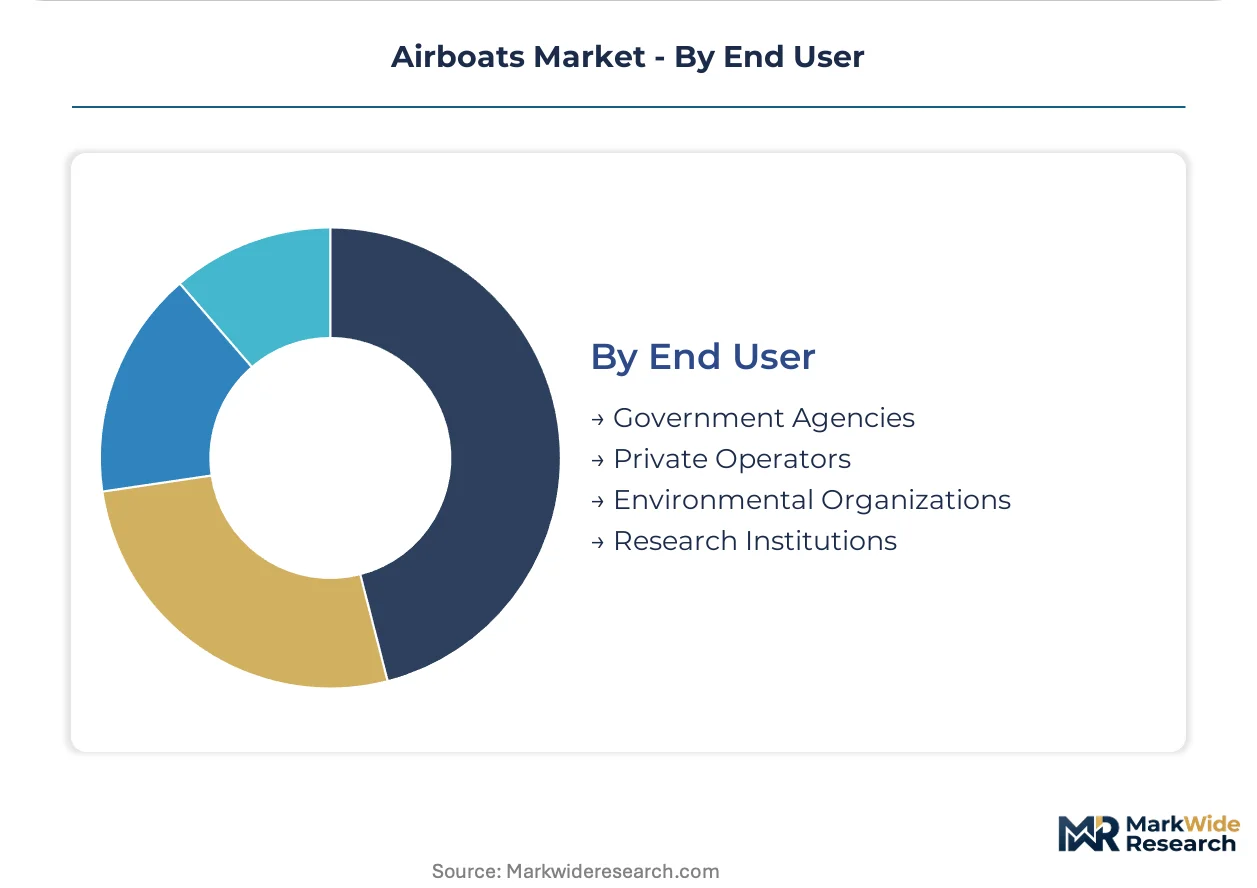
| Segmentation | Product Type: Commercial Airboats, Recreational Airboats, Rescue Airboats, Military Airboats Engine Type: Gasoline Engines, Diesel Engines, Electric Engines, Hybrid Engines Application: Tourism, Search and Rescue, Wildlife Conservation, Law Enforcement End User: Government Agencies, Private Operators, Environmental Organizations, Research Institutions |
| Companies Covered | Airboats.com, Marsh Master Airboats, Panther Airboats, Elite Airboats, American Airboats, Diamondback Airboats, Custom Airboats Inc., ProAirboat Manufacturing, AeroWake Boats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airboats Market Emerging Trajectories
Propulsion technology convergence with automotive electric drivetrains is redefining competitive advantage, while regulatory pressure on noise emissions accelerates product development cycles.
Brushless DC electric motors paired with high-density lithium-ion packs are rendering obsolete the 300-600 horsepower aircraft engines that dominated shallow-water propulsion for decades. Florida wildlife agencies are mandating electric conversion timelines for new fleet acquisitions. The technology is compressing maintenance intervals and fuel logistics for conservation operators.
EPA wetland access regulations are tightening seasonal speed limits and no-wake zone enforcement across Gulf Coast states. Hull manufacturers must now engineer quieter propeller designs and integrate sound-dampening cowlings to maintain operational permits. Louisiana state environmental agencies are extending these restrictions to previously exempt commercial tour operators.
State procurement offices are consolidating vendor qualification lists and demanding integrated service packages spanning hull fabrication, propulsion installation, and operator training. Dealer networks serving institutional buyers are losing ground to manufacturers with direct technical support capabilities. Texas and Mississippi emergency management divisions exemplify this concentration pattern.
Airboats Market Segmentation
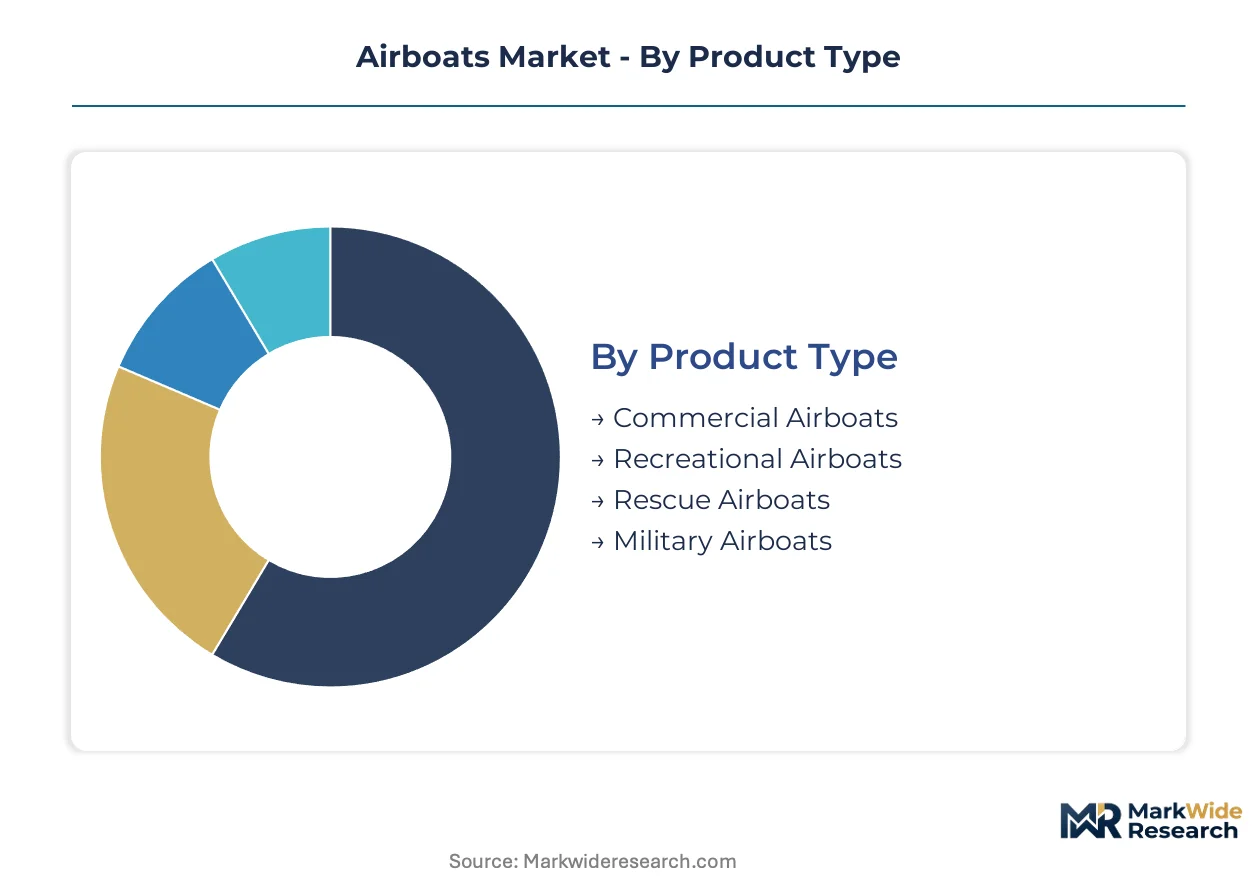
Airboat procurement patterns diverge sharply across institutional and commercial channels, with hull specifications, propulsion systems, and equipment packages calibrated to distinct operational mandates. Understanding these segment boundaries clarifies why manufacturers maintain parallel product lines rather than unified platforms.
Product Type:
Mature hull configurations dominate government contracting, while emerging designs target noise-restricted conservation zones and recreational buyers seeking premium experiences.
- Commercial Airboats:Aluminum-hull vessels rated for 8-12 passenger capacity with open-deck configurations and minimal sound-dampening. Demand concentrates in Louisiana and Texas marshland tour operators facing seasonal capacity constraints during peak migration months.
- Recreational Airboats:Compact single-engine hulls with automotive powertrains and customizable rigging for hunting and fishing access. Florida private owners drive volume through shallow-water lake systems where conventional outboards cannot operate.
- Rescue Airboats:Integrated thermal imaging arrays, medical equipment mounts, and reinforced hull structures for ice and debris impact. Configured for rapid deployment protocols.
- Military Airboats:Armored variants with reduced acoustic signatures and extended fuel range for special operations in littoral environments. Procurement cycles align with defense budgeting timelines.
Recreational Airboats handles the majority of throughput; Electric-adjacent Rescue configurations are expanding most quickly on share.
Engine Type:
Cost tier stratification separates established combustion platforms from emerging electrification architectures requiring substantial battery infrastructure investment.
- Gasoline Engines:Automotive V8 blocks rated 350-600 horsepower dominate existing fleet maintenance and replacement cycles. Gulf Coast fabrication shops stock standardized mounting kits for these powertrains.
- Diesel Engines:Marine-rated compression-ignition units with extended torque curves for heavy-load commercial applications. Demand concentrates in law enforcement patrol vessels requiring extended range without refueling logistics.
- Electric Engines:Brushless DC motors paired with lithium-ion battery packs displacing combustion in Florida Everglades conservation zones where EPA noise restrictions now prohibit gasoline operation. Battery density improvements are extending operational range beyond previous limitations.
- Hybrid Engines:Series-hybrid architectures combining diesel generators with electric propulsion for extended missions requiring both range and acoustic discretion. Emerging configurations for military and research applications.
Gasoline Engines retains the largest installed base; Electric Engines is climbing the fastest as regulatory deadlines approach.
Application:
Customer type differentiation separates volume-driven commercial operators from mission-critical institutional buyers with specialized certification requirements.
- Tourism:Scheduled passenger vessels with Coast Guard-inspected hull certifications and liability-driven equipment standards. Louisiana and Florida operators compete on route exclusivity in protected wetland access corridors.
- Search and Rescue:Rapid-deployment configurations with integrated communications, medical evacuation capacity, and all-weather operational ratings. State emergency management offices in Texas and Mississippi are expanding dedicated fleet procurement.
- Wildlife Conservation:Low-noise electric propulsion with non-invasive observation platforms for biological monitoring. Florida Fish and Wildlife Conservation Commission mandates are accelerating fleet conversion timelines.
- Law Enforcement:High-speed pursuit ratings with reinforced hulls for barrier penetration and suspect apprehension in marshland environments. Inter-agency task forces coordinate procurement specifications.
Tourism generates the highest unit volume; Wildlife Conservation is gaining share fastest through regulatory mandate.
End User:
Procurement channel concentration determines pricing leverage, with direct manufacturer relationships replacing dealer intermediaries for institutional accounts.
- Government Agencies:State procurement offices with consolidated vendor lists and multi-year fleet replacement schedules. Louisiana Department of Wildlife and Fisheries and Texas Parks and Wildlife Department anchor regional demand.
- Private Operators:Individual owners and small commercial ventures purchasing through dealer networks or direct factory orders. Price sensitivity drives preference for standardized hull configurations over custom fabrication.
- Environmental Organizations:Non-profit conservation groups with grant-funded acquisition and strict operational compliance requirements. Partnerships with research universities influence equipment specifications.
- Research Institutions:Academic and government laboratories requiring instrumented platforms for hydrological and ecological data collection. Custom sensor integration drives procurement decisions.
Government Agencies controls the largest contract value; Environmental Organizations is expanding most rapidly through foundation funding expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA wetland access regulations anchor demand concentration in the United States, where shallow-water conservation mandates and flood response procurement drive fleet replacement cycles across Gulf Coast states.
United States
Florida Fish and Wildlife Conservation Commission mandates are accelerating electric airboat acquisitions in Everglades conservation zones where EPA noise restrictions now prohibit gasoline operation. The US Coast Guard enforces small vessel safety standards that extend type-approval timelines for commercial hull certifications. Manufacturing clusters concentrate in Louisiana and Texas fabrication shops serving state procurement offices.
Canada
Provincial wildlife agencies in Ontario and Manitoba are expanding airboat fleets for boreal wetland access and ice rescue operations. Transport Canada administers small vessel construction standards parallel to US Coast Guard protocols, creating cross-border certification efficiencies. Quebec-based operators serve remote northern communities where conventional watercraft cannot navigate shallow river systems.
Australia
Queensland and Northern Territory environmental agencies deploy airboats for crocodile population monitoring and floodplain ecosystem research. The country's national environmental regulator enforces seasonal access restrictions in Ramsar-listed wetlands that mirror EPA conservation zone logic. Manufacturing concentrates in Brisbane-area fabricators supplying both domestic operators and Pacific island export markets.
Brazil
IBAMA, Brazil's national environmental agency, mandates low-impact vessel standards for Pantanal wetland research and ecotourism operations. State environmental police in Mato Grosso and Mato Grosso do Sul are procuring shallow-draft patrol vessels for remote waterway enforcement. Assemblers in Campo Grande serve regional demand with imported hull components and locally fabricated rigging systems.
United Kingdom
Environment Agency flood response units and RSPB conservation teams operate limited airboat fleets in Somerset Levels and East Anglian wetlands. The Maritime and Coastguard Agency applies small commercial vessel codes that restrict gasoline propulsion in noise-sensitive areas. Specialist fabricators in East Anglia maintain niche production for European conservation and rescue applications.
Airboats Market Vendor Landscape
Specialized hull fabricators and regional assemblers split the market along capability and scale vectors. The vendor base concentrates in Gulf Coast metalworking clusters where aluminum fabrication expertise and shallow-water design knowledge co-locate. Three archetypes dominate: custom hull specialists with direct agency relationships, regional assemblers sourcing standardized components, and diversified marine manufacturers extending into shallow-draft categories. Competitive moves center on backward integration into aluminum supply chains and direct procurement channel development bypassing dealer networks.
Within the specialized hull tier, Panther Airboats and Diamondback Airboats exemplify divergent strategic positioning. Panther anchors government contracting relationships through shallow-draft design specialization, while Diamondback represents in-house fabrication control over aluminum hull production and custom rigging systems. American Airboats occupies a position among regional assemblers serving price-sensitive private operators through standardized configurations. These three fabricators illustrate how technical specialization, vertical production control, and scale-driven assembly define distinct competitive positions in a market where institutional procurement consolidation rewards direct manufacturer engagement.
| Leading Market Players |
|---|
| Airboats.com |
| Marsh Master Airboats |
| Panther Airboats |
| Elite Airboats |
| American Airboats |
| Diamondback Airboats |
| Custom Airboats Inc. |
| ProAirboat Manufacturing |
| AeroWake Boats |
| Others |
Supply Flow & Price Mechanics
Aluminum sheet price volatility determines both tier spreads between custom and standard hull configurations and the geographic clustering of fabrication capacity along Gulf Coast metalworking corridors. Hull manufacturers pass commodity fluctuations through to institutional buyers via contract escalation clauses while absorbing margin compression in recreational segments.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standardized recreational hulls due to agency-specific certification requirements and integrated propulsion packages. Three-tier pricing structure across premium rescue configurations, standard commercial tour vessels, and economy recreational hulls reflects certification grade differentiation and after-sales service bundling. Cost compression in the recreational tier is intensifying because regional assemblers compete on standardized automotive powertrain mounting kits. Private operators exhibit highest price sensitivity, while government procurement offices prioritize technical compliance over unit cost.
Supply Chain Analysis
5052 marine-grade aluminum feedstock draws from primary smelters in the United States, Canada, and China before conversion at Gulf Coast rolling mills. Hull fabrication rests on aluminum sheet supply, lithium-ion battery pack availability for electric conversions, and specialized maritime welding labor pools concentrated in Louisiana and Texas. Single-source vulnerability exists in certified battery suppliers meeting pending Coast Guard safety protocols. Distribution runs through direct manufacturer relationships with state procurement offices and fragmented dealer networks serving private operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
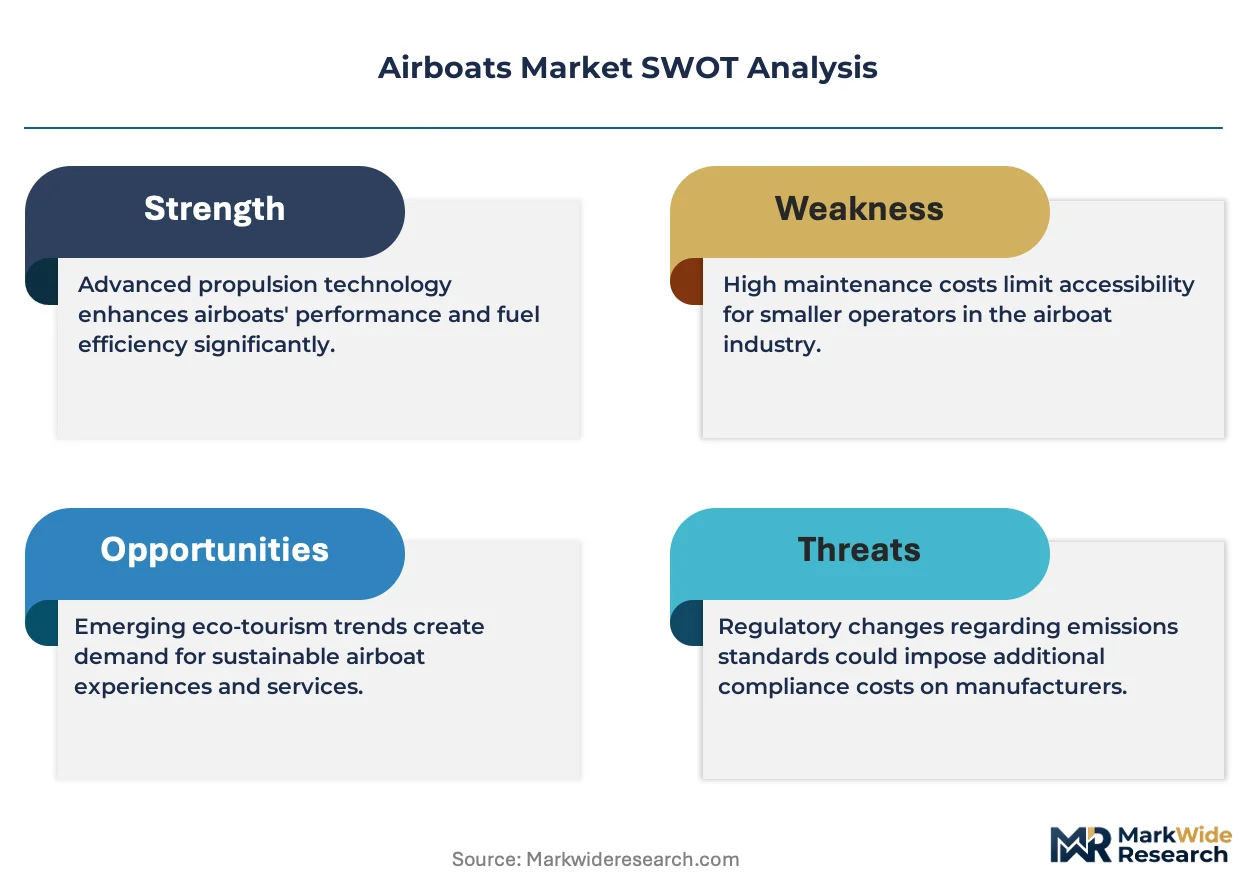
This market functions as a regulatory entrenchment story where EPA wetland access mandates and Coast Guard certification requirements create substantial switching costs for institutional buyers.
For Market Incumbents: Build certification moats by securing early Coast Guard battery safety protocol approvals ahead of electrification deadlines. Deepen backward integration into aluminum supply chains to buffer margin pressure from commodity volatility. Panther Airboats and Diamondback Airboats exemplify how direct agency relationships and in-house fabrication control defend against regional assemblers. For New Entrants and Emerging Players: Texas Coastal Bend eco-tourism represents the most penetrable white-space target, with underdeveloped guided wetland tour operations seeking commercial vessels outside government contracting channels. Queensland and Northern Territory environmental agencies in Australia offer secondary expansion corridors with parallel regulatory logic to EPA conservation zones. Partner with established Gulf Coast fabrication shops for hull production rather than greenfield capacity investment. For Investors and Strategic Acquirers: EPA electrification mandates reshape the acquisition landscape by privileging manufacturers with certified electric propulsion systems and direct state procurement relationships. Target acquisition archetypes are mid-cap hull fabricators with captive aluminum supply and established Coast Guard type-approval track records. Monitor Florida Fish and Wildlife Conservation Commission fleet conversion timelines as the primary inflection indicator for electric airboat demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Agency Sales Channel Development | Bypassing dealer networks captures consolidated Louisiana and Texas state procurement contracts. |
| Electric Propulsion Certification Investment | Early Coast Guard battery safety protocol approval locks in Florida Everglades conservation zone supply. |
| Aluminum Supply Chain Backward Integration | In-house 5052 marine-grade hull fabrication insulates margins from commodity price volatility. |
| Integrated Operator Training Packages | State procurement offices now bundle technical support with hull acquisition for vendor list consolidation. |
| Quiet Propeller Design R&D | Sound-dampening cowling engineering maintains operational permits under tightening EPA noise restrictions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with state procurement officers at Louisiana Department of Wildlife and Fisheries and Texas Parks and Wildlife Department, hull fabrication shop owners in Gulf Coast metalworking clusters, conservation fleet managers, and maritime welding specialists. Secondary validation drew from EPA wetland access regulation filings, US Coast Guard small vessel safety standard updates, customs records tracking aluminum sheet imports, and SEC filings from diversified marine manufacturers. Bottom-up hull production estimates and top-down fleet replacement cycle analysis were triangulated against state budget appropriation documents.
Calibration across the analysis window applied segment-specific growth assumptions to derive volume and value projections, with segmentation dimensions spanning hull configuration type, propulsion architecture, application mandate, and end-user procurement channel. CAGRs were computed from modeled replacement cycles and regulatory compliance deadlines rather than extrapolated historical trends. Industry-specific forecast inputs included Florida Fish and Wildlife Conservation Commission electrification timelines and Texas emergency management flood response procurement schedules.
Practitioners should monitor EPA noise restriction enforcement patterns and Coast Guard certification backlog durations for early signals of demand timing shifts. Forecasts reflect assumptions regarding lithium-ion battery density improvement trajectories and aluminum price stabilization. Cross-checking against state budget appropriation documents and federal fleet modernization announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Sea-Based Vehicle Carrier Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Marine Reciprocating Engine Market