
 Outboard Engines Market | 2026-2036
Outboard Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Outboard Engines Market Analysis
Asset-light leasing and marine equipment financing is tilting competitive access toward smaller fleet operators and independent charter businesses. Mercury Marine leverages its captive distribution network to sustain manufacturing scale across freshwater and saltwater product lines. Yamaha Motor Co., Ltd. anchors its position through vertical integration into precision-cast powerhead components. Brunswick Corporation differentiates via brand portfolio breadth spanning tournament fishing through premium yacht tender segments.
An outboard engine is a self-contained marine propulsion system mounted externally on a vessel transom, comprising a powerhead, driveshaft housing, and gearcase with propeller, typically rated from 2.5 HP to over 600 HP depending on cylinder configuration and displacement. The assembly converts internal combustion or electric energy into thrust for vessel maneuverability across recreational, commercial, and military applications. Four-stroke gasoline configurations now lead unit shipments in recreational boating due to their emissions compliance and fuel efficiency advantages over legacy two-stroke designs. Electric outboards represent the fastest-expanding segment within water sports and inland lake applications where noise restrictions and environmental sensitivity constrain internal combustion operation. Diesel outboards occupy a narrow but high-margin niche in commercial fishing and heavy-duty yacht tender roles where torque density and fuel commonality with vessel systems justify premium positioning.
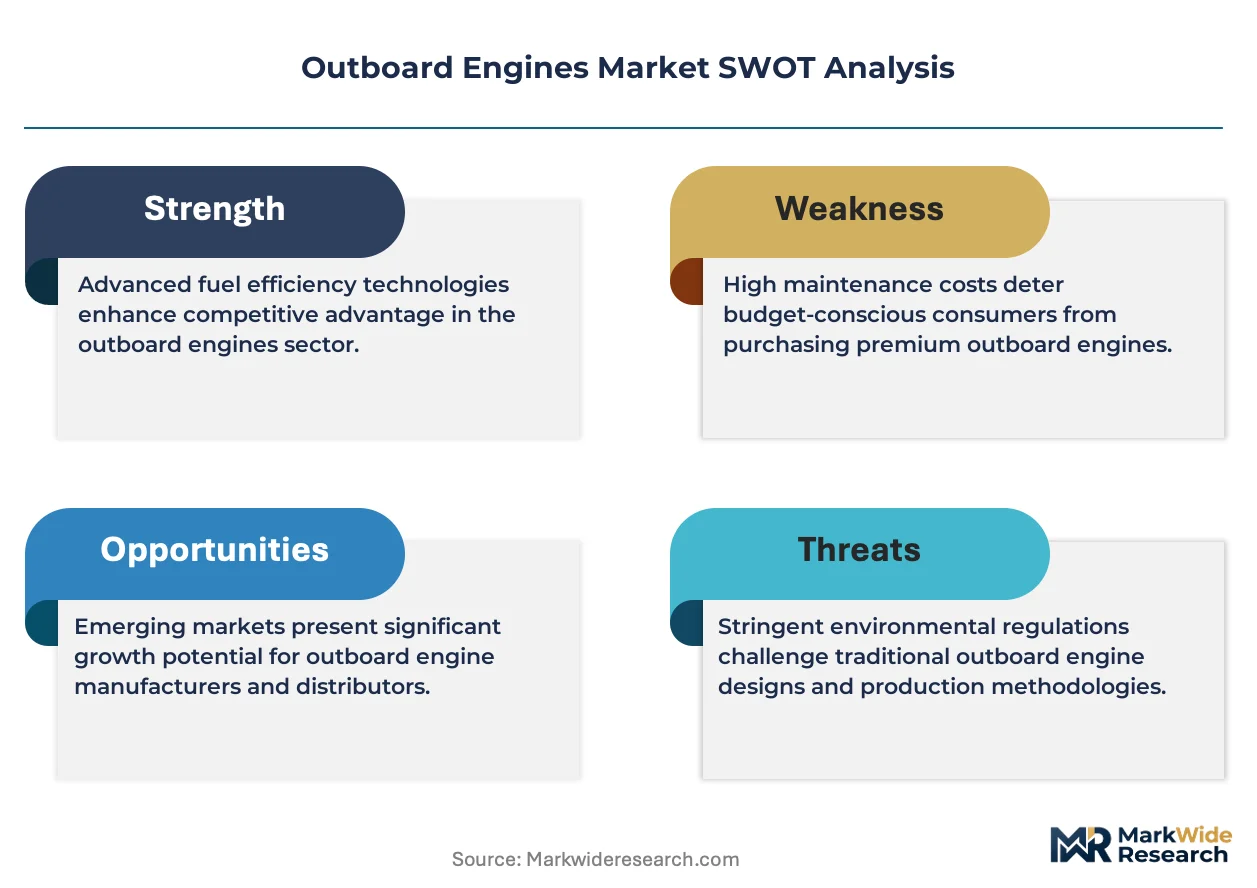
EPA Tier 3 marine emissions standards and CARB evaporative emission regulations are compelling manufacturers to redesign fuel systems and combustion chambers, directly elevating R&D recovery requirements across gasoline-dominant product portfolios. ISO 8178 test cycles and EU Recreational Craft Directive compliance costs are filtering smaller importers from European market access, consolidating certified supplier rosters. Stakeholders must monitor electrification cost curves and charging infrastructure deployment timelines to calibrate portfolio transitions between combustion and zero-emission propulsion architectures.
Market Dynamics
EPA Tier 3 marine emissions standards and CARB evaporative emission regulations are forcing gasoline outboard manufacturers to redesign fuel systems and combustion architectures, elevating R&D recovery requirements while filtering non-compliant suppliers from certified rosters.
Growth Catalysts
- Recreational fleet expansion:North American marinas are expanding motorized vessel rosters, concentrating demand in coastal United States states with established boating infrastructure and service networks.
- Electrification tailwinds:Noise restrictions and environmental sensitivity across inland lake applications are accelerating electric outboard adoption where internal combustion operation faces operational constraints.
- ISO 8178 compliance consolidation:EU Recreational Craft Directive certification costs are filtering smaller importers from European market access, consolidating certified supplier rosters among established manufacturers.
Market Restraints
- Precision-cast powerhead supply concentration:Vertical integration into critical engine block components limits second-tier manufacturers' access to high-tolerance casting capacity, constraining production scaling.
- Lithium-ion battery cost volatility:Electric outboard margins remain exposed to cathode material price swings, compressing pathway to cost parity with gasoline alternatives in high-horsepower segments.
- Torque density limitations:Diesel outboards face fundamental power-to-weight constraints versus gasoline equivalents, restricting addressable market to commercial fishing and heavy-duty yacht tender niches.
Strategic Opportunities
- Asset-light leasing penetration:Marine equipment financing models are tilting competitive access toward smaller fleet operators and independent charter businesses, expanding addressable customer base beyond traditional ownership.
- Charging infrastructure deployment:Marina dock electrification timelines in coastal United States states will calibrate electric outboard portfolio transitions between combustion and zero-emission architectures.
- Tournament fishing segment specialization:Brand portfolio breadth spanning freshwater and saltwater product lines enables premium positioning through application-specific performance tuning and service bundling.
Industry Challenges
- Emissions compliance engineering timelines:Redesign cycles for fuel system vapor recovery and combustion chamber optimization must synchronize with EPA certification windows, compressing product development schedules.
- Legacy two-stroke service network transition:Technician retraining and parts inventory reconfiguration create operational friction as four-stroke architectures displace legacy installed base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outboard Engines Market |
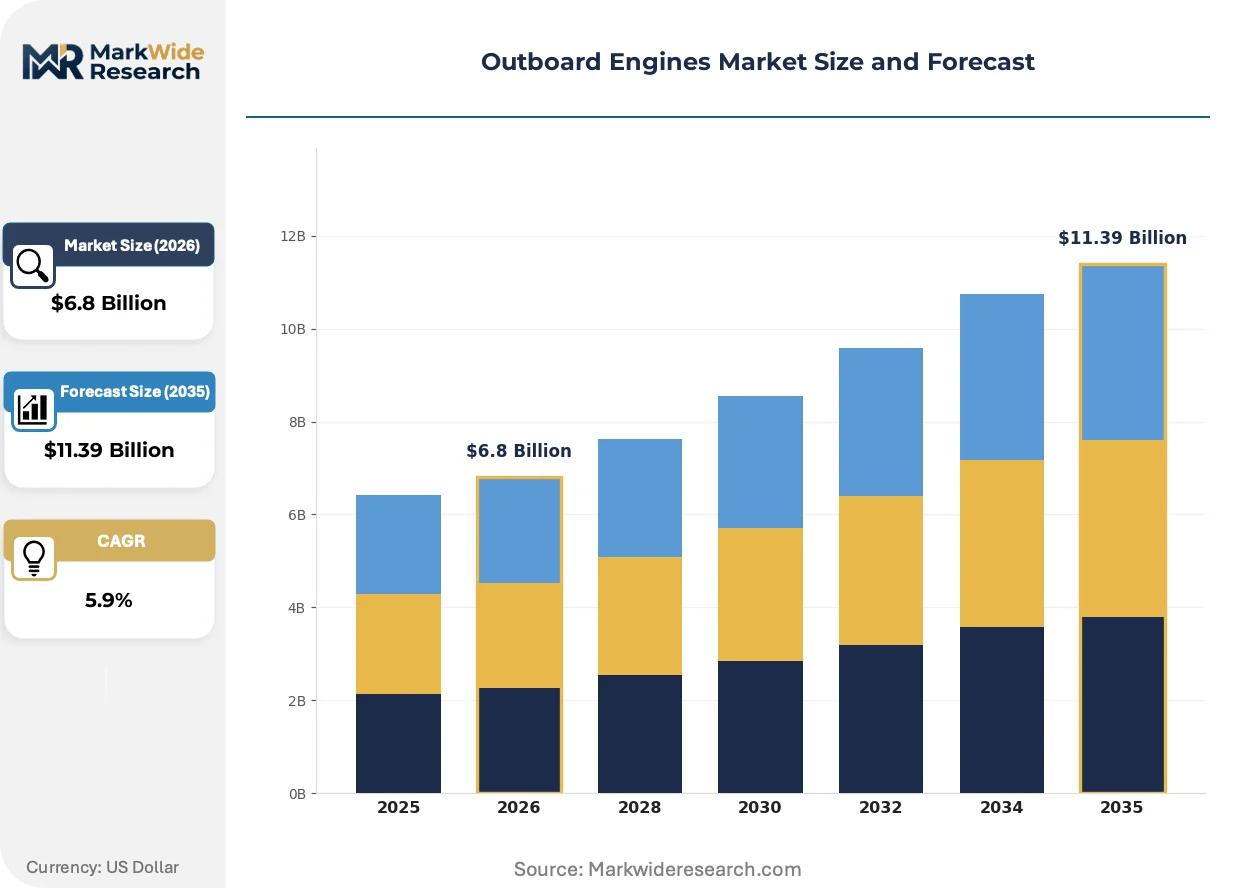
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Two-Stroke, Four-Stroke, Electric, Hybrid Power Rating: 15 HP, 30 HP, 50 HP, 100 HP Application: Recreational Boating, Commercial Fishing, Water Sports, Yachting Fuel Type: Gasoline, Diesel, Propane, Others |
| Companies Covered | Honda Motor Co., Ltd., Tohatsu Corporation, Yamaha Motor Co., Ltd., Selva SpA, AB Volvo, Mercury Marine, Suzuki Motor Corporation, Hidea Power Machinery Co. Ltd., Brunswick Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outboard Engines Market Emerging Trajectories
Propulsion architecture decisions are migrating from incremental efficiency improvements toward fundamental platform bets between refined combustion systems and battery-electric powertrains, with charging infrastructure deployment pacing regional adoption curves.
Four-stroke gasoline configurations are migrating from recreational boating dominance into commercial applications previously served by two-stroke designs. Charter operators and small-scale fishing fleets in the United States are adopting these engines at accelerating pace due to fuel efficiency advantages and emissions compliance. This migration from legacy two-stroke architectures is compressing residual value premiums for pre-Tier 3 inventory while elevating service revenue attachment rates for precision maintenance protocols.
CARB evaporative emission regulations are compelling manufacturers to integrate carbon canister systems and sealed fuel tank designs into gasoline product lines. The industrial consequence spans powerhead redesign, fuel line material specification changes, and diagnostic system upgrades. Saltwater fishing applications in California and Florida are responding fastest, with buyers prioritizing CARB-certified inventory to preempt resale restrictions and marina access limitations.
After-sales service unbundling is fragmenting traditional dealer revenue models as independent marine technicians gain access to diagnostic software and proprietary tooling. Tournament fishing segments in the southeastern United States are leading this shift, with owners separating engine purchase from maintenance contracts to optimize lifetime cost structures. This pattern is most visible in Texas and Louisiana, where independent service network density now rivals authorized dealer coverage in major metropolitan corridors.
Outboard Engines Market Segmentation
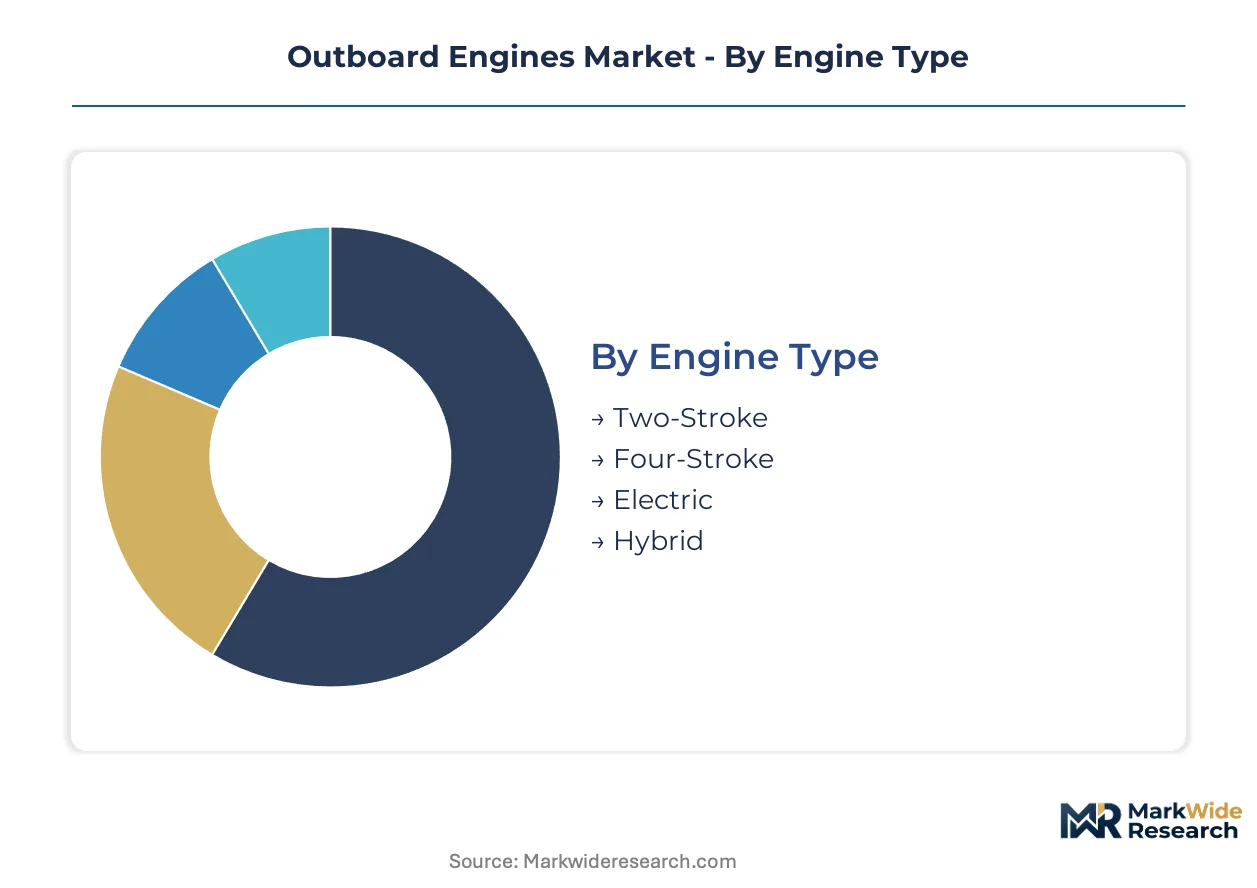
Outboard engine segmentation reveals divergent service intensity patterns across propulsion architectures. Electric and hybrid systems demand specialized technician certification and dockside charging infrastructure that reshapes dealer economics. Traditional combustion platforms sustain denser third-party service networks but face escalating compliance-driven maintenance protocols.
Engine Type:
After-sales-service intensity varies dramatically across propulsion architectures, with electric systems requiring dockside charging infrastructure and specialized technician certification that combustion platforms bypass.
- Two-Stroke:Legacy carbureted and direct-injection designs retain foothold in price-sensitive emerging markets and commercial fishing fleets prioritizing power-to-weight ratios. Southeast Asian operators continue procurement despite tightening EPA and EU emissions windows, though residual value compression accelerates fleet turnover timelines. By volume, two-stroke units still lead in developing coastal economies. By growth pace, electric configurations are ahead.
- Four-Stroke:Overhead valve and direct-acting valvetrain architectures dominate North American and European recreational boating due to EPA Tier 3 compliance and fuel efficiency advantages. CARB-certified inventory commands resale premiums in California and Florida marinas where evaporative emission regulations constrain pre-certified vessel access. Tournament fishing operators in Texas and Louisiana prioritize four-stroke torque curves for precision boat control.
- Electric:Brushless DC and permanent magnet motor systems target inland lake applications with noise restrictions and environmental sensitivity constraints. Battery-electric architectures eliminate winterization protocols but impose charging infrastructure dependency that marina electrification timelines will calibrate.
- Hybrid:Parallel and series-hybrid configurations blend combustion range extension with electric maneuvering modes for yacht tender and extended-cruise applications. Dual-powertrain complexity elevates diagnostic and parts inventory requirements beyond single-architecture service models.
Four-stroke architectures command the largest installed base. Electric systems are climbing the fastest as marina infrastructure deploys.
Power Rating:
Cost tier stratification aligns with hull displacement requirements and licensing thresholds that fragment customer acquisition economics.
- 15 HP:Single-cylinder portable outboards serve dinghy and small-craft applications where manual transportability and shallow-water operation dominate purchasing criteria. Inland lake fishermen in Minnesota and Wisconsin favor this segment for canoe and jon-boat propulsion.
- 30 HP:Twin-cylinder configurations target aluminum fishing boats and pontoon applications where horsepower-to-weight optimization balances performance with fuel economy. Coastal United States family boating clusters concentrate demand in this mid-tier bracket.
- 50 HP:Three-cylinder powerheads enable fiberglass runabout and deck boat applications with watersports towing capability. This threshold marks the transition from portable to permanent mounting configurations, elevating dealer installation revenue attachment.
- 100 HP:Four-cylinder and V6 architectures serve offshore fishing and performance pontoon segments where hull size and passenger capacity demand sustained high-RPM operation. Saltwater corrosion protection specifications differentiate premium from standard offerings.
By volume, 30 HP and 50 HP brackets dominate unit shipments. By margin contribution, 100 HP configurations lead.
Application:
Customer type fragmentation separates ownership models from charter and fleet operators with divergent financing and maintenance contract structures.
- Recreational Boating:Private owners prioritize brand reputation, warranty terms, and resale value preservation in freshwater and saltwater configurations. Tournament fishing segments demand application-specific performance tuning and rapid service turnaround commitments.
- Commercial Fishing:Fleet operators emphasize total cost of ownership calculations spanning fuel efficiency, maintenance intervals, and downtime minimization. Diesel compatibility with vessel fuel systems drives niche specification requirements.
- Water Sports:Wakeboarding and waterskiing applications demand precise throttle response and sustained RPM capability for ballast-loaded hulls. Electric outboards gain traction where noise restrictions constrain combustion operation.
- Yachting:Tender and auxiliary propulsion roles prioritize compact stowage dimensions and corrosion-resistant materials for saltwater exposure. Premium positioning justifies integrated control system compatibility with mothership electronics.
Recreational applications generate the highest unit volumes. Commercial fishing delivers the most stable replacement demand cycles.
Fuel Type:
Supply concentration in gasoline refining and distribution infrastructure constrains alternative fuel penetration despite regulatory tailwinds.
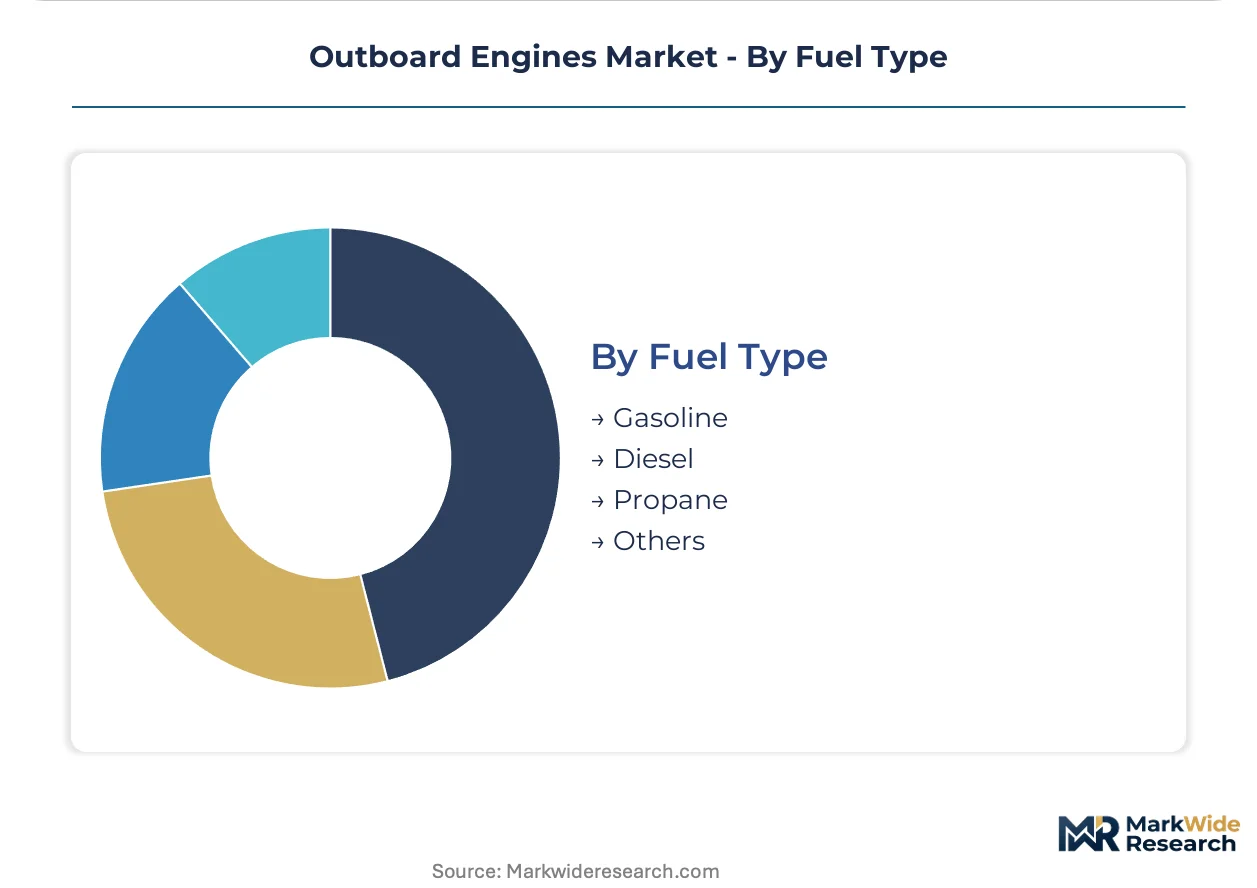
- Gasoline:Port fuel injection and direct-injection architectures dominate recreational and light-commercial segments with established marina fueling infrastructure. EPA Tier 3 and CARB evaporative emission regulations force carbon canister integration and sealed fuel system redesigns.
- Diesel:Compression-ignition outboards occupy high-torque commercial niches where fuel commonality with vessel systems and safety considerations override power-to-weight penalties. European commercial fishing fleets and heavy-duty yacht tenders sustain demand.
- Propane:LPG conversions and dedicated propane injection systems target environmental compliance in enclosed waterways and emission-restricted lakes. Fuel tank certification and storage logistics limit geographic penetration.
- Others:Compressed natural gas and hydrogen pilot programs remain experimental, constrained by bunkering infrastructure absence and power density limitations versus liquid fuels.
Gasoline retains overwhelming volume leadership. Electric propulsion is expanding most quickly among alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows favor established manufacturing bases with captive distribution networks, while demand concentrates in coastal economies with marina infrastructure density. The United States maintains net importer status for high-horsepower configurations despite domestic assembly presence.
United States
Recreational fleet expansion drives motorized vessel procurement across Florida, Texas, and California coastal clusters. EPA Tier 3 marine emissions standards and CARB evaporative emission regulations compel carbon canister integration and sealed fuel system redesigns. Tournament fishing operators in the southeastern states prioritize four-stroke torque curves for precision boat control.
Japan
Precision-cast powerhead component supply anchors domestic manufacturing scale for regional export markets. METI industrial standards and JIS certification protocols filter non-compliant importers from certified supplier rosters. Nagoya-based production clusters concentrate vertical integration into critical engine block casting capacity.
China
Price-sensitive emerging market demand sustains two-stroke procurement despite tightening emissions windows. MIIT equipment standards and GB certification requirements elevate compliance costs for smaller fabricators. Yangtze River Delta manufacturing corridors concentrate assembly operations for Southeast Asian export destinations.
Germany
Commercial fishing fleet operators emphasize total cost of ownership calculations spanning fuel efficiency and maintenance intervals. EU Recreational Craft Directive and ISO 8178 test cycles consolidate certified supplier rosters among established manufacturers. Northern maritime regions sustain diesel outboard specification for torque-density applications.
Italy
Premium yacht tender and auxiliary propulsion roles prioritize compact stowage dimensions and corrosion-resistant materials. CE marking and REACH chemical compliance elevate material specification costs for saltwater exposure applications. Adriatic coastal marinas concentrate demand for integrated control system compatibility with mothership electronics.
Outboard Engines Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturers with captive distribution networks and in-house production of critical powerhead components. Three strategic archetypes dominate: vertically integrated full-line producers, specialized high-torque diesel fabricators, and emerging electric propulsion specialists. Competitive moves center on portfolio diversification between combustion and zero-emission architectures and geographic expansion through marina service network density.
Among Japanese motor manufacturers, Yamaha Motor Co., Ltd. and Honda Motor Co., Ltd. represent the vertically integrated archetype with upstream control over precision-cast component supply. Brunswick Corporation occupies a position exemplifying brand portfolio breadth across freshwater and saltwater product lines. These three anchors illustrate how competitive positioning stratifies between manufacturing scale, distribution captivity, and application-specific performance tuning.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Tohatsu Corporation |
| Yamaha Motor Co., Ltd. |
| Selva SpA |
| AB Volvo |
| Mercury Marine |
| Suzuki Motor Corporation |
| Hidea Power Machinery Co. Ltd. |
| Brunswick Corporation |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on precision-cast aluminum powerhead components determines both the spread between premium and economy tier pricing and the geographic clustering of final assembly operations. Manufacturers with captive foundry capacity in Japan and the United States command wider margin buffers against import duty volatility than assemblers dependent on Chinese casting supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the outboard engines market. Price differentiation hinges on CARB certification tier and EPA Tier 3 compliance grade, with evaporative emission-compliant inventory commanding resale premiums in California and Florida marinas. Pricing pressure stems from lithium-ion cathode material cost volatility compressing electric outboard margins against gasoline alternatives. Charter fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while yacht tender specifications show lowest sensitivity given mothership integration requirements.
Supply Chain Analysis
Precision-cast aluminum feedstock and rare earth magnet supply concentrate manufacturing gravity across Japan, China, and the United States. Critical inputs include high-tolerance engine block castings, permanent magnet motor components, and sealed fuel system vapor recovery hardware. Single-source vulnerability in Nagoya-based powerhead casting capacity creates bottleneck risk for second-tier assemblers lacking backward integration. Distribution runs through captive marina dealer networks and independent marine service channels with divergent diagnostic software access tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across propulsion architectures creates white-space opportunities as electrification timelines diverge by horsepower segment and geographic marina infrastructure deployment. Fleet operators and independent charter businesses represent the fastest-expanding demand archetype outside traditional ownership models.
For Market Incumbents: Insulate manufacturing scale through captive precision-cast component supply and EPA certification roster depth against emerging electric specialists with superior dockside charging partnerships. Priority levers include carbon canister integration R&D recovery and saltwater corrosion specification differentiation for tournament fishing segments in Texas and Louisiana. For New Entrants and Emerging Players: Build out marina electrification partnerships in Minnesota and Wisconsin inland lake clusters where noise restrictions constrain combustion operation and charging infrastructure gaps persist. Target 15 HP to 30 HP portable electric configurations for canoe and jon-boat applications with lowest incumbent service network density. For Investors and Strategic Acquirers: The market sits at a platform transition phase that favors hybrid combustion-electric specialists with yacht tender integration capabilities over pure-play gasoline incumbents. Long-term viability hinges on charging infrastructure deployment pacing across coastal United States states. Signal to monitor: marina dock electrification permit acceleration in Florida and California as inflection indicator for electric outboard adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Canister Integration | EPA Tier 3 compliance enables California and Florida marina access for gasoline product lines. |
| Precision-Cast Powerhead Capacity Expansion | Captive foundry investment in Nagoya or Tennessee insulates against tariff exposure on engine block supply. |
| Marina Charging Infrastructure Partnership | Dock electrification agreements in Minnesota and Wisconsin calibrate electric portfolio timing against infrastructure deployment. |
| Tournament Fishing Service Network Density | Independent technician certification programs in Texas and Louisiana fragment traditional dealer revenue models. |
| Hybrid Propulsion Architecture Development | Dual-powertrain configurations address yacht tender range requirements with electric maneuvering modes. |
Methodological Framework
Cross-validation between OEM procurement director interviews and customs trade data anchors the qualitative findings on supply chain concentration. Primary fieldwork encompassed marine engine plant managers, marina operator procurement leads, aftermarket service technicians, and tournament fishing fleet operators. Secondary validation drew from EPA certification filings, CARB evaporative emission test data, marina infrastructure development permits, and SEC 10-K disclosures from listed manufacturers. Bottom-up unit shipment modeling and top-down value chain triangulation reconciled volume estimates across the analysis window.
Calibration against historical EPA certification cycles and marina electrification deployment timelines shaped the projection framework. Segmentation dimensions modeled include propulsion architecture, horsepower tier, application type, and regional regulatory cluster. CAGRs derived from installed base turnover rates, fleet expansion patterns, and electrification substitution curves. Industry-specific inputs encompassed lithium-ion battery cost trajectories and precision-casting capacity utilization rates.
Stress conditions across cathode material price volatility, tariff rate fluctuations, and EPA certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on marina infrastructure deployment pacing and emissions regulatory enforcement intensity. Cross-checking against state-level marina electrification permit databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Reciprocating Engine Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Europe Inland Waterways Vessel Market