
 Marine Passenger Seat Market | 2026-2036
Marine Passenger Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Passenger Seat Market Analysis
Aftermarket refurbishment revenue is reconfiguring margin distribution across the marine seating value chain. Springfield Marine Company leverages its vertical integration into aluminum frame extrusion to sustain pricing power in North American commercial vessel contracts. Todd Marine Products anchors its position through specialized shock-absorbing seat engineering for high-speed ferry applications. Ullman Dynamics differentiates via R&D intensity in ergonomic suspension systems for offshore passenger transport.
Marine passenger seats are engineered structures combining corrosion-resistant frames with fire-rated upholstery, designed to withstand dynamic vessel motion, salt exposure, and repetitive loading cycles exceeding marine safety standards. Their primary purpose centers on occupant safety, comfort, and regulatory compliance during commercial and recreational waterborne transit. Folding seats lead the product type category due to space optimization demands on compact commercial vessels, while shock-absorbing features command premium positioning in offshore ferry specifications. Recreational boats represent the fastest-growing end user segment as leisure boating participation expands across coastal economies.
The U.S. Coast Guard enforces structural fire protection standards through 46 CFR subchapter T, directly mandating flame-retardant material specifications for passenger vessel seating assemblies. The International Maritime Organization's SOLAS convention shapes global product access requirements, while the EU Marine Equipment Directive establishes conformity pathways for seats installed on European-flagged vessels. Stakeholders must monitor evolving harmonization between national maritime safety administrations and international certification frameworks to anticipate compliance-driven replacement cycles.
Market Dynamics
The International Maritime Organization's updated fire safety codes are forcing wholesale replacement of non-compliant seating fleets across commercial ferry operators, compressing procurement timelines and redistributing contract volume toward certified suppliers.
Growth Catalysts
- IMO SOLAS Chapter II-2 amendments:Mandatory flame-retardant upholstery specifications are triggering fleet-wide retrofit programs among Southeast Asian ferry operators.
- Aluminum extrusion advances:Corrosion-resistant frame manufacturing is reducing seat weight by fifteen to twenty percent, enabling higher passenger density on compact commercial vessels.
- Vietnam-Indonesia procurement clusters:Mid-range commercial vessel retrofits are concentrating regional demand, creating scale economies for regional fabricators.
Market Restraints
- Fire-rated foam input volatility:Specialized polyurethane formulations face price instability due to concentrated petrochemical feedstock supply.
- Single-source certification dependency:Lloyd's Register and DNV GL testing bottlenecks create twelve-to-eighteen-month approval queues for new seat designs.
- Structural steel substitution:Lower-cost welded bench seating persists in budget ferry segments, capping premium product penetration.
Strategic Opportunities
- Offshore wind crew transfer vessels:High-impact suspension seating demand is emerging from North Sea and East Asian wind farm service fleets.
- EU Marine Equipment Directive harmonization:Mutual recognition agreements are opening pathways for Asian manufacturers to access European-flagged vessel contracts.
- Digital specification platforms:Online configurators are collapsing traditional distributor layers, enabling direct OEM-to-operator contracting.
Industry Challenges
- Marine upholstery technician scarcity:Skilled craftspeople capable of fire-rated material installation and seam welding remain concentrated in legacy shipbuilding regions.
- Legacy vessel structural incompatibility:Retrofit mounting patterns for aging steel decks conflict with modern aluminum frame designs, requiring custom adapter engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Passenger Seat Market |
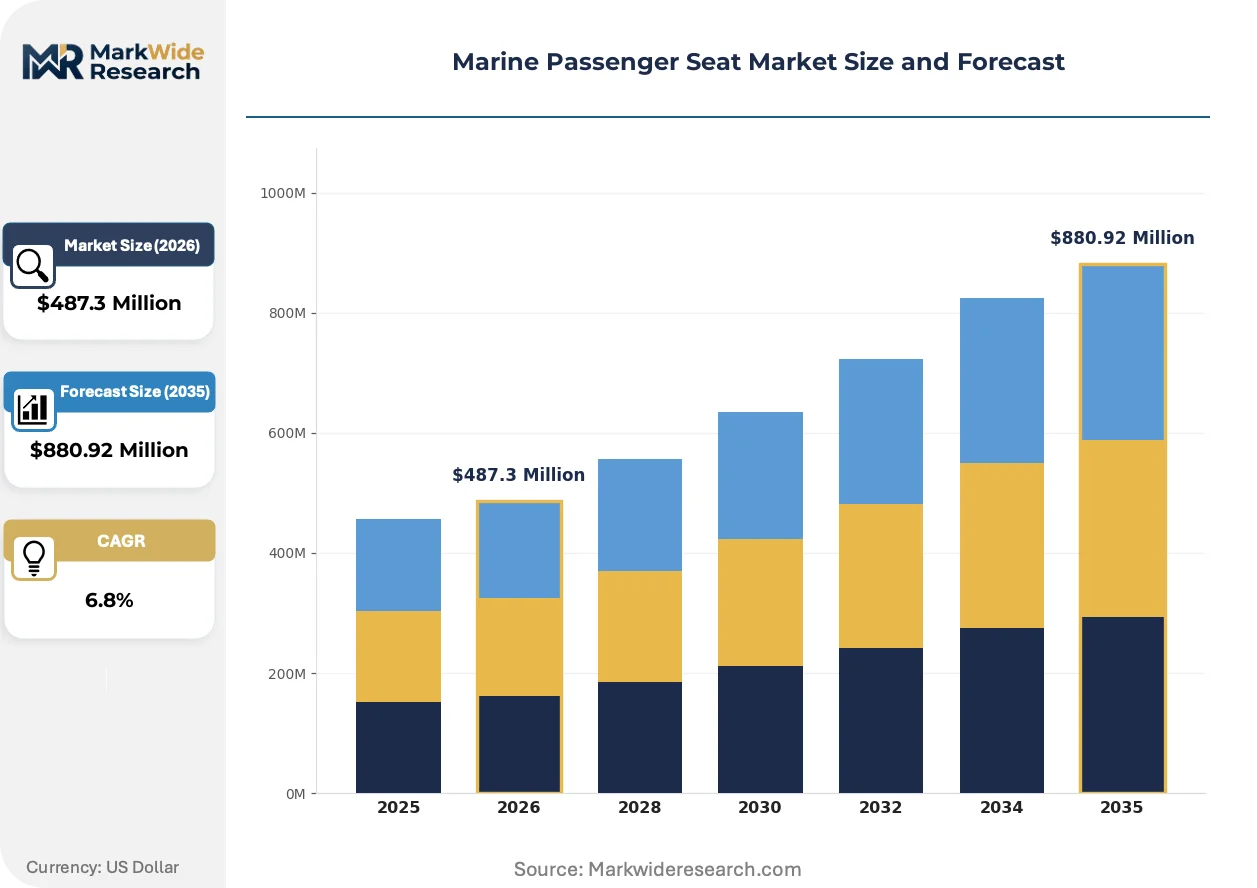
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recliner Seats, Fixed Seats, Folding Seats, Sliding Seats End User: Commercial Vessels, Recreational Boats, Ferries, Yachts Material: Leather, PVC, Fabric, Aluminum Feature: Adjustable Armrests, Built-in Storage, Easy Clean, Shock Absorbing |
| Companies Covered | Springfield Marine Company, Mercury Marine, West Marine, Ullman Dynamics, Todd Marine Products, The Wise Company, Inc., Stidd Systems Inc., NorSap AS, Quality Pacific Manufacturing, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Passenger Seat Market Emerging Trajectories
Active suspension systems and smart materials are redefining passenger comfort benchmarks while regulatory pressure on fire safety is compressing product development cycles across the supply base.
Magnetorheological damper technology is collapsing the performance gap between passive and active seating systems. High-speed ferry operators in the Mediterranean and Baltic are adopting these units for routes exceeding forty knots. The technology is collapsing premium pricing tiers as mid-range vessels spec comparable shock absorption.
REACH Annex XVII restrictions on flame retardants are forcing reformulation of polyurethane foam cores across European supply chains. Manufacturers must phase out legacy halogenated compounds by specified deadlines. Recreational boat builders face compressed compliance timelines compared to commercial operators with grandfathered fleet exemptions.
Operator procurement teams are consolidating seat purchases into vessel-wide outfitting contracts rather than component-level sourcing. Traditional marine equipment distributors are losing share to turnkey interior integrators. This pattern is most visible in Scandinavian and German ferry operator tendering, where lifecycle cost models dominate evaluation criteria.
Marine Passenger Seat Market Segmentation
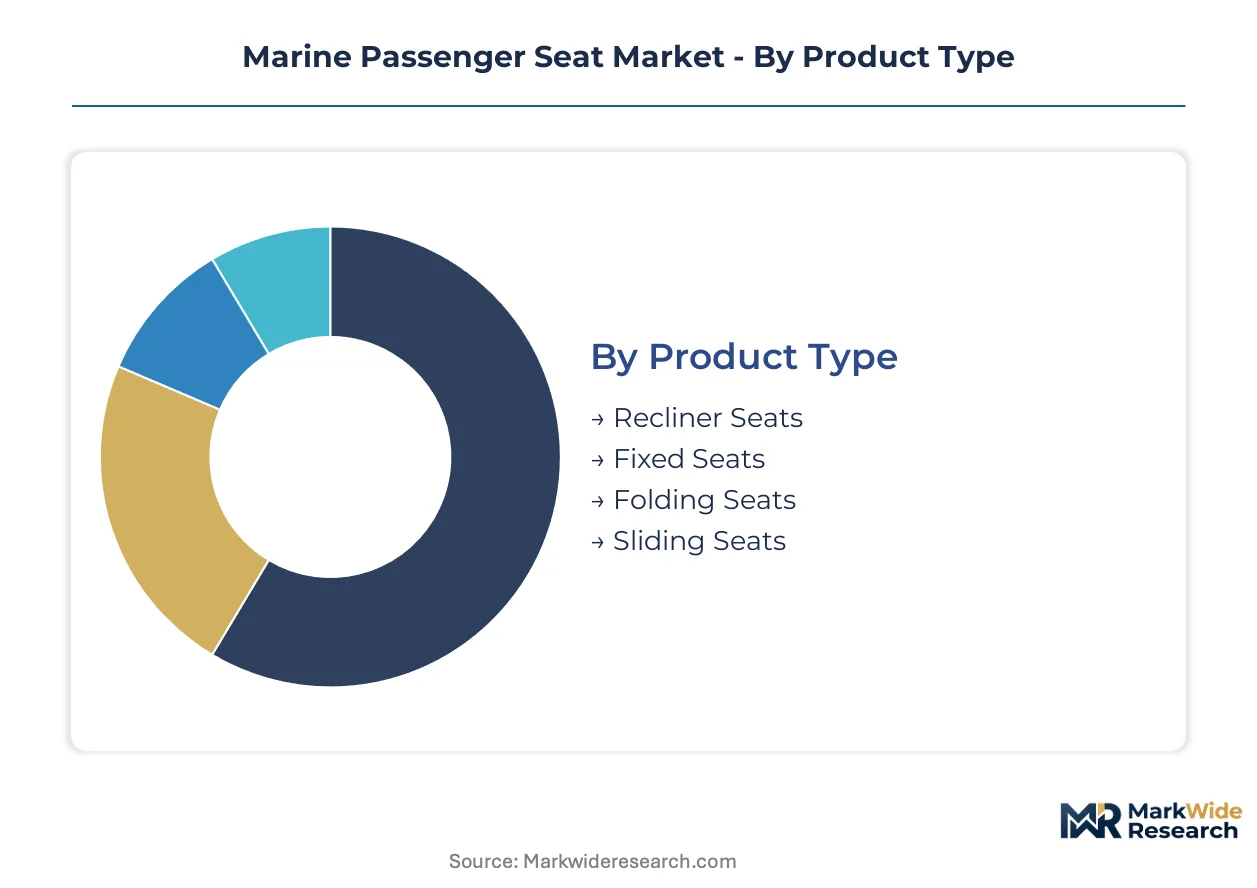
Seat architecture varies sharply across vessel classes, with regulatory compliance and space constraints driving specification divergence. Procurement teams weight fire safety certification, weight reduction, and passenger density differently depending on operational profile and route characteristics.
Product Type:
Mature folding designs dominate compact commercial fleets while emerging active suspension systems reshape premium ferry specifications.
- Folding Seats:Collapsible aluminum-frame designs maximize passenger density on space-constrained commuter ferries and water taxis. Vietnam and Indonesia retrofit programs concentrate procurement volume for mid-range folding configurations.
- Fixed Seats:Rigid-mount structures with integrated fire-rated upholstery anchor regulatory compliance in SOLAS-mandated fleet upgrades. Mediterranean operators prioritize these for high-frequency routes where durability trumps flexibility.
- Recliner Seats:Articulating backrest mechanisms with corrosion-resistant hinges target overnight ferry cabins and premium yacht lounges.
- Sliding Seats:Fore-aft adjustment rails accommodate variable passenger loads on multi-purpose deck configurations.
Folding seats retain volume leadership; shock-absorbing fixed configurations hold the steepest expansion curve.
End User:
Application context determines whether procurement prioritizes regulatory compliance, passenger comfort metrics, or lifecycle cost optimization.
- Ferries:High-capacity bench and individual seating systems face mandatory IMO fire safety retrofit deadlines across Southeast Asian operators. Shock-absorbing specifications climb on routes exceeding thirty-five knots.
- Recreational Boats:Premium upholstery and ergonomic contouring command price premiums in coastal leisure markets. REACH Annex XVII flame-retardant phaseouts compress reformulation timelines for European builders.
- Commercial Vessels:Crew transfer and offshore supply operations specify suspension seating for sea state tolerance.
- Yachts:Custom leather and exotic material finishes differentiate superyacht interior specifications.
Ferries generate the highest unit volumes; recreational boats are climbing fastest on participation expansion.
Material:
Cost tier and performance requirements split procurement between synthetic surfaces and metal structural elements.
- Aluminum:Extruded and cast frame components deliver fifteen-to-twenty percent weight reduction versus legacy steel. Springfield Marine and Todd Marine Products maintain captive extrusion capacity for margin control.
- PVC:Marine-grade synthetic upholstery balances chemical resistance and cleanability for high-turnover ferry applications. Fire-rated foam backing layers add certification complexity.
- Fabric:Woven polyester and acrylic blends with fluoropolymer treatments target mid-range commercial specifications.
- Leather:Full-grain and corrected-grain surfaces dominate yacht and premium recreational segments.
Aluminum frames anchor structural procurement; PVC upholstery surfaces expand most quickly on regulatory retrofit demand.
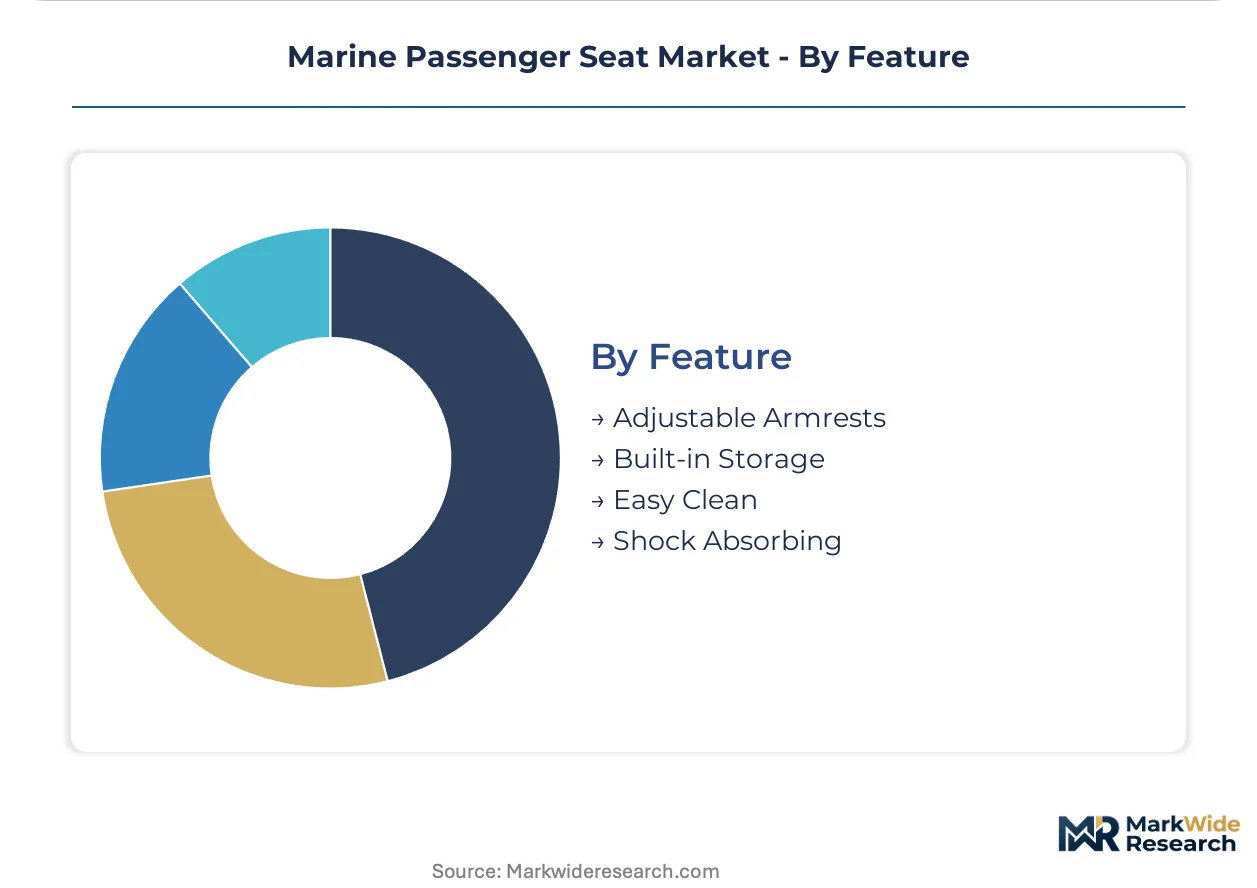
Feature:
Functional differentiation separates commodity seating from value-added configurations commanding price premiums.
- Shock Absorbing:Magnetorheological damper and passive spring suspension systems reduce impact loading on high-speed craft. Ullman Dynamics and Todd Marine Products specialize in this engineering tier.
- Easy Clean:Seam-welded upholstery and non-porous surfaces minimize turnaround maintenance for commuter operators.
- Built-in Storage:Under-seat compartments and backrest pockets address space constraints on compact vessels.
- Adjustable Armrests:Width and height modification accommodates varying passenger demographics and accessibility requirements.
Shock absorption commands the highest price premiums; easy-clean specifications retain broadest commercial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ferry operators in Vietnam and Indonesia show the highest price elasticity, squeezing margins on standard folding seats, while North Sea wind farm contractors absorb premium shock-absorbing configurations with minimal negotiation.
United States
The U.S. Coast Guard enforces 46 CFR subchapter T fire protection standards, mandating flame-retardant upholstery for all passenger vessel seating assemblies. Commercial ferry operators on the Pacific Northwest routes face compressed retrofit timelines. Seattle-area shipyards concentrate procurement activity for aluminum-frame seat installations on aging steel-deck vessels.
Germany
Baltic Sea ferry operators specify magnetorheological damper systems for high-speed routes exceeding forty knots. REACH Annex XVII restrictions on halogenated flame retardants force polyurethane foam reformulation across domestic supply chains. Hamburg and Kiel anchor the procurement clusters for turnkey interior outfitting contracts.
China
Domestic ferry fleet modernization drives volume demand for mid-range folding seat configurations. MIIT and SAMR coordinate marine equipment certification pathways under GB standards. The Yangtze River Delta shipyards concentrate regional production capacity for corrosion-resistant aluminum extrusion.
Norway
Offshore wind crew transfer vessels generate specialized demand for high-impact suspension seating. The Norwegian Maritime Authority aligns domestic fire safety regulations with SOLAS Chapter II-2 amendments. Stavanger and Bergen anchor the North Sea supply chain for shock-absorbing seat engineering.
Indonesia
Archipelago ferry operators replace aging seating fleets to accommodate rising inter-island passenger volumes. The national maritime safety administration implements IMO-mandated fire safety retrofits across commercial fleets. Surabaya and Jakarta concentrate procurement activity for mid-range vessel retrofit programs.
Marine Passenger Seat Market Vendor Landscape
Vertically integrated frame manufacturers and specialized suspension engineering houses split the market into distinct capability tiers. Consolidation pressure concentrates around certified suppliers capable of meeting Lloyd's Register and DNV GL testing queues. Three archetypes dominate: captive aluminum extruders controlling upstream material costs, ergonomic R&D specialists commanding premium positioning, and regional fabricators capturing scale economies in retrofit clusters. Competitive moves center on backward integration into corrosion-resistant metal production and direct OEM-to-operator contracting platforms.
Among North American manufacturers, Springfield Marine Company exemplifies the captive extrusion archetype through its in-house aluminum frame production. Todd Marine Products occupies a position within the specialized engineering tier, while Ullman Dynamics anchors the ergonomic R&D specialist segment. These three represent the strategic positioning spectrum visible across the competitive set.
| Leading Market Players |
|---|
| Springfield Marine Company |
| Mercury Marine |
| West Marine |
| Ullman Dynamics |
| Todd Marine Products |
| The Wise Company, Inc. |
| Stidd Systems Inc. |
| NorSap AS |
| Quality Pacific Manufacturing, Inc. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta shipyards concentrate aluminum extrusion capacity for marine frame production, feeding downstream pricing power to seat assemblers who control corrosion-resistant metal supply. This geographic clustering compresses input costs for regional fabricators while forcing distant competitors to absorb logistics premiums or surrender margin.
Pricing Analysis
Aftermarket refurbishment contracts and spare parts provisioning drive lifetime value capture across the marine seating value chain. Three-tier pricing structure across premium shock-absorbing, standard fixed-mount, and economy folding configurations separates certified IMO-compliant suppliers from uncertified regional competitors. Pricing pressure stems from Vietnam-Indonesia procurement clusters squeezing mid-range folding seat margins through volume aggregation. Ferry operators in Southeast Asia exhibit highest price sensitivity, while North Sea wind farm contractors absorb premium suspension seating with minimal negotiation.
Supply Chain Analysis
Contract manufacturing for marine seating concentrates among Yangtze River Delta metal fabricators, Vietnamese aluminum processors, and Indonesian upholstery workshops. Raw material flows draw from Chinese aluminum billet suppliers, South Korean petrochemical feedstocks for fire-rated polyurethane, and European fluoropolymer treatment specialists. Single-source certification dependency at Lloyd's Register and DNV GL testing facilities creates twelve-to-eighteen-month approval bottlenecks. Distribution runs through traditional marine equipment distributors losing share to turnkey interior integrators in Scandinavian and German ferry procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital specification platforms are collapsing traditional distributor layers, creating platform-economics inflection as direct OEM-to-operator contracting replaces multi-tier channel structures. Interoperability between online configurators and vessel outfitting software is rewiring procurement authority toward fleet operators.
For Market Incumbents: Entrench position through captive aluminum extrusion capacity and accelerated Lloyd's Register certification pipelines to outpace testing bottlenecks. Defend against emerging Asian fabricators by locking long-term supply agreements with Yangtze River Delta metal suppliers. Prioritize R&D investment in magnetorheological damper miniaturization to maintain premium tier differentiation as mid-range vessels adopt comparable shock absorption.
For New Entrants and Emerging Players: Pursue white-space opportunity in offshore wind crew transfer vessel seating across North Sea and East Asian wind farm service fleets. Target Indonesia's archipelago ferry retrofit programs where procurement decentralization creates entry points against established European suppliers. Lead with digital specification platforms enabling direct operator engagement, bypassing traditional distributor relationships that incumbent players dominate.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because IMO SOLAS amendment cycles create predictable replacement demand independent of vessel newbuild cycles. Acquisition targets should display captive aluminum extrusion or specialized suspension engineering capabilities with Lloyd's Register approval queues already cleared. Monitor Lloyd's Register and DNV GL testing queue lengths as inflection signal—shortening queues indicate supply base expansion and margin compression risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive frame production secures margin control against Yangtze River Delta supply volatility. |
| Magnetorheological Damper R&D Investment | Active suspension engineering differentiates premium positioning as technology commoditizes downstream. |
| Direct OEM-to-Operator Digital Platform | Online configurators collapse distributor layers and capture procurement authority from traditional channels. |
| IMO SOLAS Certification Pipeline Expansion | Accelerated Lloyd's Register approval queues lock out competitors facing twelve-to-eighteen-month delays. |
| Offshore Wind Vessel Seating Specialization | North Sea and East Asian wind farm fleets generate specialized demand for high-impact suspension systems. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with ferry procurement directors, shipyard outfitting managers, marine upholstery technicians, and classification society surveyors; and secondary validation through Lloyd's Register type-approval databases, DNV GL maritime equipment registers, IMO SOLAS amendment documentation, and customs trade records for aluminum extrusion and fire-rated foam inputs. Bottom-up vessel fleet analysis and top-down maritime equipment spending estimates were triangulated to establish market sizing.
Forecast inputs across the projection horizon incorporated product type segmentation by seat architecture, end-user vessel class differentiation, material composition tiers, and feature-based functional categories. CAGRs were derived from regression analysis against historical fleet replacement cycles, regulatory compliance deadline clustering, and regional procurement pattern shifts. Industry-specific forecast inputs included IMO SOLAS Chapter II-2 amendment implementation timelines and REACH Annex XVII flame-retardant phaseout schedules.
Macroeconomic conditions sit as an overlay; deviation in marine freight rates, shipyard orderbook depth, or petrochemical feedstock pricing would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and certification body capacity expansion. Quarterly review of Lloyd's Register and DNV GL approval queue lengths, Southeast Asian ferry operator tender announcements, and aluminum LME pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Sea-Based Vehicle Carrier Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Airboats Market
Marine Vehicles
Global Catamaran Market