
 Air-Cushion Vehicle Market | 2026-2036
Air-Cushion Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Cushion Vehicle Market Outlook
Amphibious manufacturing capacity in Eastern Europe is hardening as Ukrainian and Russian hull producers suspend operations. Griffon Hoverwork sustains its position through specialized military craft for littoral operations. China Hovercraft Ltd dominates domestic procurement with state-backed production scale. Textron Systems leverages its defense contracting network across NATO-aligned navies.
An air-cushion vehicle rides on a pressurized air layer contained within a flexible skirt, enabling traversal of water, ice, mud, and uneven terrain without hull contact. Lift fans generate pressures of 500-2,500 pascals to maintain ground effect separation, with powerplants ranging from diesel engines to gas turbines driving both lift and propulsion systems. Military Operations applications lead current procurement volumes, particularly for beach assault and logistics roles where conventional landing craft face access constraints. Electric Propulsion technology is gaining fastest traction in Search and Rescue configurations, where noise reduction and fuel logistics simplicity outweigh power density limitations. Hybrid Systems occupy the premium margin pool in Defense end-user contracts, combining turbine endurance with electric stealth modes.
ISO 12217 stability standards and the EU Green Deal emissions framework shape product certification requirements for commercial sales in European waters. The US Navy's Naval Sea Systems Command and the UK's Defence Equipment and Support directorate govern military qualification pathways, with ITAR and export control regimes filtering technology transfer. China's MIIT issues GB standards for domestic hovercraft construction, while SAMR enforces safety compliance for civilian operations. Stakeholders must weigh propulsion technology bets against evolving defense procurement cycles and decarbonization mandates that threaten gas turbine economics.
Market Dynamics
Defense procurement cycles in littoral warfare are compressing development timelines for amphibious craft, while EU Green Deal emissions mandates force propulsion architecture bets that lock manufacturers into decade-long technology commitments.
Growth Catalysts
- Naval modernization programs:Asia-Pacific littoral states are expanding beach assault capabilities. Procurement volumes concentrate in coastal China and the Korean peninsula for military logistics roles.
- EU Green Deal framework:Stricter marine emissions standards under this regulation are accelerating electric and hybrid propulsion development for commercial hovercraft operating in European waters.
- Arctic access requirements:Ice-capable hovercraft demand is rising as polar logistics routes open. Search and rescue configurations prioritize noise reduction and fuel logistics simplicity.
Market Restraints
- Gas turbine economics:Decarbonization mandates threaten conventional powerplant cost structures. Manufacturers face stranded asset risk on existing engine supply chains.
- Skirt material volatility:Reinforced elastomer and coated fabric input costs fluctuate with petrochemical feedstock prices. Ukrainian and Russian hull producers have suspended operations.
- Power density limitations:Battery energy density constrains electric hovercraft range and payload. This technical ceiling limits pure-electric configurations to short-haul rescue missions.
Strategic Opportunities
- Hybrid architecture premium:Defense contracts increasingly specify turbine-electric systems combining endurance with electric stealth modes. This convergence creates margin expansion potential.
- Coastal logistics corridors:Underpenetrated commercial routes between island chains and mainland ports offer volume growth. Intermodal freight integration remains nascent.
- ISO 12217 certification alignment:Stability standard harmonization across European waters reduces duplicate testing burdens. Compliance simplification accelerates product registration timelines.
Industry Challenges
- Lift fan aerodynamics expertise:Specialized computational fluid dynamics and skirt design talent pools are shallow. Recruitment competition with aerospace and automotive sectors intensifies.
- Dual-use export control navigation:ITAR and national military qualification pathways create licensing complexity. Technology transfer restrictions fragment supplier networks.
- Legacy system integration:Naval customers require backward compatibility with existing amphibious assault command structures. Interface standardization delays fleet-wide deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Cushion Vehicle Market |
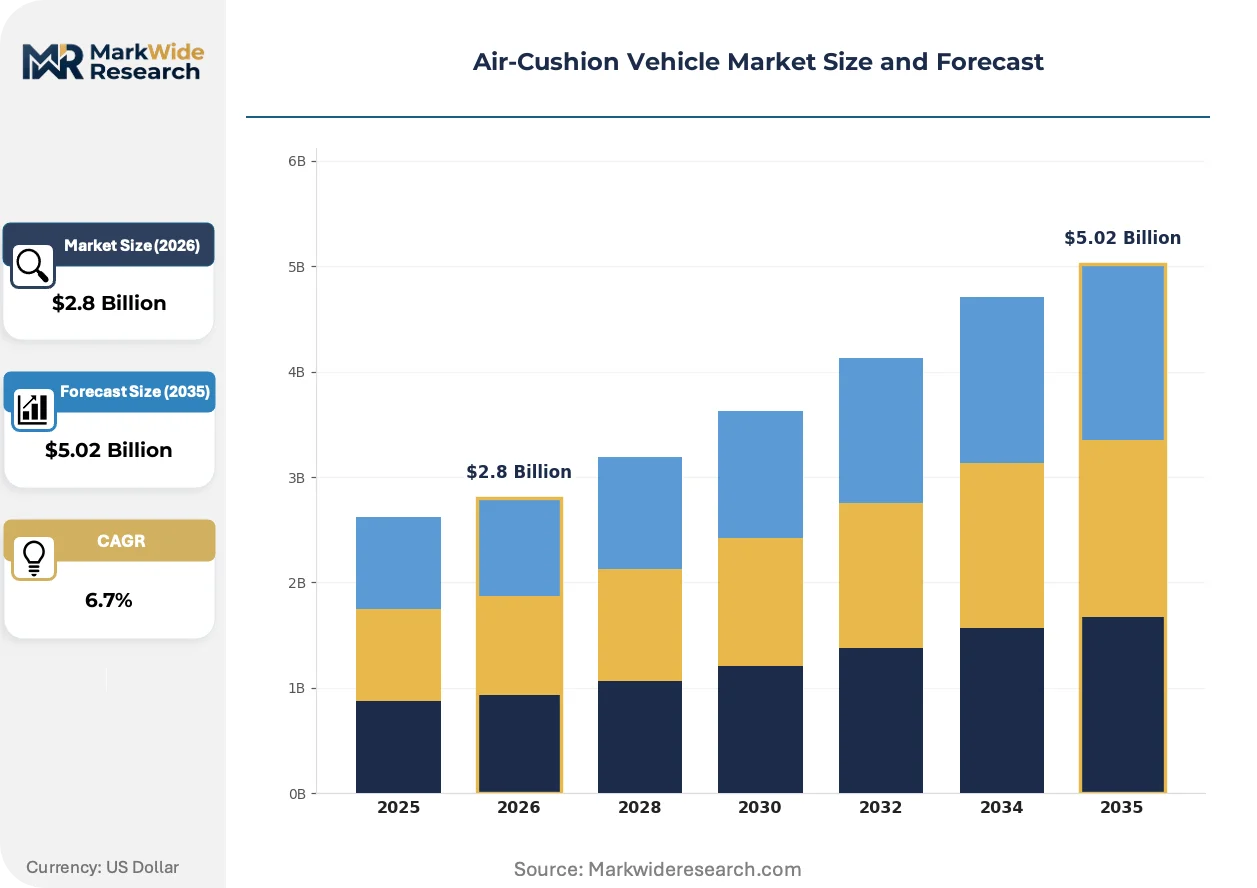
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hovercraft, Airboat, Air Cushion Truck, Air-Cushion Surface Application: Military Operations, Search and Rescue, Transport, Recreational Use End User: Defense, Commercial Transport, Tourism, Emergency Services Technology: Electric Propulsion, Gas Turbine, Hybrid Systems, Passive Systems |
| Companies Covered | Aerohod, Christy Hovercraft, Griffon Hoverwork, The British Hovercraft Company, China Hovercraft Ltd, Neoteric Hovercraft, ALMAZ, Hovertechnics, Textron Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Cushion Vehicle Market Strategic Shifts
Propulsion electrification and autonomous control systems are reconfiguring craft architecture, while regulatory pressure on marine emissions compresses development cycles for cleaner alternatives.
Electric propulsion technology is integrating into search and rescue configurations where operational profiles favor short mission durations and noise-sensitive environments. Coast guard and emergency response agencies in noise-regulated harbors are specifying battery-electric lift and propulsion systems. This shift is compressing the addressable market for pure diesel configurations while expanding the supplier base to include automotive battery integrators.
The EU Green Deal emissions framework is tightening marine exhaust standards for commercial vessels operating in European territorial waters. Manufacturers must now certify hovercraft against nitrogen oxide and particulate thresholds previously applied only to conventional shipping. Commercial operators in the North Sea and Mediterranean are responding by accelerating hybrid procurement timelines and retiring legacy gas turbine fleets ahead of schedule.
Defense procurement patterns are consolidating around multi-mission platform requirements that specify modular payload bays and interchangeable mission systems. Beach assault craft must now accommodate unmanned surface vehicle launch, medical evacuation, and command post configurations without hull modification. This flexibility mandate is most visible in NATO-aligned naval programs, where standardization across national fleets reduces through-life support costs.
Air-Cushion Vehicle Market Segmentation
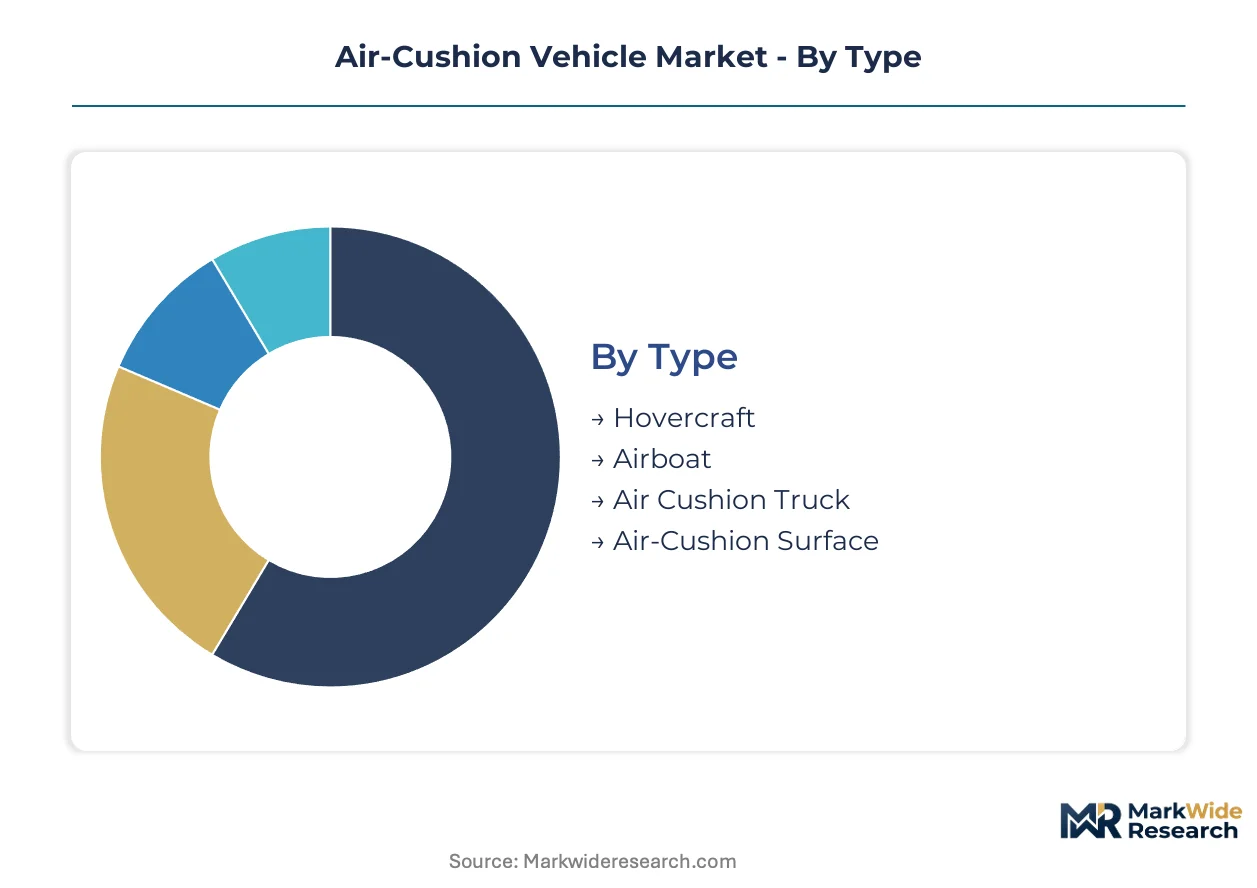
Air-cushion vehicle procurement splits across fundamentally different certification pathways. Naval buyers demand ITAR-compliant military qualification, while commercial operators navigate ISO 12217 stability mandates and EU Green Deal emissions frameworks.
Type:
Certification burden varies sharply by hull architecture. Hovercraft face dual ISO and military qualification tracks. Airboats operate under lighter recreational craft standards. Surface-effect ships encounter novel regulatory territory with limited precedent.
- Hovercraft:Pressurized air containment through flexible skirts enables water-ice-mud traversal without hull contact. Lift fans generate 500-2,500 pascal pressures. Beach assault procurement in coastal China and the Korean peninsula concentrates demand for military logistics roles.
- Airboat:Flat-bottomed hulls with aircraft-style propellers suit shallow-water and marsh environments. Recreational and emergency services applications dominate. Noise regulations in harbors are accelerating electric conversion timelines.
- Air Cushion Truck:Ground-effect cargo platforms for unpaved terrain access. Mining and remote logistics applications in permafrost regions drive niche procurement.
- Air-Cushion Surface:Stationary or slow-moving platforms for material handling and industrial transfer. Port container terminals and heavy manufacturing facilities specify these for load distribution.
Leading the category by volume: Hovercraft. Growing fastest: Airboat.
Application:
End-use concentration determines margin structure. Military programs absorb development costs across multi-decade fleet cycles. Commercial search and rescue contracts prioritize operational availability over unit economics.
- Military Operations:Beach assault and logistics roles where conventional landing craft face access constraints. NATO-aligned naval programs specify modular payload bays for unmanned surface vehicle launch and medical evacuation reconfiguration.
- Search and Rescue:Noise-sensitive harbor operations and ice-capable polar missions. Battery-electric configurations gain traction where fuel logistics simplicity outweighs range limitations.
- Transport:Island-mainland freight corridors and intermodal integration. Underpenetrated commercial routes between archipelagos offer volume expansion potential.
- Recreational Use:Leisure cruising and eco-tourism in wetland and coastal preserves. Environmental permitting complexity constrains fleet scaling.
Dominating procurement volume: Military Operations. Expanding most quickly: Search and Rescue.
End User:
Buyer sophistication tiers separate qualification requirements. Defense customers mandate backward compatibility with existing amphibious assault command structures. Commercial operators respond to emissions compliance deadlines.
- Defense:Naval Sea Systems Command and UK Defence Equipment and Support directorate govern military qualification. ITAR and export control regimes filter technology transfer and fragment supplier networks.
- Commercial Transport:EU Green Deal nitrogen oxide and particulate thresholds now apply to hovercraft in European territorial waters. North Sea and Mediterranean operators accelerate hybrid procurement timelines.
- Tourism:Harbor authorities and environmental regulators impose noise and wake restrictions. Seasonal demand patterns complicate fleet utilization economics.
- Emergency Services:Coast guard agencies specify battery-electric systems for noise-regulated harbors. Short mission profiles favor electric lift and propulsion architectures.
Commanding the largest share: Defense. Climbing the fastest: Emergency Services.
Technology:
Propulsion architecture locks manufacturers into decade-long supply chain commitments. Gas turbine economics face decarbonization headwinds. Battery energy density ceilings constrain pure-electric configurations to rescue missions.
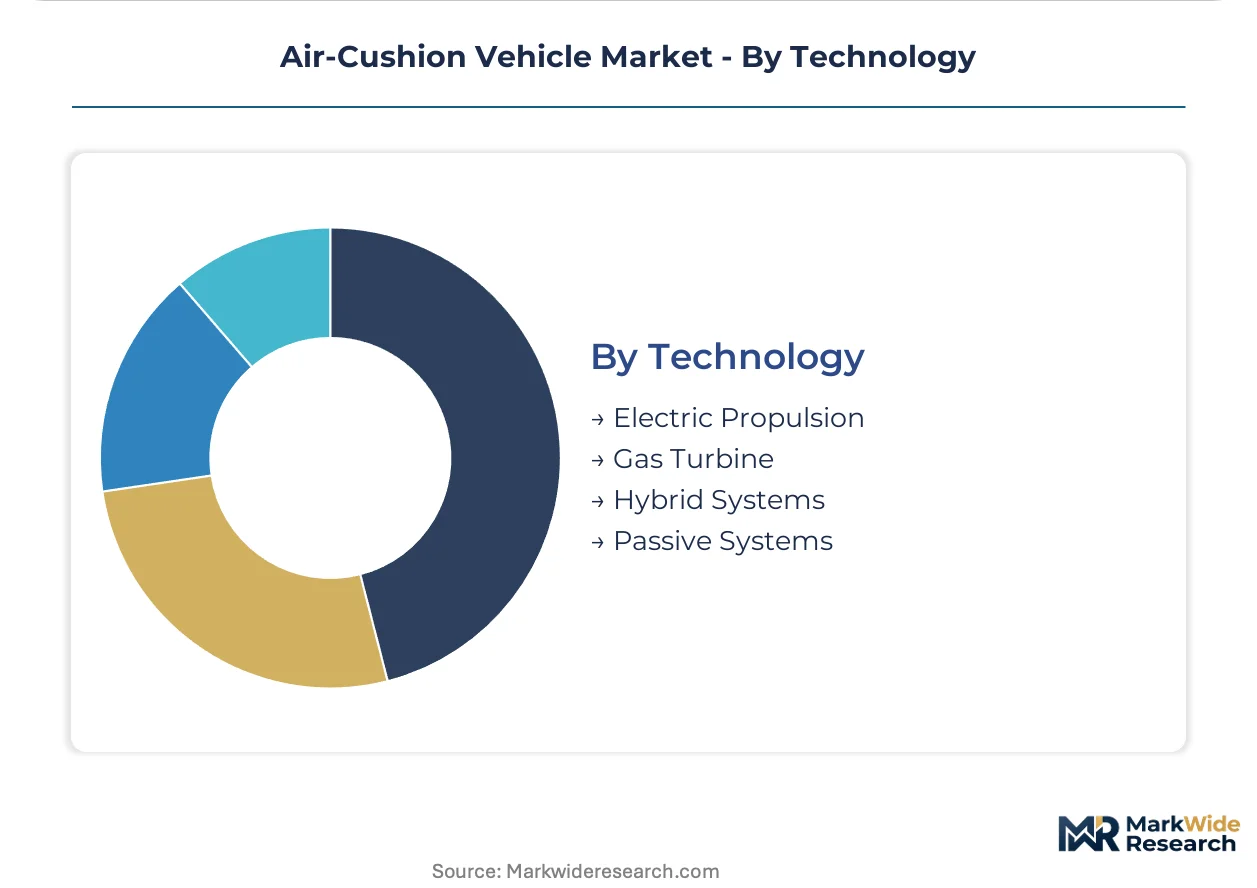
- Electric Propulsion:Battery-driven lift and propulsion systems. Search and rescue configurations in noise-regulated harbors specify these for operational simplicity.
- Gas Turbine:Conventional powerplants delivering endurance for extended military logistics missions. Stranded asset risk mounts on existing engine supply chains.
- Hybrid Systems:Turbine-electric combinations enabling endurance with electric stealth modes. NATO defense contracts increasingly specify this architecture for margin expansion.
- Passive Systems:Unpowered ground-effect platforms relying on forward motion for lift generation. Limited to specialized industrial material handling applications.
Highest volume deployment: Gas Turbine. Steepest expansion trajectory: Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skirt material feedstock availability in Eastern Europe has shifted procurement patterns toward Asian elastomer suppliers. Defense modernization programs and emissions compliance deadlines are redrawing manufacturing footprints across littoral economies.
China
Naval modernization drives beach assault craft procurement volumes along coastal provinces. MIIT issues GB standards for domestic hovercraft construction while SAMR enforces civilian safety compliance. State-backed production scale concentrates in Shanghai and Guangzhou shipyard clusters.
United States
Naval Sea Systems Command governs military qualification pathways for amphibious logistics platforms. ITAR export controls filter technology transfer to allied navies. Defense contracting networks cluster around Virginia and Mississippi Gulf Coast facilities.
United Kingdom
Defence Equipment and Support directorate oversees military craft qualification for NATO littoral operations. EU Green Deal emissions frameworks apply to commercial hovercraft in territorial waters. Griffon Hoverwork maintains specialized military production on the Solent.
South Korea
Peninsula defense procurement concentrates orders for amphibious landing craft in coastal shipyards. MFDS-aligned safety standards govern civilian rescue configurations. Busan-Ulsan industrial corridor hosts composite hull fabrication for regional export.
Germany
EU Green Deal nitrogen oxide thresholds accelerate hybrid propulsion development for North Sea operators. KBA-type certification pathways influence commercial registration timelines. Northern shipyards adapt skirt manufacturing for Arctic-capable rescue specifications.
Air-Cushion Vehicle Market Competitive Environment
Global majors compete with regional champions across defense contracting networks and specialized littoral craft fabrication. Market structure tilts toward consolidated military procurement relationships with fragmented commercial rescue and transport segments. Three archetypes dominate: state-backed naval suppliers, European specialist fabricators, and diversified defense conglomerates. Capacity expansion in Asian shipyards and strategic partnerships for electric propulsion integration represent the dominant competitive vectors.
Within the state-backed tier, China Hovercraft Ltd anchors domestic procurement scale. European specialists exemplify adaptive positioning, with Griffon Hoverwork occupying a position in NATO-aligned military programs and The British Hovercraft Company representing craft-to-order fabrication for commercial rescue applications. Textron Systems sits within the diversified defense conglomerate archetype, leveraging cross-platform contracting relationships.
| Leading Market Players |
|---|
| Aerohod |
| Christy Hovercraft |
| Griffon Hoverwork |
| The British Hovercraft Company |
| China Hovercraft Ltd |
| Neoteric Hovercraft |
| ALMAZ |
| Hovertechnics |
| Textron Systems |
| Others |
Value Chain & Pricing Dynamics
Electric propulsion development in European waters is simultaneously compressing gas turbine margins and redistributing supplier power toward battery integrators and hybrid system architects. This technological pivot locks manufacturers into decade-long component commitments while fragmenting legacy engine supply chains.
Pricing Analysis
Warranty and through-life service bundling separates defense contracting premiums from unbundled commercial rescue configurations. Three-tier pricing structure across military-specification, commercial-certified, and recreational craft levels reflects ISO 12217 compliance burdens and ITAR qualification costs. Price differentiation centers on propulsion architecture grade and skirt material specification, with hybrid turbine-electric systems commanding premium positioning. Cost compression in pure gas turbine tiers is intensifying because EU Green Deal emissions deadlines accelerate fleet retirement timelines. Emergency services buyers exhibit highest price sensitivity due to municipal budget constraints, while naval procurement teams prioritize operational availability over unit economics.
Supply Chain Analysis
Domestic-content mandates in China's MIIT GB standards and South Korea's defense procurement protocols are reshaping sourcing toward Shanghai shipyard clusters and Busan-Ulsan fabrication corridors. Reinforced elastomer skirt materials draw from Chinese and South Korean petrochemical feedstock bases, with lift fan assemblies anchored in German and UK precision manufacturing. Single-source vulnerability concentrates in Ukrainian and Russian hull producers where operations have suspended. Distribution runs through naval contracting networks for military end-users and specialized marine distributors for commercial rescue operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure mounts as decarbonization mandates strand gas turbine investments and defense procurement cycles compress development timelines for sub-scale players.
For Market Incumbents: Extend hybrid propulsion certification pipelines to capture NATO defense contract specifications before qualification windows close. Deepen backward integration into skirt material production to offset petrochemical feedstock volatility and secure elastomer supply continuity against Eastern European disruption. Lock in multi-decade through-life support agreements with naval customers to create switching costs that emerging entrants cannot replicate. For New Entrants and Emerging Players: EU Green Deal nitrogen oxide thresholds in German and UK territorial waters open a window for battery-electric rescue craft specialists to penetrate harbor authority procurement. Target underpenetrated island-mainland freight corridors in Southeast Asian archipelagos where intermodal integration remains nascent. Pursue coast guard agency relationships as the most penetrable buyer archetype, leveraging operational simplicity messaging against incumbent complexity. For Investors and Strategic Acquirers: Exit pathways concentrate in defense conglomerate acquisition of specialized littoral fabricators with NATO qualification credentials. Long-term viability favors hybrid architecture patent holders and skirt material compound specialists with captive formulation expertise. Watch ITAR licensing velocity as the critical inflection signal—accelerated approvals indicate contracting pipeline expansion, while processing delays signal procurement budget compression.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Certification | EU Green Deal compliance unlocks NATO defense contract access for turbine-electric architectures. |
| Skirt Material Backward Integration | Captive elastomer production insulates margin pressure from petrochemical feedstock volatility. |
| Arctic-Capable Rescue Specification | Polar logistics route opening creates first-mover advantage in ice-capable hovercraft segments. |
| Coast Guard Agency Partnership | Emergency services procurement cycles offer faster revenue conversion than naval contracting timelines. |
| ISO 12217 Harmonization Alignment | Stability standard compliance reduces duplicate testing burdens across European territorial waters. |
Study Parameters
Independent corroboration across naval program officers, commercial fleet operators, and skirt material suppliers underwrites the qualitative findings on procurement pattern shifts. Primary interviews with defense contracting specialists, coast guard procurement managers, shipyard production engineers, and battery system integrators combined with secondary validation from NATO equipment disclosures, MIIT GB standard filings, and EU Green Deal regulatory texts. Bottom-up craft production estimates and top-down defense budget allocation analysis triangulate volume and value outputs.
Comparable-period anchoring to historical naval modernization cycles and emissions compliance deadlines structures the projection horizon across the analysis window. Segmentation modeling spans propulsion architecture type, hull certification pathway, end-use application, and regional procurement jurisdiction. CAGRs derive from contracted fleet replacement schedules and commercial operator retirement timelines. Forecast inputs incorporate battery energy density improvement curves and skirt material compound cost trajectories.
Caveats apply where defense budget reallocations or battery technology breakthroughs could materially shift the outlook. Forecasts reflect assumptions on procurement cycle continuity and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Yacht Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Tugboat Market