
 Europe Inland Waterways Vessel Market | 2026-2036
Europe Inland Waterways Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Inland Waterways Vessel Market Analysis
The Netherlands is fragmenting its inland vessel manufacturing base across multiple shipyard clusters along the Waal and Maas rivers. Damen Shipyards Group leverages its Gorinchem facilities to dominate hybrid propulsion R&D for European canal networks. Rhenus Group anchors its fleet strategy on the Rhine-Main-Danube corridor, sustaining one of the largest container barge operations between Rotterdam and Basel. Contargo GmbH & Co. KG competes through trimodal terminal integration, extending its control over last-mile feeder connections from inland ports.
Europe inland waterways vessels are self-propelled or towed craft purpose-built for operation on rivers, canals, and lakes, typically measuring 38 to 135 meters in length with cargo capacities ranging from 300 to 11,000 tonnes depending on waterway class. Their primary function is to move bulk commodities, containerized freight, and passengers through networks where road or rail infrastructure faces capacity or environmental constraints. Barges and tankers together occupy the mature core of the fleet, while hybrid propulsion systems represent the fastest-growing technology segment as operators confront fuel cost volatility and emission zone restrictions. Freight transport generates the dominant revenue pool, though tour boats and passenger services command higher per-vessel margins due to premium cabin fit-out and shorter replacement cycles.
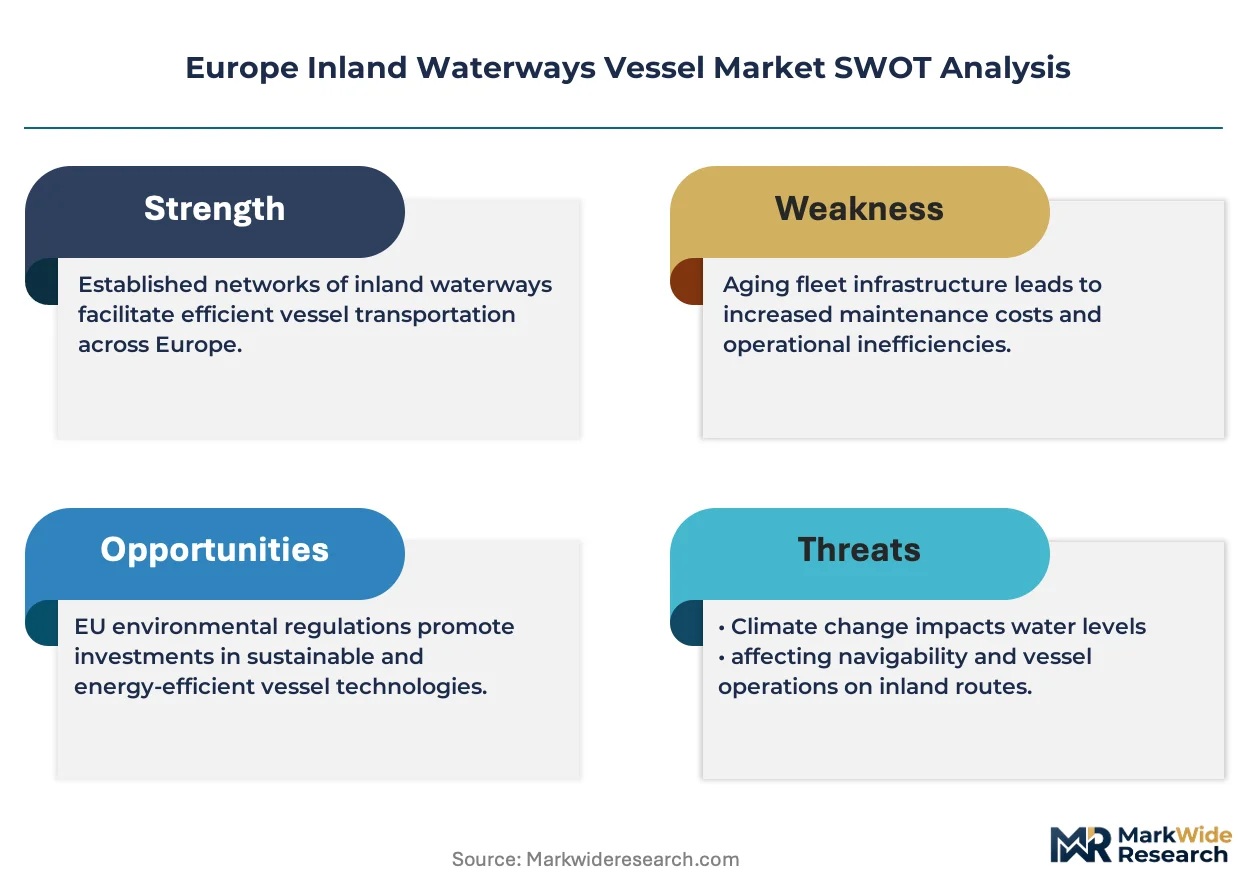
The European Maritime Safety Agency coordinates technical standards with national regulators such as Germany's Federal Maritime and Hydrographic Agency and France's Voies Navigables de France, ensuring unified certification for cross-border Rhine and Danube operations. The EU Green Deal and F-Gas Regulation together are forcing engine retrofits and accelerating scrappage of pre-Stage V diesel units, reshaping replacement demand curves. Stakeholders must monitor hydrogen bunkering infrastructure commitments at key ports and decide whether to lock in battery-electric designs or await fuel-cell commercialization before committing to newbuild programs.
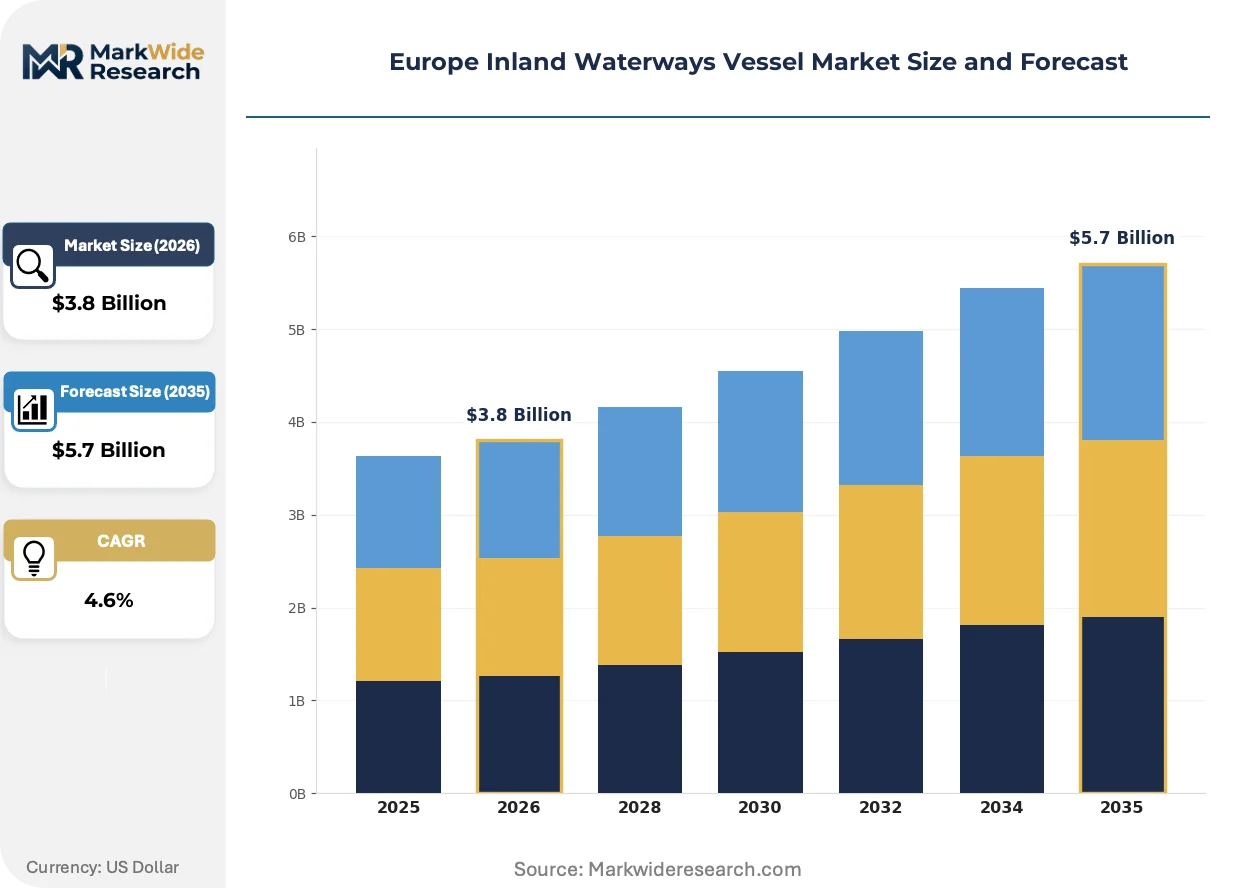
Market Dynamics
Stage V emission standards and the EU Green Deal's modal shift mandates are compressing replacement cycles for diesel-powered inland fleets while redirecting capital toward hydrogen and battery-electric newbuilds.
Growth Catalysts
- EU Green Deal modal shift policy:The framework mandates 25% freight transfer from road to water by 2030, expanding barge slot demand across Rhine-Danube corridors.
- Netherlands hydrogen bunkering infrastructure:Port of Rotterdam's H2 pilot terminals are creating anchor demand for fuel-cell vessel prototypes.
- Battery-electric propulsion systems:Lithium-ion pack energy density improvements are extending operational range for 110-meter container barges on medium-haul routes.
Market Restraints
- Steel plate and marine engine input volatility:Hull construction material costs swing with European energy pricing, squeezing shipyard margins on fixed-price contracts.
- Rhine-Main-Danube waterway level instability:Climate-induced low-water events reduce load factors and extend voyage times, degrading asset utilization.
- F-Gas Regulation retrofit timelines:Compressed compliance windows for refrigerant and auxiliary systems force premature capital deployment.
Strategic Opportunities
- Eastern European corridor expansion:Danube links through Romania and Bulgaria remain underdeveloped for containerized freight, offering greenfield terminal development.
- Hybrid-diesel methanol convergence:Dual-fuel engine architectures allow operators to hedge fuel price exposure while awaiting hydrogen supply maturity.
- Digital freight booking platforms:Real-time slot allocation systems are disintermediating traditional broker networks on Rotterdam-Antwerp shuttle routes.
Industry Challenges
- Marine electrical engineering skill scarcity:Shipyards lack sufficient technicians certified for high-voltage battery installation and fuel-cell stack maintenance.
- Stage V certification timeline compression:Type approval backlogs at Germany's Federal Maritime and Hydrographic Agency delay newbuild deliveries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Inland Waterways Vessel Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Barges, Tankers, Hopper Barges, Tugs Use Case: Freight Transport, Recreational Services, Passenger Transport, Tour Boats Technology: Hybrid Propulsion, Electric Drive, Conventional Diesel, Automation Systems End User: Shipping Companies, Tourism Operators, Government Agencies, Logistics Providers |
| Companies Covered | DFDS, Danser Group, Damen Shipyards Group, Port-Liner, European Cruise Service, Rhenus Group, Contargo GmbH & Co. KG, Compagnie Maritime Belge, CMA CGM Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Inland Waterways Vessel Market Emerging Trajectories
Propulsion architecture decisions now dominate vessel design cycles as operators weigh hydrogen against battery-electric pathways under tightening emission zone enforcement.
Hybrid propulsion systems are hybridizing the inland fleet by combining diesel prime movers with electric boost motors for lock transit and harbor maneuvering. Container operators on the Rotterdam-Basel corridor are retrofitting existing hulls with battery banks and shore-power interfaces to avoid urban emission penalties. This dual-mode capability is hybridizing asset deployment flexibility, allowing single vessels to switch between zero-emission port operations and extended range on liquid fuel.
The F-Gas Regulation is accelerating refrigerant system replacements across temperature-controlled cargo fleets, banning hydrofluorocarbon-based units from 2027. Reefer barge operators face simultaneous engine and cooling system retrofit obligations, concentrating compliance spending among mid-size fleet owners. Rhine-based logistics providers are responding by pooling certification resources through industry associations to defray testing costs.
Freight procurement is consolidating around long-term slot commitments as shippers seek volume certainty amid waterway capacity constraints. Chemical and container verticals are locking multi-year barge contracts directly with vessel operators, bypassing traditional freight forwarder intermediaries. This shift is most pronounced in Netherlands-Germany chemical corridor movements, where just-in-time delivery requirements favor dedicated fleet arrangements over spot market exposure.
Europe Inland Waterways Vessel Market Segmentation
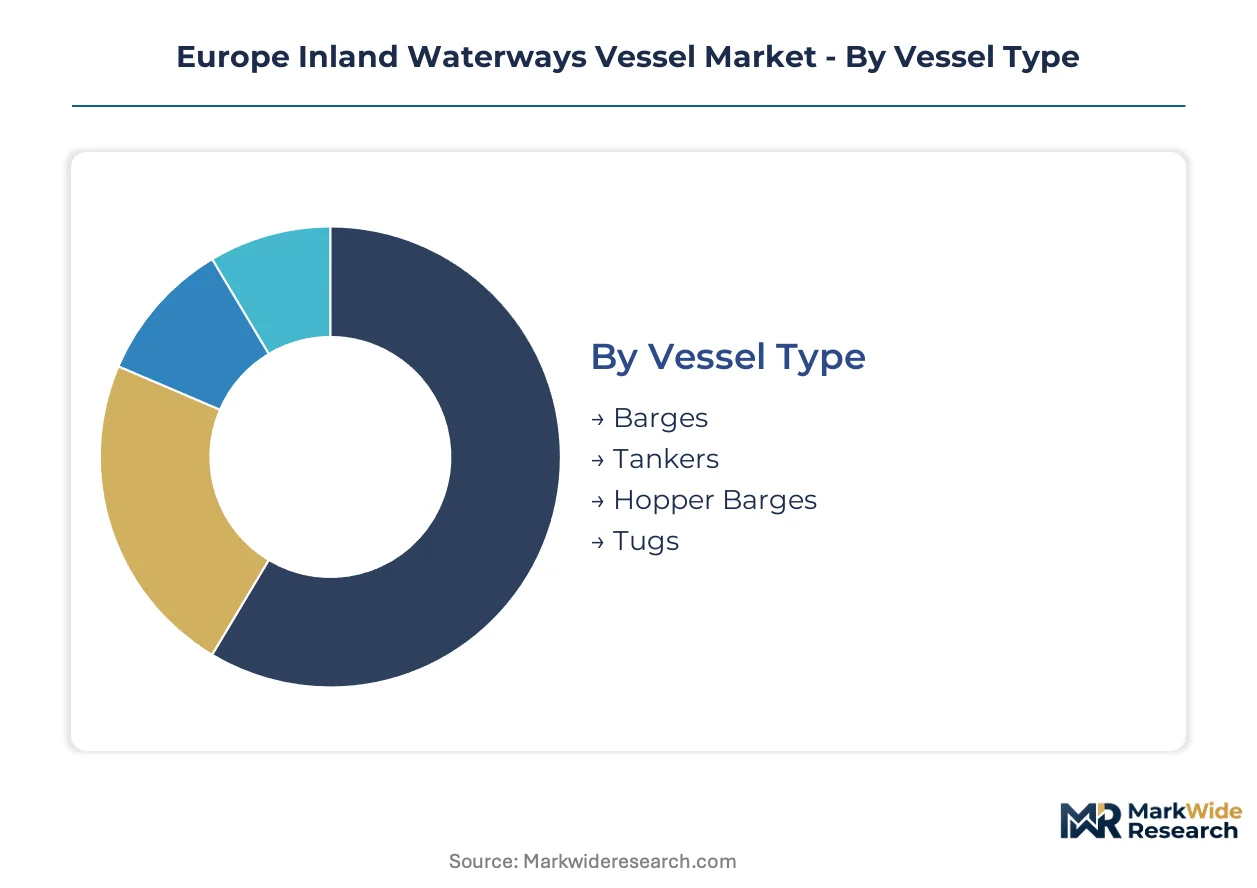
Vessel classification across Europe's inland waterways determines regulatory treatment, financing terms, and emission zone access. Operators must align fleet composition with corridor-specific cargo profiles and propulsion mandates.
Vessel Type:
Mature hull designs dominate tonnage volumes while specialized configurations address niche cargo demands.
- Barges:Flat-bottomed cargo carriers measuring 38 to 135 meters form the backbone of Rhine-Danube container and bulk movements. Dutch and German operators along the Rotterdam-Basel corridor are retrofitting existing hulls with battery-electric systems to meet Stage V harbor emission restrictions.
- Tankers:Double-hulled liquid cargo vessels transport chemicals, petroleum products, and edible oils through the Netherlands-Germany chemical corridor. The EU Green Deal's modal shift mandates are accelerating tanker newbuilds with methanol-ready engine architectures.
- Hopper Barges:Open-hold vessels designed for dredging spoil, aggregates, and bulk minerals serve construction and port maintenance fleets.
- Tugs:Maneuvering craft with high bollard pull ratings assist lock transits and harbor operations at Rotterdam, Antwerp, and Hamburg terminals.
Barges retain volume leadership; tankers hold the steepest expansion curve.
Use Case:
Revenue concentration tilts toward freight movements while passenger services command premium per-vessel margins.
- Freight Transport:Containerized cargo, bulk commodities, and liquid chemicals generate the dominant revenue pool across European inland networks. Chemical and container verticals are locking multi-year barge contracts directly with vessel operators, bypassing traditional freight forwarder intermediaries.
- Passenger Transport:Scheduled ferry services and water taxis operate on urban waterways in Berlin, Vienna, and Budapest. Battery-electric propulsion is displacing diesel on short-haul commuter routes where shore-power infrastructure exists.
- Recreational Services:Private charter and leisure cruising concentrate on French canals and Dutch lake districts.
- Tour Boats:Sightseeing vessels with premium cabin fit-out serve heritage routes on the Rhine and Danube, cycling through shorter replacement intervals than cargo fleets.
Freight transport anchors revenue scale; tour boats deliver the highest per-asset margins.
Technology:
Propulsion architecture decisions now determine vessel financing terms and operational zone eligibility.
- Hybrid Propulsion:Dual-mode systems combining diesel prime movers with electric boost motors enable zero-emission lock transits and harbor maneuvering. Container operators on the Rotterdam-Basel corridor are retrofitting existing hulls with battery banks and shore-power interfaces to avoid urban emission penalties.
- Electric Drive:Battery-electric systems with lithium-ion packs are extending operational range for 110-meter container barges on medium-haul routes. The Netherlands' hydrogen bunkering infrastructure at Port of Rotterdam is creating anchor demand for fuel-cell vessel prototypes.
- Conventional Diesel:Pre-Stage V diesel engines face accelerated scrappage under F-Gas Regulation and EU Green Deal timelines, compressing replacement demand curves.
- Automation Systems:Autonomous navigation and remote monitoring packages reduce crew requirements on repetitive shuttle routes.
Conventional diesel retains installed-base dominance; electric drive is climbing the fastest.
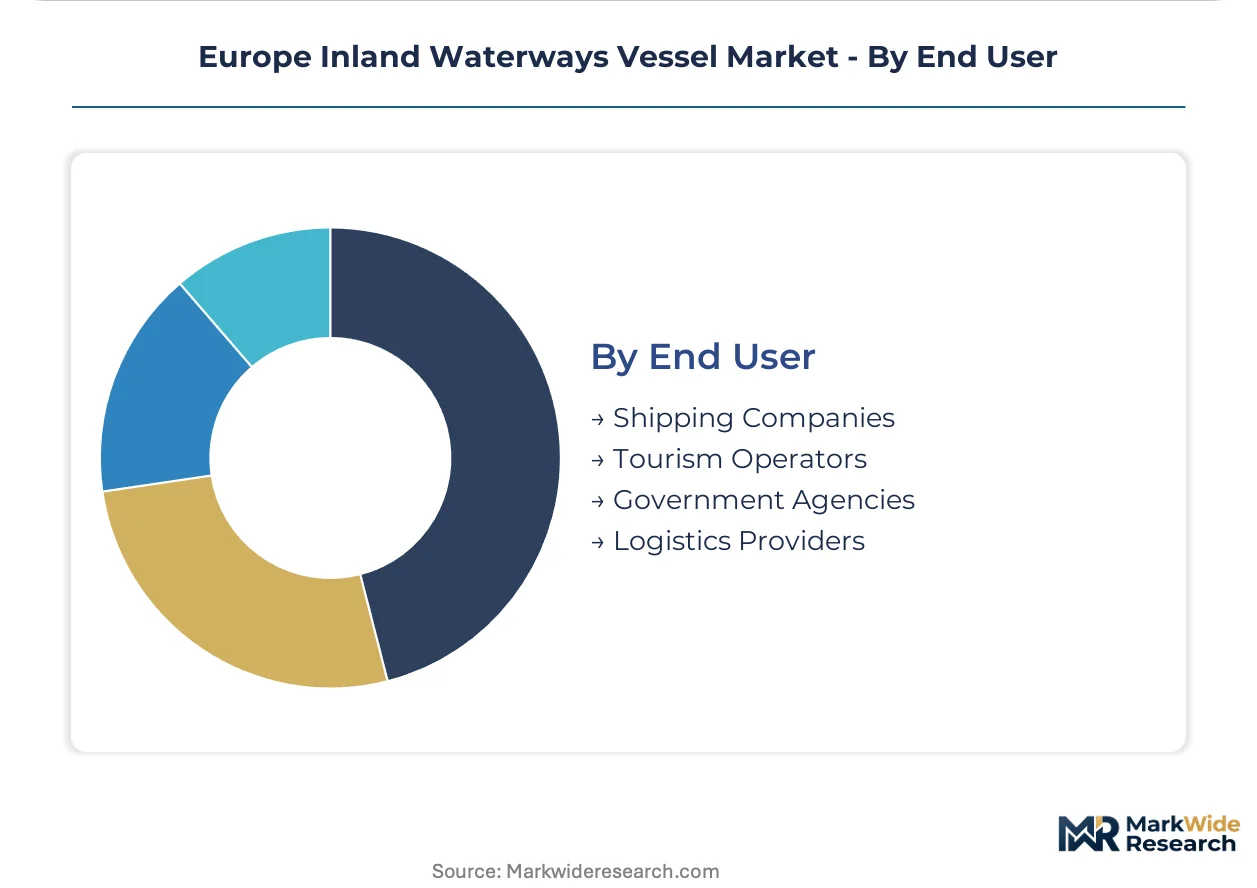
End User:
Procurement authority concentrates among integrated logistics groups and state-backed fleet operators.
- Shipping Companies:Container barge operators like Rhenus Group sustain fleet renewal programs across the Rhine-Main-Danube corridor, locking in hybrid propulsion designs.
- Logistics Providers:Trimodal terminal operators such as Contargo GmbH & Co. KG control last-mile feeder connections from inland ports, driving dedicated vessel specifications.
- Tourism Operators:Cruise and sightseeing companies commission premium-fit vessels with shorter depreciation schedules.
- Government Agencies:Waterway authorities and municipal transport departments procure patrol, maintenance, and ferry craft under public procurement frameworks.
Shipping companies command the largest order books; logistics providers are expanding fleet ownership fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors demand concentration in the Netherlands, where Rotterdam's hydrogen bunkering pilots and Stage V enforcement timelines are compressing vessel replacement cycles across Rhine corridor operations.
Netherlands
Rotterdam-Antwerp shuttle routes drive container barge demand as shippers lock multi-year slot commitments. The Port of Rotterdam Authority's H2 terminal investments are creating anchor demand for fuel-cell prototypes. Shipyard clusters along the Waal and Maas rivers, led by Damen Shipyards Group's Gorinchem facilities, dominate hybrid propulsion R&D for European canal networks.
Germany
Chemical corridor movements between Ludwigshafen and Antwerp sustain tanker fleet renewal as operators retrofit methanol-ready engine architectures. The Federal Maritime and Hydrographic Agency's Stage V certification backlogs are delaying newbuild deliveries. Industrial concentration in North Rhine-Westphalia and Lower Saxony supports Rhenus Group's Rhine-Main-Danube container operations between Rotterdam and Basel.
Belgium
Trimodal terminal integration at Antwerp and Ghent is driving dedicated vessel specifications for last-mile feeder connections. F-Gas Regulation refrigerant bans from 2027 are forcing simultaneous engine and cooling system retrofits among reefer barge operators. Compagnie Maritime Belge anchors fleet operations serving the Netherlands-Germany chemical corridor.
France
Voies Navigables de France coordinates technical standards with EU regulators for cross-border Rhine operations. Battery-electric propulsion is displacing diesel on short-haul commuter ferry routes in Paris and Lyon where shore-power infrastructure exists. Tour boat operators on French canals commission premium-fit vessels with shorter depreciation schedules than cargo fleets.
Romania
Danube links through the Port of Constanta remain underdeveloped for containerized freight, offering greenfield terminal development opportunities. Black Sea connectivity is attracting logistics providers seeking alternative routes to Central Europe. Bulgarian and Romanian waterway modernization programs are accelerating under EU cohesion funding frameworks.
Europe Inland Waterways Vessel Market Vendor Landscape
Capability concentration sits with specialized shipyards and integrated logistics groups; scale advantage sits with diversified maritime conglomerates. The vendor base organizes around three archetypes: hybrid propulsion technology developers, trimodal terminal operators controlling feeder networks, and diversified shipping groups with cross-modal asset portfolios. Competitive dynamics center on strategic partnerships for hydrogen bunkering infrastructure and vertical integration into terminal operations to secure cargo volume commitments.
Among Netherlands-based fabricators, Damen Shipyards Group occupies a position exemplifying specialized shipyard capability concentration, while Contargo GmbH & Co. KG represents the trimodal terminal operator archetype integrating last-mile feeder control. Rhenus Group anchors the diversified logistics tier with fleet ownership spanning the Rhine-Main-Danube corridor. These three entities collectively illustrate the competitive structure: technology-led shipbuilding, infrastructure-integrated logistics, and corridor-scale fleet operations.
| Leading Market Players |
|---|
| DFDS |
| Danser Group |
| Damen Shipyards Group |
| Port-Liner |
| European Cruise Service |
| Rhenus Group |
| Contargo GmbH & Co. KG |
| Compagnie Maritime Belge |
| CMA CGM Group |
| Others |
Supply Flow & Price Mechanics
Steel plate mills in Germany and the Netherlands concentrate hull construction input supply, anchoring margin pools with shipyards capable of locking long-term material contracts against energy price volatility. Dutch operators along the Waal river clusters leverage this proximity to stabilize newbuild pricing while Eastern European yards absorb spot market steel cost swings.
Pricing Analysis
Price spreads between Rotterdam-based operators and Danube corridor yards reflect a 15-20% delivery premium tied to Stage V certification proximity and hydrogen bunkering infrastructure access. Three-tier pricing structure across premium hybrid propulsion, standard diesel-electric, and economy pre-Stage V retrofit tiers segments the fleet replacement market. Cost compression in standard-tier newbuilds is intensifying because lithium-ion pack integration complexity outpaces technician availability. Chemical shippers locking multi-year slot commitments show least price sensitivity; spot-market bulk operators face acute margin pressure.
Supply Chain Analysis
EU dual-use export controls on high-voltage marine battery management systems limit technology flows from South Korean and Japanese suppliers into European shipyard integration facilities. Hull steel draws from German and Dutch mills; lithium-ion cells rest on South Korean and Chinese cathode supply; fuel-cell stacks hinge on German and Danish electrolyzer output. Single-source vulnerability concentrates in marine electrical engineering certification capacity at Germany's Federal Maritime and Hydrographic Agency. Distribution runs through integrated logistics groups controlling trimodal terminal networks rather than independent vessel brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine electrical engineering skill scarcity constrains fleet renewal velocity, with high-voltage battery installation and fuel-cell stack maintenance certification gaps limiting shipyard throughput regardless of capital availability.
For Market Incumbents: Build certification moats by capturing scarce technician training capacity at German and Dutch maritime academies before competitors lock cohort placement. Secure backward integration into hydrogen bunkering infrastructure at Rotterdam and Antwerp terminals to anchor cargo volume commitments against emerging logistics providers. Stage V compliance timeline compression at Germany's Federal Maritime and Hydrographic Agency threatens delivery schedules; early certification filing reserves production slots. For New Entrants and Emerging Players: Romanian and Bulgarian Danube corridor container terminal development offers the most penetrable geographic entry point, with EU cohesion funding accelerating waterway modernization and Black Sea connectivity creating alternative Central Europe routing. Target underdeveloped reefer barge fleets facing simultaneous F-Gas Regulation refrigerant bans and engine retrofit obligations, where pooled compliance resources create partnership entry angles. Lead with digital freight booking platforms disintermediating traditional broker networks on established Rotterdam-Antwerp shuttle routes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-size Dutch and German fleet operators backed by infrastructure-focused private equity, where holding periods approach exit windows and hydrogen pilot project valuations remain unmarked to commercial scale. Long-term viability hinges on 5-10 year hydrogen supply chain maturation rather than near-term fuel-cell vessel economics. Watch Port of Rotterdam H2 terminal utilization rates as the inflection signal separating prototype demand from commercial fleet commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Bunkering Infrastructure Partnership | Port of Rotterdam H2 terminal access locks cargo volume commitments for fuel-cell vessel operators. |
| Marine Electrical Engineering Training Investment | German and Dutch academy cohort placement secures scarce high-voltage battery installation capacity. |
| Danube Corridor Terminal Development | Romanian and Bulgarian greenfield sites capture EU cohesion funding for containerized freight expansion. |
| Digital Freight Platform Launch | Real-time slot allocation systems disintermediate traditional broker networks on Rotterdam-Antwerp routes. |
| Hybrid Propulsion Retrofit Program | Battery-electric harbor operation capability avoids urban emission penalties under Stage V enforcement. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with shipyard operations directors, fleet managers at integrated logistics groups, port authority infrastructure planners, and marine electrical engineering training providers; and secondary validation against EU customs trade data, Rhine navigation authority vessel registration databases, SEC filings of listed shipping groups, and Port of Rotterdam hydrogen infrastructure investment disclosures. Bottom-up vessel order book aggregation triangulated against top-down corridor freight volume estimates.
Forecast inputs considered propulsion technology adoption curves, Stage V and F-Gas Regulation compliance timeline impacts, and hydrogen bunkering infrastructure deployment schedules across the analysis window. Segmentation dimensions modeled include vessel type, propulsion architecture, cargo category, and corridor-specific regulatory cluster. CAGRs derived from logistic curve fitting to technology substitution patterns and policy mandate enforcement trajectories. Rhine-Main-Danube waterway level volatility and steel plate input cost cycles fed scenario-weighted outputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed fleet operators or hydrogen infrastructure consortia would shift outcomes beyond modeled ranges. Material shifts in EU Green Deal modal shift mandate enforcement intensity or hydrogen supply chain commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Yacht Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
Sea-Based Vehicle Carrier Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Fishing Boat Market