
 Marine Outboard Engine Market | 2026-2036
Marine Outboard Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Outboard Engine Market Outlook
Japanese outboard manufacturers is broadening production flexibility across multiple displacement classes. Yamaha Motor Co leverages its integrated marine division to sustain global distribution density. Brunswick Corporation anchors North American market presence through Mercury Marine's specialized high-performance portfolio. Honda Motor Co competes in the premium four-stroke niche with fuel-injection technology leadership.
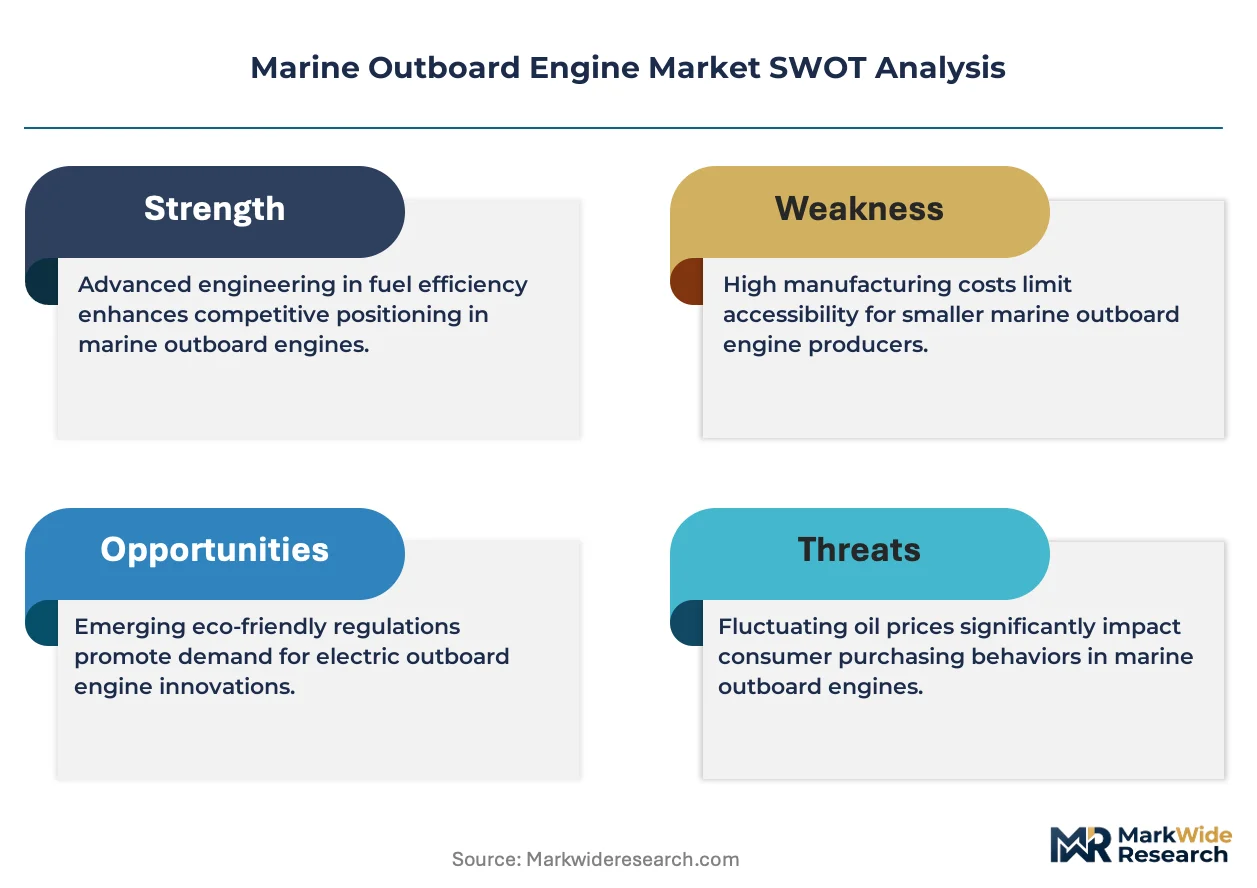
A marine outboard engine is a self-contained propulsion unit mounted on a boat's transom, typically comprising a powerhead, midsection, and gearcase with propeller, designed to convert internal combustion or electric energy into thrust for watercraft propulsion. The four-stroke gasoline configuration dominates commercial and recreational applications due to superior fuel efficiency and reduced hydrocarbon emissions versus two-stroke alternatives. Electric outboard systems represent the fastest-growing product type as lithium-ion battery energy density improves and harbor authorities restrict internal combustion operation in sensitive waterways. The 10-50 HP power rating band captures the largest margin pool, serving the dense recreational boating and light commercial fishing fleet replacement cycles across temperate coastal zones.
EPA non-road emissions regulations and EU Stage V standards constrain two-stroke engine certification pathways while accelerating four-stroke and electric platform development. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces domestic marine engine efficiency benchmarks that influence export specifications. Stakeholders must monitor battery supply chain localization requirements and charging infrastructure commitments in key boating geographies to anticipate platform transition timing.
Market Dynamics
Propulsion electrification is compressing traditional four-stroke replacement cycles as harbor authorities in Florida, California, and Norway impose combustion restrictions in sensitive waterways. This shift is restructuring manufacturer R&D allocation and dealer network capabilities simultaneously.
Growth Catalysts
- EPA Tier 3 and EU Stage V emissions standards:These regulations are eliminating two-stroke certification pathways and forcing fleet operators toward four-stroke and electric alternatives.
- Recreational boating density in coastal Florida:Aging fleet replacement demand concentrates in the 10-50 HP band where fuel efficiency premiums justify upgrade costs.
- Lithium-ion energy density improvements:Battery pack weight reductions are extending electric outboard range thresholds into commercially viable territory for light commercial fishing.
Market Restraints
- Neodymium and lithium supply concentration:Electric powertrain dependency on Chinese-processed rare earth elements creates input cost volatility and geopolitical exposure.
- Four-stroke powerhead manufacturing consolidation:Production of critical castings and precision-machined components clusters in Japanese and Thai supplier networks.
- Harbor charging infrastructure gaps:Marina electrical capacity limitations in Mediterranean ports constrain electric adoption despite regulatory pressure.
Strategic Opportunities
- Norwegian fjord tourism electrification mandates:The country's Ministry of Climate and Environment zero-emission requirements in World Heritage waterways create captive demand for electric propulsion.
- Leasing and power-by-the-hour models:Commercial fishing cooperatives in Japan are adopting usage-based contracts that shift capital burden from vessel owners to manufacturers.
- Integration of solar charging with dockside storage:Photovoltaic canopy installations at Mediterranean marinas are converging with battery-swapping services to eliminate range anxiety.
Industry Challenges
- Marine electrician certification scarcity:High-voltage system installation and maintenance skills lag electric outboard deployment rates in US coastal markets.
- Dual certification timeline compression:Manufacturers must secure EPA, EU Stage V, and Japan MLIT approvals simultaneously for product launches.
- Legacy two-stroke service network obsolescence:Dealer technical training and parts inventory systems require capital-intensive reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Outboard Engine Market |
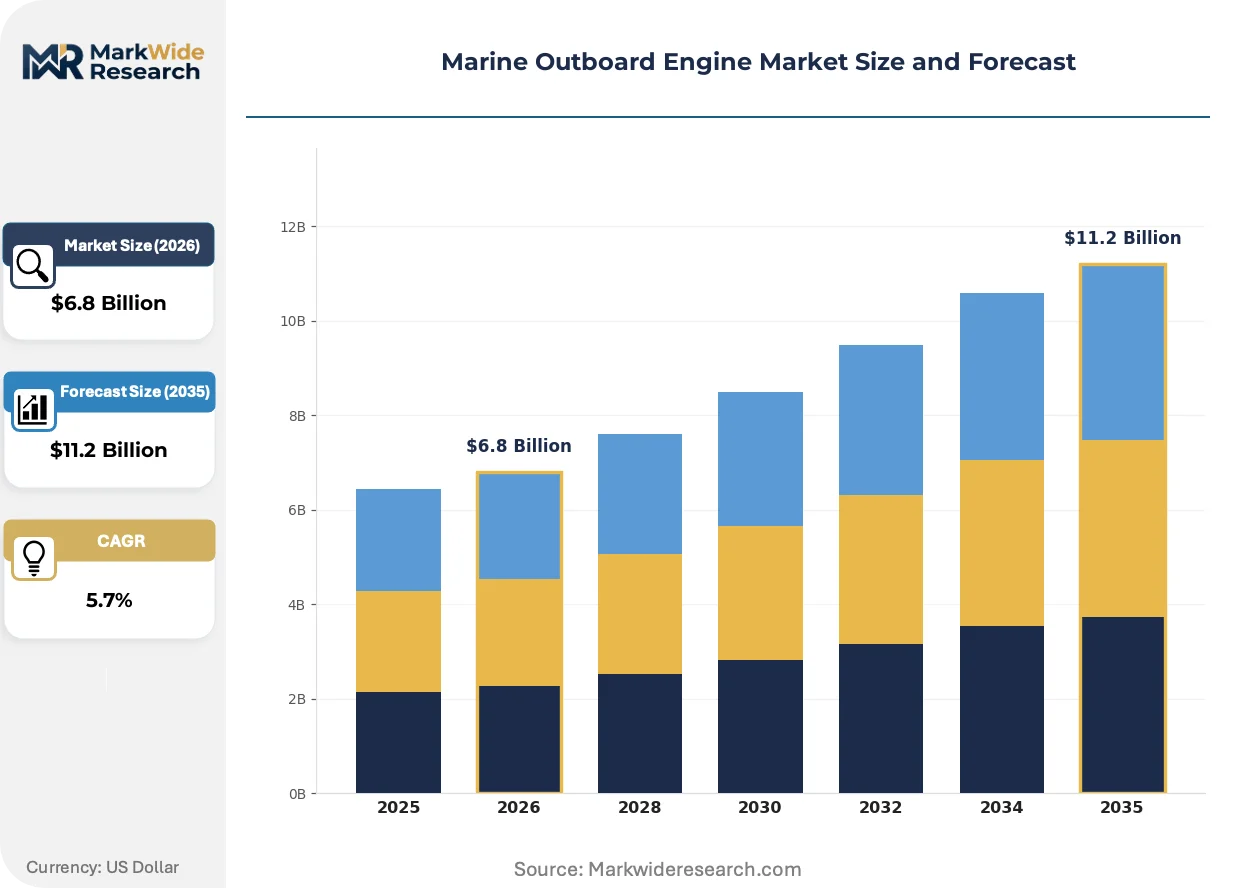
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Stroke, Four-Stroke, Electric, Hybrid End User: Recreational Boating, Commercial Fishing, Water Sports, Government Agencies Power Rating: Under 10 HP, 10-50 HP, 51-100 HP, Above 100 HP Fuel Type: Gasoline, Diesel, Propane, Others |
| Companies Covered | Yamaha Motor Co, Brunswick Corporation, Honda Motor Co, Suzuki Motor Corporation, Mercury Marine, Tohatsu Corporation, Kawasaki Heavy Industries, Nissan Marine, Cox Powertrain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Outboard Engine Market Strategic Shifts
Digitalization of propulsion control systems is merging with battery management intelligence to create integrated vessel energy platforms. This convergence is redefining competitive differentiation beyond horsepower ratings toward total cost of ownership optimization.
Brushless permanent magnet motors paired with silicon carbide inverters are converging with vessel-wide energy management systems. Recreational boaters in Norway and commercial operators in Japan are adopting these configurations at accelerating rates. The technology is converging with autonomous docking assistance to create integrated mobility platforms that compress the traditional engine-plus-controls procurement model.
EU Stage V non-road spark-ignition standards are tightening hydrocarbon and particulate limits beyond two-stroke technical feasibility. Engine manufacturers are redirecting R&D spend toward electric platform development and four-stroke combustion refinement. The 10-50 HP segment serving Mediterranean charter fleets faces the most acute compliance pressure, with Italian and Greek operators accelerating fleet turnover.
Buyer preference is migrating from discrete engine purchases toward integrated propulsion-service bundles. Charter operators in Florida are contracting directly with manufacturers for maintenance-inclusive agreements that displace traditional dealer service departments. This pattern is most visible in high-utilization commercial segments where downtime costs exceed premium pricing for guaranteed availability.
Marine Outboard Engine Market Segmentation
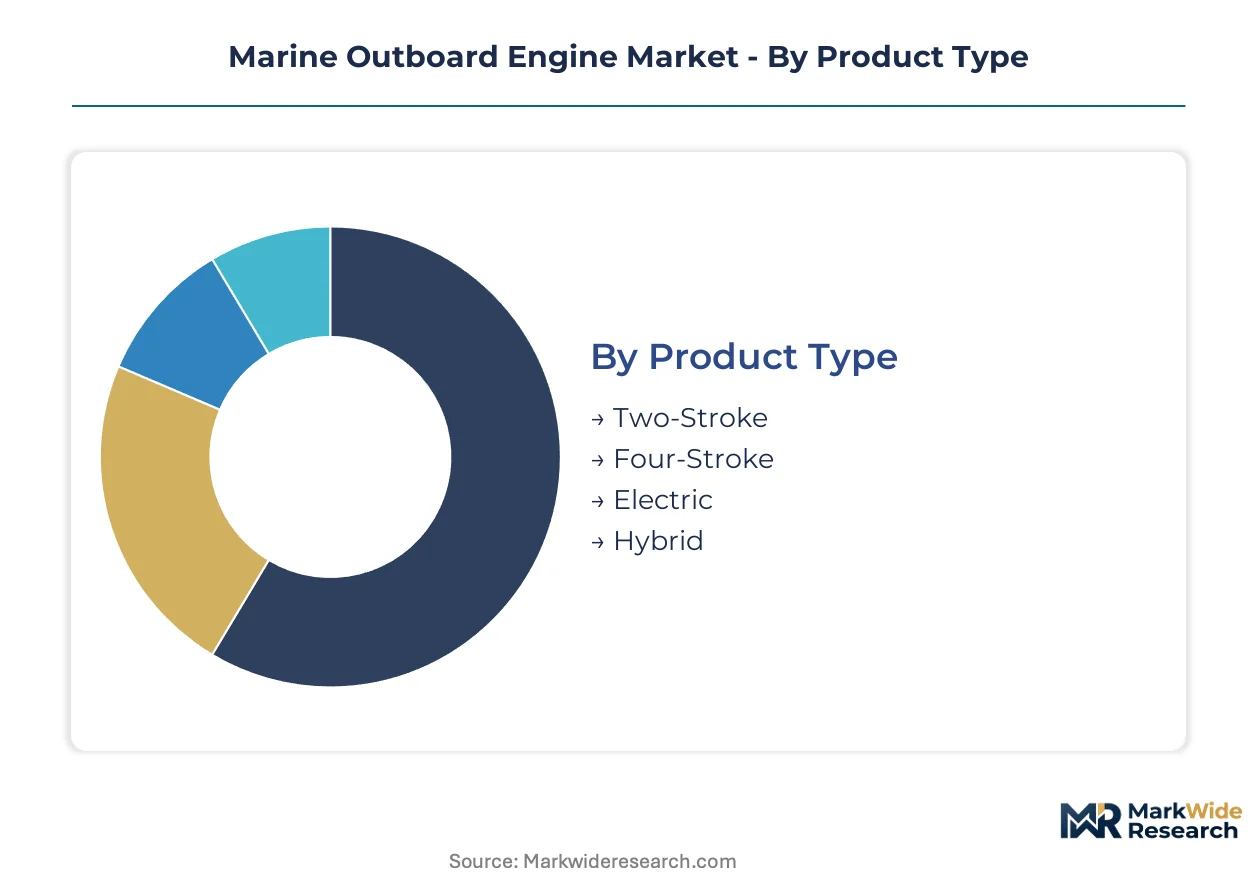
Segmentation in marine outboard engines reveals how certification burdens, power requirements, and end-use intensity create divergent margin structures. Manufacturers configure platform architectures around EPA Tier 3, EU Stage V, and Japan MLIT approval pathways that segment customers by operational profile and regulatory exposure.
Product Type:
EPA Tier 3 and EU Stage V certification requirements fall unevenly across propulsion architectures, with two-stroke platforms facing elimination while electric systems navigate battery safety standards.
- Four-Stroke:Dominant gasoline configuration employs overhead valve architecture with direct fuel injection. Coastal Florida recreational fleets and Mediterranean charter operators concentrate replacement demand here as harbor authorities restrict older two-stroke operation. EPA Tier 3 compliance costs are absorbed through manufacturing scale advantages in this segment.
- Electric:Brushless permanent magnet motors paired with lithium-ion battery packs deliver zero-emission operation. Norwegian fjord tourism mandates and California harbor combustion bans are accelerating commercial viability in light commercial fishing applications. Battery energy density improvements are extending range thresholds into practical territory.
- Two-Stroke:Loop-charged carbureted designs face regulatory phase-out. Remaining demand concentrates in price-sensitive emerging markets where EPA and EU certifications are not enforced.
- Hybrid:Combustion-electric architectures with onboard generation for extended range. Japanese commercial fishing cooperatives are piloting these systems for diesel-electric operation in coastal waters.
Four-Stroke sits at the top of the volume ranking, with Electric climbing the fastest.
End User:
Customer procurement patterns split between capital-constrained individual owners and fleet operators with usage-based contracting capabilities.
- Recreational Boating:Individual owners and family operators in coastal Florida and Mediterranean leisure markets. Replacement cycles concentrate in the 10-50 HP band where fuel efficiency premiums justify upgrade costs against aging two-stroke fleets.
- Commercial Fishing:High-utilization operators in Japan and Norway with downtime-sensitive revenue models. Leasing and power-by-the-hour contracts are shifting capital burden from vessel owners to manufacturers in this segment.
- Water Sports:Towboat operators and ski schools requiring high-torque low-speed performance. Demand clusters around specialized propeller configurations for wake generation.
- Government Agencies:Patrol and rescue fleets with multi-hundred-hour annual utilization. Procurement runs through centralized tender processes with maintenance-inclusive contracting.
Recreational Boating commands the largest revenue pool, though Commercial Fishing exhibits the steepest expansion trajectory in electric platform adoption.
Power Rating:
Manufacturing tooling and component sourcing economies concentrate around specific displacement classes, with 10-50 HP capturing the densest supplier network.
- 10-50 HP:Single and twin-cylinder four-stroke architectures serving the densest replacement demand. Mediterranean charter fleets and Florida recreational boaters drive volume here, with Italian and Greek operators accelerating fleet turnover under EU Stage V pressure.
- Under 10 HP:Portable outboards for small craft and auxiliary power. Price sensitivity dominates procurement decisions in this segment.
- 51-100 HP:Inline four-cylinder configurations for larger recreational vessels and light commercial applications. Manufacturing consolidation in Japanese and Thai casting networks constrains supply flexibility.
- Above 100 HP:V6 and V8 architectures for high-performance recreational and commercial patrol applications. Low-volume specialization with premium pricing structures.
10-50 HP holds the dominant position in unit volume, with Above 100 HP gaining share fastest in the premium performance tier.
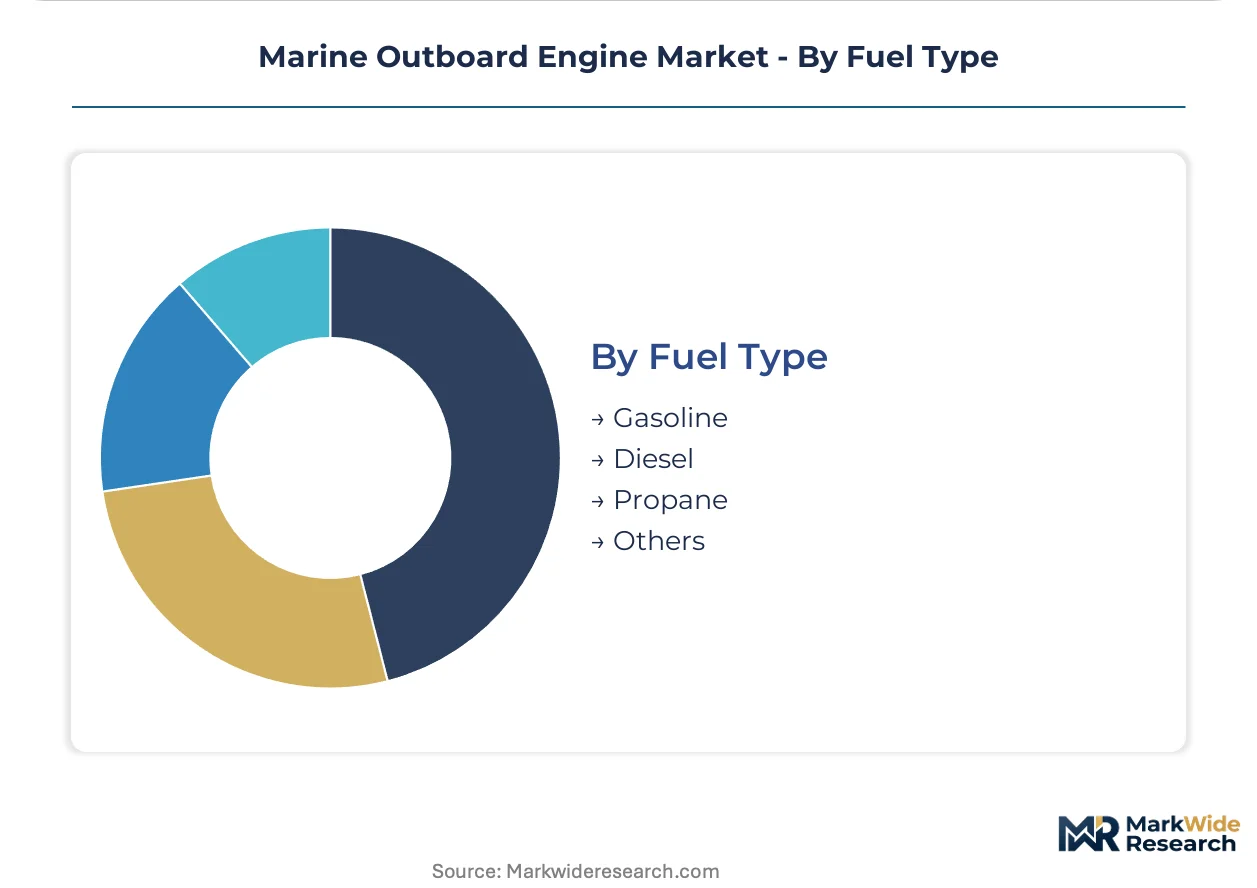
Fuel Type:
Energy density requirements and infrastructure availability shape fuel selection across operating environments, with harbor restrictions increasingly constraining gasoline alternatives.
- Gasoline:Dominates four-stroke and two-stroke platforms with established marina distribution networks. EPA and EU hydrocarbon limits are forcing injection technology upgrades in this category.
- Diesel:Compression-ignition architectures for commercial fishing and government patrol requiring high torque and fuel availability in remote ports. Japanese coastal operators maintain strong preference here.
- Propane:LPG conversions for reduced emissions in inland waterways. Limited infrastructure constrains adoption outside specific geographic clusters.
- Others:Compressed natural gas and hydrogen pilot programs. Experimental deployments in Norwegian and Japanese demonstration fleets.
Gasoline retains the highest shipment volumes, with Diesel expanding most quickly in commercial segments requiring operational range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing manufacturing investment toward jurisdictions with streamlined certification reciprocity. Japanese and Thai production networks absorb capacity from higher-compliance-cost environments.
United States
Coastal Florida's recreational boating density drives replacement demand in the 10-50 HP band. EPA Tier 3 emissions standards eliminate two-stroke certification pathways for domestic manufacturers. Miami-Dade and Fort Lauderdale marine service clusters are retrofitting dealer networks for electric platform support.
Japan
Commercial fishing cooperatives in coastal prefectures are piloting power-by-the-hour leasing contracts. The Ministry of Land, Infrastructure, Transport and Tourism enforces marine engine efficiency benchmarks that shape export specifications. Nagoya and Hamamatsu industrial corridors concentrate precision casting and fuel-injection component production.
Norway
Fjord tourism operators face zero-emission mandates in World Heritage waterways from the Ministry of Climate and Environment. Electric outboard adoption accelerates among light commercial fishing fleets. Bergen and Tromsø harbor authorities are expanding dockside charging infrastructure with battery-swapping services.
Italy
Mediterranean charter fleets in Liguria and Campania accelerate four-stroke turnover under EU Stage V hydrocarbon limits. Italian operators absorb premium pricing for compliant engines to maintain harbor access. Genoa marine engineering clusters specialize in integrated vessel energy management systems.
Thailand
Japanese supplier networks have relocated powerhead casting and precision machining to Thai industrial estates. EU Stage V and EPA certification reciprocity agreements streamline export logistics from Southeast Asian production bases. Rayong and Chonburi manufacturing zones serve as consolidation points for four-stroke component supply.
Marine Outboard Engine Market Competitive Environment
Japanese producers anchor the integrated marine systems tier; North American specialists hold the high-performance premium segment. Market structure concentrates around three dominant archetypes: diversified motor manufacturers with captive marine divisions, pure-play marine propulsion engineers, and industrial conglomerates with selective marine exposure. Competitive moves center on R&D reallocation toward electric platforms and dealer network capability restructuring for high-voltage service.
Within the integrated manufacturer tier, Yamaha Motor Co and Honda Motor Co occupy positions that exemplify platform breadth across displacement classes. Brunswick Corporation, operating through Mercury Marine, represents the specialized marine engineering archetype with concentrated North American distribution density. These three anchors illustrate how competitive positioning diverges between diversified industrial portfolios and focused marine propulsion expertise.
| Leading Market Players |
|---|
| Yamaha Motor Co |
| Brunswick Corporation |
| Honda Motor Co |
| Suzuki Motor Corporation |
| Mercury Marine |
| Tohatsu Corporation |
| Kawasaki Heavy Industries |
| Nissan Marine |
| Cox Powertrain |
| Others |
Value Chain & Pricing Dynamics
Four-stroke fuel-injection technology migration is compressing cost structures for Japanese and Thai manufacturing networks while simultaneously concentrating precision-casting capabilities in Nagoya and Hamamatsu industrial corridors. This dual shift rewards manufacturers with captive component production and penalizes assemblers dependent on spot-market powerhead sourcing.
Pricing Analysis
Distributor margins absorb EPA Tier 3 and EU Stage V compliance premiums before reaching end-users. Three-tier pricing structure across premium, standard, and economy levels separates Mercury Marine's high-performance V6 architectures from Yamaha's volume four-stroke mid-range and Tohatsu's portable utility segment. Cost compression in the 10-50 HP band is intensifying because Thai casting consolidation limits second-source availability. Charter operators in Florida exhibit lowest price sensitivity due to downtime-cost premiums, while Mediterranean leisure buyers in Greece and Italy face acute budget constraints.
Supply Chain Analysis
Neodymium and lithium supply rests on Chinese-processed rare earth refineries and South Korean cathode material producers. Japanese precision-machined fuel-injection components and Thai aluminum powerhead castings form the core manufacturing inputs. Single-source vulnerability concentrates in permanent-magnet motor assemblies where Japanese brushless designs dominate. Distribution runs through Brunswick's captive Mercury Marine dealer network and Yamaha's integrated marine division channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine outboard production is shifting toward Thai industrial estates to exploit EPA-EU certification reciprocity and escape Japanese labor-cost premiums. This geographic-arbitrage play rewards early relocators with margin expansion against domestic competitors.
For Market Incumbents: Anchor four-stroke platform dominance by securing long-term casting contracts with Rayong and Chonburi suppliers before capacity constraints harden. Defend against electric entrants by accelerating high-voltage technician certification programs in Florida and California dealer networks. Prioritize backward integration into lithium-ion battery pack assembly to capture electric platform margins.
For New Entrants and Emerging Players: Commercial fishing cooperatives in Japan represent the most penetrable buyer archetype due to power-by-the-hour contracting appetite and limited incumbent leasing infrastructure. Norwegian fjord tourism operators face captive zero-emission demand with thin electric supplier coverage. Pursue direct vessel-operator relationships bypassing established dealer networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among Thai-based component specialists with EPA/EU dual-certification capabilities and Japanese parent-company technical backing. Long-term viability hinges on electric platform transition timing rather than four-stroke replacement cycle durability. Watch battery-swapping service penetration in Bergen and Tromsø harbors as inflection indicator for Nordic electric adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform R&D Scale-Up | EPA Tier 3 and EU Stage V compliance deadlines eliminate two-stroke development pathways entirely. |
| Thai Manufacturing Footprint Expansion | Rayong and Chonburi industrial estates offer streamlined export logistics to US and European markets. |
| High-Voltage Technician Certification Programs | Marina service capacity in Florida and California lags electric outboard deployment rates. |
| Power-by-the-Hour Leasing Models | Japanese commercial fishing cooperatives shift capital burden from vessel owners to manufacturers. |
| Battery-Swapping Infrastructure Partnerships | Norwegian harbor authorities in Bergen and Tromsø expand dockside charging with swap services. |
Study Parameters
Direct dialogue with marine propulsion engineers, EPA certification specialists, marina operators in Florida and California, and procurement leads at Japanese fishing cooperatives grounded qualitative assessments. Secondary validation drew from EPA non-road emissions filings, EU Stage V technical documentation, Japan MLIT efficiency benchmark publications, and customs records for outboard engine trade flows. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-level projections across product type, power rating, end user, and fuel type dimensions were generated through the modeling period. CAGRs were derived from replacement cycle analysis, regulatory compliance timeline compression, and electric platform penetration curves. Key inputs included harbor authority combustion restriction schedules, lithium-ion energy density improvement trajectories, and Thai manufacturing capacity expansion announcements.
Inputs from EPA and EU regulatory filings were available through the study window; gaps in real-time Japanese cooperative leasing contract terms introduce uncertainty bands around commercial segment forecasts. Forecasts reflect assumptions regarding certification timeline adherence and battery supply chain localization commitments. A small set of triggers—including Norwegian fjord mandate enforcement velocity and Mediterranean marina electrical infrastructure investment rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Small Boats Market
Marine Vehicles
Marine Reciprocating Engine Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Trawler Boat Market