
 Liquid and Bulk Transportation Vessels Market | 2026-2036
Liquid and Bulk Transportation Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid and Bulk Transportation Vessels Market Foresight
Chemical transport demand from European petrochemical clusters is decoupling from traditional oil-linked contracting. Stolt-Nielsen specializes in parcel tanker operations for specialty chemicals across Atlantic and Asian trade lanes. COSCO Shipping leverages state-owned fleet scale to dominate crude and refined product movements on Middle East-to-Asia routes. Mitsui O.S.K. Lines anchors Japanese industrial supply chains with dedicated carriers for liquefied natural gas and petrochemical feedstocks.
Liquid and bulk transportation vessels are engineered steel-hulled cargo carriers with segregated cargo tanks or holds, designed to ISO 8686 load-line standards and double-hull mandates for hazardous liquid containment. Their primary purpose is the intercontinental movement of unprocessed commodities, processed liquids, and containerized goods between production zones and consumption or refining centers. Tankers and bulk carriers together carry the majority of tonnage-miles, with chemical tankers commanding premium day rates due to coating complexity and cleaning protocols. Barge fleets on inland waterways sustain margin pools through lower unit costs on repetitive routes between US river terminals and coastal hubs.
The International Maritime Organization enforces carbon intensity indicator ratings that penalize older, less efficient vessels with restricted port access or higher insurance burdens. ISO tank standards and the EU Emissions Trading System for maritime are tightening compliance costs for operators serving European ports. Classification societies including Lloyd's Register and DNV are certifying alternative-fuel-ready designs that will determine resale values and charter eligibility. Stakeholders must monitor fuel technology commitments against charterer carbon-accounting requirements to avoid stranded asset risk in vessel portfolios.
Market Dynamics
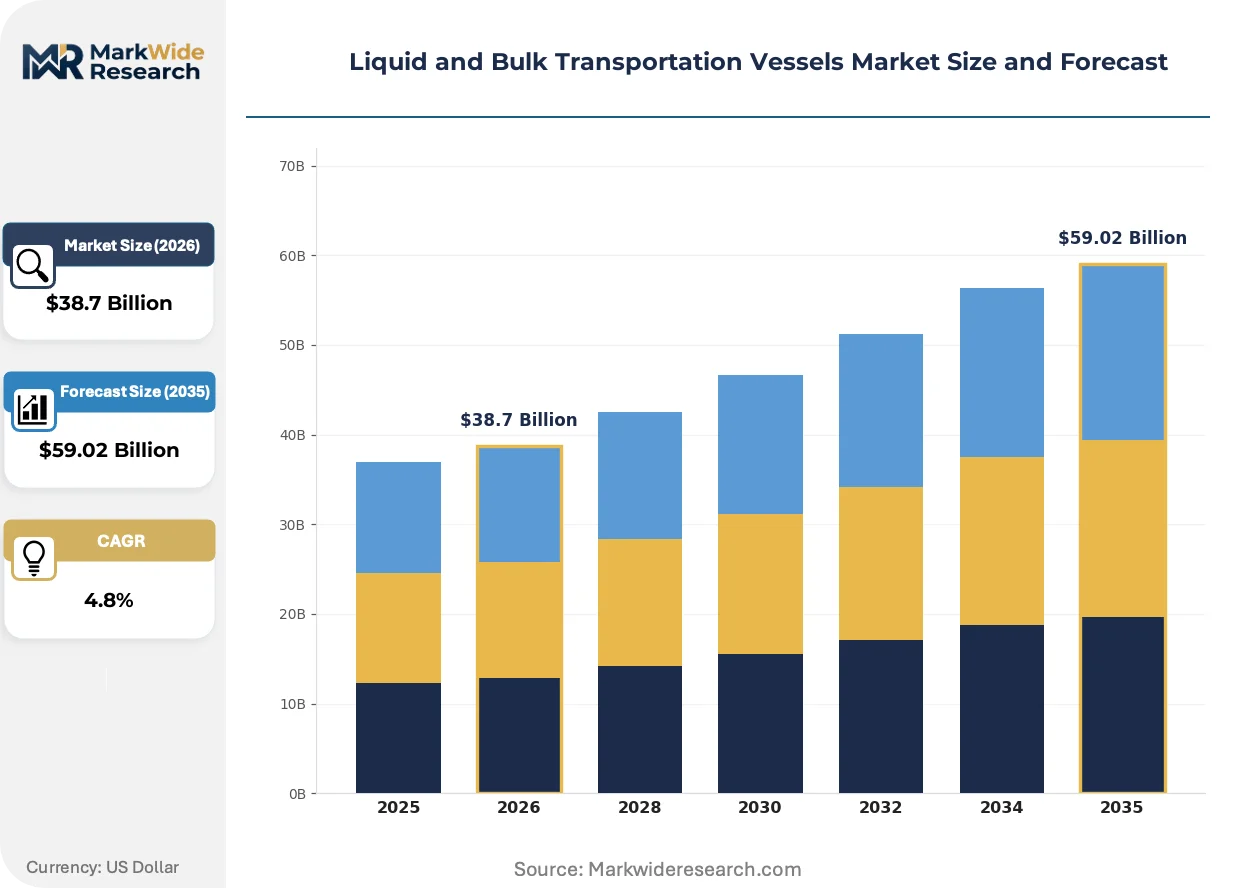
The International Maritime Organization's carbon intensity indicator is forcing fleet renewal decisions across chemical tanker and bulk carrier segments. Older vessels face restricted port access in Singapore, Rotterdam, and Houston, while charterers impose carbon-accounting requirements that reshape vessel ordering patterns and resale value calculations.
Growth Catalysts
- EU Emissions Trading System for Maritime:The EU ETS phase-in creates compliance-driven demand for dual-fuel-ready newbuilds. Shipyards in South Korea and Japan report order backlogs stretching into 2028 for methanol-capable chemical tankers.
- US Gulf Coast petrochemical expansion:Ethylene cracker additions along the Texas-Louisiana corridor generate incremental parcel tanker demand for specialty chemical exports to Asian manufacturing centers.
- Digital freight matching platforms:Algorithmic cargo-vessel pairing reduces ballast voyages and improves fleet utilization rates. Operators adopting these systems report reduced empty-running days on intra-Asia routes.
Market Restraints
- Steel plate cost volatility:Newbuild vessel construction depends on heavy steel plate pricing tied to Chinese blast furnace output. Price spikes in 2021-2022 delayed several speculative tanker orders at Asian yards.
- Engine maker concentration:Two-stroke marine engine supply concentrates around MAN Energy Solutions and WinGD. Technical failures or delivery delays at either supplier cascade through newbuild delivery schedules.
- Scrubber payback uncertainty:Exhaust gas cleaning system retrofits face extended payback periods when high-sulfur fuel oil spreads compress. Some owners deferred scrubber installations after 2020 IMO fuel sulfur rules stabilized.
Strategic Opportunities
- Ammonia fuel conversion pathways:Classification societies including DNV and Lloyd's Register certify ammonia-ready vessel designs. First-movers securing these notations capture charterer preference for future-proofed tonnage.
- Indian coastal chemical distribution:The country's Petrochemicals Investment Region scheme clusters production at Dahej and Paradeep. Short-sea chemical tanker demand between these hubs and western port complexes remains underserved.
- Carbon capture-ready vessel architecture:Onboard CO2 capture systems enter pilot phase for LNG carriers. Retrofit-ready tanker designs could access premium charter rates from European industrial shippers with net-zero commitments.
Industry Challenges
- Marine engineer scarcity:Specialized training for dual-fuel engine maintenance outpaces available technical school capacity. Operators report extended recruitment timelines for engineering officers qualified on methanol and ammonia systems.
- Coating certification delays:Cargo tank lining approvals for novel chemical cargoes require extended testing protocols at classification society laboratories. Product tanker operators face revenue loss when specialty chemical contracts await coating compatibility verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid and Bulk Transportation Vessels Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Tankers, Barges, Bulk Carriers, Container Ships Payload Capacity: Small, Medium, Large, Extra Large Application: Chemical Transport, Oil & Gas Transport, Food & Beverage Logistics, General Cargo End User: Shipping Companies, Logistics Providers, Manufacturing Firms, Energy Sector |
| Companies Covered | Maersk Tankers, Stolt-Nielsen, CMA CGM Group, Hapag-Lloyd, Mitsui O.S.K. Lines, COSCO Shipping, Teekay Corporation, Scorpio Tankers, Frontline Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid and Bulk Transportation Vessels Market Shifts & Advancements
Alternative fuel propulsion systems are reshaping vessel specification sheets and charter negotiation frameworks. Shipowners now lead engineering discussions with fuel pathway commitments rather than traditional speed-consumption curves.
Modular battery-electric propulsion is decentralizing auxiliary power architecture on short-sea chemical tankers. Scandinavian coastal operators deploy plug-in hybrid systems for port maneuvering and berth emissions compliance. This technology is decentralizing the traditional central-engine-room power model toward distributed energy zones with redundant failure modes.
The EU Emissions Trading System for maritime entered full phase-in during 2024, imposing direct carbon costs on vessel operators serving European ports. Freight contracts now separate EUA pass-through clauses from base hire rates. Chemical tanker trades from Rotterdam to Mediterranean industrial ports exhibit the most active carbon cost hedging through forward EUA purchases.
Charterers now unbundle vessel performance guarantees from standard time charter agreements. Major European petrochemical producers issue separate emissions accountability contracts requiring verified fuel consumption data. This restructuring concentrates procurement influence among shippers with in-house carbon accounting capabilities, particularly German and Dutch industrial conglomerates with Scope 3 reporting obligations.
Liquid and Bulk Transportation Vessels Market Segmentation
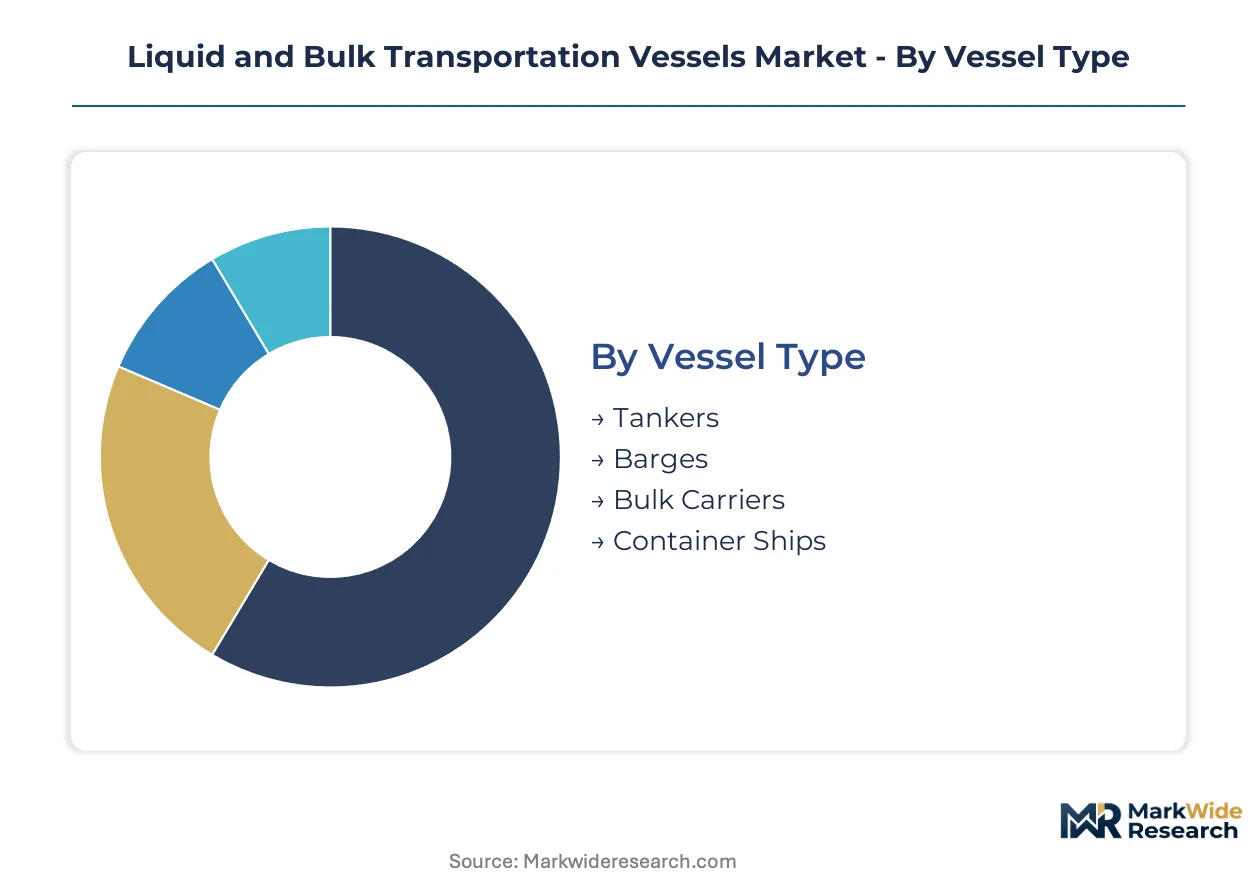
Vessel specification choices lock in decades of operating economics and regulatory compliance paths. Segment boundaries in this market reflect capital deployment thresholds, cargo containment requirements, and charterer carbon-accounting preferences.
Vessel Type:
Tankers command the heaviest upfront capital outlays, with specialized cargo containment systems and coating protocols driving construction premiums at Asian shipyards.
- Tankers:Segregated cargo tanks with epoxy or stainless-steel linings handle hazardous liquids under ISO 8686 load-line standards. Parcel chemical tankers serving Rotterdam and Houston petrochemical corridors absorb the strictest coating certification requirements.
- Barges:Flat-bottomed hulls with push-tow configurations dominate Mississippi River and Rhine corridor movements. Lower unit costs on repetitive routes between US river terminals and coastal hubs sustain margin pools despite restricted seakeeping capability.
- Bulk Carriers:Single-deck designs with large hatch openings transport unpackaged dry commodities. Capesize vessels on Brazil-to-China iron ore routes face the steepest carbon intensity indicator penalties from IMO regulations.
- Container Ships:Cellular guide systems and lashing bridges enable intermodal cargo unitization. Dual-fuel methanol conversions at Singapore repair yards are concentrating among this segment due to charterer net-zero commitments.
Tankers absorb the bulk of installed capacity; container ships are expanding most quickly as liner operators retrofit for alternative fuels.
Payload Capacity:
Size tier selection determines port access economics and cargo aggregation strategies across trade lane configurations.
- Extra Large:Capesize bulk carriers and VLCC tankers exceed 200,000 deadweight tons, restricting access to deepwater terminals at Singapore, Rotterdam, and Houston. These vessels achieve lowest unit costs on long-haul crude and iron ore movements.
- Large:Suezmax and Aframax tankers, plus Panamax bulk carriers, balance draft limitations against economies of scale. European petrochemical clusters favor this tier for flexible parcel chemical operations.
- Medium:Handysize bulkers and chemical tankers serve secondary ports with restricted channel depths. Indian coastal chemical distribution between Dahej and Paradeep relies heavily on this tier.
- Small:Inland waterway barges and short-sea feeders operate below 10,000 deadweight tons. Scandinavian coastal operators deploy plug-in hybrid variants for berth emissions compliance.
Large vessels carry the majority of tonnage-miles; small craft are gaining share fastest through electrification pilots.
Application:
Cargo chemistry dictates hull architecture, with hazardous liquid containment commanding premium specification tiers.
- Chemical Transport:Stainless-steel or epoxy-coated tanks with multi-compartment segregation handle specialty cargoes. Coating certification delays at classification society laboratories create revenue bottlenecks for product tanker operators.
- Oil & Gas Transport:Crude carriers and LNG vessels feature membrane or spherical cargo containment. Methanol-capable newbuilds at South Korean yards are concentrating in this segment.
- Food & Beverage Logistics:Edible oil and juice tankers require food-grade certification and temperature control. ISO tank standards govern intermodal movements of liquid foodstuffs.
- General Cargo:Breakbulk and neo-bulk vessels handle non-containerized manufactured goods. This segment faces the weakest carbon-accounting pressure from charterers.
Oil and gas transport dominates fleet capacity deployment; chemical transport is climbing the fastest on specialty cargo premiumization.
End User:
Procurement authority concentrates among integrated energy majors and German-Dutch industrial conglomerates with Scope 3 reporting obligations.
- Shipping Companies:Independent owners and liner operators manage vessel assets against charter market cycles. These firms face stranded asset risk from IMO carbon intensity indicator downgrades.
- Logistics Providers:Freight forwarders and 3PLs charter tonnage on spot and contract markets. Digital freight matching platforms are reshaping their vessel sourcing patterns.
- Manufacturing Firms:Petrochemical and steel producers operate captive fleets or long-term charters. EU Emissions Trading System compliance costs flow through to these shippers via EUA pass-through clauses.
- Energy Sector:Oil majors and LNG portfolio players control crude, product, and gas carrier fleets. These entities lead ammonia fuel conversion pathway discussions with classification societies.
Shipping companies control the largest installed base; manufacturing firms are expanding their direct tonnage involvement fastest through carbon-accounting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's hub port complex anchors vessel concentration through tax-advantaged registration frameworks and bunkering infrastructure. Demand clusters at the US Gulf Coast petrochemical corridor and Rotterdam's refining hub.
United States
Ethylene cracker additions along the Texas-Louisiana corridor generate parcel tanker demand for specialty chemical exports. The EPA enforces vessel emissions standards under the Clean Air Act for coastal operations. Houston's petrochemical corridor absorbs the highest concentration of chemical tanker calls on the Gulf Coast.
Singapore
The Maritime and Port Authority of Singapore mandates low-carbon fuel standards for harbor craft and coastal vessels. Its hub port complex concentrates chemical tanker transhipment between Middle East producers and Asian manufacturers. Jurong Island's integrated petrochemical facilities drive dedicated short-sea chemical distribution requirements.
Germany
Rhine corridor barge operators face EU Emissions Trading System compliance costs for inland waterway movements. The Federal Maritime and Hydrographic Agency enforces double-hull standards for liquid cargo vessels. Ludwigshafen's BASF complex and Hamburg's port cluster sustain chemical tanker demand for industrial feedstock deliveries.
China
State-owned fleet operators dominate crude import routes from the Middle East and Africa. The Ministry of Transport implements domestic emission control area regulations for coastal shipping. Ningbo-Zhoushan port complex handles the largest crude oil throughput volumes globally.
Netherlands
Rotterdam's petrochemical corridor decouples from traditional oil-linked contracting models. The Human Environment and Transport Inspectorate enforces port state control under Paris MoU standards. The Port of Rotterdam Authority mandates shore power connections for berth emissions compliance.
Liquid and Bulk Transportation Vessels Market Competitive Landscape
Top-tier vendors anchor state-backed fleet scale, while independent owners concentrate on specialized chemical and parcel tanker niches. The market structures around three distinct tiers: integrated energy majors with captive tonnage, diversified industrial conglomerates with long-term charter portfolios, and independent shipowners trading spot market cycles. Strategic archetypes include dual-fuel newbuild specialists, scrubber retrofit aggregators, and digital freight platform operators. Competitive moves concentrate on ammonia-ready vessel certification and carbon-accounting data partnerships with European charterers.
Within the diversified industrial tier, Mitsui O.S.K. Lines and COSCO Shipping exemplify state-linked fleet operators with integrated energy transport portfolios. Stolt-Nielsen occupies a specialized position among parcel chemical tanker operators serving Atlantic and Asian trade lanes. These three entities represent contrasting archetypes: Japanese industrial supply chain anchoring, Chinese state-scale crude movement dominance, and European specialty chemical logistics focus.
| Leading Market Players |
|---|
| Maersk Tankers |
| Stolt-Nielsen |
| CMA CGM Group |
| Hapag-Lloyd |
| Mitsui O.S.K. Lines |
| COSCO Shipping |
| Teekay Corporation |
| Scorpio Tankers |
| Frontline Ltd. |
| Others |
Supply & Pricing Matrix
EU Emissions Trading System compliance costs are reshaping charterer procurement preferences toward dual-fuel-ready vessels, forcing shipyards to reconfigure production lines and compressing margins on conventional newbuilds. This demand-side specification shift concentrates pricing power among South Korean and Japanese yards with certified alternative-fuel capabilities.
Pricing Analysis
Short lead-time premiums dominate chemical tanker contracting, with charterers paying 15-20% day-rate spreads for immediate availability of IMO carbon intensity indicator-compliant tonnage. Pricing stratifies across methanol-ready, LNG-dual-fuel, and conventional residual-fuel tiers, with certification grade from DNV or Lloyd's Register commanding measurable hire-rate premiums. Cost compression in the conventional segment is intensifying because older vessels face Rotterdam and Singapore port access restrictions. Independent shipowners with spot-market exposure exhibit the highest price sensitivity, while integrated energy majors with captive fleets absorb specification premiums for long-term carbon-accounting compliance.
Supply Chain Analysis
Classification society certification requirements gate vessel construction eligibility, with Lloyd's Register and DNV approvals determining resale values and charter eligibility across the global fleet. Heavy steel plate supply concentrates in China, South Korea, and Japan, with blast furnace output volatility feeding directly into newbuild pricing. Marine engine supply draws from MAN Energy Solutions and WinGD, creating single-source vulnerability for two-stroke propulsion systems. Distribution runs through Singapore's hub port complex for transhipment, Rotterdam for European petrochemical corridors, and Houston for US Gulf Coast chemical exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with players pursuing backward control over methanol and ammonia fuel supply chains to lock in charterer preference for future-proofed tonnage.
For Market Incumbents: Acquire ammonia-ready vessel designs certified by classification societies to preempt charterer carbon-accounting requirements. Secure long-term methanol supply offtakes from Middle Eastern producers before fuel pathway standardization crystallizes. Defensive positioning requires scrubber retrofit aggregators to consolidate distressed conventional tonnage before IMO carbon intensity indicator downgrades accelerate resale value erosion. For New Entrants and Emerging Players: Digital freight matching platforms offer a technology-first wedge into the spot-market vessel sourcing layer currently dominated by traditional broker networks. Target Indian coastal chemical distribution between Dahej and Paradeep, where short-sea tanker capacity remains underserved by established operators. A go-to-market angle anchored in verified carbon-accounting data partnerships with German and Dutch industrial conglomerates bypasses incumbent scale advantages. For Investors and Strategic Acquirers: The window for entry favors dual-fuel newbuild specialists with order backlogs at South Korean yards extending through the analysis window. Long-term viability hinges on exposure to ammonia fuel conversion pathways rather than transitional LNG dual-fuel positions. The signal to watch is classification society certification velocity for novel fuel systems, which determines charter eligibility and resale liquidity.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Ready Vessel Certification | DNV and Lloyd's Register notations determine future charter eligibility from European petrochemical producers. |
| Backward Integration into Fuel Supply | Captive methanol sourcing from Middle Eastern producers locks in operating cost advantages for dual-fuel fleets. |
| Digital Freight Matching Platform | Algorithmic cargo-vessel pairing reduces ballast voyages and captures margin from traditional broker networks. |
| Scrubber Retrofit Aggregation | Consolidation of distressed conventional tonnage defends residual value before IMO carbon intensity penalties deepen. |
| Carbon-Accounting Data Partnership | Verified fuel consumption reporting meets Scope 3 obligations from German and Dutch industrial conglomerates. |
Research Methodology
Multi-period observation of vessel order backlogs, charter rate indices, and regulatory implementation timelines anchored the trend analysis, supplemented by interviews with fleet managers at independent shipowners, procurement leads at European petrochemical conglomerates, shipyard commercial officers in South Korea and Japan, and marine engineers qualified on methanol and ammonia systems. Secondary validation drew from Lloyd's Register and DNV certification databases, International Maritime Organization regulatory filings, EU Emissions Trading System compliance records, and customs trade data for chemical tanker movements. Bottom-up fleet capacity modeling triangulated against top-down demand projections from petrochemical capacity expansion announcements.
Segment-weighting across vessel type, payload capacity tier, fuel technology readiness, and regional trade lane concentration shaped the analytical framework over the projection horizon. CAGRs were derived from regression analysis against historical charter rate volatility, newbuild delivery schedules, and regulatory phase-in trajectories. Industry-specific forecast inputs included IMO carbon intensity indicator compliance cost curves and shipyard steel plate pricing sensitivity.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations, marine engine maker supply disruptions, and geopolitical interruptions to Middle East methanol supply chains. Forecasts reflect documented assumptions regarding fuel technology adoption rates and classification society certification timelines. A model refresh is warranted upon material change in IMO regulatory enforcement stringency or breakthrough in onboard carbon capture system commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Boat Davits Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Marine Fuel Injection System Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
Marine Outboard Engine Market