
 Marine Hybrid Propulsion Market | 2026-2036
Marine Hybrid Propulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Hybrid Propulsion Market Intelligence
Norway is fragmenting its marine propulsion supply base as state-funded ferry electrification programs multiply regional OEM partnerships. Wärtsilä leverages its Helsinki engineering campus to dominate diesel-electric integration for offshore support vessels. Siemens Energy anchors German harbor craft retrofits with shore-charging grid interfaces. MAN Energy Solutions competes through dual-fuel engine architectures that bridge conventional and hybrid operational profiles.
Marine hybrid propulsion combines two or more power sources—typically internal combustion engines with electric motors, energy storage, or fuel cells—through a unified drivetrain management system operating at 690V to 3.3kV DC bus voltages. The architecture enables load-optimized fuel consumption, zero-emission harbor maneuvering, and redundancy for critical vessel operations. Diesel-electric configurations retain the largest installed base among propulsion types, though battery-electric systems claim the fastest expansion trajectory in sub-1,000-tonne coastal craft. Permanent magnet motors command premium positioning within drive technology segments due to torque density advantages, while induction motor variants sustain cost-sensitive retrofit demand across aging ferry fleets.
IMO sulfur regulations and EEDI Phase 3 standards reshape vessel design specifications, compelling shipyards to certify hybrid architectures for compliance. The EPA enforces Tier 4 marine engine rules in US waters, restricting particulate emissions from auxiliary gensets that hybrid systems must offset. EU Green Deal funding mechanisms and national subsidy programs in Germany and Norway accelerate port electrification infrastructure build-outs. Stakeholders must weigh fuel cell maturity curves against battery energy density limits when specifying next-generation coastal vessel platforms.
Market Dynamics
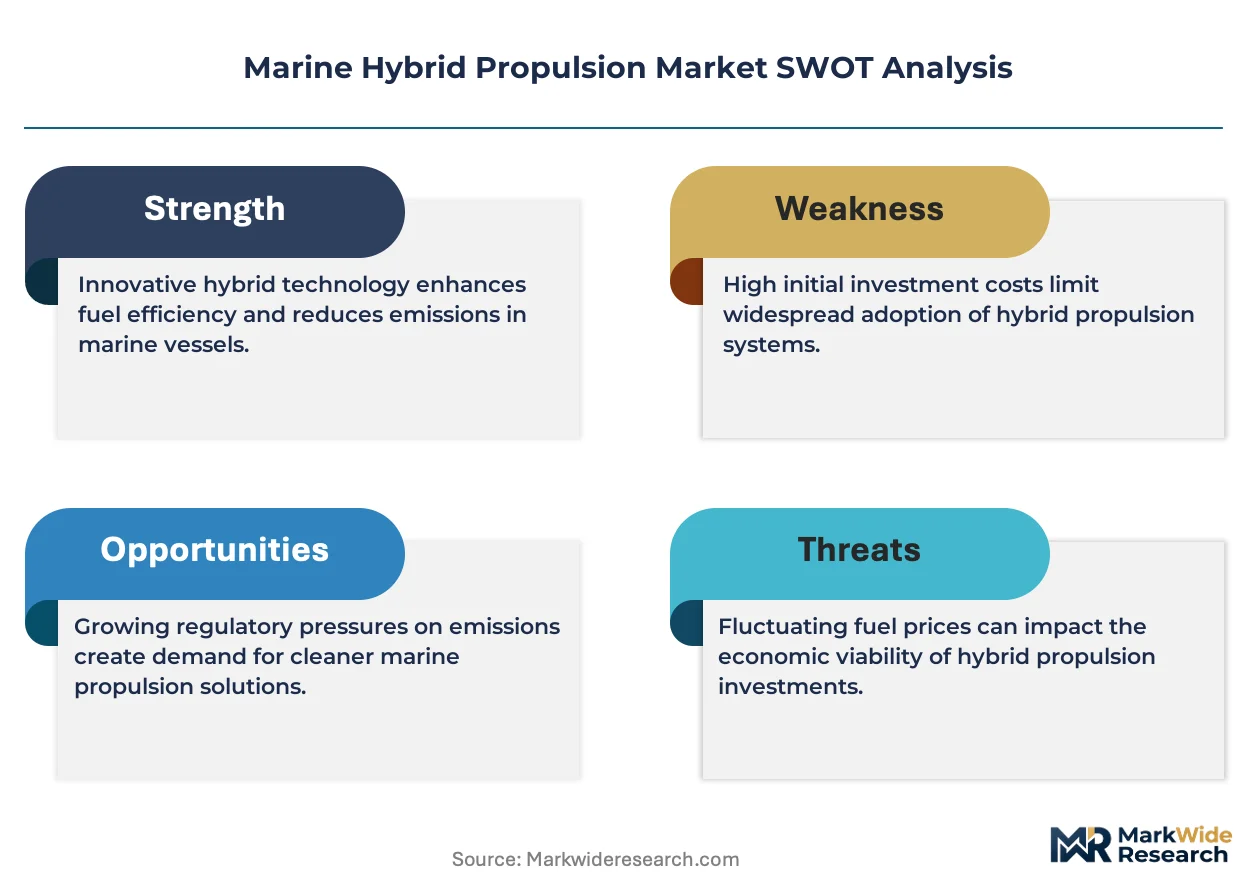
IMO sulfur caps and EEDI Phase 3 standards are forcing ferry operators and offshore vessel owners to re-specify propulsion architectures, converting what was once a fuel-efficiency option into a compliance mandate.
Growth Catalysts
- EU Green Deal port electrification subsidies:Norway and Germany channel state funding into shore-charging infrastructure, lowering the capital barrier for hybrid ferry retrofits.
- Permanent magnet motor torque density:Advances in high-efficiency drive technology cut harbor transit fuel consumption by enabling electric-only maneuvering modes.
- Offshore support vessel redundancy requirements:North Sea operators specify diesel-electric architectures to satisfy insurance and charterer demands for operational continuity.
Market Restraints
- Lithium-ion battery cell cost volatility:Raw material price swings for nickel and cobalt compress margins on battery-electric system integrators.
- Harbor grid capacity constraints:Port authorities in Japan and Northern Europe face multi-year lead times for substation upgrades that hybrid vessels require.
- Fuel cell stack durability limitations:Proton exchange membrane degradation rates in salt-air environments delay commercial deployment beyond pilot phases.
Strategic Opportunities
- Japanese coastal electrification corridors:METI-funded island ferry routes present untapped demand for battery-hybrid specifications.
- Modular swappable battery container systems:Containerized energy storage enables rapid refueling without fixed infrastructure, opening short-sea routes.
- Dual-fuel engine hybrid integration:Ammonia-ready combustion architectures allow shipowners to future-proof against evolving IMO decarbonization pathways.
Industry Challenges
- Marine electrical engineer scarcity:Shipyards in Norway and Germany compete for limited talent pools capable of integrating 3.3kV DC bus systems.
- Type approval timeline compression:Classification societies face backlogs certifying novel hybrid architectures under updated IGF Code amendments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Hybrid Propulsion Market |
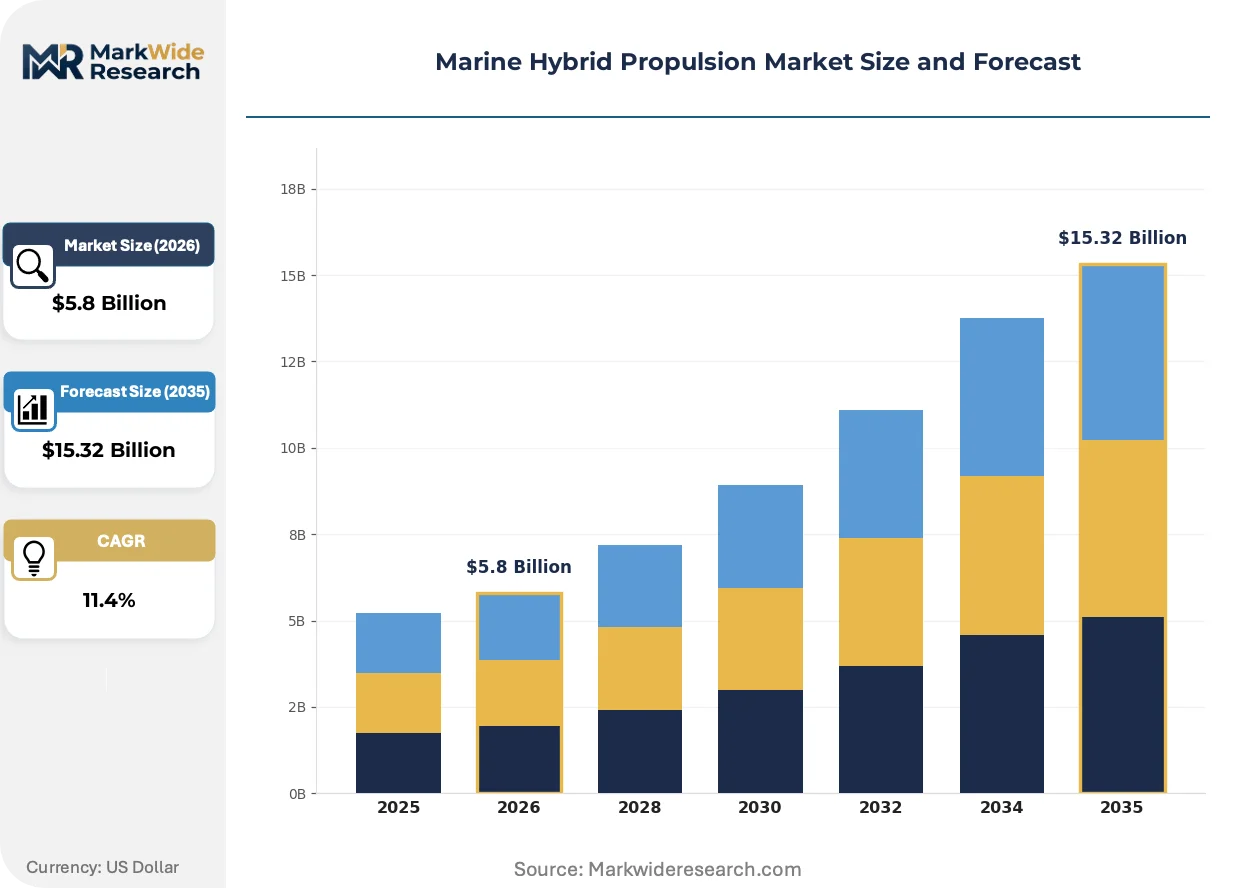
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Diesel-Electric, Fuel Cell, Battery-Electric, Gas Turbine Hybrid, Solar-Assisted Vessel Type: Cruise Ships, Ferries, Offshore Support Vessels, Naval Ships, Research Vessels Drive Technology: Permanent Magnet Motors, Induction Motors, Synchronous Motors, Switched Reluctance Motors End User: Maritime Operators, Shipbuilders, Defense Contractors, Shipping Lines |
| Companies Covered | ABB, BAE Systems, Caterpillar, MAN Energy Solutions, Wärtsilä, Rolls-Royce, Siemens Energy, General Electric, Nidec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Hybrid Propulsion Market Strategic Shifts & Innovations
Digital twin technology is compressing vessel design cycles while regulatory pressure accelerates hardware refresh rates. The convergence of simulation tools and electrification mandates is reshaping how propulsion systems are specified, tested, and commissioned.
Digital twin platforms are virtualizing propulsion system validation by modeling load profiles, thermal behavior, and energy flow before physical installation. Ferry operators in Norway now require simulation-based performance guarantees from integrators. The technology is virtualizing traditional sea-trial protocols, cutting commissioning time and warranty risk for complex hybrid drivetrains.
EPA Tier 4 marine engine rules enforce particulate emission limits on auxiliary gensets in US waters. Hybrid system designers must offset conventional engine runtime to maintain compliance. Offshore supply vessel fleets operating in the Gulf of Mexico are responding by expanding battery-electric harbor mode specifications.
Charterers now unbundle propulsion performance guarantees from vessel day-rate contracts, demanding fuel-consumption clauses tied to actual operating data. This shifts risk to system integrators and favors suppliers with telemetry infrastructure. The practice is most visible in North Sea offshore vessel markets where ESG reporting requirements pressure asset operators.
Marine Hybrid Propulsion Market Segmentation
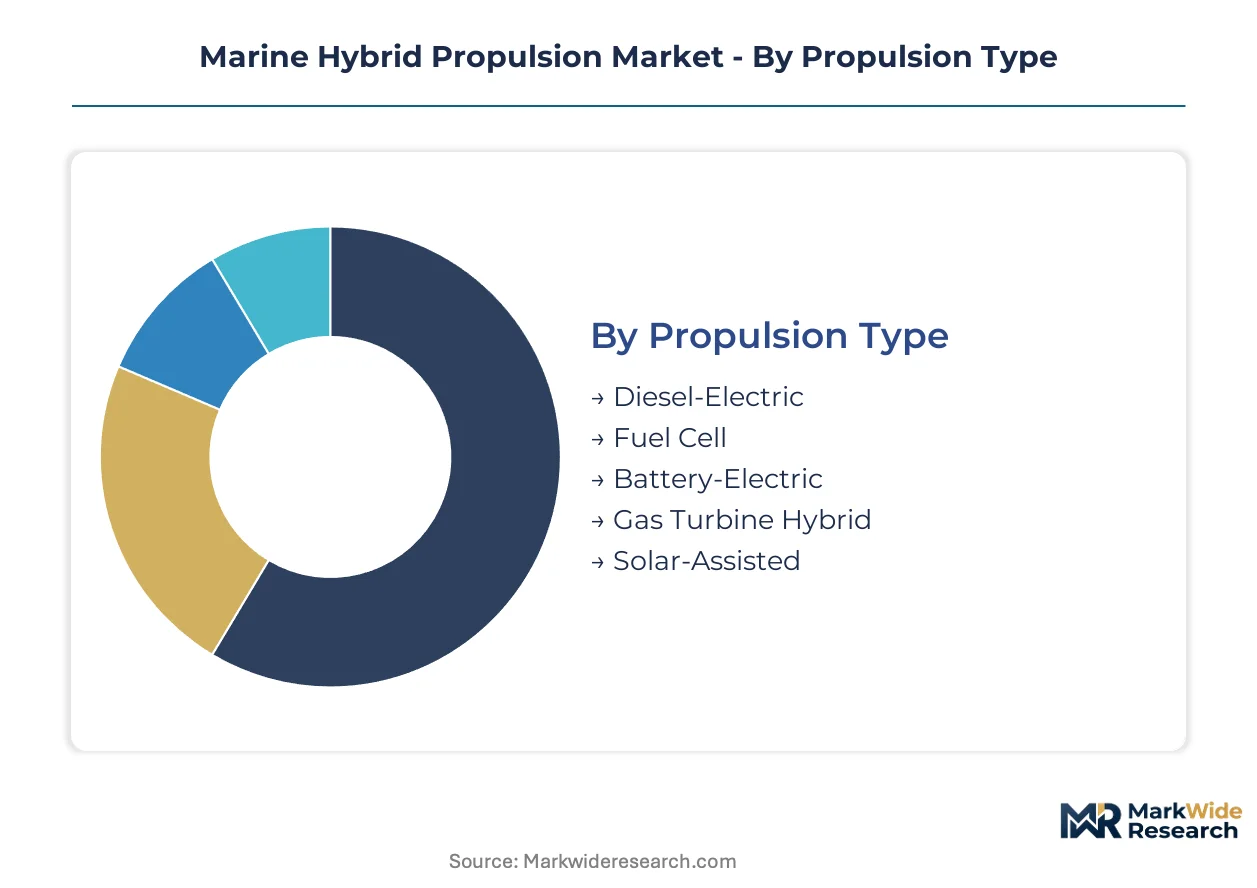
Marine hybrid propulsion architectures vary dramatically across operational profiles, from harbor maneuvering to open-ocean transit. Segment boundaries reflect fundamental trade-offs between capital intensity, fuel flexibility, and regulatory compliance pathways that shape procurement decisions.
Propulsion Type:
Use-case spectrum spans diesel-electric redundancy for offshore operations through zero-emission battery-electric harbor craft to experimental fuel cell platforms for coastal corridors.
- Diesel-Electric:Combines conventional combustion engines with generator sets feeding electric distribution buses at 690V to 3.3kV DC. Norwegian ferry operators specify these architectures for route flexibility where shore-charging infrastructure remains incomplete.
- Battery-Electric:Relies entirely on lithium-ion energy storage with no onboard combustion, requiring megawatt-scale shore-charging interfaces. German port authorities fund these specifications for scheduled short-sea routes with predictable duty cycles.
- Fuel Cell:Proton exchange membrane stacks generate electricity through hydrogen oxidation, emitting only water vapor. Japanese METI-funded pilot programs test these systems on island ferry corridors.
- Gas Turbine Hybrid:Aero-derivative turbines provide rapid power response for naval applications requiring sprint speeds alongside electric cruise modes.
- Solar-Assisted:Photovoltaic arrays supplement primary propulsion on research vessels with extended loiter requirements and minimal speed demands.
The dominant share belongs to Diesel-Electric, while Battery-Electric is closing the gap fastest.
Vessel Type:
Cost tier segmentation separates capital-intensive cruise retrofits from subsidy-dependent coastal ferries and mission-critical naval specifications.
- Ferries:Coastal passenger vessels with predictable route profiles enable battery-electric specifications where shore infrastructure exists. EU Green Deal subsidies in Norway and Germany concentrate orders in this category.
- Offshore Support Vessels:Dynamic positioning requirements and insurance-mandated redundancy drive diesel-electric specifications for North Sea oilfield service fleets.
- Cruise Ships:Large passenger vessels face EEDI Phase 3 compliance pressure through hybrid auxiliary systems rather than full propulsion electrification.
- Naval Ships:Military specifications prioritize acoustic signature reduction and battle redundancy through integrated electric propulsion architectures.
- Research Vessels:Scientific mission profiles with extended station-keeping requirements favor hybrid systems enabling silent electric observation modes.
Ferries command the largest order backlog, though Offshore Support Vessels sustain the highest average system value per installation.
Drive Technology:
Volume concentration favors mature induction motor platforms for cost-sensitive retrofits while premium permanent magnet systems capture newbuild specifications.
- Permanent Magnet Motors:Rare-earth magnet rotors deliver torque density advantages enabling compact packaging for restricted engine room envelopes. Japanese coastal electrification corridors specify these for weight-critical battery-electric ferries.
- Induction Motors:Squirrel-cage rotor designs without permanent magnets reduce capital cost and supply chain risk for aging European ferry fleet retrofits.
- Synchronous Motors:Field-excited rotor architectures provide precise speed control for dynamic positioning applications in offshore vessel thrusters.
- Switched Reluctance Motors:Magnet-free designs with robust rotor construction suit military specifications prioritizing supply chain independence and fault tolerance.
Permanent Magnet Motors anchor premium newbuild demand, while Induction Motors defend the retrofit volume base.
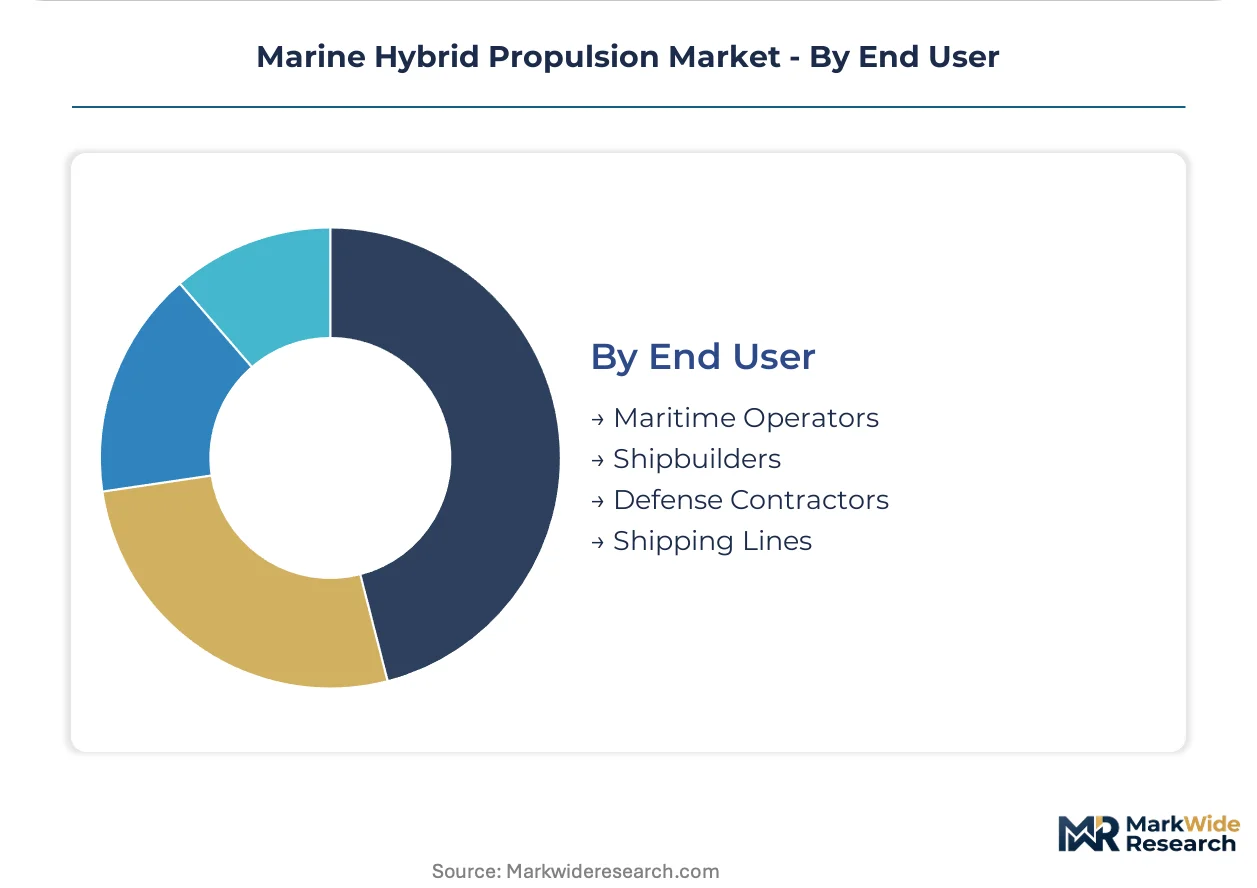
End User:
Customer type segmentation distinguishes fleet operators with ESG reporting obligations from shipbuilders integrating systems under yard contracts and defense procurement with classified requirements.
- Maritime Operators:Ferry companies and offshore vessel owners specify hybrid systems to satisfy charterer fuel-consumption clauses and IMO compliance mandates. Norwegian operators unbundle propulsion performance guarantees from day-rate contracts.
- Shipbuilders:European and Japanese yards integrate hybrid architectures during new construction, managing classification society certification timelines for novel IGF Code amendments.
- Defense Contractors:Naval system integrators face distinct electromagnetic signature and shock-hardening specifications separate from commercial marine standards.
- Shipping Lines:Container and bulk carriers explore hybrid auxiliary systems for harbor maneuvering rather than full propulsion electrification given route unpredictability.
Maritime Operators drive commercial specification evolution, while Shipbuilders control integration risk and certification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway deploys battery-dominant architectures for short-sea ferries, while Germany and Japan favor diesel-electric hybrids with shore-charging infrastructure. The United States concentrates on offshore vessel retrofits under EPA Tier 4 mandates.
Norway
Ferry operators along the fjord corridors specify full battery-electric systems for routes under 10 nautical miles. The Norwegian Maritime Authority fast-tracks zero-emission vessel certifications through streamlined approval pathways. Bergen and Stavanger host integration clusters where local shipyards partner with European drivetrain suppliers on state-funded electrification programs.
Germany
Harbor craft operators in Hamburg and Bremerhaven retrofit diesel-electric architectures to meet EU Green Deal port electrification timelines. The Federal Maritime and Hydrographic Agency enforces strict shore-power connection standards for vessels at berth. The North Sea coast concentrates system integration activity, with Kiel-based engineering firms dominating ferry retrofit contracts.
Japan
Island ferry routes in the Seto Inland Sea test fuel cell-battery hybrid configurations under METI decarbonization pilots. The country's ship classification society, ClassNK, issues provisional rules for hydrogen-fueled vessel construction. Nagasaki and Kobe anchor manufacturing clusters where heavy industry groups assemble proton exchange membrane systems for coastal deployment.
United States
Gulf of Mexico offshore support vessel fleets expand battery-electric harbor modes to satisfy EPA Tier 4 particulate limits on auxiliary gensets. The US Coast Guard coordinates with classification societies on hybrid system safety equivalencies under 46 CFR standards. Louisiana shipyards and Houston engineering offices concentrate diesel-electric retrofit activity for oilfield service operators.
United Kingdom
Scottish ferry operators specify hybrid architectures for Orkney and Shetland route renewals under Transport Scotland decarbonization funding. The Maritime and Coastguard Agency aligns hybrid certification with updated IMO IGF Code amendments. The Clyde shipbuilding corridor and Aberdeen offshore engineering clusters drive system integration for North Sea vessel operators.
Marine Hybrid Propulsion Market Key Industry Players
Capability concentration sits with engineering-intensive system integrators; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three tiers: full-propulsion providers managing 3.3kV DC bus architectures, component specialists supplying permanent magnet motors and power electronics, and shipyard-affiliated integrators handling retrofit installations. Strategic moves center on port electrification partnerships and dual-fuel engine hybridization to bridge compliance timelines.
Among Nordic engineering groups, Wärtsilä and ABB occupy positions anchoring diesel-electric and full-electric system integration for commercial vessel operators. Siemens Energy exemplifies the grid-interface specialist archetype, supplying shore-charging infrastructure and vessel-side power management. MAN Energy Solutions represents the combustion-hybrid tier, bridging conventional engine architectures with electric drivetrain compatibility for shipowners navigating IMO decarbonization pathways.
| Leading Market Players |
|---|
| ABB |
| BAE Systems |
| Caterpillar |
| MAN Energy Solutions |
| Wärtsilä |
| Rolls-Royce |
| Siemens Energy |
| General Electric |
| Nidec |
| Others |
Cost & Logistics Intelligence
Bergen and Stavanger anchor European system integration capacity, where local shipyard partnerships with state-funded ferry electrification programs concentrate procurement leverage. This geographic clustering enables tiered pricing power for permanent magnet motor assemblies and 3.3kV DC bus architectures, while raw material volatility for rare-earth magnets compresses margins on battery-electric specifications.
Pricing Analysis
European harbor craft retrofits command 15-25% premiums over Asian newbuilds due to EU Green Deal compliance certification requirements. Three-tier pricing structure across premium permanent magnet systems, standard induction motor retrofits, and economy diesel-electric configurations reflects torque density and shore-charging compatibility. Cost compression in battery-electric tiers is intensifying because nickel and cobalt cell price volatility feeds through to system integrators. Ferry operators in Norway exhibit lowest price sensitivity given state subsidy coverage, while independent offshore vessel owners in the Gulf of Mexico face acute capital constraints.
Supply Chain Analysis
Foundry capacity for high-voltage power electronics concentrates in Germany, Japan, and South Korea, with ABB and Siemens Energy holding dominant semiconductor packaging positions. Permanent magnet rotors draw from Chinese rare-earth processing and Japanese magnet alloy production, creating single-source vulnerability for neodymium supply. Tariff exposure on Chinese magnetic materials threatens cost predictability for European drivetrain assemblers. Distribution runs through shipyard-integrated procurement channels rather than independent aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full battery-electric architectures represent the primary substitution threat to diesel-electric incumbents as shore-charging infrastructure matures and cell energy density improves.
For Market Incumbents: Pre-empt margin erosion in harbor maneuvering segments by securing exclusive shore-charging interface partnerships with port authorities in Hamburg and Bergen. Backward integration into permanent magnet rotor production reduces exposure to Chinese rare-earth price volatility. Dual-fuel engine certification investments bridge IMO decarbonization timelines while defending installed base against pure-electric challengers.
For New Entrants and Emerging Players: Japanese island ferry routes under METI decarbonization pilots represent the most penetrable entry point for fuel cell-battery hybrid configurations. Modular swappable battery container systems for short-sea corridors bypass fixed infrastructure requirements that favor established integrators. Partner with ClassNK on provisional hydrogen construction rules to accelerate type approval timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because IMO sulfur caps and EEDI Phase 3 standards convert fuel-efficiency options into mandatory specifications. Acquisition targets should emphasize shipyard-affiliated integrators with IGF Code certification track records and telemetry infrastructure for performance-based charter contracts. Monitor Norwegian Maritime Authority zero-emission certification velocity as demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Shore-Charging Infrastructure Partnership | Port authority agreements in Hamburg and Bergen lock in captive demand for hybrid ferry specifications. |
| Dual-Fuel Engine Certification | Ammonia-ready MAN Energy Solutions architectures future-proof against IMO 2050 decarbonization pathways. |
| Permanent Magnet Motor Vertical Integration | In-house rare-earth rotor production insulates Wärtsilä and ABB from Chinese supply price volatility. |
| Digital Twin Platform Deployment | Simulation-based performance guarantees compress commissioning timelines and warranty risk for Norwegian operators. |
| Fuel Cell Stack Durability Investment | Proton exchange membrane salt-air degradation solutions unlock Japanese coastal corridor commercialization. |
Research Approach
A standing panel of ferry fleet managers, offshore vessel technical superintendents, shipyard procurement directors, and classification society surveyors provided ongoing calibration for demand assumptions and technology adoption timelines. Primary fieldwork combined structured interviews with secondary validation through IMO regulatory filings, EU Green Deal funding disbursement records, and national maritime authority certification databases. Bottom-up vessel orderbook analysis triangulated against top-down propulsion system value estimates across the analysis window.
Scenario-bracketing framed low, base, and high cases for battery energy density improvement curves and shore-charging infrastructure deployment rates throughout the forecast period. Segmentation modeling spanned propulsion architecture, vessel tonnage class, drive technology tier, and regional subsidy regime. CAGRs derived from logistic diffusion curves fitted to historical hybrid adoption patterns in Norwegian and German ferry fleets, with cross-validation against Japanese METI pilot program expansion trajectories.
Practitioners should monitor lithium-ion cell raw material price indices and IMO IGF Code amendment ratification timelines for early signals of forecast revision. Assumptions reflect current regulatory enforcement intensity and state subsidy commitment levels. Quarterly review of Norwegian Maritime Authority zero-emission certification throughput and German port authority shore-power connection standards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
India Aluminium Fishing Boat Market