
 Fishing Boat Market | 2026-2036
Fishing Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Fishing Boat Market Analysis
The EU Green Deal is consolidating demand around low-emission propulsion systems across European commercial fleets. Viking leverages its deep-hull engineering heritage to dominate North Atlantic longliner specifications. Boston Whaler sustains brand strength through unsinkable hull construction and extensive dealer networks. Scout differentiates with stepped-hull designs that optimize fuel efficiency in coastal sportfishing segments.
A fishing boat is a purpose-built marine vessel engineered with hull lengths from fifteen to over one hundred feet, constructed through resin-infusion molding, welded aluminum extrusion, or steel plate assembly, designed to withstand corrosive saltwater environments while providing stable working platforms for fish capture, storage, and crew operations. Commercial trawlers and longliners represent the mature volume core where replacement cycles drive steady demand, while recreational fiberglass outboard models in the twenty-five to forty-foot range capture the fastest-growing margin pool as leisure fishing participation expands. Aluminum hull construction anchors freshwater and nearshore commercial segments where durability and repairability outweigh premium finishing requirements.
The International Maritime Organization's MARPOL Annex VI standards, the EPA's marine engine emission regulations, and the EU F-Gas Regulation collectively mandate cleaner combustion and refrigerant management, forcing hull builders to redesign engine compartments and integrate alternative propulsion architectures. Japan's METI and South Korea's MFDS enforce parallel domestic standards that restrict market access for non-compliant imports. Stakeholders must monitor regulatory divergence between major fishing nations when allocating R&D budgets and certifying hull platforms for multi-jurisdiction deployment.
Market Dynamics
The fishing boat market pivots on regulatory compression of marine engine emissions, forcing hull builders to redesign propulsion architectures and certify platforms across multiple jurisdictions simultaneously.
Growth Catalysts
- EU Green Deal mandates:The framework consolidates fleet procurement around low-emission propulsion systems, accelerating replacement cycles in North Atlantic commercial operations.
- Fiberglass resin-infusion advances:Automated molding processes reduce hull weight while maintaining structural integrity, enabling longer range with smaller powerplants.
- Southeast Asian fleet modernization:Indonesian, Vietnamese, and Philippine government tenders specify emission-compliant engines, creating concentrated demand for new hull deliveries.
Market Restraints
- Aluminum sheet volatility:Nearshore commercial builders face margin pressure from fluctuating metal input costs that resist pass-through pricing.
- Engine supply concentration:Outboard and inboard marine propulsion systems depend on a limited supplier base in Japan and South Korea, creating delivery bottlenecks.
- Dual-certification burden:Builders targeting both EU and US markets must satisfy divergent EPA and EU F-Gas refrigerant management standards, extending development timelines.
Strategic Opportunities
- Hybrid-electric coastal segments:Twenty-five to forty-foot recreational fiberglass models present white space for battery-assisted propulsion in leisure fishing expansion zones.
- Indonesia archipelago logistics:Distributed island geography favors smaller, fuel-efficient hulls with shallow draft capabilities for inter-island fish transport.
- Japan METI efficiency incentives:Domestic subsidy programs for low-emission vessel retrofits create aftermarket demand for repowering kits and hull modifications.
Industry Challenges
- Marine electrician skill scarcity:Electrified propulsion architectures require technicians trained in high-voltage systems, a capability gap acute in Southeast Asian shipyards.
- Legacy hull certification delays:Modified designs for alternative fuel compatibility trigger extended approval processes with classification societies.
- Refrigerant system integration:Hold cooling retrofits for MARPOL Annex VI compliance demand coordination between hull builders and specialized HVAC subcontractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishing Boat Market |
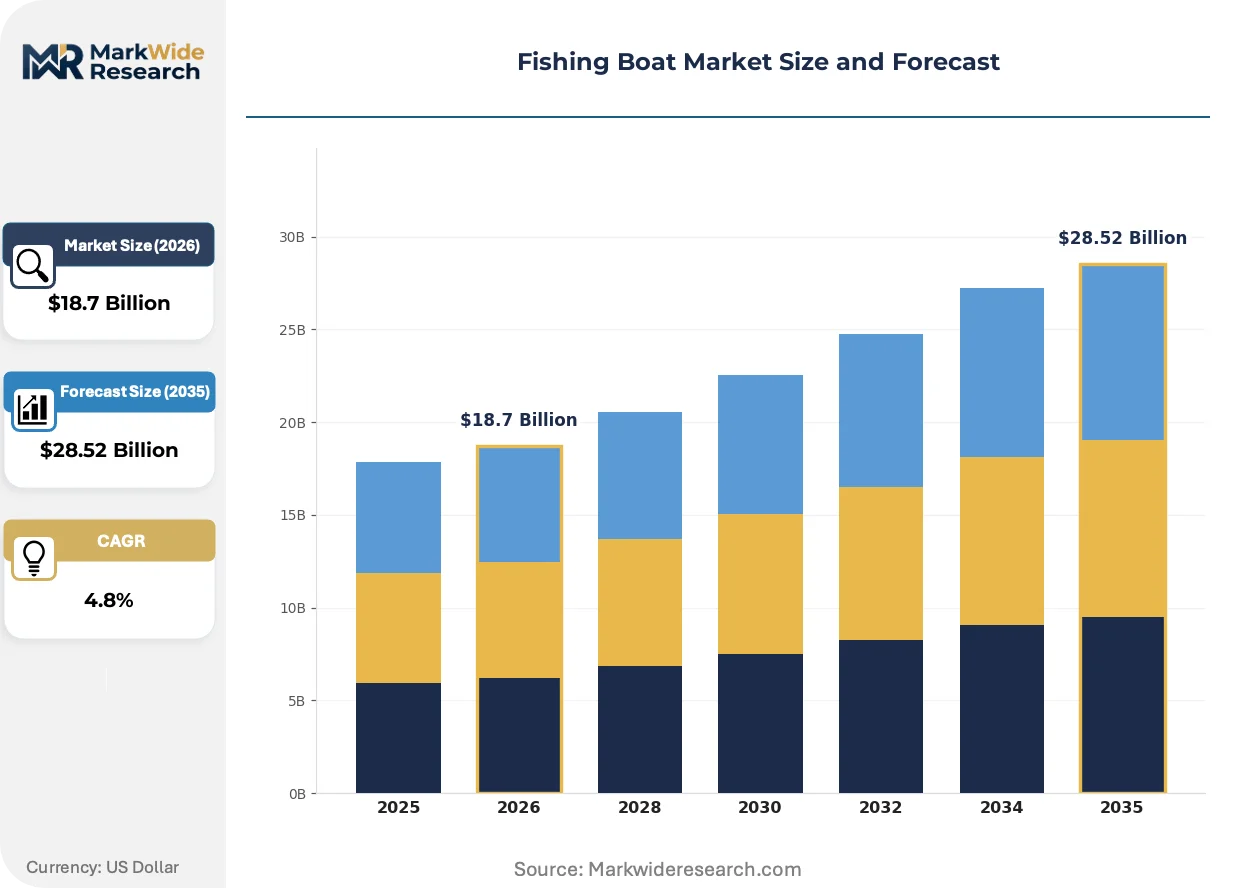
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Recreational, Commercial, Trawlers, Longliners Material: Fiberglass, Aluminum, Steel, Wood Size: Small, Medium, Large, Extra-Large Engine Type: Outboard, Inboard, Electric, Hybrid |
| Companies Covered | Invincible, Scout, Boston Whaler, Sea Hunt, Viking, Everglades, NorthCoast, HCB Yachts, Grady-White, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishing Boat Market Emerging Trajectories
Propulsion electrification and digital hull monitoring are compressing traditional replacement cycles while opening margin pools in aftermarket service and data analytics.
Battery-assisted hybrid systems are electrifying coastal commercial operations by enabling diesel engines to run at optimal load points with electric boost for maneuvering. Indonesian and Vietnamese fleet operators are piloting these configurations in forty-foot trawler classes. The technology is electrifying competitive positioning by allowing smaller builders to compete on total cost of ownership against established diesel specialists.
The EU F-Gas Regulation tightens refrigerant containment standards for onboard fish hold cooling systems, mandating leak detection and recovery infrastructure. Hull builders must redesign engine compartments to accommodate larger condenser units and piping runs. Longliner specifications in Spain and Portugal show the earliest compliance-driven specification changes, with owners accepting reduced hold volume for regulatory assurance.
Leisure buyers now specify factory-integrated electronics packages over aftermarket installation, compressing the traditional dealer customization model. Scout and Boston Whaler respond with pre-wired hulls accepting multi-brand sonar and navigation systems. This preference shift concentrates most visibly in Florida and Gulf Coast markets where tournament fishing participation drives equipment sophistication expectations.
Fishing Boat Market Segmentation
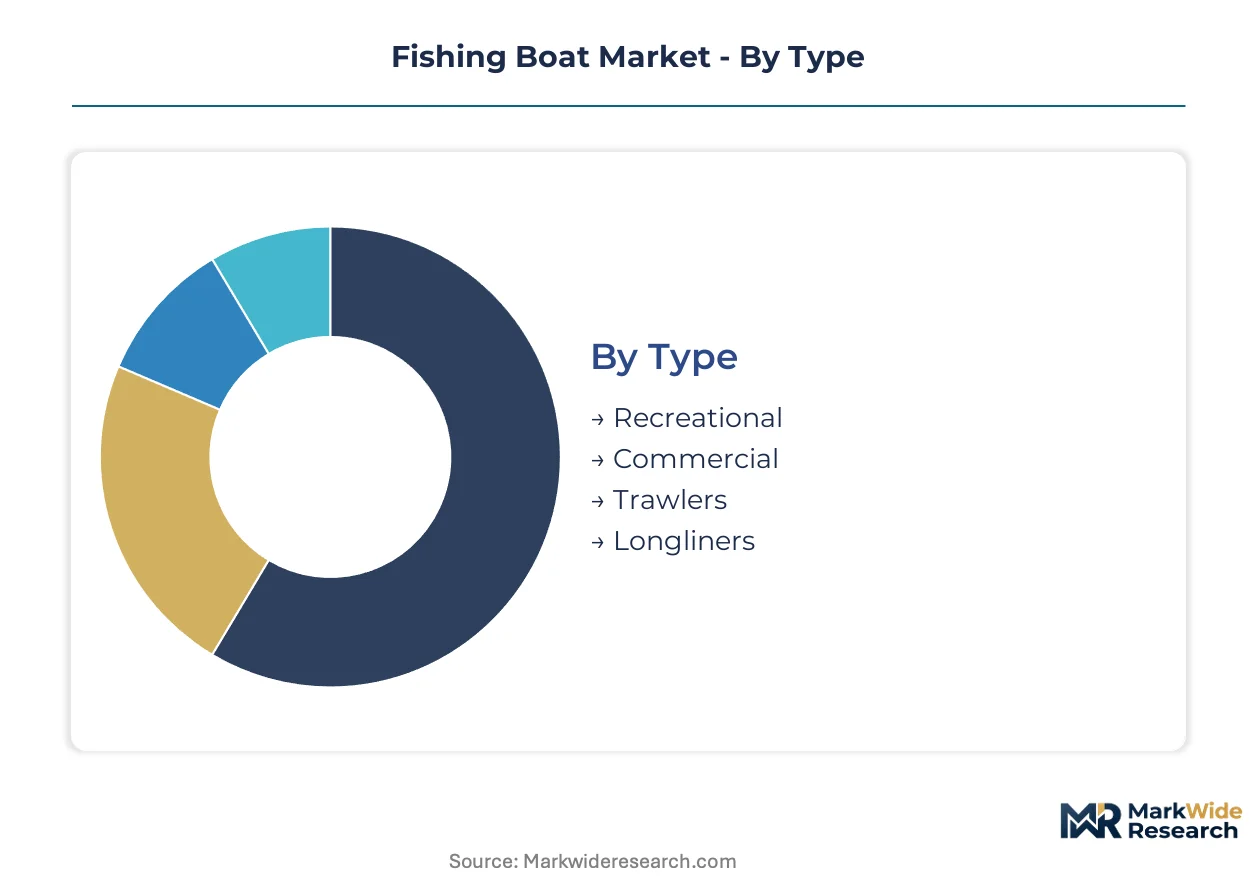
Propulsion architecture and hull material choices determine certification pathways and total cost of ownership for fleet operators navigating divergent regulatory regimes. Segmentation clarity enables suppliers to align R&D spend with replacement cycle timing across commercial and recreational buyer pools.
Type:
Application intensity and revenue per vessel-day drive procurement priorities across owner-operator segments.
- Commercial:High-utilization vessels engineered for continuous operation in corrosive saltwater environments, with reinforced working decks and integrated catch handling systems. Demand concentrates in Indonesian and Vietnamese government tender programs where emission-compliant engine specifications trigger fleet-wide replacement. Volume sits with Commercial; growth tilts toward Recreational.
- Recreational:Fiberglass outboard configurations in the twenty-five to forty-foot range optimized for leisure fishing participation and tournament competition. Florida and Gulf Coast markets show strongest specification intensity for factory-integrated electronics packages.
- Trawlers:Bottom-towing hull designs with reinforced stern structures for net deployment and retrieval in sustained commercial operations.
- Longliners:Specialized deck layouts accommodating mile-long mainlines with multiple branch lines for pelagic species targeting.
Commercial hulls dominate installed base; recreational configurations climb fastest as leisure participation expands.
Material:
Corrosion resistance and repairability tradeoffs shape material selection against operating environment severity.
- Fiberglass:Resin-infusion molded hulls achieving weight reduction through automated fiber placement while maintaining structural integrity for extended range operations. Southeast Asian fleet modernization programs specify fiberglass construction for emission-compliant replacements in Indonesia, Vietnam, and the Philippines.
- Aluminum:Welded extrusion construction prioritizing durability and field repairability in freshwater and nearshore commercial segments. Margin pressure from metal input cost volatility constrains pricing flexibility for nearshore builders.
- Steel:Plate assembly configurations for large-format hulls requiring maximum structural load capacity in heavy-weather operations.
- Wood:Traditional plank-on-frame construction persisting in heritage vessel restoration and select artisanal fishing communities.
Steel commands the largest hull formats; fiberglass gains share fastest through resin-infusion automation advances.
Size:
Draft requirements and payload economics determine dimensional specifications against harbor infrastructure constraints.
- Small:Shallow-draft hulls under twenty-five feet optimized for inter-island logistics in Indonesia's distributed archipelago geography. Battery-assisted hybrid propulsion pilots concentrate in this segment for coastal commercial operators.
- Medium:Twenty-five to forty-foot configurations capturing recreational margin expansion with stepped-hull designs optimizing fuel efficiency.
- Large:Extended-range hulls accommodating multi-day operations with integrated hold cooling and crew quarters.
- Extra-Large:Industrial-scale vessels exceeding one hundred feet for distant-water fleet operations with factory-level processing capabilities.
Medium hulls concentrate recreational value; small formats expand most quickly through archipelago logistics demand.
Engine Type:
Emission compliance trajectories and fuel infrastructure availability determine propulsion architecture selection.
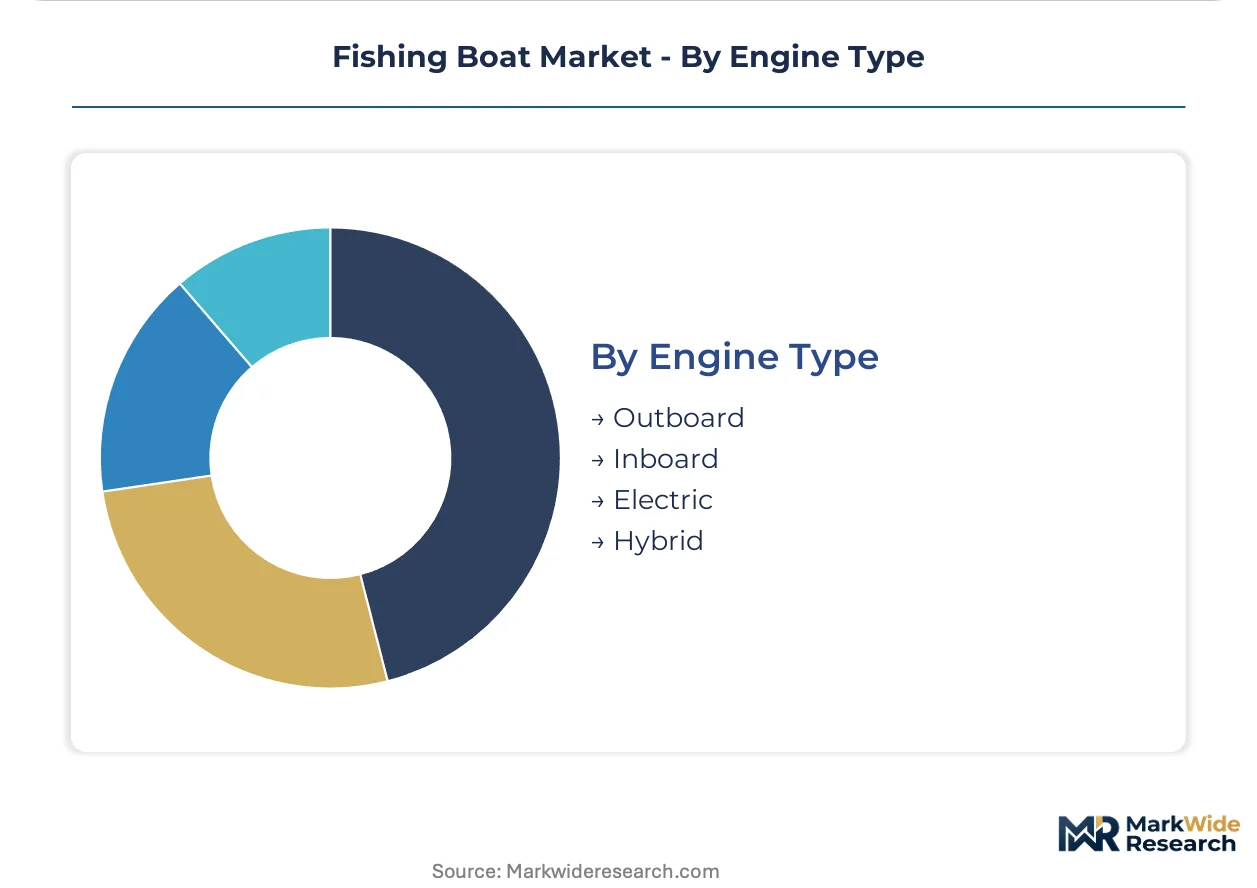
- Outboard:Portable power systems enabling rapid field replacement and shallow draft operation for recreational and nearshore commercial applications. Scout and Boston Whaler integrate pre-wired hull architectures accepting multi-brand configurations.
- Hybrid:Battery-assisted diesel systems enabling optimal load-point operation with electric boost for maneuvering. Japanese METI subsidy programs for low-emission retrofits create aftermarket demand for repowering kits.
- Inboard:Fixed installations delivering maximum power density for large-format commercial hulls with dedicated engine compartments.
- Electric:Pure battery propulsion emerging in restricted-waterway applications with shore-charging infrastructure.
Outboard dominates recreational installation; hybrid architectures gain fastest through EU Green Deal fleet procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Bedford anchors North Atlantic commercial fishing activity, with concentrated hull fabrication and longliner specification activity across Massachusetts and Maine harbors. Fleet operators here face simultaneous EPA marine engine emission mandates and EU F-Gas refrigerant compliance for catch hold cooling. This dual-jurisdiction pressure shapes procurement patterns across the regional builder base.
United States
Florida and Gulf Coast markets drive recreational fiberglass demand through tournament fishing participation and factory-integrated electronics specifications. EPA marine engine regulations force repowering decisions across aging commercial fleets. Scout and Boston Whaler anchor dealer networks in Miami-Dade and Tampa Bay corridors.
Indonesia
Archipelago logistics favor shallow-draft small hulls for inter-island fish transport and coastal commercial operations. Government tenders specify emission-compliant engines for fleet modernization programs. Surabaya and Makassar shipyards concentrate fiberglass resin-infusion capacity for domestic and export orders.
Vietnam
Government procurement programs accelerate replacement cycles for nearshore commercial trawler fleets. METI-aligned efficiency incentives from Japanese development cooperation create aftermarket retrofit demand. Da Nang and Hai Phong fabrication clusters specialize in aluminum extrusion hulls for durability-focused operators.
Japan
METI subsidy programs for low-emission vessel retrofits generate aftermarket demand for repowering kits and hull modifications. Domestic fleet operators pilot battery-assisted hybrid configurations in forty-foot trawler classes. Nagasaki and Shimonoseki maintain heritage steel-plate assembly capabilities for distant-water longliners.
Spain
EU F-Gas Regulation drives earliest compliance-driven specification changes for onboard fish hold cooling systems. Spanish and Portuguese longliner owners accept reduced hold volume for regulatory assurance. Vigo and Marin shipyards integrate leak detection and recovery infrastructure into new hull deliveries.
Fishing Boat Market Vendor Landscape
Premium-margin players sit above commodity-margin players across hull material specialization and electronics integration depth. The vendor base organizes around three strategic archetypes: heritage deep-hull engineers, resin-infusion automation specialists, and stepped-hull fuel efficiency optimizers. Consolidation pressure concentrates among recreational fiberglass builders where dealer network scale determines geographic reach. Dominant competitive moves include vertical integration into engine compartment design and strategic partnerships with marine electronics OEMs.
Within the heritage engineering tier, Viking exemplifies North Atlantic longliner specification dominance through multi-generational hull architecture refinement. Scout and Boston Whaler occupy distinct positions in recreational coastal segments—Scout through stepped-hull fuel efficiency optimization, Boston Whaler through unsinkable hull construction claims and extensive dealer infrastructure. These three entities represent contrasting archetypes rather than direct substitutes, with each anchoring margin pools defined by buyer risk tolerance and operating environment severity.
| Leading Market Players |
|---|
| Invincible |
| Scout |
| Boston Whaler |
| Sea Hunt |
| Viking |
| Everglades |
| NorthCoast |
| HCB Yachts |
| Grady-White |
| Others |
Supply Flow & Price Mechanics
Aluminum sheet volatility cascades through nearshore commercial hull pricing tiers, compressing margins for Indonesian and Vietnamese builders while fiberglass resin-infusion automation in Surabaya and Makassar insulates premium segments from metal input cost swings. Buyers in government tender programs absorb compliance-driven premiums for emission-certified engine compartments, separating procurement pools by certification burden rather than hull size alone.
Pricing Analysis
Total-cost-of-ownership anchoring dominates fleet procurement decisions, with Indonesian and Vietnamese operators calculating fuel efficiency gains and maintenance intervals against upfront hull premiums. Price differentiation separates EU F-Gas compliant longliners with integrated leak detection from standard configurations in Southeast Asian nearshore fleets. Pricing pressure stems from aluminum input cost volatility that resists pass-through to budget-constrained owner-operators. Small-hull archipelago logistics buyers show highest price sensitivity; North Atlantic commercial fleets demonstrate lowest sensitivity due to regulatory compliance mandates and replacement cycle urgency.
Supply Chain Analysis
Marine electrician skill scarcity in Indonesian and Vietnamese shipyards constrains output expansion for electrified propulsion architectures, forcing hull builders to import technicians from Japan and South Korea. Manufacturing concentrates in Indonesia, Vietnam, and the Philippines for fiberglass resin-infusion capacity; Japan and South Korea anchor engine and hybrid system production. Raw material dependencies include aluminum extrusion stock, fiberglass roving, and marine-grade resin formulations. Single-source vulnerability sits with outboard and inboard propulsion systems from concentrated Japanese and Korean suppliers. Distribution runs through government tender channels in Southeast Asia and dealer networks in North American recreational markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fishing boat market operates as a cost-of-compliance arena where MARPOL Annex VI and EU F-Gas standards erect regulatory moats favoring builders with pre-certified hull platforms and established classification society relationships.
For Market Incumbents: Lock in fleet replacement cycles by pre-certifying hybrid-electric architectures across multiple jurisdictions simultaneously, insulating procurement decisions from regulatory divergence delays. Deepen backward integration into engine compartment design to capture repowering retrofit demand from Japan's METI subsidy programs. The threat of marine electrician skill scarcity in Southeast Asian shipyards favors incumbents with established training pipelines and technician retention programs. For New Entrants and Emerging Players: Battery-assisted hybrid configurations in twenty-five to forty-foot recreational fiberglass segments offer technology-first entry points where established diesel specialists lack electrification expertise. Target Florida and Gulf Coast tournament fishing markets with factory-integrated electronics packages that compress dealer customization timelines. A direct-to-operator digital specification tool bypasses traditional dealer networks and captures leisure buyers prioritizing equipment sophistication. For Investors and Strategic Acquirers: Distressed-cycle entries favor resin-infusion automation specialists with Surabaya or Makassar fabrication footprints and established Indonesian government tender relationships. Long-term viability across the projection horizon rests on regulatory certification assets rather than pure manufacturing scale. Watch for METI subsidy program expansion or contraction as the inflection signal for aftermarket repowering demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Certification | Pre-cleared EU F-Gas and MARPOL Annex VI compliance accelerates fleet replacement procurement decisions. |
| Resin-Infusion Automation Scale-Up | Surabaya and Makassar capacity expansion captures Indonesian and Vietnamese government tender volume concentration. |
| Marine Electrician Training Partnership | Joint programs with Japanese and Korean technical institutes address Southeast Asian shipyard skill scarcity. |
| Factory-Integrated Electronics Packaging | Pre-wired hull architectures for multi-brand sonar systems penetrate Florida and Gulf Coast tournament markets. |
| Backward Integration into Engine Compartments | In-house compartment design captures Japan METI-subsidized retrofit demand and reduces HVAC subcontractor coordination friction. |
Methodological Framework
Trade customs databases, classification society certification registries, and marine engine manufacturer technical filings formed the secondary backbone for hull production volume and propulsion system deployment tracking. Primary interviews with fleet operations managers at Indonesian and Vietnamese government tender programs, shipyard production directors in Surabaya and Makassar, marine electronics integration specialists, and classification society surveyors validated secondary estimates. Bottom-up hull delivery counts triangulated against top-down fleet replacement cycle modeling.
Historical trendline analysis of commercial fleet age distributions and recreational participation rates established baseline replacement demand across the projection horizon. Segmentation modeling incorporated propulsion architecture, hull material, size classification, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of tender award volumes and dealer shipment data. Industry-specific forecast inputs included EPA marine engine compliance timelines and EU F-Gas refrigerant phase-down schedules.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to MARPOL Annex VI, abrupt aluminum tariff adjustments, and breakthrough solid-state battery commercialization for marine propulsion. Forecasts reflect stated policy trajectories and announced fleet modernization programs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Marine Reciprocating Engine Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Airboats Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Yacht Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Outboard Engines Market