
 Fuel Injection Systems Market | 2026-2036
Fuel Injection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Injection Systems Market Intelligence
Software calibration services for direct injection systems is tilting the market's profit structure away from purely hardware sales. Robert Bosch GmbH leverages its extensive electronics expertise to lead in this integrated systems space. Continental AG competes through its advanced sensor and control unit offerings. Meanwhile, Denso Corporation differentiates with its focus on high-precision gasoline direct injection (GDI) components for Japanese automakers.
A fuel injection system delivers pressurized fuel into an internal combustion engine's cylinders or intake manifold. These systems atomize fuel under high pressure, sometimes exceeding 2,500 bar, to optimize combustion for efficiency and power. Direct injection technology now dominates new vehicle production, especially within the high-volume passenger cars segment. While passenger cars drive volume, the commercial vehicles application provides higher-margin opportunities for suppliers of robust common rail systems.
Regulatory frameworks are a primary market force, with the US EPA's emissions targets, the EU Green Deal's mandates, and China's GB standards setting stringent performance floors. These rules compel automakers to adopt advanced direct injection and common rail systems to meet tightening pollution limits. The key decision for component suppliers is how to allocate R&D between optimizing internal combustion engine efficiency and pivoting capabilities toward future powertrain technologies.
Market Dynamics
The market's central dynamic is the tension between stringent global emissions regulations, which demand more sophisticated internal combustion engine technologies, and the automotive industry's long-term strategic pivot towards full electrification, which threatens the system's entire existence.
Growth Catalysts
- Stringent Emissions Mandates:The EU's Euro 7 standards and similar regulations from the US EPA compel automakers to adopt advanced direct injection and common rail systems to meet tightening limits on NOx and particulate matter.
- Vehicle Production in China:China's massive automotive manufacturing sector, governed by its own GB standards for fuel economy, creates immense volume demand for efficient GDI systems in passenger cars.
- Heavy-Duty Sector Demand:The commercial vehicles segment requires high-pressure common rail systems to improve fuel efficiency, reduce operational costs, and comply with emissions rules for long-haul and vocational trucks.
Market Restraints
- Electrification Threat:The accelerating industry-wide transition to battery electric vehicles (BEVs) represents a direct substitution threat, as EVs do not require any form of fuel injection system, capping the market's long-term lifecycle.
- High Component Cost:Manufacturing high-pressure direct injection components requires precision engineering and specialized materials to withstand extreme pressures, resulting in a high per-unit cost passed on to automakers and consumers.
- Regulatory Divergence:Inconsistent timelines and technical requirements between major regulatory bodies like the US EPA, Europe's KBA, and China's MEE create complexity and increase R&D costs for suppliers developing global platforms.
Strategic Opportunities
- Software and Calibration Services:Offering standalone software calibration services for direct injection systems creates a high-margin revenue stream, particularly in the performance aftermarket and for automakers seeking to optimize specific engine variants.
- Hybrid Powertrain Integration:There is a significant opportunity in developing fuel injection systems specifically designed for hybrid-electric vehicles, optimizing engine performance for frequent start-stop cycles and seamless power blending.
- Aftermarket in Developing Economies:As emissions standards are gradually introduced in markets across Southeast Asia and Latin America, a substantial opportunity emerges for aftermarket conversion kits and replacement parts for an aging vehicle fleet.
Industry Challenges
- R&D Capital Allocation:Component suppliers face the difficult strategic challenge of allocating investment between incrementally improving ICE efficiency and funding a fundamental pivot toward developing components for future electric powertrains.
- Skilled Engineering Scarcity:A shortage of software engineers with expertise in complex engine control unit (ECU) calibration is a major operational bottleneck, as talent is increasingly attracted to the EV and autonomous driving sectors.
- System Integration Complexity:Ensuring flawless integration of advanced fuel injection systems with sophisticated exhaust after-treatment technologies is critical for passing stringent real-world driving emissions (RDE) tests.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Injection Systems Market |
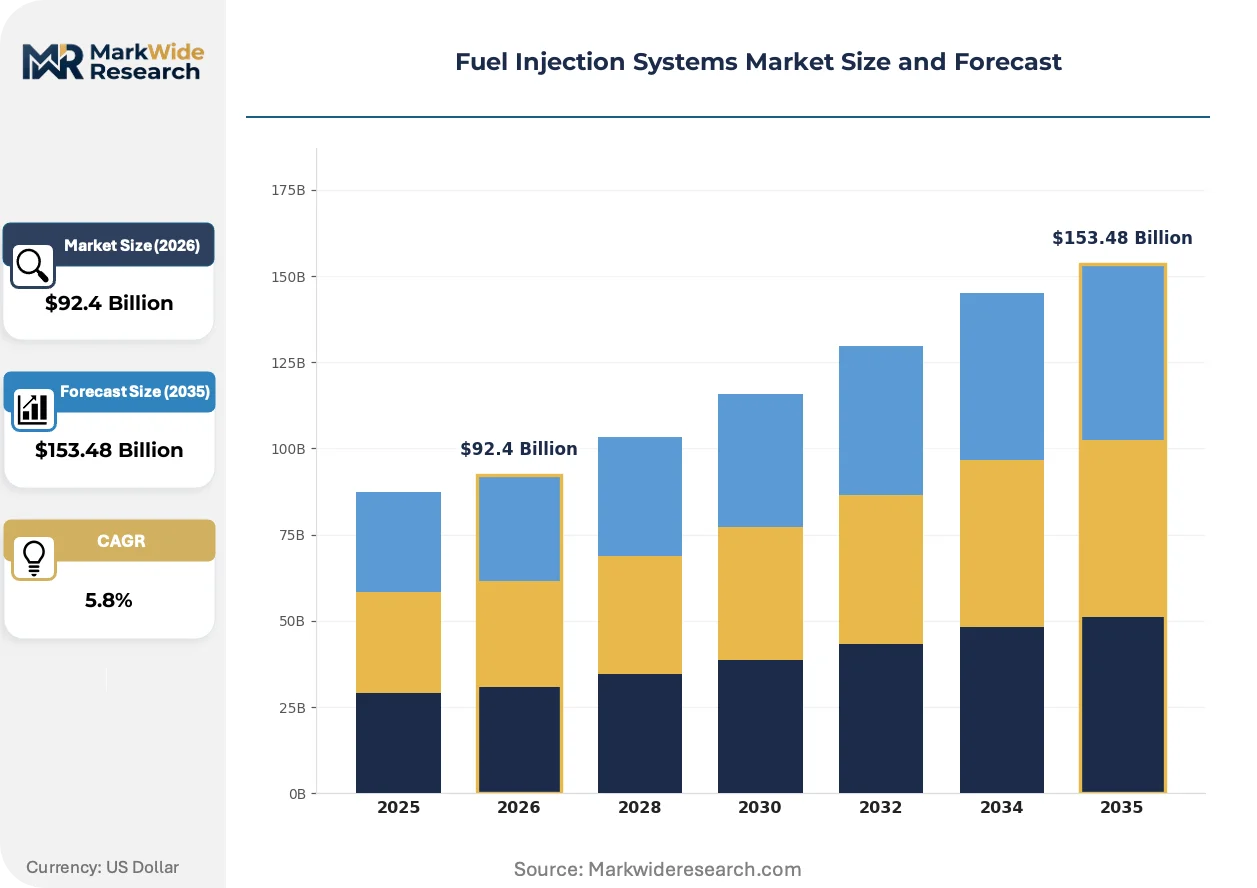
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Injectors, Diesel Injectors, Common Rail Systems, Piezoelectric Injectors End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Electronic Fuel Injection, Multi-Point Fuel Injection, Direct Injection, Sequential Fuel Injection Application: Passenger Cars, Commercial Vehicles, Heavy-Duty Vehicles, Motorcycles |
| Companies Covered | BorgWarner Inc., Hitachi Astemo, Ltd., Robert Bosch GmbH, Cummins Inc., Keihin Corporation, Denso Corporation, Marelli Holdings Co., Ltd., Stanadyne LLC, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Injection Systems Market Strategic Shifts & Innovations
The market is evolving from a focus on purely mechanical hardware to integrated electro-mechanical systems. Software calibration and electronic controls now define performance, efficiency, and regulatory compliance, creating new value streams beyond the physical injector.
Gasoline direct injection (GDI) technology delivers a precisely metered, high-pressure fuel spray directly into the combustion chamber. Automakers across the passenger car segment are rapidly adopting GDI to achieve fuel economy and power density targets. This technology is hybridizing with mild-hybrid vehicle systems, where its precise fuel control is essential for managing engine start-stop cycles and providing smooth torque-fill from the electric motor.
Regulatory frameworks like the US EPA's stringent emissions standards for heavy-duty vehicles are a primary market force. These rules mandate significant reductions in pollutants, compelling engine manufacturers to enhance combustion efficiency. The commercial vehicle segment is most affected, accelerating its adoption of advanced common rail systems that feature higher injection pressures and more sophisticated electronic rate-shaping capabilities.
A notable shift in demand is the unbundling of software services from hardware sales. This move away from procuring standalone components toward integrated system solutions, including custom ECU calibration, is disrupting the traditional supplier-OEM relationship. The trend is most visible in Europe, where automakers collaborate with specialists to fine-tune engine maps for specific models to comply with complex on-road emissions testing protocols.
Fuel Injection Systems Market Segmentation
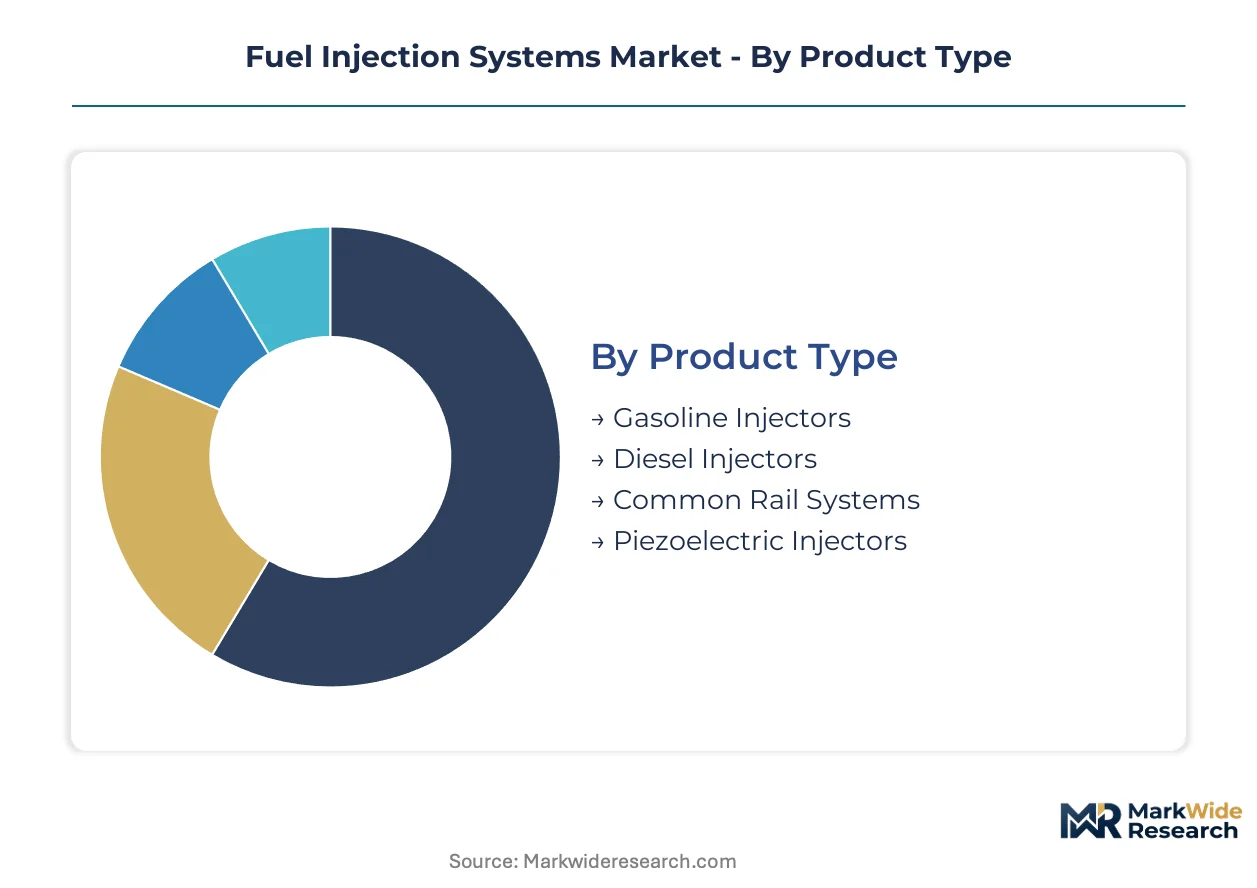
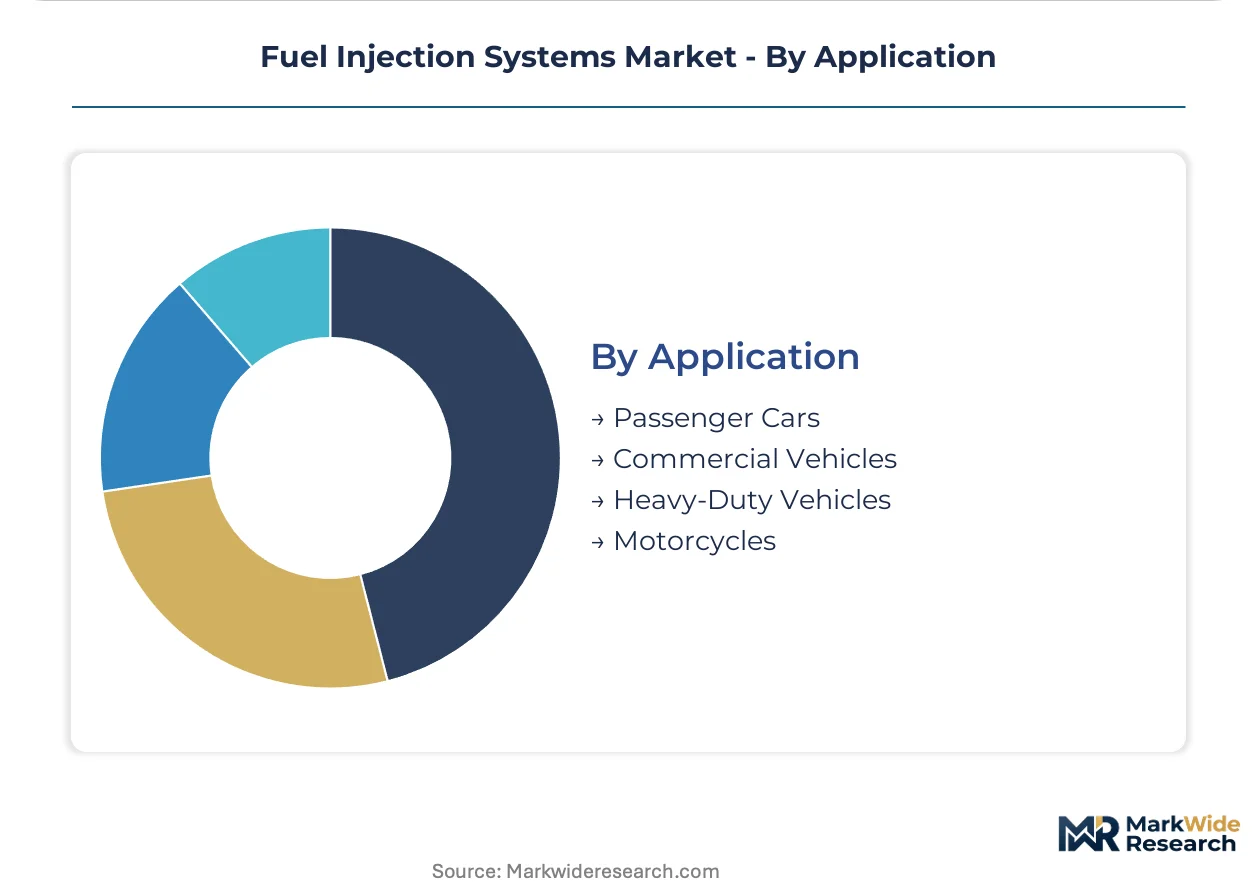
The Fuel Injection Systems Market segmentation provides a granular view of component demand and technological adoption across diverse vehicle platforms. Understanding these distinct segments is crucial for suppliers to align their product development and market strategies with evolving industry requirements and regulatory pressures.
Product Type:
The product type segmentation reveals differing investment cycles, with some components experiencing rapid innovation while others maintain longer lifespans.
- Gasoline Injectors:Meter and atomize gasoline into the engine's intake manifold or directly into the combustion chamber, supporting efficient combustion.
- Diesel Injectors:Designed to withstand higher pressures and inject diesel fuel, crucial for compression-ignition engines in various applications.
- Common Rail Systems:Deliver highly pressurized fuel to a common rail, which then distributes it to individual injectors, enabling precise control over injection timing and quantity. Demand concentrates in commercial vehicles due to stringent emissions regulations requiring enhanced combustion efficiency.
- Piezoelectric Injectors:Utilize piezoelectric actuators for extremely rapid and precise opening and closing, allowing for multiple injections per combustion cycle. Automakers in Europe integrate these for superior fuel atomization and reduced particulate matter emissions.
Gasoline Injectors anchor the volume base while Piezoelectric Injectors gain share at the steepest rate.
End User:
The market's end-user segments illustrate distinct procurement behaviors and margin structures across the value chain.
- OEMs:Original Equipment Manufacturers procure fuel injection systems directly for integration into new vehicle production lines. Demand is influenced by China's expansive vehicle manufacturing base and domestic market growth.
- Aftermarket Providers:Supply replacement parts and upgrade kits for vehicles already in operation, catering to repair, maintenance, and performance enhancement. Developing economies in Southeast Asia provide significant opportunity for these services.
- Vehicle Assemblers:Integrate various components, including fuel injection systems, into the final vehicle product for diverse markets.
- Tier-1 Suppliers:Develop and manufacture complex sub-systems and components, often supplying directly to OEMs with integrated solutions.
OEMs represent the largest purchasing block, with Aftermarket Providers exhibiting expanding demand for replacement parts.
Technology:
Technology segmentation highlights the varying maturity levels of fuel injection systems, from established designs to cutting-edge innovations.
- Electronic Fuel Injection:Utilizes electronic control units to precisely meter fuel delivery, replacing older mechanical carburetor systems for better performance.
- Multi-Point Fuel Injection:Delivers fuel to the intake port of each cylinder, improving fuel distribution and efficiency compared to single-point systems.
- Direct Injection:Sprays fuel directly into the combustion chamber, allowing for more precise fuel delivery and higher compression ratios. This technology dominates new passenger car production to meet fuel economy targets.
- Sequential Fuel Injection:Electronically controls each injector independently, timing fuel delivery to each cylinder's intake stroke. This system optimizes combustion efficiency and reduces emissions in modern gasoline engines.
Direct Injection technology drives efficiency improvements across new vehicle platforms, while Electronic Fuel Injection remains foundational for many engine designs.
Application:
Application segments delineate where the primary demand volume originates and where specialized performance requirements dictate component design.
- Passenger Cars:Represent the largest volume segment, driven by global vehicle production and the widespread adoption of direct injection for fuel efficiency. China's domestic market significantly influences demand in this segment.
- Commercial Vehicles:Encompass light and medium-duty trucks and vans, utilizing fuel injection systems tailored for diverse operational demands and payload capacities.
- Heavy-Duty Vehicles:Require robust, high-pressure common rail systems for large engines, prioritizing durability, fuel economy, and compliance with strict emissions standards like the US EPA's targets.
- Motorcycles:Integrate compact fuel injection systems to enhance performance, fuel efficiency, and emissions compliance in two-wheeled vehicles across various markets.
Passenger Cars continue to generate the highest unit volumes, while Heavy-Duty Vehicles offer higher-margin opportunities for specialized systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fuel injection systems varies significantly across global markets, reflecting diverse priorities. Developing economies often exhibit higher price sensitivity, focusing on robust and cost-efficient solutions. Conversely, mature automotive markets prioritize advanced, high-precision systems to meet stringent environmental regulations and performance demands.
China
China's expansive vehicle production fuels significant demand for efficient gasoline direct injection (GDI) systems. The country's GB standards for fuel economy compel automakers to integrate advanced fuel delivery technologies. The Yangtze River Delta, particularly around Shanghai, concentrates on scaling GDI component production for high-volume passenger cars.
Germany
Germany's automotive industry drives demand for sophisticated fuel injection systems in premium passenger cars. The EU's Euro 7 standards compel manufacturers to adopt advanced direct injection technologies. The Stuttgart region, a hub for automotive engineering, concentrates on developing piezoelectric injectors and complex engine control unit calibration services.
United States
The United States market sees robust demand from its heavy-duty vehicle sector and light truck segments. The US EPA's emissions targets mandate significant reductions in pollutants, accelerating adoption of advanced common rail systems. Around Detroit, Michigan, automotive suppliers integrate high-pressure direct injection systems for both gasoline and diesel engines.
Japan
Japan's automotive sector emphasizes high-precision gasoline direct injection components, particularly for its strong hybrid vehicle market. METI policies promoting fuel efficiency encourage continuous innovation in fuel delivery. The Chubu region, centered around Nagoya, serves as a critical hub for Denso and other suppliers specializing in advanced GDI systems.
India
India's expanding passenger car market and commercial vehicle sector generate increasing demand for fuel injection systems. The country's evolving BIS standards drive the adoption of more efficient engine technologies. Around Pune in Maharashtra, a growing automotive manufacturing cluster, suppliers focus on cost-effective yet compliant fuel injection solutions.
Fuel Injection Systems Market Key Industry Players
Integrated systems providers and specialized component manufacturers split the fuel injection systems market. The competitive landscape features a blend of large, diversified technology conglomerates and focused precision engineering firms. Companies engage in strategic partnerships to co-develop advanced solutions and pursue technology licensing to expand their market reach. Portfolio diversification into software calibration services is a common competitive move.
Within the integrated systems provider archetype, Robert Bosch GmbH, a German-based electronics and engineering firm, exemplifies a broad portfolio approach across various engine types. Continental AG, another German-headquartered company, occupies a position focused on advanced sensor and control unit offerings, leveraging its extensive electronics expertise. Denso Corporation, a Japanese-headquartered specialist, anchors the segment for high-precision gasoline direct injection components, particularly for Asian automakers. These entities represent different strategic vectors within the market, continuously adapting to evolving powertrain demands.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Hitachi Astemo, Ltd. |
| Robert Bosch GmbH |
| Cummins Inc. |
| Keihin Corporation |
| Denso Corporation |
| Marelli Holdings Co., Ltd. |
| Stanadyne LLC |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Underutilized manufacturing capacity in European component plants currently drives both supplier behavior and pricing posture within the fuel injection systems market. This situation compels suppliers to optimize production efficiencies and seek new revenue streams beyond traditional hardware sales.
Pricing Analysis
Aftermarket parts and service contracts represent a significant lifetime value driver for fuel injection system suppliers. The dominant pricing structure remains per-unit transactional for OEM integration, with value-based pricing applied to advanced software calibration services. Price differentiation stems from precision engineering and brand premium, particularly for high-pressure direct injection systems. Pricing softness reflects intense competition for high-volume passenger car contracts, making OEMs the most price-sensitive segment, while heavy-duty vehicle operators prioritize reliability over initial component cost.
Supply Chain Analysis
Single-source vulnerabilities for specialized piezoelectric materials and high-precision machining equipment represent a structural supply chain risk. Geographic supply concentration for core components centers in Germany, Japan, and China, reflecting established automotive manufacturing hubs. Key raw material dependencies include high-grade steel alloys and advanced ceramic composites required for extreme pressure applications. The dominant distribution model for new components runs directly from Tier-1 suppliers to OEMs, while aftermarket providers manage a fragmented network of distributors and service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The increasing consolidation among global automotive OEMs shifts buyer power, compelling fuel injection system suppliers to adapt their strategic focus. This dynamic necessitates innovative approaches to maintain market relevance and profitability.
For Market Incumbents: Build intellectual property moats around advanced software calibration algorithms and high-pressure common rail system designs. This defensive move counters the long-term threat of electrification by extending the viability of optimized internal combustion engines. Invest in R&D for hybrid powertrain integration, leveraging existing expertise to provide seamless engine management solutions for new vehicle architectures.
For New Entrants and Emerging Players: Underpenetration in Southeast Asian commercial vehicle markets offers a strategic entry point for cost-effective fuel injection solutions tailored to regional emissions standards. Target the aftermarket segment in Latin America with robust, easily serviceable replacement parts. A go-to-market angle focusing on durability and simplified maintenance for aging vehicle fleets can capture significant share.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software calibration service providers and specialized aftermarket component manufacturers. Focus on acquiring firms with established platforms in these high-margin areas, particularly those with strong OEM relationships or extensive distribution networks. The signal to watch is the rate of adoption of advanced hybrid vehicle architectures, indicating sustained demand for optimized ICE components.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Engine Control Development | Enhances fuel efficiency and emissions compliance for hybrid powertrains, creating new value streams. |
| High-Pressure Common Rail System Refinement | Meets stringent heavy-duty vehicle emissions targets while improving fuel economy for commercial fleets. |
| Regional Aftermarket Expansion (Southeast Asia) | Captures demand for replacement parts in developing economies with evolving emissions regulations. |
| Precision GDI Component Miniaturization | Enables integration into compact hybrid vehicle architectures, optimizing space and performance. |
| Strategic Partnership for Hybrid Integration | Accelerates development of fuel injection systems optimized for frequent engine start-stop cycles. |
Research Approach
A spread of perspectives from OEM procurement heads, Tier-1 R&D directors, aftermarket distributors, and regulatory compliance officers converged on the working assumptions for this market analysis. This primary research was triangulated with secondary validation from vehicle production databases, emissions regulation reports, and company financial filings, ensuring a comprehensive view. Both bottom-up and top-down approaches were applied to validate market sizing and growth projections.
Demand-supply balance modeling informed the forecast framework across the analysis window, projecting market evolution without specific annual targets. Segmentation dimensions modeled included product type, end user, technology, application, and regional regulatory compliance tiers. Compound annual growth rates were derived from historical data trends and projected technological adoption curves. New vehicle production volumes and evolving emissions regulation timelines served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major EV manufacturers would shift outcomes, particularly regarding internal combustion engine development priorities. This study's projections reflect current regulatory trajectories and technological development pipelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South America Internal Combustion Engines Market
Powertrain
Internal Combustion Engine Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Variable Displacement Compressor Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Clutch Friction Plate Market
Powertrain
Transmission Oil Filters Market
Powertrain
Global Powertrain Market
Powertrain
Torque Converter Market
Powertrain
Automotive Camless Engine Market
Powertrain
Tuning Box Market
Powertrain
Automotive Drivetrain Market
Powertrain
Clutch Hub Puller Market
Powertrain
Automotive Crankshaft Market