
 2 Wheeler Fuel Injection System Market | 2026-2036
2 Wheeler Fuel Injection System Market Size, Share, and Industry Trends Forecast 2026-2036
2 Wheeler Fuel Injection System Market Outlook
BS-VI emission norms in India is consolidating the supplier base by mandating oxygen-sensor feedback and precise fuel mapping that only electronically controlled architectures can deliver. Robert Bosch GmbH leverages its powertrain electronics portfolio to anchor high-volume programs for domestic motorcycle OEMs. Continental AG sustains development of compact injector designs tailored to single-cylinder engines below 150cc. Denso Corporation dominates thermal-management-integrated fuel rail assemblies for Asian scooter platforms.
A 2 wheeler fuel injection system meters pressurized fuel through solenoid injectors into intake ports or combustion chambers under ECU-commanded pulse-width modulation, typically operating at 2.5 to 3.5 bar for port injection architectures. Electronic Fuel Injection has displaced carburetors across mass-market motorcycles due to real-time lambda correction and cold-start enrichment precision. Multi-Point Injection configurations command margin pools in performance-oriented segments where cylinder-specific tuning justifies cost premiums. OEMs represent the concentrated demand channel as factory-fit systems align with homologation and warranty requirements.
India's CEA and ARAI enforce Bharat Stage VI compliance, while the European Commission's Euro 5 framework through ECHA-aligned testing protocols eliminates carburetor sales in member states. EPA and NHTSA tailpipe standards in the United States similarly redirect aftermarket replacement demand toward EFI-compatible components. Stakeholders must monitor regulatory phase-in calendars across production clusters to align capacity and calibration service investments with enforcement timelines.
Market Dynamics
Emission mandates across India, Southeast Asia, and Europe are systematically eliminating carburetor architectures, forcing a complete powertrain electronics overhaul that concentrates procurement among ECU-capable Tier 1 suppliers.
Growth Catalysts
- Bharat Stage VI:India's CEA and ARAI enforcement mandates closed-loop lambda control and precise fuel mapping, eliminating carburetor compliance pathways for domestic motorcycle OEMs.
- Euro 5 Framework:The European Commission's ECHA-aligned testing protocols through tailpipe and evaporative emission standards prohibit carburetor sales in member states, redirecting factory-fit demand.
- Single-cylinder engine optimization:Compact injector designs with 2.5 to 3.5 bar port injection architectures enable real-time correction for commuter motorcycles below 150cc displacement.
Market Restraints
- Semiconductor input volatility:ECU microcontroller and sensor chip supply constraints inflate bill-of-material costs for fuel injection system manufacturers.
- Supplier concentration risk:Powertrain electronics capability clusters in Germany and Japan create single-source dependencies for Indian and Indonesian OEMs.
- Carburetor aftermarket persistence:Informal repair networks in rural Vietnam and Indonesia sustain replacement demand for legacy architectures, delaying full EFI penetration.
Strategic Opportunities
- Electric two-wheeler hybridization:Range-extender platforms in India require fuel injection systems optimized for intermittent combustion cycles, creating new calibration service revenue.
- Indonesian scooter premiumization:Thermal-management-integrated fuel rail assemblies capture margin pools in automatic transmission scooters above 125cc displacement.
- PLI scheme alignment:India's production-linked incentive scheme for automotive components subsidizes localized ECU and injector manufacturing capacity.
Industry Challenges
- Embedded software talent scarcity:Fuel mapping and lambda control algorithm development requires powertrain calibration engineers concentrated in Stuttgart and Nagoya.
- Homologation timeline compression:Bharat Stage VI and Euro 5 certification cycles for new motorcycle platforms demand simultaneous emission and OBD compliance validation.
- Legacy mechanic retraining:Diagnostic tool operation and sensor replacement protocols exceed skill levels of informal service networks across Southeast Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2 Wheeler Fuel Injection System Market |
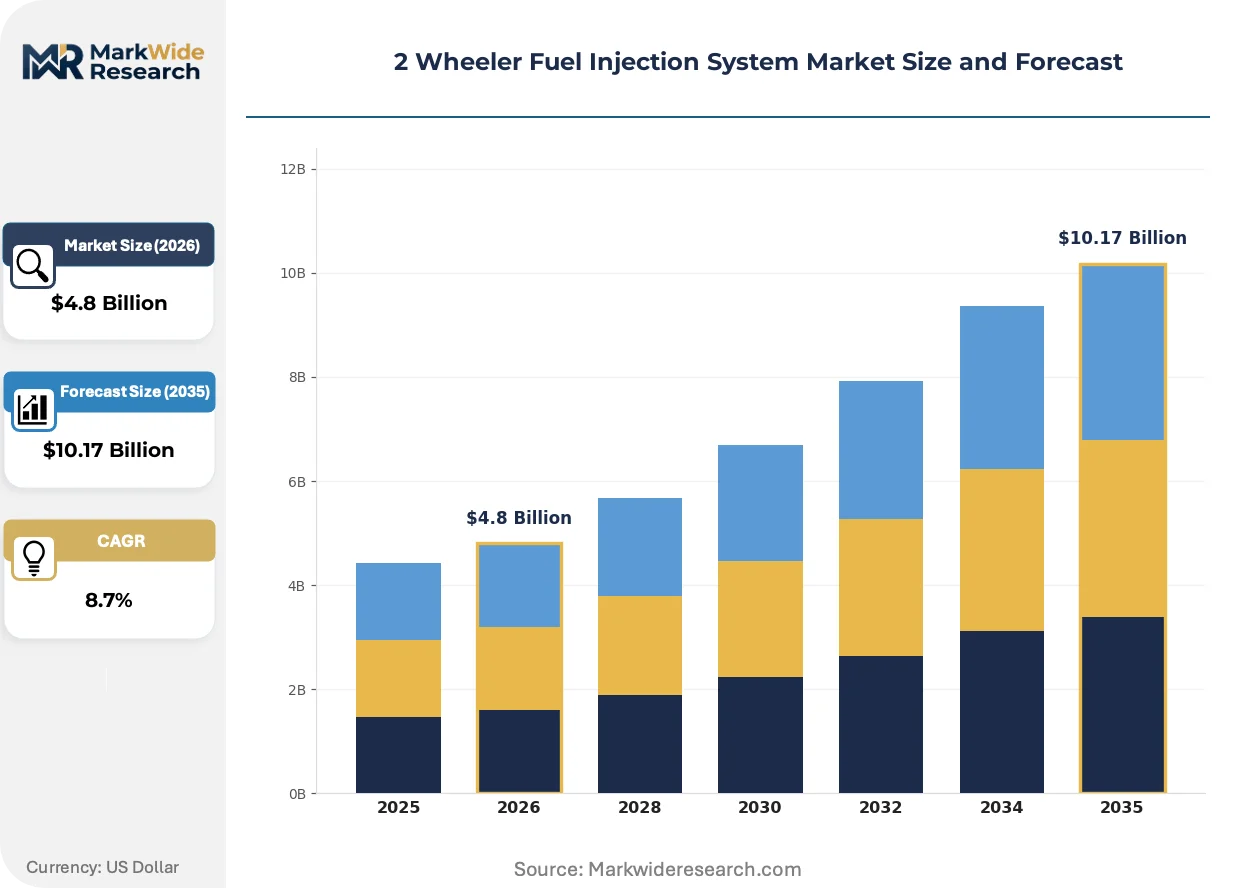
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Fuel Injection, Multi-Point Injection, Direct Injection, Sequential Injection Technology: Closed Loop Control, Open Loop Control, Hybrid Systems, Multi-Point Technology End User: OEMs, Aftermarket Retailers, Repair Shops, Fleet Operators Application: Motorcycles, Scooters, Dirt Bikes, Electric Bicycles |
| Companies Covered | Mikuni Corporation, Continental AG, Robert Bosch GmbH, Keihin Corporation, Delphi Automotive, Marelli Holdings Co. Ltd., Hitachi Astemo, Ltd., UCAL Systems Inc., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2 Wheeler Fuel Injection System Market Strategic Shifts
Powertrain electrification and embedded intelligence are compressing development cycles for fuel metering architectures, with software-defined calibration displacing hardware-centric fuel delivery systems.
Multi-point injection configurations with cylinder-specific pulse-width modulation are overtaking single-point architectures in performance-oriented motorcycles above 200cc. Thai and Indian OEMs are adopting MPI for premium commuter segments where individual cylinder tuning justifies cost premiums. This technology is overtaking port-injection simplicity in markets where torque delivery precision commands buyer preference.
EPA and NHTSA tailpipe standards in the United States are tightening evaporative emission controls, forcing sealed fuel system designs with integrated pressure sensors. The regulatory consequence extends to aftermarket replacement components, which must now carry EFI-compatible certification. Mexican export-oriented assembly plants serving the US market are reconfiguring supply chains to source EPA-validated injector and rail assemblies.
Buying committees at Indonesian and Vietnamese motorcycle distributors now specify fuel injection system procurement through total cost of ownership frameworks rather than upfront component pricing. Channel intermediaries are unbundling installation and calibration services from hardware supply, creating separate revenue streams for diagnostic and mapping support. This behavioral shift is most visible in Jakarta and Ho Chi Minh City, where fleet operators negotiate multi-year service contracts alongside injector hardware procurement.
2 Wheeler Fuel Injection System Market Segmentation
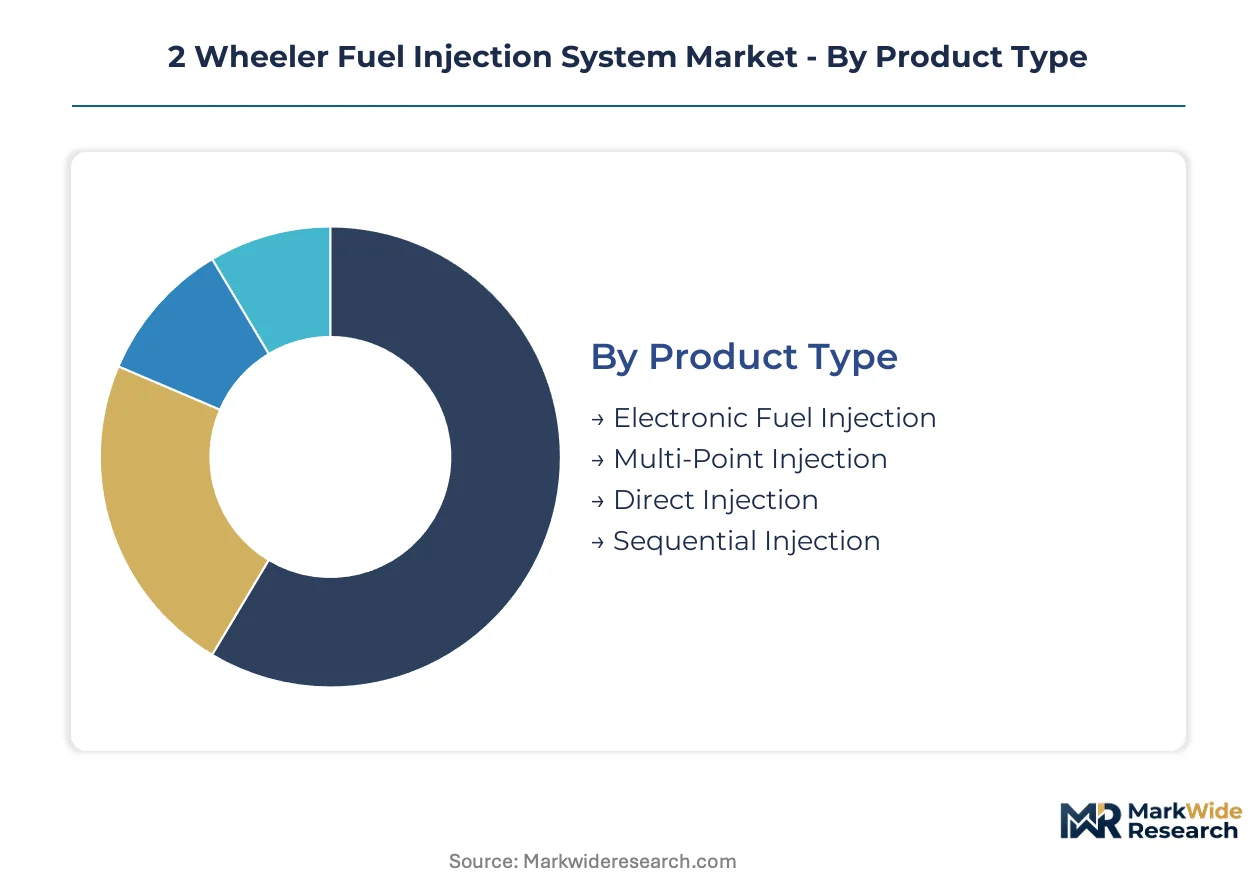
Fuel injection architectures diverge sharply across displacement classes and emission compliance tiers, with Bharat Stage VI and Euro 5 mandates compressing technology choices for Indian and European OEMs. Procurement committees weigh calibration complexity against unit economics differently in commuter motorcycles versus premium scooters, fragmenting supplier engagement models across product categories.
Product Type:
Cost tier determines factory-fit penetration, with port injection dominating below 150cc displacement while direct injection commands premium positioning.
- Electronic Fuel Injection:Solenoid injectors meter pressurized fuel at 2.5 to 3.5 bar through intake ports under ECU pulse-width modulation. Indian commuter motorcycle OEMs in Pune and Chennai source EFI architectures for Bharat Stage VI homologation, where real-time lambda correction eliminates carburetor compliance pathways.
- Multi-Point Injection:Cylinder-specific injectors enable individual fuel mapping for torque delivery precision. Thai and Indian manufacturers deploy MPI in performance-oriented motorcycles above 200cc, where buyer preference for throttle response justifies cost premiums over single-point architectures.
- Direct Injection:Combustion chamber fuel placement at elevated pressures enables lean-burn strategies for emission optimization. Compact two-wheeler applications remain limited by injector packaging constraints in single-cylinder layouts.
- Sequential Injection:Timed injection events synchronized to intake valve opening improve cold-start emission performance. Euro 5 certification cycles in Italy and Spain drive adoption for small-displacement premium motorcycles.
Electronic Fuel Injection leads on scale across Asian production clusters; Multi-Point Injection leads on momentum in premium displacement segments.
Technology:
Emission enforcement intensity dictates control architecture selection, with closed-loop systems mandatory in regulated markets and open-loop persisting in cost-sensitive geographies.
- Closed Loop Control:Oxygen sensor feedback enables real-time air-fuel ratio correction to stoichiometric targets. ARAI-validated systems dominate Indian OEM procurement for Bharat Stage VI, where lambda sensor integration is mandatory for type approval.
- Open Loop Control:Pre-mapped fuel delivery without exhaust gas feedback minimizes hardware cost. Rural Indonesian and Vietnamese markets sustain demand for open-loop retrofit kits where formal emission testing infrastructure remains sparse.
- Hybrid Systems:Dual-mode architectures switch between closed-loop urban operation and open-loop highway efficiency. Emerging relevance for range-extender electric two-wheelers in Indian metropolitan fleets.
- Multi-Point Technology:Distributed sensing and actuation across multiple injection points. Scooter platforms above 125cc in Jakarta and Ho Chi Minh City integrate thermal-management-optimized variants for automatic transmission thermal loads.
Closed Loop Control commands factory-fit volume; Hybrid Systems are expanding most quickly through electric two-wheeler hybridization programs.
End User:
Warranty liability and calibration capability separate procurement channels, with OEMs demanding full system validation and aftermarket prioritizing plug-and-play replacement.
- OEMs:Factory-integrated fuel injection systems with homologation documentation and multi-year warranty support. Indian motorcycle manufacturers in Gurugram and Bengaluru concentrate procurement among ECU-capable Tier 1 suppliers for Bharat Stage VI compliance.
- Aftermarket Retailers:Component-level injector and rail assembly sales for legacy platform maintenance. EPA and NHTSA tailpipe standards in the United States redirect demand toward EFI-compatible certified components.
- Repair Shops:Diagnostic and recalibration services for sensor replacement and fuel mapping adjustment. Skill gaps in informal Southeast Asian service networks limit penetration of advanced closed-loop maintenance protocols.
- Fleet Operators:Total cost of ownership procurement frameworks with multi-year service contracts. Jakarta and Ho Chi Minh City commercial scooter fleets unbundle hardware supply from calibration support.
OEMs anchor procurement volume; Fleet Operators are gaining share fastest through commercial electrification transition programs.
Application:
Platform thermal environment and duty cycle intensity shape injector specification, with air-cooled commuter engines requiring different fuel rail integration than liquid-cooled performance architectures.
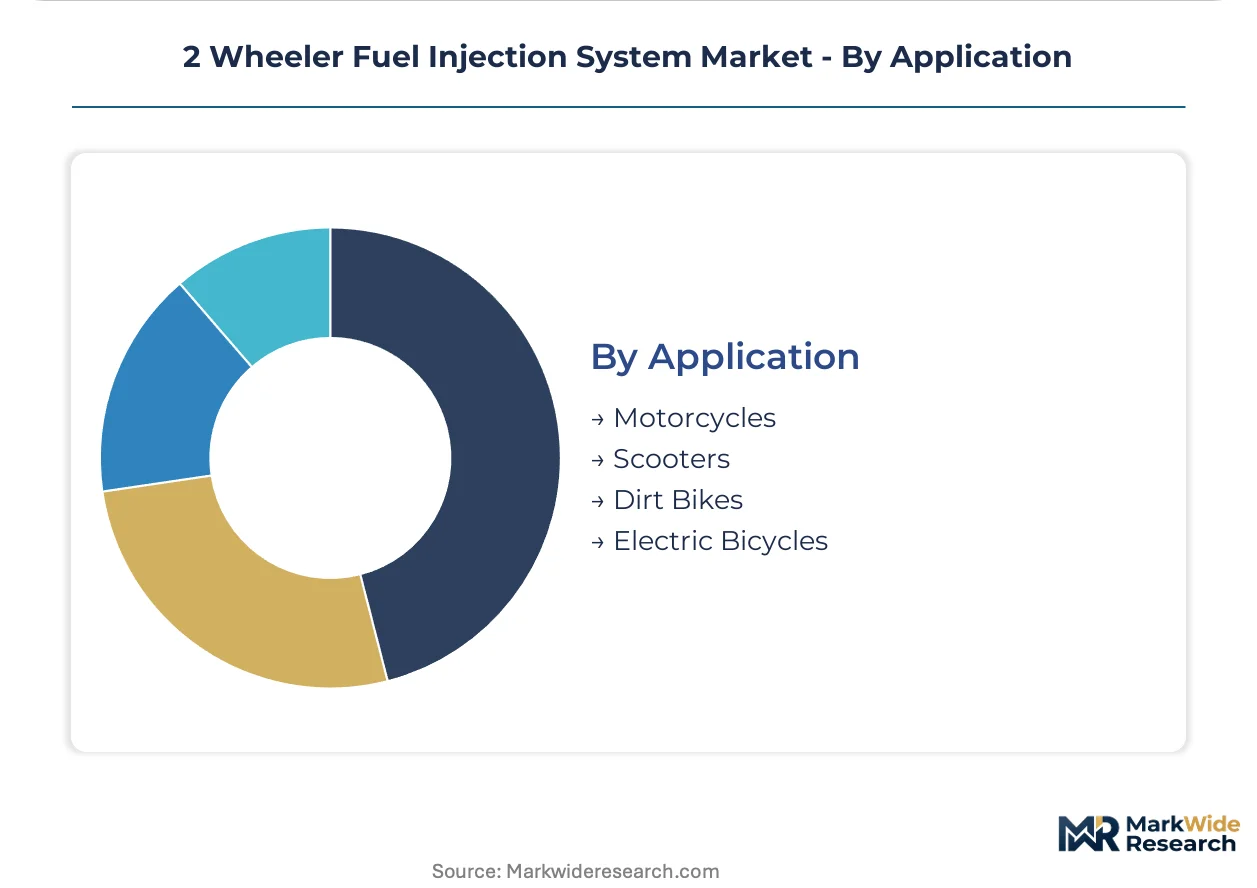
- Motorcycles:Dominant application spanning commuter singles to multi-cylinder performance platforms. Indian production above 150cc displacement increasingly mandates closed-loop EFI for BS-VI compliance.
- Scooters:Automatic transmission thermal management demands integrated fuel rail and injector cooling solutions. Indonesian premium scooter platforms above 125cc specify thermal-management-optimized assemblies.
- Dirt Bikes:Off-road duty cycles with high vibration and contamination exposure require ruggedized injector sealing. Limited emission regulation in recreational applications sustains carburetor persistence in aftermarket channels.
- Electric Bicycles:Range-extender and hybrid architectures requiring intermittent combustion cycle optimization. Indian PLI scheme subsidies accelerate localized fuel injection system development for hybrid two-wheeler platforms.
Motorcycles lead on installed base scale; Electric Bicycles show the steepest expansion trajectory through powertrain hybridization roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered precision fuel metering for small-displacement engines during the 1980s, establishing the technical foundations that German and Indian suppliers now adapt for Bharat Stage VI and Euro 5 compliance cycles.
India
Domestic motorcycle OEMs in Gurugram and Chennai source closed-loop EFI architectures to meet ARAI-validated Bharat Stage VI mandates. The CEA enforces oxygen-sensor feedback requirements that eliminate carburetor compliance pathways for production above 150cc displacement. Pune-based manufacturing clusters concentrate injector and ECU assembly capacity under PLI scheme subsidies.
Indonesia
Premium scooter platforms above 125cc displacement drive procurement of thermal-management-integrated fuel rail assemblies. The country's national emission regulator mandates evaporative emission controls that redirect factory-fit demand toward sealed fuel system designs. Jakarta-based fleet operators unbundle hardware supply from multi-year calibration service contracts.
Vietnam
Informal repair networks in rural provinces sustain aftermarket demand for open-loop retrofit kits where formal testing infrastructure remains sparse. The national transport ministry phases emission standards that gradually compress carburetor replacement windows. Ho Chi Minh City commercial scooter fleets specify total cost of ownership frameworks for fuel injection system procurement.
Germany
Stuttgart-based powertrain electronics capability clusters supply ECU microcontrollers and lambda control algorithms to Indian and Indonesian OEMs. The KBA enforces Euro 5 certification cycles that demand simultaneous emission and OBD compliance validation. Continental AG and Robert Bosch GmbH anchor development of compact injector designs for single-cylinder engines below 150cc.
Thailand
Performance-oriented motorcycle manufacturers deploy multi-point injection configurations for torque delivery precision in platforms above 200cc. The national industrial standards body aligns testing protocols with Euro 5 frameworks for export-oriented assembly. Bangkok-area OEMs adopt cylinder-specific fuel mapping to capture premium commuter segment margin pools.
2 Wheeler Fuel Injection System Market Competitive Environment
The competitive structure tilts toward diversified automotive electronics conglomerates with powertrain heritage. Tier 1 suppliers concentrate procurement leverage through ECU capability and homologation documentation. Three archetypes dominate: diversified automotive electronics conglomerates, specialized fuel system component manufacturers, and diversified industrial conglomerates with precision engineering divisions. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers align calibration service investments with regulatory enforcement timelines.
Within the diversified automotive electronics tier, Robert Bosch GmbH, Continental AG, and Denso Corporation exemplify scale-driven positioning. Bosch leverages its Stuttgart-based powertrain electronics portfolio to anchor high-volume programs for domestic motorcycle OEMs. Continental sustains development of compact injector architectures tailored to single-cylinder commuter engines. Denso occupies a position in thermal-management-integrated fuel rail assemblies for Asian scooter platforms. Keihin Corporation and Mikuni Corporation represent specialized fuel system component manufacturers with heritage in carburetor-to-EFI transitions. Marelli Holdings Co. Ltd. and Hitachi Astemo, Ltd. sit within diversified industrial conglomerate structures that span multiple mobility verticals. UCAL Systems Inc. anchors Indian-market positioning through localized manufacturing alignment with PLI scheme subsidies.
| Leading Market Players |
|---|
| Mikuni Corporation |
| Continental AG |
| Robert Bosch GmbH |
| Keihin Corporation |
| Delphi Automotive |
| Marelli Holdings Co. Ltd. |
| Hitachi Astemo, Ltd. |
| UCAL Systems Inc. |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in Germany and Japan anchor the 2 wheeler fuel injection system supply base, concentrating ECU microcontroller and precision injector manufacturing in Stuttgart and Nagoya clusters. This ownership pattern transmits directly into pricing discipline, as state-supported R&D amortization and long-term offtake agreements with Indian and Indonesian OEMs insulate Tier 1 suppliers from commodity-style margin compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with Bharat Stage VI certification grade and volume scale as the primary differentiation drivers. Cost compression in economy-tier port injection architectures is intensifying because Indian OEMs consolidate supplier lists under PLI scheme localization mandates. Fleet operators in Jakarta and Ho Chi Minh City exhibit the lowest price sensitivity due to total cost of ownership frameworks, while rural Vietnamese aftermarket retailers face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume demand from Indian and Indonesian motorcycle manufacturers, bypassing distributor markups for factory-fit ECU and injector procurement. Manufacturing concentrates in Germany, Japan, and India, with semiconductor die supply drawing from Taiwan and South Korea foundries. Single-source vulnerability in lambda sensor MEMS fabrication creates structural risk, as Bosch and Denso captive production limits second-source availability for ARAI-validated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 2 wheeler fuel injection system market functions as a stable compounder, with emission mandate phase-ins across India, Southeast Asia, and Europe delivering predictable procurement volume expansion regardless of macroeconomic cycles.
For Market Incumbents: Deepen backward integration into ECU microcontroller supply through foundry partnerships in Taiwan and South Korea, insulating against semiconductor input volatility that threatens bill-of-material stability. Expand calibration service capacity in Chennai and Jakarta to capture recurring revenue from Bharat Stage VI and Euro 5 homologation timelines, defending against emerging software-defined fuel mapping specialists.
For New Entrants and Emerging Players: The price-point gap between Bosch-led premium closed-loop systems and unbranded open-loop retrofit kits creates white-space opportunity in Vietnamese and Indonesian rural aftermarket channels. Target open-loop EFI conversion kits for carburetor legacy fleets where formal emission testing infrastructure remains sparse, partnering with informal repair networks for installation training rather than competing on hardware specification.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized fuel system component manufacturers with carburetor-to-EFI transition heritage but limited ECU capability. Long-term viability hinges on software-defined calibration competence rather than mechanical injector expertise alone. Watch Indian PLI scheme subsidy renewal announcements as the inflection signal for localized manufacturing capacity economics.
| Strategic Initiative | Industry Significance |
|---|---|
| ECU Microcontroller Supply Agreement | Semiconductor foundry partnerships in Taiwan reduce single-source exposure for Bosch and Continental. |
| Calibration Service Center Expansion | Chennai and Jakarta facilities capture recurring revenue from Bharat Stage VI homologation cycles. |
| Open-Loop EFI Retrofit Kit Launch | Vietnamese rural aftermarket penetration bypasses premium closed-loop supplier concentration. |
| Thermal-Management Fuel Rail Development | Indonesian scooter premiumization above 125cc displacement commands margin expansion. |
| PLI Scheme Manufacturing Localization | Indian component subsidies enable UCAL Systems and domestic challengers to compete with Japanese imports. |
Study Parameters
Direct dialogue with Tier 1 supplier procurement managers, OEM platform engineers, ARAI homologation officials, and Jakarta-based fleet operators grounded the qualitative foundation. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from diversified automotive electronics conglomerates, and CEA regulatory enforcement calendars. Bottom-up and top-down triangulation reconciled injector shipment volumes with motorcycle platform-level content assumptions.
Bottom-up modeling aggregated displacement-class-specific adoption rates across commuter, premium, and electric-hybrid segments, while top-down analysis cross-checked aggregate fuel injection system revenue against OEM powertrain electronics spending disclosures. Segmentation dimensions included injection architecture, control loop type, end-user channel, and regional regulatory cluster. CAGRs derived from slope-logic regression across the projection horizon, with Bharat Stage VI and Euro 5 phase-in calendars as primary demand drivers.
Caveats apply where semiconductor supply normalization or subsidy scheme modifications could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Thrust Bearings Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
RV Battery Market