
 South Africa Third-Party Logistics (3PL) Market | 2026-2036
South Africa Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Third-Party Logistics (3PL) Market Analytics
Freight corridor capacity in South Africa is shifting toward integrated multimodal networks connecting Durban harbor to inland industrial zones. Imperial Logistics dominates containerized road-rail intermodal services along the Maputo Corridor. DHL Supply Chain leverages its pharmaceutical cold-chain certification to anchor healthcare distribution contracts. Bidvest International Logistics specializes in automotive parts logistics, sustaining just-in-time delivery relationships with Eastern Cape vehicle assembly plants.
Third-Party Logistics (3PL) denotes outsourced management of transportation, warehousing, and fulfillment operations performed by external providers rather than in-house supply chain departments. These services coordinate inventory flow through temperature-controlled storage, cross-dock consolidation, and route-optimized last-mile delivery to reduce working capital requirements for shippers. Warehousing claims the deepest margin pools as automated storage and retrieval systems raise facility throughput rates. E-Commerce within industry verticals is expanding fastest as direct-to-consumer order profiles multiply SKU handling complexity. Cloud Solutions among technology segments leads adoption as fleet telematics and warehouse management platforms migrate from on-premise servers to distributed architectures.
The National Land Transport Act and Cross-Border Road Transport Agency regulations govern carrier licensing, driver hours, and vehicle roadworthiness standards across South African freight operations. BIS certification requirements for warehouse equipment and the country's national pharmaceutical regulator's distribution guidelines shape facility investment and cold-chain compliance costs. Stakeholders must monitor how port congestion at Durban and Richards Bay reshapes inland routing decisions and inventory positioning strategies.
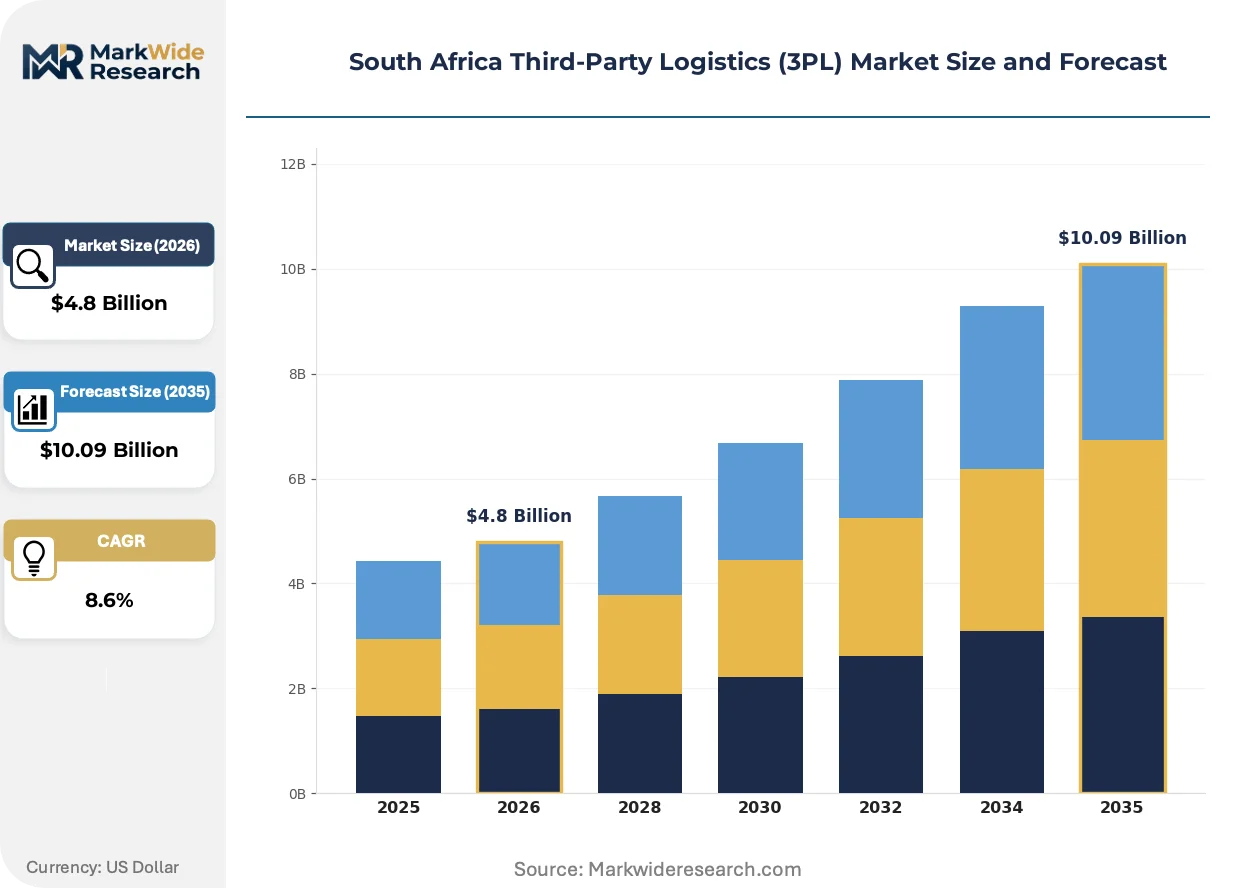
Market Dynamics
The National Land Transport Act is redistributing carrier compliance burdens across South Africa's freight network, forcing 3PL providers to consolidate licensing operations and reconfigure fleet deployment around driver-hour restrictions and roadworthiness mandates.
Growth Catalysts
- E-commerce fulfillment outsourcing:Direct-to-consumer order profiles are multiplying SKU handling complexity. Retailers are divesting in-house warehousing to access automated storage and retrieval systems.
- Cross-Border Road Transport Agency alignment:Harmonized licensing frameworks are reducing friction for corridor operators moving goods between South Africa and neighboring states.
- Cold-chain pharmaceutical certification:The country's national pharmaceutical regulator is tightening distribution guidelines. Temperature-controlled logistics providers are capturing healthcare contracts previously managed in-house.
Market Restraints
- Fuel price volatility:Diesel costs constitute the largest variable input for road freight operators. Margin compression limits pricing flexibility during energy price spikes.
- Durban port congestion:Container backlogs at South Africa's primary harbor are forcing inventory pre-positioning inland. Working capital requirements rise as safety stock levels increase.
- Rail infrastructure degradation:Transnet Freight Rail capacity constraints limit intermodal optionality. Shippers remain dependent on road transport for time-sensitive cargo.
Strategic Opportunities
- Eastern Cape automotive expansion:Vehicle assembly plants near Gqeberha are expanding just-in-time parts logistics requirements. Specialist 3PL providers can anchor supplier park operations.
- Cloud-based warehouse management platforms:Migration from on-premise servers to distributed architectures is opening subscription revenue models for technology-enabled logistics operators.
- Richards Bay mineral export corridor:Bulk commodity flows through KwaZulu-Natal's northern port are underserved by integrated logistics. Multimodal providers can capture mining sector contracts.
Industry Challenges
- Professional driver shortage:Compliance with the National Land Transport Act's hour restrictions requires larger qualified driver pools. Recruitment lags behind fleet expansion needs.
- Automated facility capex cycles:BIS certification requirements for warehouse equipment mandate capital-intensive retrofits. Mid-tier operators face financing constraints for modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Third-Party Logistics (3PL) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Fulfillment, Freight Forwarding Industry Vertical: Retail, E-Commerce, Manufacturing, Healthcare Delivery Model: Direct Shipping, Cross-Docking, Drop Shipping, Last-Mile Delivery Technology: Automation, IoT, Cloud Solutions, Data Analytics |
| Companies Covered | Imperial Logistics, DHL Supply Chain, Bidvest International Logistics, CEVA Logistics, Bolloré Logistics, Kuehne + Nagel, Barloworld Logistics, Onelogix, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Third-Party Logistics (3PL) Market Evolving Landscape
Cloud-native logistics platforms are redistributing computational workloads across distributed architectures, compressing deployment timelines and lowering barriers for mid-market 3PL adoption.
Blockchain-enabled documentation is decentralizing custody verification across the Maputo Corridor. Mining and automotive shippers are piloting distributed ledger systems to reduce customs clearance delays. The technology is decentralizing trust mechanisms previously concentrated around paper-based bills of lading and manual inspection protocols.
The National Land Transport Act's driver-hour restrictions are compressing permissible duty cycles. Fleet operators are responding with relay scheduling systems and expanded driver pools. Long-haul segments between Johannesburg and Durban are most affected, with carriers splitting routes across multiple crews.
Shippers are unbundling warehousing from transportation procurement. Large retailers are awarding separate contracts to specialized temperature-controlled storage providers and last-mile delivery operators. Gauteng province exhibits this pattern most acutely, with pharmaceutical and fast-moving consumer goods verticals leading the disaggregation.
South Africa Third-Party Logistics (3PL) Market Segmentation
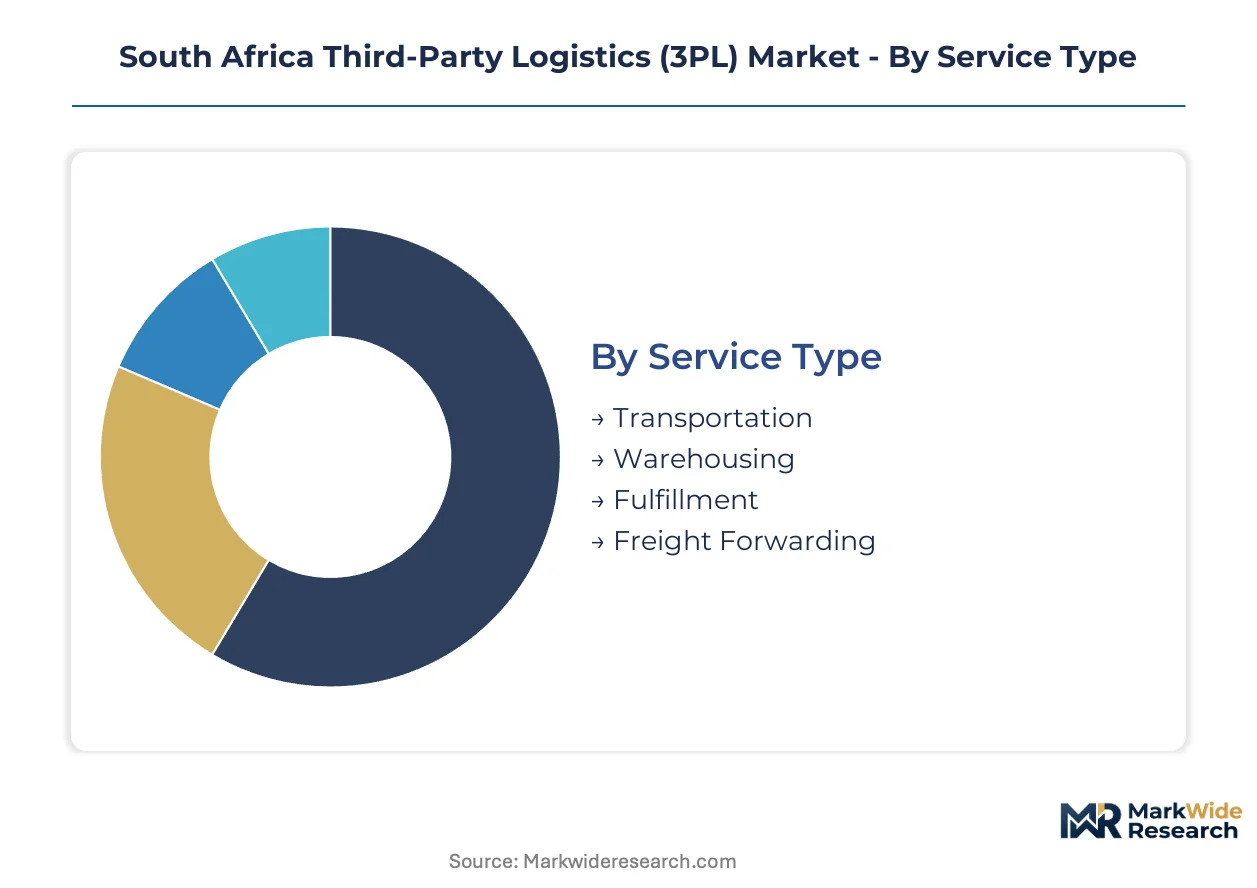
Third-party logistics providers in South Africa configure service portfolios around cargo characteristics, regulatory exposure, and infrastructure access. Segment boundaries blur as automated warehouses absorb fulfillment functions and cloud platforms unify previously siloed transportation management.
Service Type:
Cost tier separates buyers seeking asset-light coordination from those requiring capital-intensive facility commitments.
- Transportation:Road freight dominates modal mix with specialized reefers and tautliners serving temperature-sensitive and high-value cargo. Fleet operators concentrate in Gauteng province where the Johannesburg-Pretoria corridor absorbs the majority of long-haul volumes; diesel price volatility compresses margins during energy price spikes.
- Warehousing:Automated storage and retrieval systems raise facility throughput rates and deepen margin pools relative to conventional rack storage. Demand concentrates in Durban-Johannesburg logistics zones where importers pre-position inventory to buffer port congestion; BIS certification requirements for equipment mandate capital-intensive retrofits.
- Fulfillment:Direct-to-consumer order processing with pick-pack-ship operations integrated into e-commerce platforms.
- Freight Forwarding:Customs brokerage and international documentation coordination for cross-border cargo flows.
Volume sits with Transportation; growth tilts toward Warehousing.
Industry Vertical:
Application-specific compliance requirements reshape provider capabilities and certification investments.
- E-Commerce:Direct-to-consumer order profiles multiply SKU handling complexity and demand same-day or next-day delivery windows. Retailers divest in-house warehousing to access automated systems; the National Land Transport Act's driver-hour restrictions force relay scheduling for last-mile operations.
- Healthcare:Temperature-controlled logistics with cold-chain certification from the country's national pharmaceutical regulator. Distribution contracts concentrate around Johannesburg medical hubs; tightening guidelines are displacing in-house hospital pharmacy operations.
- Retail:Omnichannel inventory pooling with store fulfillment and home delivery integration.
- Manufacturing:Just-in-time parts logistics anchoring supplier park operations near Eastern Cape vehicle assembly plants.
Revenue concentrates with Retail; expansion accelerates fastest in E-Commerce.
Delivery Model:
Customer type determines network design, with enterprise shippers demanding control and marketplace sellers prioritizing flexibility.
- Last-Mile Delivery:Final-stage distribution to residential or commercial endpoints with route optimization and real-time tracking. Demand clusters in Gauteng urban corridors; professional driver shortage limits fleet expansion despite order volume growth.
- Cross-Docking:Rapid freight consolidation with minimal inventory holding between inbound and outbound movements.
- Direct Shipping:Point-to-point cargo movement without intermediate handling or storage.
- Drop Shipping:Inventory-free fulfillment where suppliers ship directly to end consumers via 3PL coordination.
Operational scale favors Cross-Docking; value capture is shifting toward Last-Mile Delivery.
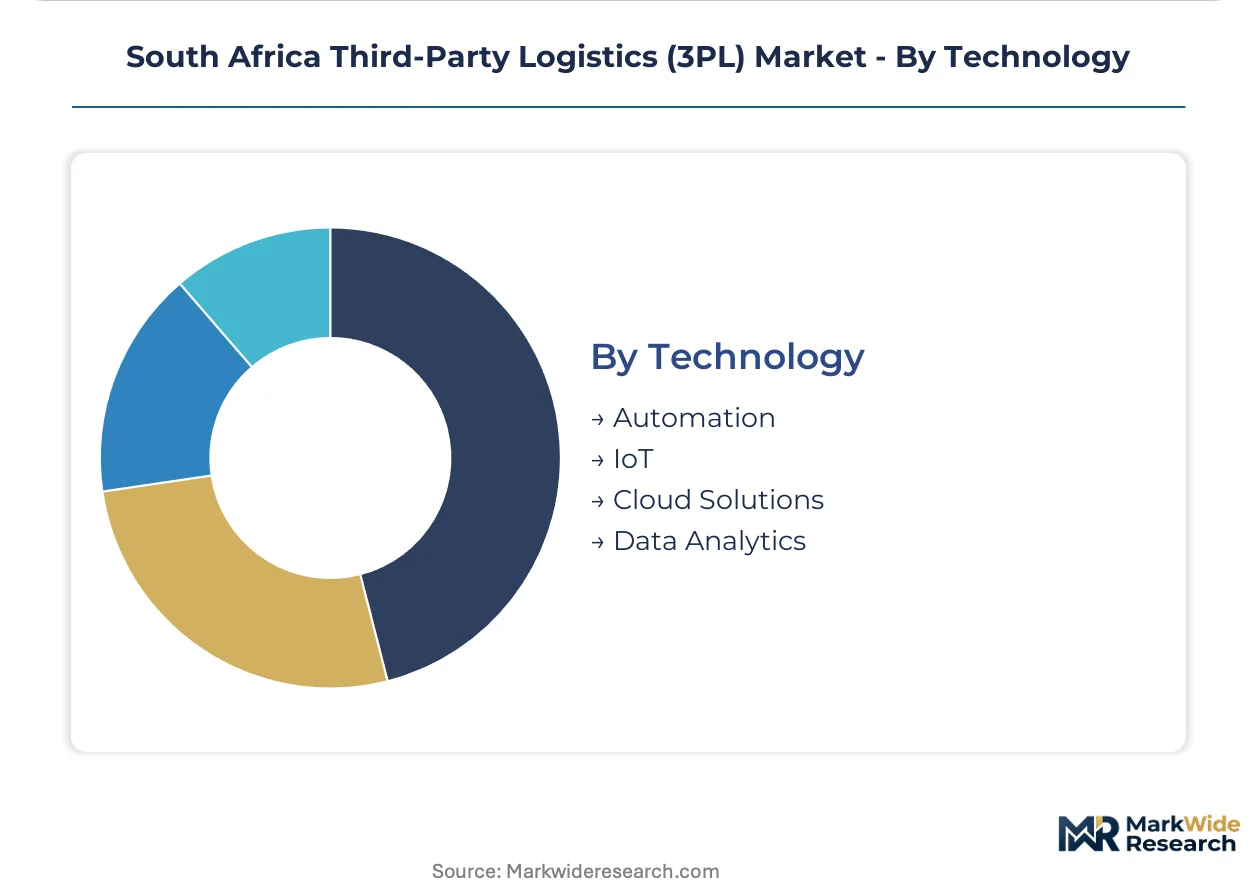
Technology:
Maturity gradient separates legacy on-premise operators from cloud-native entrants.
- Cloud Solutions:Distributed warehouse management and fleet telematics platforms migrating from on-premise servers. Mid-market 3PL adoption is climbing the fastest as deployment timelines compress; subscription revenue models are displacing perpetual license structures.
- Automation:Robotic picking, autonomous mobile robots, and automated sortation systems.
- IoT:Sensor networks for cargo condition monitoring and vehicle tracking across the Maputo Corridor.
- Data Analytics:Predictive demand forecasting and route optimization algorithms.
Investment intensity peaks with Automation; adoption velocity is highest in Cloud Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral export corridors through Richards Bay anchor KwaZulu-Natal's logistics gravity, while Gauteng's Johannesburg-Pretoria freight axis absorbs the majority of warehousing investment and intermodal capacity.
Gauteng Province
Pharmaceutical distribution hubs and automotive supplier parks drive warehousing demand in Johannesburg medical clusters and Pretoria industrial zones. The National Land Transport Act's driver-hour restrictions compress permissible duty cycles for long-haul operators. The Johannesburg-Pretoria corridor concentrates automated storage facilities serving e-commerce fulfillment networks.
KwaZulu-Natal Province
Durban harbor container backlogs and Richards Bay bulk mineral exports reshape inland routing decisions for importers and mining houses. Transnet Freight Rail capacity constraints limit intermodal optionality for time-sensitive cargo. The Durban-Johannesburg logistics zone hosts temperature-controlled storage investments buffering port congestion delays.
Eastern Cape Province
Vehicle assembly plants near Gqeberha expand just-in-time parts logistics requirements for supplier park operations. The Cross-Border Road Transport Agency harmonizes licensing frameworks for corridor operators moving components from South Africa into neighboring states. The Coega Industrial Development Zone attracts automotive-focused 3PL providers anchoring OEM delivery contracts.
Western Cape Province
Cape Town's pharmaceutical cold-chain certification concentration supports healthcare distribution contracts previously managed in-house by hospital pharmacy operations. The country's national pharmaceutical regulator tightens distribution guidelines for temperature-sensitive products. The Atlantis Industrial area hosts specialized reefers and tautliners serving high-value cargo segments.
Mpumalanga Province
Maputo Corridor road-rail intermodal services connect inland mining operations to Mozambique's port access. Imperial Logistics dominates containerized movements along this route. The Nelspruit logistics cluster serves as a consolidation point for agricultural exports and mining equipment imports.
South Africa Third-Party Logistics (3PL) Market Competitive Landscape
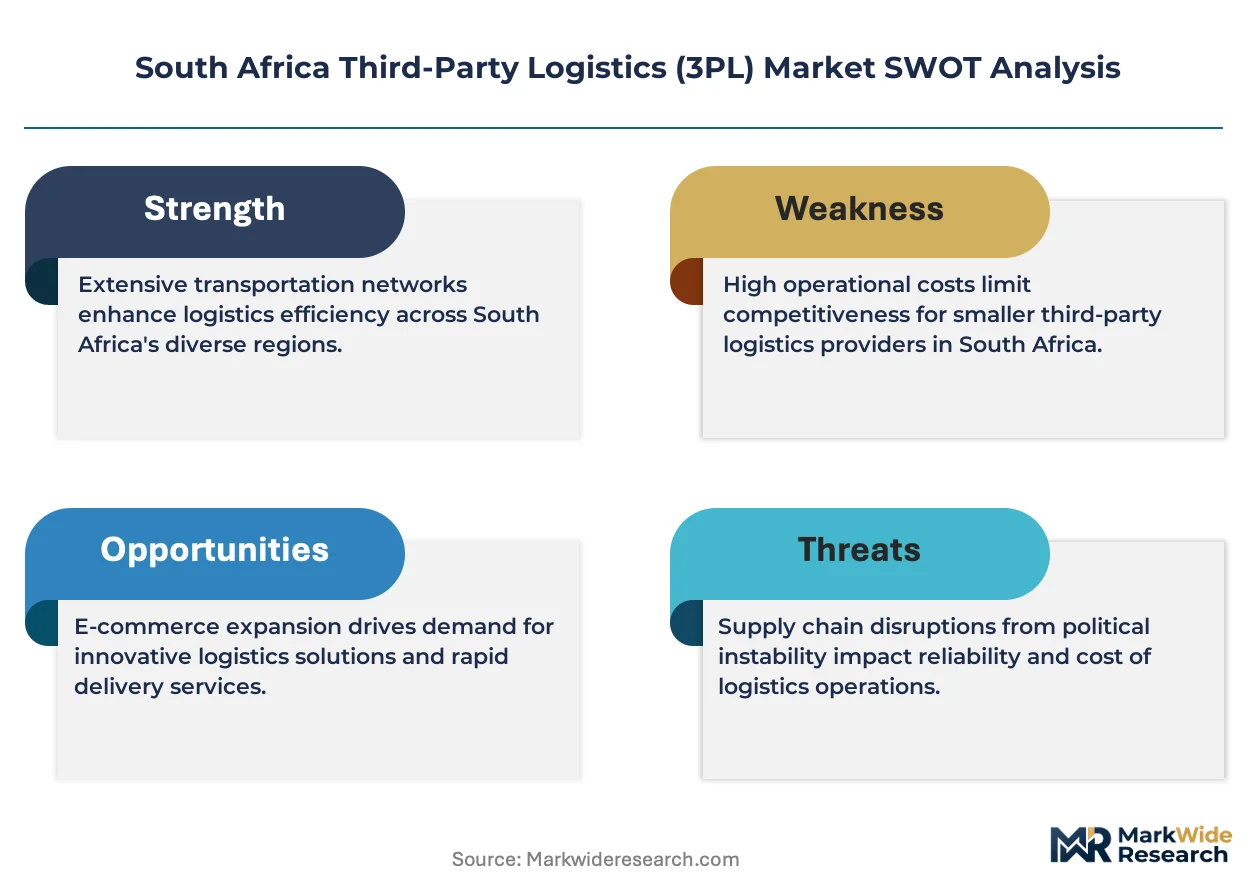
Established producers occupy the standard tier; emerging entrants pursue technology-enabled coordination platforms and specialized cold-chain certifications. The market structure concentrates around integrated multimodal operators with harbor access and asset-light technology providers serving mid-market shippers. Three archetypes dominate: diversified conglomerates with captive logistics arms, international freight forwarders with pharmaceutical certifications, and regional specialists anchoring automotive supplier parks. Competitive moves center on cloud-based warehouse management platform deployment and relay scheduling systems addressing driver-hour compliance.
Among diversified South African conglomerates, Imperial Logistics and Bidvest International Logistics exemplify integrated operators with corridor-specific intermodal dominance and automotive just-in-time specialization. DHL Supply Chain anchors the international forwarder tier, leveraging pharmaceutical cold-chain certification to capture healthcare distribution contracts. These three represent distinct strategic positions: domestic corridor control, vertical industry specialization, and global network certification.
| Leading Market Players |
|---|
| Imperial Logistics |
| DHL Supply Chain |
| Bidvest International Logistics |
| CEVA Logistics |
| Bolloré Logistics |
| Kuehne + Nagel |
| Barloworld Logistics |
| Onelogix |
| DSV |
| Others |
Value Network & Pricing Analysis
Professional driver pools in Gauteng province anchor labor-cost differentials that separate premium-tier corridor operators from economy-grade fleet contractors. The National Land Transport Act's hour restrictions widen these pricing spreads as compliance investments concentrate among licensed carriers.
Pricing Analysis
Warranty and service bundling separates full-service logistics contracts from unbundled transportation-only procurement. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain certification grade and volume scale commitments. Price differentiation stems from after-sales service inclusion and geographic delivery cost variations. Healthcare verticals show least price sensitivity due to regulatory compliance requirements; mid-market retailers face greatest cost compression as they migrate from in-house operations.
Supply Chain Analysis
BIS certification requirements for warehouse equipment gate supplier qualification, filtering equipment vendors through capital-intensive compliance protocols. Manufacturing concentration rests on China for automated systems, Germany for precision components, and domestic South African fabricators for structural steel. Diesel fuel, pallet racking, and refrigeration units constitute critical input dependencies. Single-source vulnerability runs through specialized cold-chain compressor suppliers. Distribution runs through Johannesburg-Pretoria logistics clusters with final-mile spokes to coastal demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional driver scarcity props pricing power across South Africa's 3PL sector, with the National Land Transport Act's compliance burdens constraining fleet expansion faster than demand growth.
For Market Incumbents: Cement corridor dominance by acquiring relay-scheduling technology providers and expanding driver training academy capacity. Imperial Logistics and Bidvest International Logistics should deepen Maputo Corridor control before Cross-Border Road Transport Agency harmonization attracts multinational forwarders. Cold-chain certification investments defend margin position against pharmaceutical vertical price pressure. For New Entrants and Emerging Players: The National Land Transport Act in South Africa opens a window for technology-enabled fleet operators unburdened by legacy compliance infrastructure. Target mid-market e-commerce fulfillment in Gauteng's underserved industrial zones with cloud-native warehouse management platforms. White-space capture favors subscription-based SaaS logistics coordination over asset-heavy fleet ownership. For Investors and Strategic Acquirers: Re-rating potential sits with cold-chain-certified regional specialists given pharmaceutical distribution guideline tightening by the country's national pharmaceutical regulator. Five-to-ten-year viability favors operators with automated facility footprints and harbor-adjacent land positions. Monitor Durban port congestion duration as inflection signal for inland warehousing valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Relay Scheduling System Deployment | Addresses National Land Transport Act driver-hour constraints on Johannesburg-Durban long-haul routes. |
| Cloud Warehouse Management Platform Launch | Captures mid-market 3PL adoption migrating from on-premise server architectures. |
| Cold-Chain Certification Investment | Unlocks healthcare distribution contracts as pharmaceutical regulator tightens guidelines. |
| Maputo Corridor Intermodal Expansion | Strengthens containerized road-rail service dominance against Transnet Freight Rail capacity constraints. |
| Automated Storage and Retrieval System Installation | Raises facility throughput rates to meet e-commerce SKU complexity demands in Gauteng zones. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South Africa 3PL market analysis. Primary interviews with fleet operations directors, warehouse facility managers, pharmaceutical procurement leads, and Cross-Border Road Transport Agency licensing officers combined with secondary sources including National Land Transport Act compliance databases, BIS certification registries, and Transnet Freight Rail capacity disclosures. Bottom-up service-type segmentation triangulated against top-down provincial demand aggregation.
Data-stream reconciliation across transportation volume metrics, warehousing square footage investments, and fulfillment transaction counts shaped the analytical framework. Segmentation dimensions modeled include service type, industry vertical, delivery model, and technology adoption tier across the projection horizon. CAGRs derived from trend extrapolation of corridor freight volumes and automated facility deployment rates. Forecast inputs incorporated e-commerce order profile evolution and pharmaceutical cold-chain compliance cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for cloud-native logistics platforms would alter the outlook if on-premise server retention exceeds projected rates. Forecasts reflect assumptions around Transnet Freight Rail capacity recovery and diesel price stabilization. A model refresh is warranted upon material change in National Land Transport Act enforcement intensity or Durban harbor congestion duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
India 3PL Market