
 Automotive Coolant Aftermarket Market | 2026-2036
Automotive Coolant Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Coolant Aftermarket Market Analysis
Skilled chemical formulation talent is collapsing across North American and European manufacturing hubs, forcing coolant producers to restructure technical hiring pipelines. Prestone Products Corporation leverages its captive retail shelf space and DIY brand recognition to sustain volume leadership in North American auto parts chains. ExxonMobil Corporation anchors its aftermarket position through backward integration into ethylene glycol feedstock production, controlling raw material cost volatility. Shell plc differentiates via global lubricant-coolant bundling programs that occupy premium service bays in Europe and Asia-Pacific.
Automotive coolant aftermarket encompasses the secondary market for heat-transfer fluids formulated from ethylene glycol or propylene glycol bases, typically blended with corrosion inhibitors, defoamers, and pH buffers to maintain engine operating temperatures between 90°C and 120°C while preventing aluminum, copper, and solder degradation. Organic Acid Technology coolants dominate volume due to extended five-year service life, though Hybrid Organic Acid Technology formulations are capturing growth in heavy-duty truck fleets requiring nitrite-free protection for wet-sleeve diesel engines. Passenger Cars sustain the largest vehicle-type revenue pool, yet Commercial Vehicles generate higher per-unit margins through specification-grade fleet contracts and bulk dispensing systems.
EPA oversees antifreeze disposal and toxicity labeling under FIFRA and RCRA frameworks, while REACH restricts certain boron- and amine-based corrosion inhibitors across European formulations, compelling BASF SE and TotalEnergies SE to reformulate additive packages. The EU F-Gas Regulation indirectly shapes coolant demand by accelerating thermal system redesigns in vehicle OEMs, which cascades into aftermarket compatibility requirements for next-generation engines. Stakeholders must monitor regulatory divergence between California's Safer Consumer Products program and emerging Chinese GB standards for glycol-based engine coolants to anticipate formulation investment priorities and regional market access barriers.
Market Dynamics
Extended service intervals mandated by OEM thermal management redesigns are compressing replacement frequency while simultaneously elevating specification complexity for aftermarket formulators. This tension between volume erosion and value-per-unit expansion defines current competitive positioning.
Growth Catalysts
- REACH chemical restrictions:European bans on boron- and amine-based corrosion inhibitors force continuous additive package innovation, creating recurring revenue streams for compliant suppliers.
- Heavy-duty fleet electrification:Battery thermal management systems require dielectric coolants with new conductivity and material compatibility profiles, opening specification-grade contract opportunities.
- Aging vehicle parc concentration:The United States, Germany, and China collectively host over 800 million vehicles exceeding five years of age, sustaining baseline coolant consumption despite interval extension.
Market Restraints
- Ethylene glycol price volatility:Crude oil derivative costs swing with energy markets, compressing blender margins and discouraging long-term contract pricing.
- Feedstock supply concentration:Saudi Arabia and Kuwait control over 60% of global ethylene glycol export capacity, exposing formulators to geopolitical shipping disruptions.
- Propylene glycol performance ceiling:Lower thermal conductivity versus ethylene glycol limits adoption in high-performance engines despite toxicity advantages.
Strategic Opportunities
- India BIS standardization:Pending mandatory IS 5759 certification for engine coolants creates first-mover advantage for pre-qualified suppliers in a fragmented aftermarket.
- Direct-to-fleet digital platforms:Bulk dispensing system integration with telematics-enabled predictive maintenance compresses distributor layers and captures service bay data.
- EU F-Gas Regulation cascade:Vehicle HVAC refrigerant phase-down accelerates engine cooling system redesigns, requiring compatible aftermarket formulations for next-generation architectures.
Industry Challenges
- Formulation chemist scarcity:North American and European manufacturing hubs face collapsing pipelines of skilled corrosion inhibitor specialists, forcing restructuring of technical hiring and retention programs.
- Cross-regional certification timelines:Divergent approval pathways between EPA FIFRA labeling, REACH dossier submission, and emerging Chinese GB standards extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Coolant Aftermarket Market |
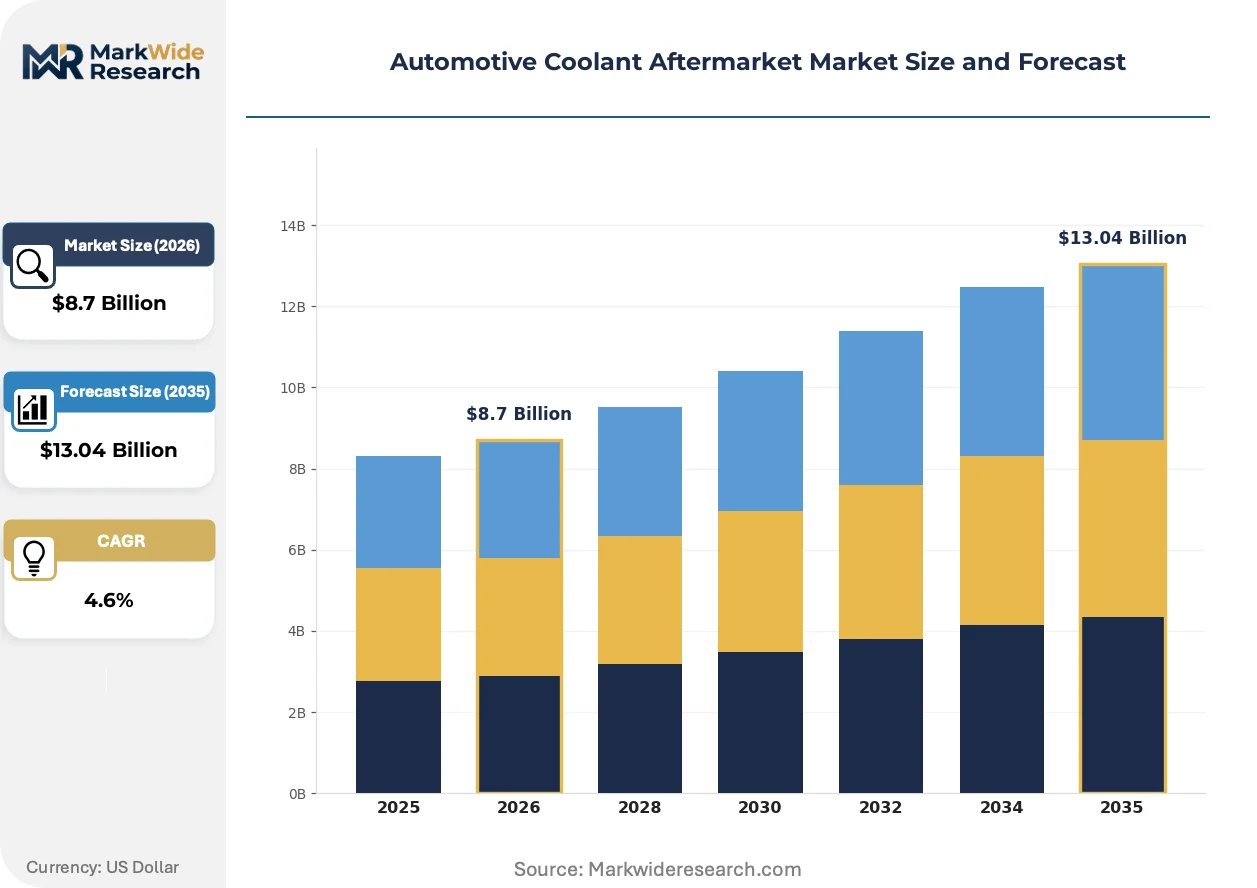
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Organic Acid Technology, Hybrid Organic Acid Technology End User: Retailers, Wholesalers, Repair Shops, Car Manufacturers Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Distribution Channel: Online Retail, Brick-and-Mortar Stores, Distributors, Auto Parts Shops |
| Companies Covered | Prestone Products Corporation, ExxonMobil Corporation, Shell plc, Chevron Corporation, Valvoline Inc., TotalEnergies SE, BASF SE, Castrol Limited, Motul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Coolant Aftermarket Market Emerging Trajectories
Formulation chemistry and distribution architecture are undergoing parallel transformation as thermal management requirements diverge across powertrain technologies. Three developments are restructuring how value is captured and defended.
Hybrid Organic Acid Technology coolants are supplanting conventional Organic Acid Technology in heavy-duty diesel applications by eliminating nitrites that degrade wet-sleeve cylinder liners. Fleet maintenance managers at long-haul operators are specifying HOAT for extended drain intervals exceeding 600,000 miles. This chemistry migration is compressing commodity ethylene glycol volumes while expanding premium additive package margins.
EPA's evolving RCRA hazardous waste classification for spent antifreeze is forcing service shops to adopt closed-loop recycling equipment or certified third-party disposal contracts. The industrial consequence is capital deployment into collection infrastructure rather than inventory expansion. Independent repair facilities in California face additional Safer Consumer Products program scrutiny, accelerating consolidation toward franchised service networks with compliance scale.
Fleet procurement departments are consolidating coolant purchasing through national maintenance agreements that bundle specification compliance, bulk delivery, and used fluid retrieval. This behavior shift is displacing traditional jobber distribution in the commercial vehicle segment. The transformation is most visible across United States interstate trucking corridors where telematics-integrated inventory management now governs replenishment timing.
Automotive Coolant Aftermarket Market Segmentation
Coolant formulation chemistry and procurement channel structure determine margin capture in this aftermarket. Specification divergence across powertrain technologies and fleet digitalization are fragmenting historical segment boundaries.
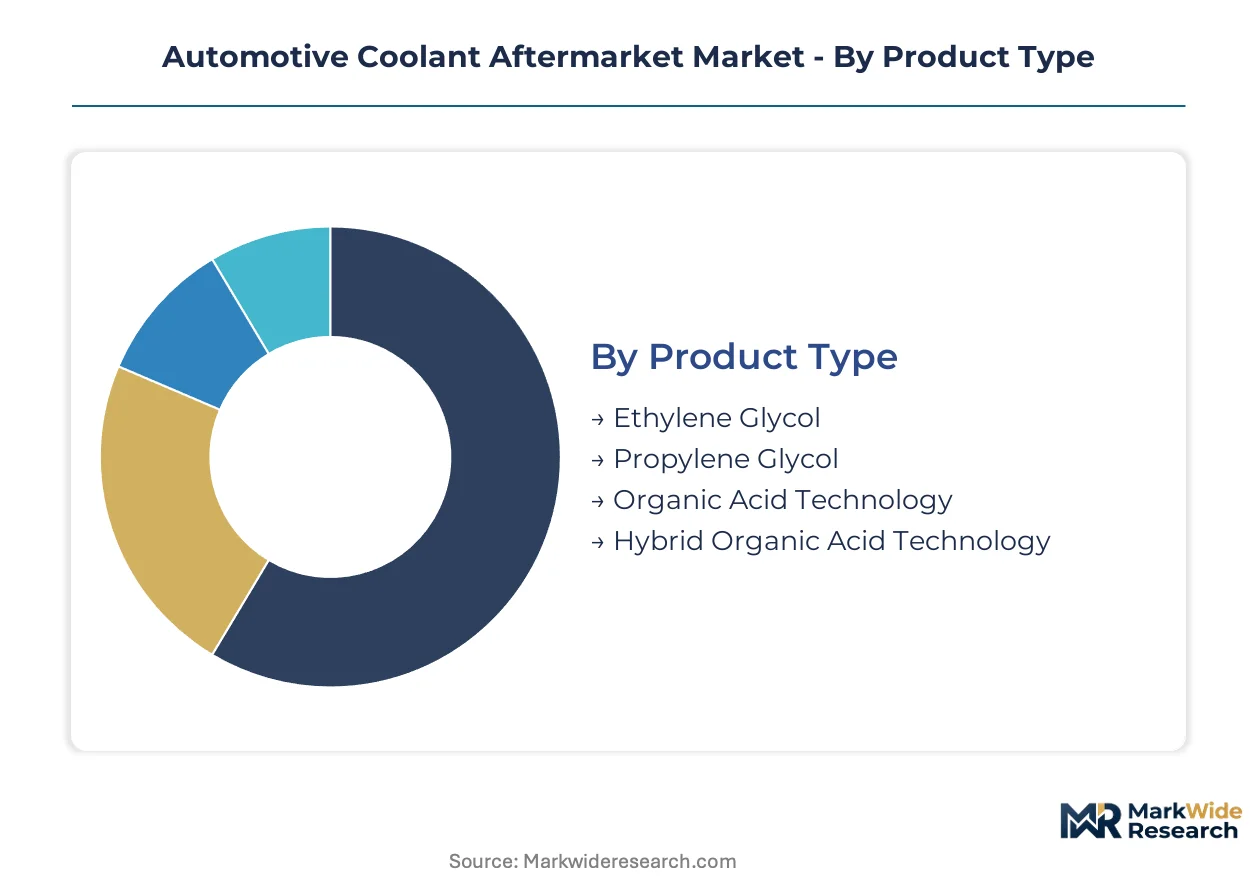
Product Type:
Substitution pressure intensifies as REACH-compliant additive packages displace legacy boron- and amine-based chemistries, forcing continuous reformulation investment.
- Ethylene Glycol:Dominant base fluid delivering superior thermal conductivity for high-performance engines. Demand concentrates in United States interstate trucking corridors where fleet managers prioritize heat-transfer efficiency over toxicity concerns despite handling regulations.
- Organic Acid Technology:Extended five-year service life formulations now standard in passenger car applications. United States and German aftermarket channels show strongest uptake as aging vehicle parc owners defer maintenance costs through longer drain intervals.
- Propylene Glycol:Lower toxicity base fluid with performance ceiling constraints limiting adoption to marine and recreational vehicle segments where environmental discharge regulations apply.
- Hybrid Organic Acid Technology:Nitrite-free chemistry capturing heavy-duty diesel specifications for wet-sleeve engine protection in long-haul fleet contracts.
Ethylene Glycol anchors the volume base while Hybrid Organic Acid Technology gains share at the steepest rate.
End User:
Procurement consolidation is compressing distributor layers as telematics-enabled fleet management reshapes replenishment timing.
- Repair Shops:Primary service bay channel facing EPA RCRA hazardous waste classification pressures. California independent facilities confront additional Safer Consumer Products program scrutiny accelerating consolidation toward franchised networks.
- Wholesalers:Traditional bulk distribution intermediaries losing position to direct-to-fleet digital platforms with predictive maintenance integration.
- Retailers:DIY consumer channel sustained by Prestone's captive shelf space in North American auto parts chains.
- Car Manufacturers:OES supply contracts with specification-grade requirements for warranty-compliant service networks.
Repair Shops generate the highest transaction frequency while fleet-direct procurement expands most quickly.
Vehicle Type:
Per-unit margin differentiation separates specification-grade commercial applications from commodity passenger car volumes.
- Passenger Cars:Largest installed base sustaining baseline coolant consumption despite extended OEM service intervals compressing replacement frequency.
- Heavy-Duty Trucks:Premium specification contracts with bulk dispensing systems and used fluid retrieval requirements. United States interstate operators specify HOAT formulations exceeding 600,000-mile drain intervals.
- Commercial Vehicles:Fleet maintenance agreements bundling compliance, delivery, and retrieval displacing traditional jobber distribution.
- Motorcycles:Niche segment with aluminum radiator protection requirements and seasonal usage patterns.
Passenger Cars provide the volume foundation while Heavy-Duty Trucks deliver the steepest margin expansion trajectory.
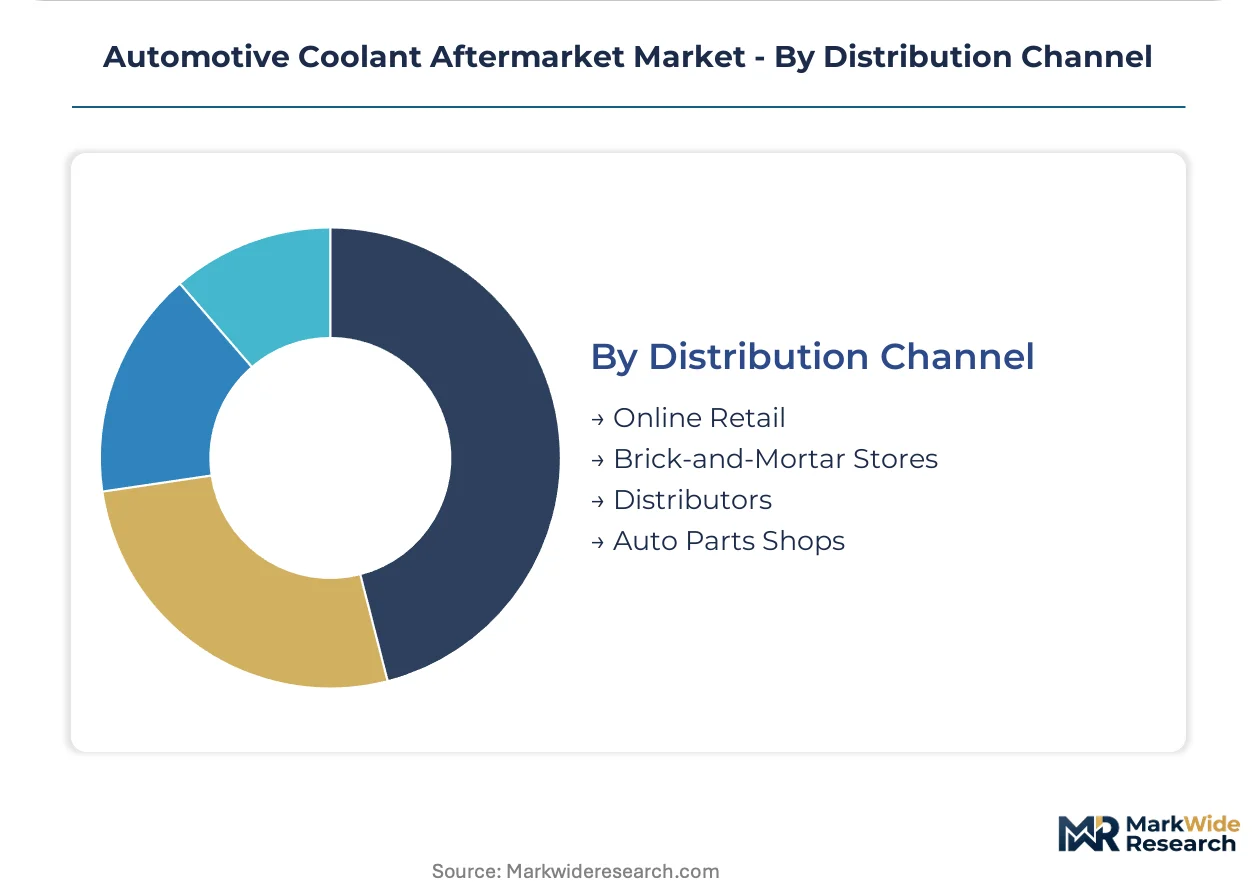
Distribution Channel:
Channel cost structure determines competitive access as digital platforms capture fleet procurement consolidation.
- Distributors:Traditional layered distribution facing margin compression from telematics-integrated inventory management systems.
- Online Retail:Growing DIY consumer channel with specification lookup tools reducing counter staff dependency.
- Auto Parts Shops:Physical retail network with technical consultation value for complex compatibility questions.
- Brick-and-Mortar Stores:Mass merchant channel for emergency top-off purchases with limited technical support.
Distributors retain the volume anchor while Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's specification-grade contracts while United States fleet operators squeeze margins through consolidated national procurement agreements. This asymmetry shapes how formulators allocate technical resources across regulatory environments.
United States
Interstate trucking corridors generate premium specification demand as fleet managers mandate 600,000-mile drain intervals under EPA FIFRA disposal frameworks. California's Safer Consumer Products program accelerates repair shop consolidation toward franchised networks with compliance scale. The Detroit-Toledo corridor anchors heavy-duty formulation development for wet-sleeve diesel protection.
Germany
REACH chemical restrictions on boron- and amine-based corrosion inhibitors force continuous additive package reformulation by BASF SE and TotalEnergies SE. The EU F-Gas Regulation cascades thermal system redesign requirements into aftermarket compatibility specifications. Stuttgart and Ludwigshafen host the densest concentration of automotive chemical R&D facilities in Europe.
China
Pending GB standards for glycol-based engine coolants create first-mover certification advantages for pre-qualified suppliers in a fragmented aftermarket. The country's national chemical regulator enforces dual carbon goals that reshape ethylene glycol feedstock sourcing. Yangtze River Delta manufacturing clusters concentrate blending capacity for both domestic consumption and export markets.
India
Mandatory IS 5759 certification requirements open specification-grade contract opportunities for compliant formulators ahead of standardization enforcement. BIS technical committees are finalizing test protocols that will displace unorganized sector suppliers. Gujarat and Maharashtra industrial corridors attract coolant blending investments targeting commercial vehicle fleet growth.
Japan
METI energy efficiency guidelines extend OEM thermal management redesigns into aftermarket service interval specifications. JIS standards maintain strict material compatibility requirements for aluminum radiator protection. Kanto region technical centers coordinate formulation approvals across Asia-Pacific distribution networks.
Automotive Coolant Aftermarket Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with specification-grade formulators commanding premium positioning while commodity blenders compete on ethylene glycol sourcing efficiency. The vendor base concentrates around three strategic tiers: captive retail shelf space operators, backward-integrated petrochemical majors, and specialty chemical additive suppliers. Dominant competitive moves include portfolio diversification into dielectric coolant formulations for electric vehicle thermal management and geographic expansion through pre-qualified regulatory certification in emerging markets.
Within the petrochemical-integrated tier, ExxonMobil Corporation and Shell plc anchor positions through captive ethylene glycol feedstock control and global lubricant-coolant bundling programs respectively. Prestone Products Corporation exemplifies the retail-captive archetype through DIY brand recognition in North American auto parts chains. These three entities represent distinct pathways for margin defense: upstream raw material control, service bay bundling scale, and consumer shelf space dominance.
| Leading Market Players |
|---|
| Prestone Products Corporation |
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| Valvoline Inc. |
| TotalEnergies SE |
| BASF SE |
| Castrol Limited |
| Motul |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Gulf Coast ethylene glycol crackers shapes both feedstock availability floors and blender margin compression, concentrating pricing power with backward-integrated petrochemical majors while forcing independent formulators toward specification-grade premium tiers.
Pricing Analysis
Configured-to-order fleet contracts command 40-60% premiums over standard DIY retail gallons, with pricing stratifying across premium HOAT formulations, standard OAT service fills, and economy ethylene glycol base fluids. Price differentiation hinges on REACH-compliant additive certification and bulk dispensing system integration. Cost compression in commodity ethylene glycol blending is intensifying because Saudi Aramco and SABIC control export terminal access. Fleet procurement departments show lowest price sensitivity due to total-cost-of-ownership calculations, while independent repair shops face acute margin pressure from RCRA disposal compliance costs.
Supply Chain Analysis
Strategic stockpiling of corrosion inhibitor additive packages dominates formulation chemistry procurement, while just-in-time ethylene glycol delivery governs blending operations. Feedstock supply concentrates in Saudi Arabia, Kuwait, and the United States Gulf Coast. The supply chain draws from crude oil derivatives, phosphate ester defoamers, and azole-based corrosion inhibitors. Single-source vulnerability runs through Saudi-Kuwaiti export capacity concentration. Distribution runs through layered jobber networks facing displacement by telematics-integrated direct-to-fleet platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy-duty fleet electrification is disrupting thermal management chemistry requirements, creating specification-grade contract opportunities for dielectric coolant formulators ahead of mass battery-electric truck deployment.
For Market Incumbents: Consolidate additive formulation expertise through captive hiring pipelines in Stuttgart and Ludwigshafen technical centers, countering the collapsing North American corrosion inhibitor specialist pipeline. Secure backward integration into ethylene glycol feedstock through long-term offtake agreements with Gulf Coast crackers, insulating margin compression from energy market volatility.
For New Entrants and Emerging Players: Lead with pre-qualified BIS IS 5759 certification in India's Gujarat and Maharashtra industrial corridors, capturing fleet procurement consolidation ahead of mandatory standardization enforcement. Target specification-grade HOAT contracts with United States interstate trucking operators through telematics-integrated bulk dispensing system partnerships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical additive suppliers with REACH dossier submission capabilities and dielectric coolant R&D pipelines. Acquisition targets should demonstrate compliant formulation archives and fleet-direct digital platform integration. The signal to watch is EPA FIFRA hazardous waste reclassification tightening disposal economics for service shop networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Glycol Feedstock | Captive supply from ExxonMobil and Shell insulates margin compression from Saudi-Kuwaiti export volatility. |
| REACH-Compliant Additive Package Reformulation | BASF SE and TotalEnergies SE secure recurring revenue streams from European boron- and amine-free chemistry mandates. |
| Telematics-Integrated Fleet Direct Platforms | Predictive maintenance data compresses distributor layers and governs replenishment timing for long-haul operators. |
| Dielectric Coolant Development for Battery Thermal Management | New conductivity and material compatibility profiles open specification-grade contract opportunities in electrified heavy-duty segments. |
| Pre-Qualified Certification in Emerging Markets | First-mover BIS IS 5759 and pending GB standard compliance creates barriers against unorganized sector suppliers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the automotive coolant aftermarket value chain, including fleet maintenance managers at interstate trucking operators, formulation chemists at additive suppliers, procurement leads at aftermarket distributors, and technical directors at ethylene glycol producers. Secondary validation drew from EPA FIFRA registration databases, REACH dossier submissions, customs trade data for glycol feedstock flows, and SEC filings from petrochemical-integrated majors. Bottom-up volume triangulation across vehicle parc aging curves and top-down value estimation from specification-grade contract pricing were reconciled to produce segment outputs.
Across the analysis window, the analytical framework modeled vehicle type segmentation by powertrain thermal load characteristics, product type by base fluid and additive chemistry compliance tier, and distribution channel by digital platform penetration versus traditional jobber layers. CAGRs were derived from replacement cycle compression rates and specification complexity premium capture. Industry-specific forecast inputs included OEM service interval extension trajectories and REACH chemical restriction implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained fleet electrification pace or regulatory divergence between EPA and emerging Chinese GB standards would require recalibration. Forecasts reflect documented assumptions around ethylene glycol feedstock availability and formulation chemist labor market recovery. Revision becomes warranted when REACH additive restriction scope or EPA hazardous waste classification thresholds cross materiality boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Automotive Paint Robots Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market