
 Outboard Boats Market | 2026-2036
Outboard Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Outboard Boats Market Analysis
Commercial fishing operators and tourism charter fleets is reorganizing demand away from purely leisure buyers across the Outboard Boats Market. Brunswick Corporation leverages integrated manufacturing from hull casting to engine distribution across North American lake and coastal networks. White River Marine Group sustains dominant retail channel control through mass-market fiberglass and aluminum lines stocked at thousands of dealer locations. Groupe Beneteau anchors European production gravity with specialized saltwater hull designs exported to Mediterranean and Caribbean operators.
Outboard boats are self-propelled watercraft powered by detachable engines mounted on the transom, typically constructed from fiberglass, aluminum, or inflatable materials with hull lengths spanning small runabouts to extra-large offshore platforms. Fiberglass hulls command premium pricing in saltwater leisure and sport-fishing applications where structural rigidity and finish durability determine resale value. Four-stroke engine configurations now dominate new registrations as two-stroke displacement faces regulatory phase-out across multiple jurisdictions. Electric and hybrid propulsion systems represent the fastest-growing engine category, though from a small base concentrated in lake-restricted waterways and European urban boating zones.
EPA marine emissions standards and CARB regulations in the United States enforce nitrogen oxide and hydrocarbon limits that reshape engine architecture and disqualify non-compliant imports from market access. The EU Marine Strategy Framework Directive and REACH chemical restrictions on antifouling coatings add compliance layers for hull manufacturers exporting to European harbors. Stakeholders must monitor battery energy density thresholds and charging infrastructure deployment in freshwater lake districts, as electric propulsion viability hinges on mooring-side power availability rather than hull design alone.
Market Dynamics
EPA Tier 3 and CARB marine emissions standards are forcing a wholesale engine architecture transition across the United States, compressing two-stroke displacement while elevating four-stroke and electric propulsion investment cycles.
Growth Catalysts
- Charter fleet modernization:Tourism operators across coastal Florida and the Gulf of Mexico corridor are accelerating hull replacement schedules to meet customer expectations for lower-emission configurations.
- REACH chemical compliance:Antifouling coating restrictions in European harbors are stimulating demand for advanced hull materials that reduce maintenance cycles and extend operational lifespan.
- Electric propulsion maturation:Battery energy density improvements are unlocking viable range thresholds for freshwater lake districts previously inaccessible to zero-emission alternatives.
Market Restraints
- Aluminum price volatility:Mass-market hull manufacturers face margin compression from fluctuating raw material input costs across North American supply chains.
- Engine supplier concentration:Critical powertrain component sourcing clusters in specific coastal manufacturing zones, creating vulnerability to regional disruption events.
- Charging infrastructure gaps:Mooring-side power availability limitations constrain electric outboard adoption outside designated freshwater lake networks.
Strategic Opportunities
- Mediterranean charter expansion:Specialized saltwater hull designs from European producers are capturing share among Caribbean tourism operators seeking premium vessel specifications.
- EU Green Deal alignment:Maritime decarbonization incentives are creating procurement preference shifts toward hybrid propulsion configurations in urban European boating zones.
- Direct-to-operator digital channels:Fleet procurement platforms are disintermediating traditional dealer networks for commercial fishing and tourism buyers with standardized volume requirements.
Industry Challenges
- Marine technician scarcity:Four-stroke and electric powertrain servicing expertise lags behind installation volumes, extending downtime for commercial operators.
- Multi-jurisdiction certification complexity:Hull and engine manufacturers must synchronize EPA, CARB, and EU Marine Strategy Framework Directive approval timelines for export market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outboard Boats Market |
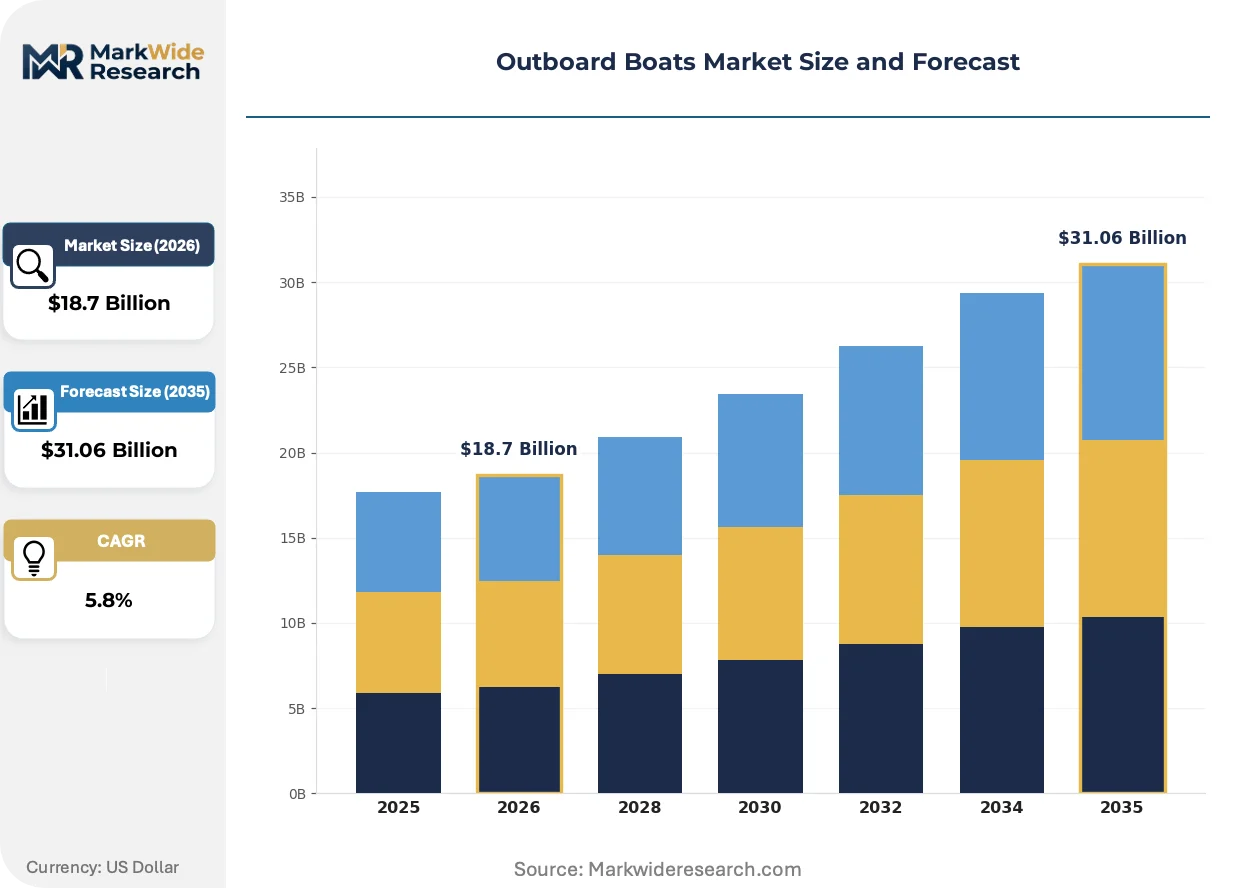
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Aluminum, Inflatable, Wooden Engine Type: Two-Stroke, Four-Stroke, Electric, Hybrid Size: Small, Medium, Large, Extra Large End User: Leisure, Commercial, Fishing, Tourism |
| Companies Covered | Brunswick Corporation, White River Marine Group, Groupe Beneteau, Polaris Inc., Campion Marine Inc., Cantieri Capelli SRL, Nimbus Group, Marine Products Corporation, Bombardier Recreational Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outboard Boats Market Emerging Trajectories
Propulsion technology diversification and regulatory compliance layering are fragmenting traditional product hierarchies while creating new competitive battlegrounds around energy storage integration and hull material specification.
Advanced lithium-ion battery systems are decomposing the historical displacement-to-power relationship that governed outboard engine selection. Commercial fishing operators in lake-restricted waterways are piloting electric configurations for trolling and low-speed maneuvering applications. This technology is decomposing the monopoly of internal combustion engines in sub-50 horsepower segments where range requirements align with daily operational patterns.
EPA marine emissions enforcement is tightening nitrogen oxide and hydrocarbon thresholds that reshape engine combustion architecture. The regulatory consequence is disqualifying non-compliant imports from United States market access while elevating domestic engineering investment. Saltwater sport-fishing hull manufacturers are responding by bundling Tier 3-certified powertrains as standard equipment to preempt buyer compliance anxiety.
Charter fleet procurement is consolidating around lifecycle cost models that internalize fuel consumption, maintenance intervals, and resale value trajectories. Traditional leisure buyer segments are fragmenting as commercial operators absorb larger vessel production capacity. This behavioral shift concentrates most visibly across the Florida Keys and Gulf Coast charter corridors where tourism demand density justifies fleet-scale investment programs.
Outboard Boats Market Segmentation
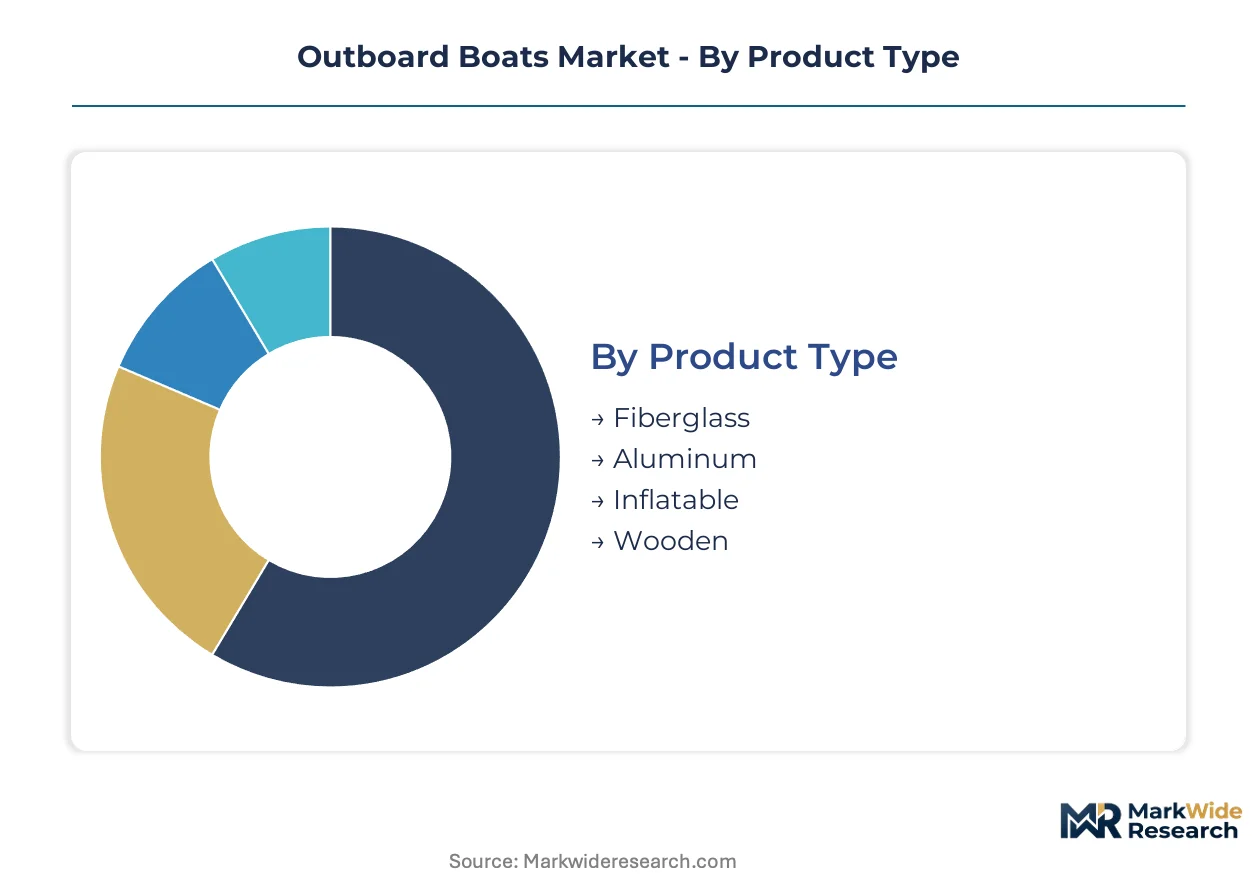
Segmentation in the outboard boats market reveals how regulatory pressure and end-use economics reshape procurement patterns across hull materials, propulsion architectures, and operational scale. Each dimension carries distinct geographic signatures and margin structures that determine manufacturer positioning strategies.
Product Type:
Fiberglass hull production concentrates in coastal Florida and Mediterranean export corridors, while aluminum fabrication dominates inland lake networks and mass-market retail channels. Wooden construction persists in artisanal pockets with negligible commercial scale.
- Fiberglass:Composite resin construction delivers structural rigidity and finish durability for saltwater sport-fishing applications. Demand clusters among Gulf Coast charter operators and Caribbean tourism fleets seeking resale value retention in corrosive marine environments. EPA Tier 3 compliance bundling with premium hull packages elevates specification requirements.
- Aluminum:Welded alloy construction offers weight advantages and impact resistance for freshwater recreational and utility applications. Mass-market retail distribution through North American lake networks sustains volume leadership despite raw material price volatility compressing manufacturer margins.
- Inflatable:Hypalon and PVC fabrications serve yacht tender and expedition diving segments requiring stowability and shallow-draft maneuverability.
- Wooden:Traditional plank and cold-molded construction persists in custom restoration and heritage craft niches with minimal production scale.
Fiberglass commands the established base. The steepest expansion runs through aluminum as lake-district participation broadens.
Engine Type:
Powertrain selection now follows regulatory jurisdiction boundaries more closely than horsepower requirements, with EPA and CARB enforcement creating divergent technology adoption curves across state lines.
- Four-Stroke:Overhead valve combustion architecture delivers fuel efficiency and emissions compliance for displacement ranges above 75 horsepower. Saltwater charter operators across Florida and Gulf Coast corridors specify four-stroke configurations to preempt customer preference shifts and regulatory enforcement actions.
- Electric:Lithium-ion battery systems with brushless DC motors unlock zero-emission operation for lake-restricted waterways under local combustion bans. Battery energy density improvements are extending viable range thresholds in freshwater districts with mooring-side charging infrastructure.
- Two-Stroke:Carbureted and direct-injection designs face regulatory phase-out across multiple United States jurisdictions, concentrating residual demand in price-sensitive utility segments.
- Hybrid:Parallel electric-combustion configurations pair range extension with emission reduction for urban European boating zones under EU Green Deal procurement incentives.
Four-Stroke retains volume dominance across saltwater applications. Electric propulsion gains share fastest where lake-district charging networks mature.
Size:
Hull length categories map directly to operational economics, with threshold effects at registration, licensing, and marina berth cost structures that fragment buyer behavior.
- Small:Runabouts and center consoles under 20 feet serve individual leisure buyers and inland fishing access. Mass-market retail channels stock aluminum and fiberglass configurations for impulse purchase patterns.
- Medium:20-30 foot platforms balance offshore capability with trailer transportability for coastal sport-fishing enthusiasts and small charter operations.
- Large:30-40 foot offshore platforms accommodate multi-day excursions and commercial passenger configurations requiring Coast Guard certification.
- Extra Large:Platforms exceeding 40 feet integrate cabin amenities and extended-range fuel systems for luxury charter and expedition fishing segments.
Medium sizes anchor production volumes. Extra Large configurations expand most quickly among tourism fleet consolidation programs.
End User:
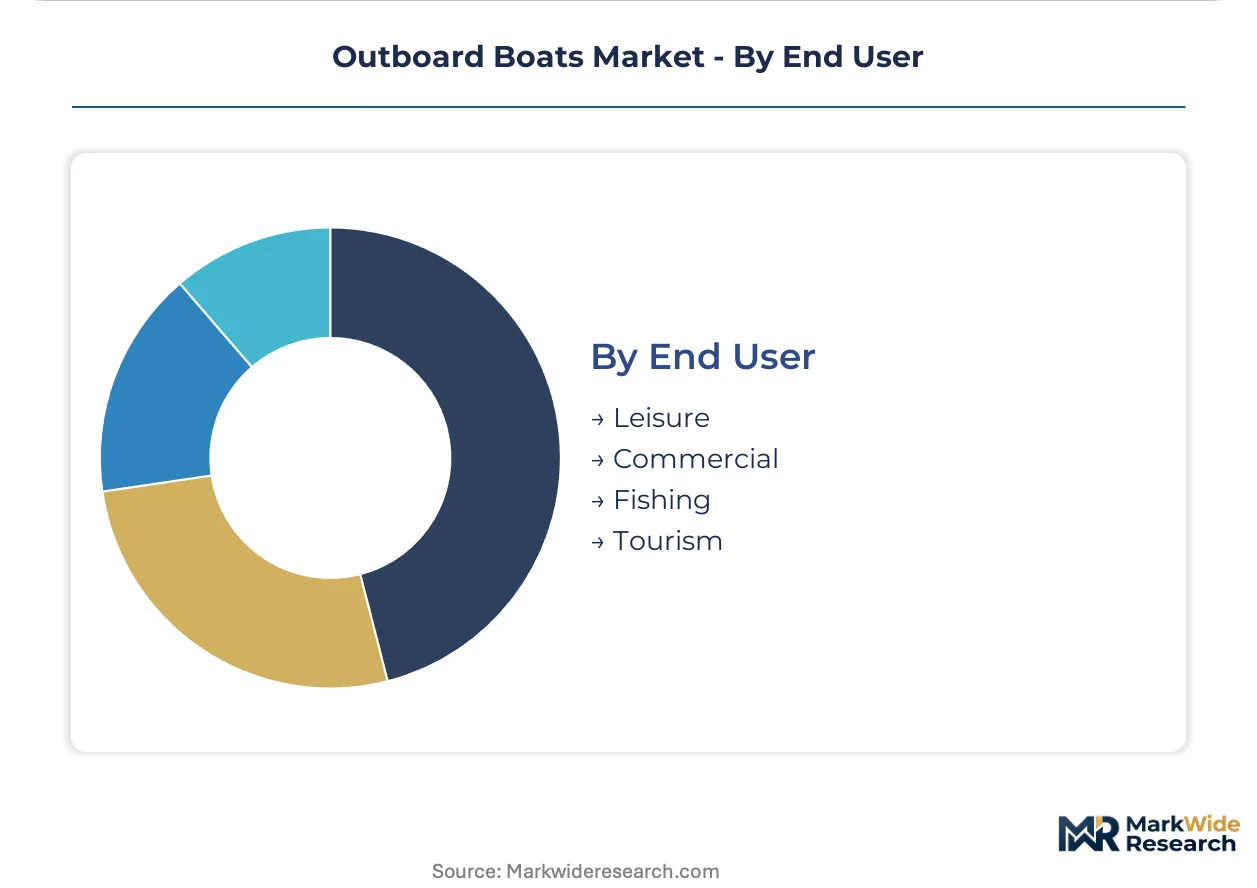
Demand composition is reorganizing as commercial operators absorb production capacity previously oriented toward individual leisure buyers, with lifecycle cost modeling displacing sticker-price sensitivity.
- Tourism:Charter fleet operators across Florida Keys and Gulf Coast corridors deploy volume procurement platforms to modernize aging hull inventories. Customer expectation for lower-emission configurations accelerates replacement schedules beyond historical depreciation cycles.
- Fishing:Commercial operators and recreational tournament participants prioritize hull durability and engine reliability for extended offshore operations. Four-stroke powertrain bundling dominates new acquisitions in this segment.
- Leisure:Individual buyers fragment across price tiers with aluminum runabouts for lake access and fiberglass sport-fishing platforms for coastal retirement migration patterns.
- Commercial:Utility and patrol applications specify aluminum durability for search-and-rescue, law enforcement, and facility maintenance operations.
Tourism operators now absorb the largest share of new hull output. The fishing segment maintains the most intensive specification requirements per vessel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine and hull manufacturing clusters in specific coastal zones dictate competitive positioning across the outboard boats market. Brunswick Corporation maintains integrated production from Wisconsin through Florida, while European specialists concentrate saltwater design expertise in Mediterranean export corridors.
United States
Charter fleet operators across coastal Florida and the Gulf of Mexico corridor drive hull replacement demand as tourism density justifies fleet-scale investment. EPA Tier 3 and CARB marine emissions standards enforce nitrogen oxide limits that disqualify non-compliant engine imports from market access. Brunswick Corporation anchors production gravity through integrated manufacturing from hull casting to engine distribution across North American lake and coastal networks.
France
Groupe Beneteau leverages specialized saltwater hull designs for Mediterranean and Caribbean export markets where premium specifications command pricing power. EU Marine Strategy Framework Directive and REACH chemical restrictions on antifouling coatings add compliance layers for hull manufacturers accessing European harbors. Production clusters in western France concentrate composite resin construction expertise for offshore sport-fishing platforms.
Canada
Bombardier Recreational Products anchors powertrain innovation from Quebec manufacturing bases serving North American freshwater and coastal segments. Canadian environmental regulations on marine emissions align with EPA thresholds, simplifying cross-border engine certification processes. Ontario and Quebec industrial corridors concentrate aluminum hull fabrication for mass-market lake networks.
Sweden
Nimbus Group exemplifies Nordic hull engineering for expedition and offshore configurations in Baltic and North Sea operating environments. EU Green Deal maritime decarbonization incentives stimulate procurement preference shifts toward hybrid propulsion in urban European boating zones. Gothenburg-area production facilities specialize in extended-range cabin amenities for luxury charter segments.
Italy
Cantieri Capelli SRL represents Mediterranean rigid-hull inflatable specialization for yacht tender and diving expedition applications. Italian harbor regulations under EU Marine Strategy Framework Directive enforce antifouling coating standards that stimulate advanced hull material demand. Adriatic coastal manufacturing zones concentrate shallow-draft maneuverability expertise for superyacht support vessels.
Outboard Boats Market Vendor Landscape
Concentration sits with integrated hull-engine manufacturers and mass-market retail channel controllers. The vendor base stratifies across three tiers: premium saltwater specialists with fiberglass composite expertise, aluminum fabricators serving lake-district volume, and inflatable specialists capturing yacht tender niches. Dominant competitive moves include backward integration into powertrain manufacturing and geographic expansion through dealer network acquisition.
Among North American integrated manufacturers, Brunswick Corporation and White River Marine Group exemplify divergent scale strategies. Brunswick anchors premium positioning through captive engine supply and saltwater hull design, while White River sustains mass-market dominance through aluminum and fiberglass lines stocked across thousands of dealer locations. European specialists Groupe Beneteau occupy a position bridging Mediterranean production gravity with Caribbean export demand.
| Leading Market Players |
|---|
| Brunswick Corporation |
| White River Marine Group |
| Groupe Beneteau |
| Polaris Inc. |
| Campion Marine Inc. |
| Cantieri Capelli SRL |
| Nimbus Group |
| Marine Products Corporation |
| Bombardier Recreational Products Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at integrated hull-engine manufacturing facilities in Wisconsin and Florida creates scale advantages that compress per-unit fixed costs while establishing price floors for independent aluminum fabricators. This concentration of production assets enables Brunswick Corporation and White River Marine Group to absorb raw material volatility that would destabilize smaller competitors, forcing pricing discipline across mass-market retail channels.
Pricing Analysis
Volume-discount tiering structures separate charter fleet procurement from individual leisure transactions, with tourism operators capturing standard-equipment bundling advantages unavailable to impulse buyers. Price differentiation hinges on EPA Tier 3 certification status and four-stroke engine displacement tiers, with compliant configurations commanding premiums over phase-out two-stroke alternatives. Pricing pressure stems from aluminum input cost volatility squeezing mass-market hull margins. Individual leisure buyers exhibit highest price sensitivity, while commercial charter operators prioritize lifecycle cost models over sticker prices.
Supply Chain Analysis
Inventory lead times for lithium-ion battery systems extend delivery windows for electric propulsion configurations beyond traditional combustion engine fulfillment cycles. Manufacturing concentration clusters in the United States, France, and Canada, with composite resin hull fabrication anchored in coastal Florida and Mediterranean export corridors. Supply chains draw from aluminum smelters, marine-grade fiberglass suppliers, and precision-machined powertrain components. Single-source vulnerability concentrates in specialized engine electronics sourced from specific coastal manufacturing zones. Distribution runs through captive dealer networks for premium saltwater hulls and mass-market retail locations for aluminum runabouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine technician scarcity for four-stroke and electric powertrain servicing creates a capability bottleneck that extends commercial operator downtime and inflates aftermarket labor premiums. This skill gap threatens fleet modernization timelines regardless of hull production capacity.
For Market Incumbents: Shield installed base profitability by captive supply chain control over Tier 3-certified engine distribution and accelerated technician certification programs. Backward integration into battery energy storage systems for electric propulsion lines secures component availability against supplier concentration risk. Prioritize dealer network acquisition in Gulf Coast charter corridors to preempt direct-to-operator procurement platforms.
For New Entrants and Emerging Players: EPA certification fast-track specialization for sub-50 horsepower electric configurations opens lake-district market access with lower regulatory barrier complexity than saltwater displacement ranges. Target freshwater recreational segments in North American lake networks where charging infrastructure deployment creates viable range thresholds absent from coastal applications. Pursue white-label powertrain supply agreements with established hull fabricators lacking captive engine manufacturing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated hull-engine manufacturers with captive aftermarket parts and service networks. Long-term viability favors acquisition targets with established EPA and CARB certification pipelines rather than pure-play hull fabricators dependent on third-party powertrain supply. Monitor battery energy density threshold announcements as the critical signal for electric propulsion inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Systems | Captive lithium-ion supply secures electric propulsion margins against component shortage risk. |
| Technician Certification Program Expansion | Four-stroke and electric servicing expertise closes commercial fleet downtime gaps. |
| Direct-to-Operator Procurement Platform | Digital fleet sales disintermediate dealer networks for standardized charter volume. |
| EU Green Deal Compliance Alignment | Hybrid propulsion configurations capture urban European boating procurement preference shifts. |
| Dealer Network Acquisition in Gulf Coast | Coastal Florida and Gulf of Mexico corridor control secures tourism fleet replacement demand. |
Methodological Framework
Desk research of trade customs data, EPA marine emissions filings, and hull manufacturer SEC disclosures preceded structured interviews with charter fleet operators, marine engine procurement directors, and dealer network managers. Primary fieldwork with tourism operators across Florida Keys and Gulf Coast corridors validated replacement schedule assumptions, while secondary triangulation against CARB registration databases and EU Marine Strategy Framework Directive compliance records anchored segmentation splits. Bottom-up hull production estimates and top-down tourism expenditure models converged through iterative reconciliation.
Variance decomposition across product type, engine architecture, hull size, and end-user segments isolated growth contribution by dimension over the projection horizon. CAGRs derived from logistic diffusion curves for electric propulsion adoption layered onto replacement-cycle baselines for combustion engine fleets. Forecast inputs incorporated battery energy density improvement trajectories, marina charging infrastructure deployment schedules, and EPA enforcement intensity assumptions.
Underlying assumptions cover regulatory compliance timeline adherence and aluminum price band stability, with deviation risk concentrated in electric charging infrastructure deployment pace and marine technician training program throughput. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Small Boats Market
Marine Vehicles
LNG Marine Engine Market