
 Air Cargo Container Market | 2026-2036
Air Cargo Container Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cargo Container Market Analysis
A capital-intensity divergence between asset-heavy ULD lessors and lightweight composite specialists is redrawing competitive boundaries in air cargo container supply. TransDigm Group sustains dominance in engineered aerospace components through backward integration into precision manufacturing. Envirotainer AB specializes in active temperature-control systems for pharmaceutical lanes, occupying a defensible premium niche. ACL Airshop LLC leverages its global pool network to compete on turnaround velocity and fleet utilization rates.
Air cargo containers are standardized load-bearing enclosures—typically fabricated from aluminum alloys, fiber-reinforced composites, or hybrid sandwich panels—engineered to interface with aircraft cargo-handling systems and maintain structural integrity under flight loads, pressurization cycles, and rapid temperature swings. Their primary purpose is to maximize volumetric efficiency, protect goods from environmental stress, and enable seamless intermodal transfer between aircraft, trucks, and warehouses. Composite material adoption is accelerating fastest among container types as airlines pursue fuel-burn reductions, while aluminum ULDs retain the largest installed base and aftermarket revenue pool. E-commerce retailers represent the fastest-growing end-user channel, driving demand for half-size and quarter-size containers optimized for parcel-density sorting.
FAA airworthiness directives and EASA CS-25 certification requirements govern structural performance and fire-resistance standards for all containers entering Western aircraft fleets, effectively filtering out uncertified manufacturers and concentrating supply among approved production facilities. The EU Green Deal's emerging sustainable aviation fuel mandates and carbon-border adjustments will progressively tie container procurement decisions to lifecycle emissions metrics and recyclability disclosures. Stakeholders must monitor how MEE enforcement of China's dual carbon goals reshapes composite material sourcing and whether India's PLI scheme for aerospace components attracts container assembly migration.
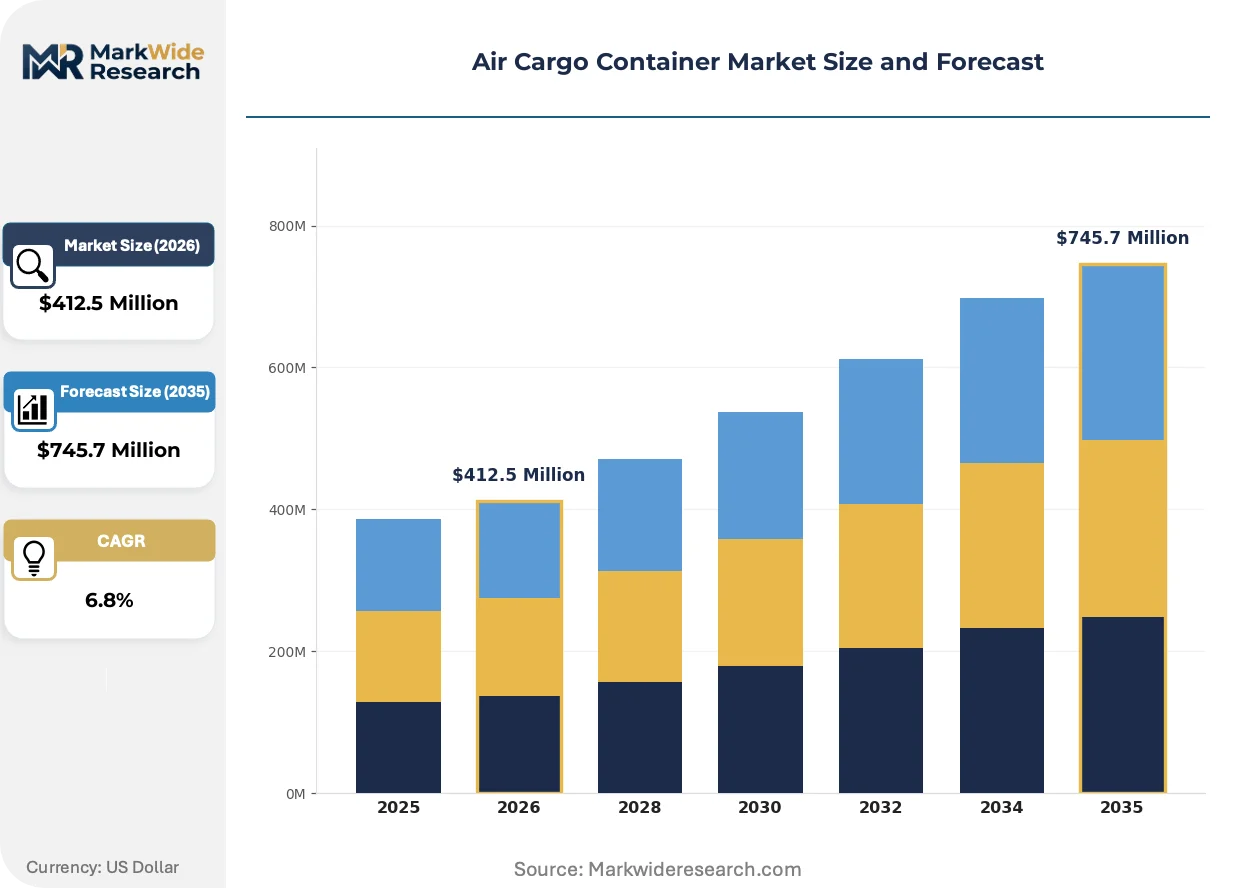
Market Dynamics
Composite sandwich panels are displacing aluminum alloys as the dominant structural material in air cargo container manufacturing, driven by airline fuel-economy mandates and the EU Green Deal's lifecycle emissions disclosure requirements. This material transition is compressing production economics for legacy metal-forming operations while rewarding precision composite fabricators with aerospace certification credentials.
Growth Catalysts
- Pharmaceutical cold chain expansion:Temperature-controlled containers now dominate high-value biologics lanes, with active heating-cooling systems replacing passive insulation for regulatory compliance across FDA and EMA jurisdictions.
- EU Green Deal SAF mandates:Sustainable aviation fuel requirements are tying container procurement to carbon-intensity metrics, accelerating demand for lightweight composite designs that reduce fuel burn per ton-mile.
- E-commerce parcel density optimization:Half-size and quarter-size containers engineered for automated sorting systems are capturing volume from traditional full-size ULD configurations in express courier networks.
Market Restraints
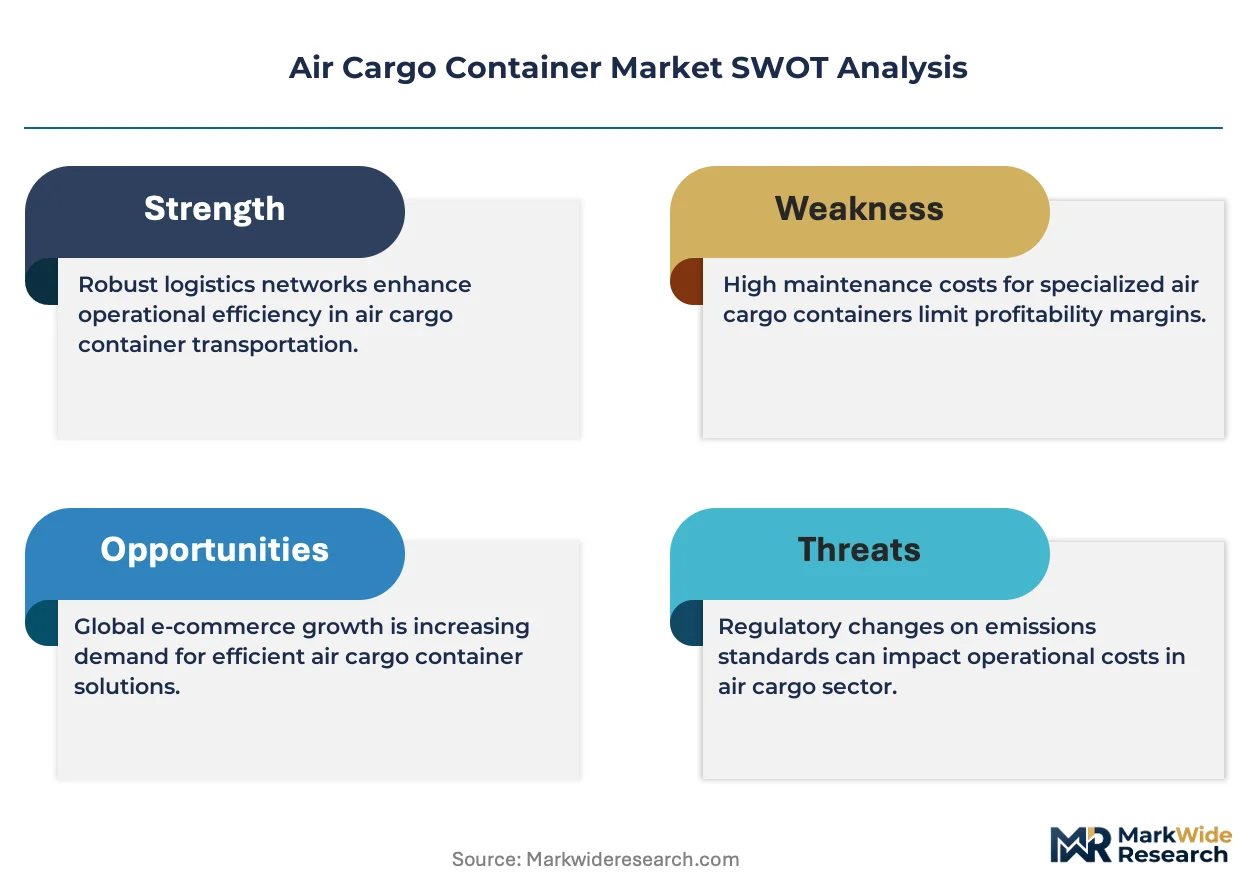
- Aluminum alloy price volatility:Raw material input costs for legacy metal containers fluctuate with LME spot pricing, compressing margins for manufacturers without composite diversification.
- Certification concentration in Germany and France:EASA CS-25 approved production facilities cluster in specific European manufacturing corridors, creating supply bottlenecks for new market entrants.
- Fire-resistant material technical limitations:FAA airworthiness directives for improved burn-through resistance require expensive phenolic resin formulations that extend production cycles.
Strategic Opportunities
- India PLI scheme for aerospace components:Production-linked incentives are attracting container assembly migration to Indian manufacturing zones, offering cost arbitrage against European production.
- Active temperature-control convergence with IoT telemetry:Real-time cargo monitoring systems integrated into container architecture create premium pricing power in pharmaceutical lanes.
- Recyclability disclosure as procurement differentiator:Airlines responding to EU carbon-border adjustments are prioritizing containers with verified end-of-life material recovery pathways.
Industry Challenges
- Aerospace composite technician scarcity:Precision layup and autoclave curing expertise concentrates in established aviation manufacturing clusters, constraining capacity expansion.
- FAA-EASA dual certification timeline compression:Container designs must satisfy divergent fire-resistance test protocols, extending approval cycles and freezing product iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cargo Container Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: ULD, Net Container, Pallet, Rigid Container Material: Aluminum, Plastic, Composite, Steel End User: Aerospace Logistics, Freight Forwarders, E-commerce Retailers, Airlines Size: Standard, Half-Size, Quarter-Size, Oversized |
| Companies Covered | ACL Airshop LLC, Envirotainer AB, TransDigm Group, Unilode Aviation Solutions Switzerland Ltd., Nordisk Aviation Products AS, Brambles, DoKaSch GmbH, CSafe Global, Safran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cargo Container Market Emerging Trajectories
Digital integration and material science advances are converging to transform container functionality from passive cargo enclosure to active supply chain node. These developments are reshaping competitive advantage toward data-enabled service models and certified lightweight engineering.
Carbon-fiber-reinforced polymer sandwich construction is displacing riveted aluminum monocoque designs in new-build container programs. Pharmaceutical logistics operators and premium freight forwarders are specifying composite ULDs for temperature-sensitive lanes, recognizing that reduced tare weight translates directly into payload revenue recovery. This material transition is displacing legacy metal-forming capacity while consolidating manufacturing share among aerospace-certified composite specialists.
EASA CS-25 fire-resistance amendments and FAA airworthiness directives issued since 2023 have tightened burn-through and flame-penetration standards for all containers entering Western fleets. Container manufacturers must now submit to extended certification testing protocols for phenolic-core and thermoplastic composite alternatives, filtering supply toward approved production facilities. Pharmaceutical and hazardous cargo segments are absorbing the steepest compliance costs, passing through premium pricing to secure certified container availability.
Airline procurement departments are unbundling container acquisition from full-service leasing arrangements, demanding standalone asset purchases with transparent lifecycle cost modeling. This buying-pattern shift disrupts traditional ULD lessor economics and rewards manufacturers with direct sales capabilities and aftermarket parts networks. The unbundling trend is most visible in North American and European flag carriers restructuring their ground equipment fleets.
Air Cargo Container Market Segmentation
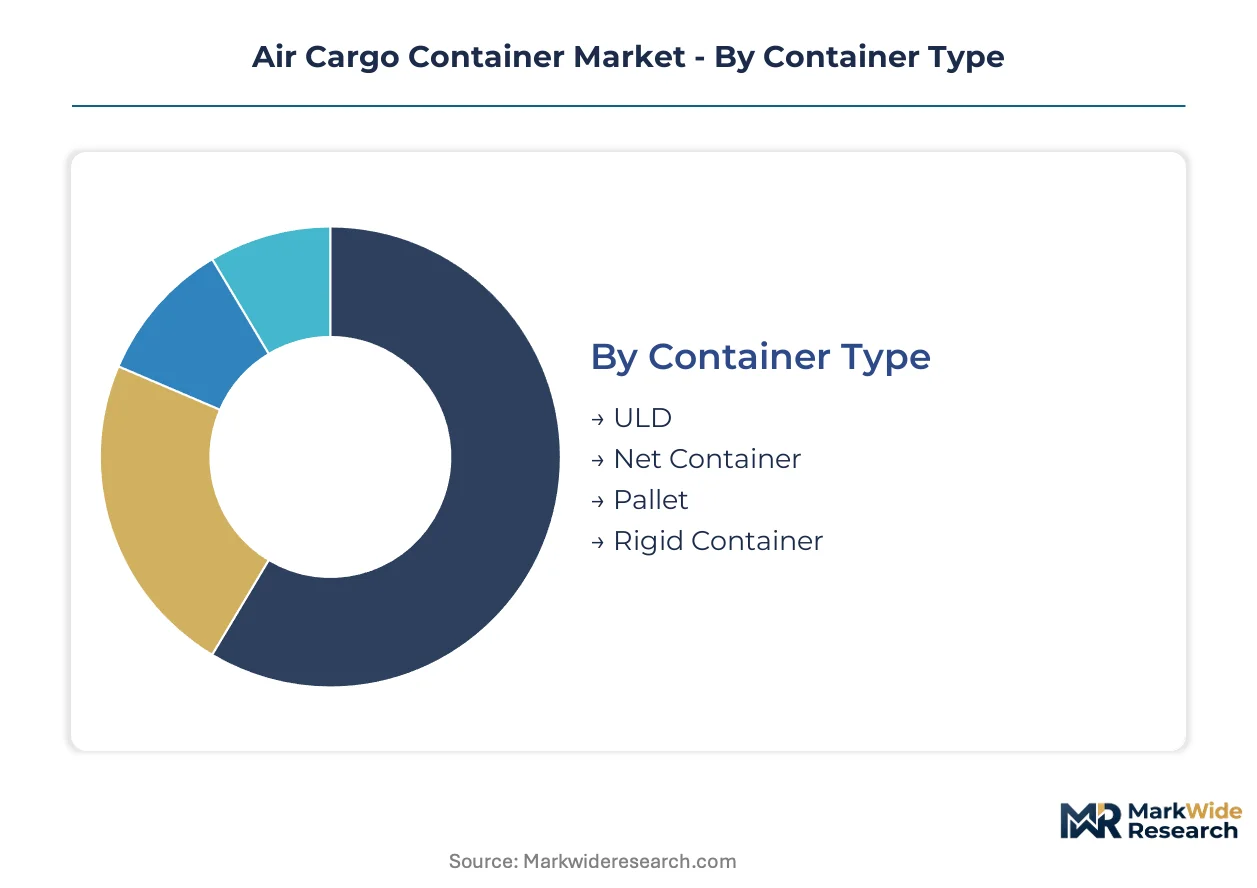
Container segmentation in air cargo logistics directly shapes procurement economics and fleet utilization strategies. Material composition and dimensional specifications determine fuel-burn penalties, while end-user channel selection governs turnaround velocity requirements and pricing power.
Container Type:
Margin pools concentrate in temperature-controlled ULD configurations serving pharmaceutical lanes, where certification premiums offset higher manufacturing complexity.
- ULD:Unit load devices dominate installed base economics through standardized interfacing with aircraft cargo-handling systems and ground support equipment. Airlines in Germany's Frankfurt cargo corridor prioritize ULD pool-sharing arrangements to maximize asset turns across high-frequency pharmaceutical and e-commerce lanes.
- Net Container:Lightweight fabric-reinforced netting systems capture volume in irregular cargo and perishable horticulture segments where tare weight reduction drives payload recovery. Southeast Asian flower export operations specify net containers for rose and orchid shipments to European markets.
- Pallet:Flat-load platforms serve bulk commodity and military logistics with minimal structural overhead.
- Rigid Container:Fixed-wall enclosures protect high-value electronics and precision instruments from handling damage.
The dominant share belongs to ULD, while Net Container is closing the gap fastest.
Material:
Cost tier stratification separates legacy metal suppliers from composite specialists commanding aerospace certification premiums.
- Aluminum:Riveted aluminum alloy monocoque construction retains the largest installed base and aftermarket parts revenue pool across legacy fleets. Indian MRO facilities concentrate aluminum container refurbishment capacity to serve Middle Eastern and African airline operators.
- Composite:Carbon-fiber-reinforced polymer sandwich panels displace metal in new-build programs seeking EU Green Deal compliance and fuel-burn reductions. EASA CS-25 certified production facilities in France and Germany capture premium pricing for phenolic-core composite ULDs serving temperature-controlled pharmaceutical lanes.
- Plastic:Thermoformed polymer containers address disposable and single-use applications in infectious substance transport.
- Steel:Heavy-gauge steel reinforcement serves hazardous cargo and military ordnance containment with maximum structural integrity.
Aluminum holds the largest revenue base, though Composite is expanding most quickly.
End User:
Application concentration varies sharply between asset-heavy airlines and asset-light freight intermediaries with divergent procurement patterns.
- Airlines:Flag carriers and cargo specialists deploy owned or leased ULD fleets with dedicated ground handling infrastructure. Lufthansa Cargo and Air France-KLM Martinair maintain captive container pools optimized for hub-and-spoke operations through Frankfurt and Amsterdam.
- E-commerce Retailers:Parcel-density optimization drives specification of half-size and quarter-size containers for automated sorting systems. Amazon Air and DHL Express networks demand rapid-turn container configurations compatible with midnight-sort hub operations.
- Freight Forwarders:Neutral intermediaries rely on airline-provided equipment or short-term leases for spot market cargo.
- Aerospace Logistics:AOG and MRO parts distribution requires specialized container formats for engine and component transport.
Airlines command the dominant procurement volume, while E-commerce Retailers are gaining share fastest.
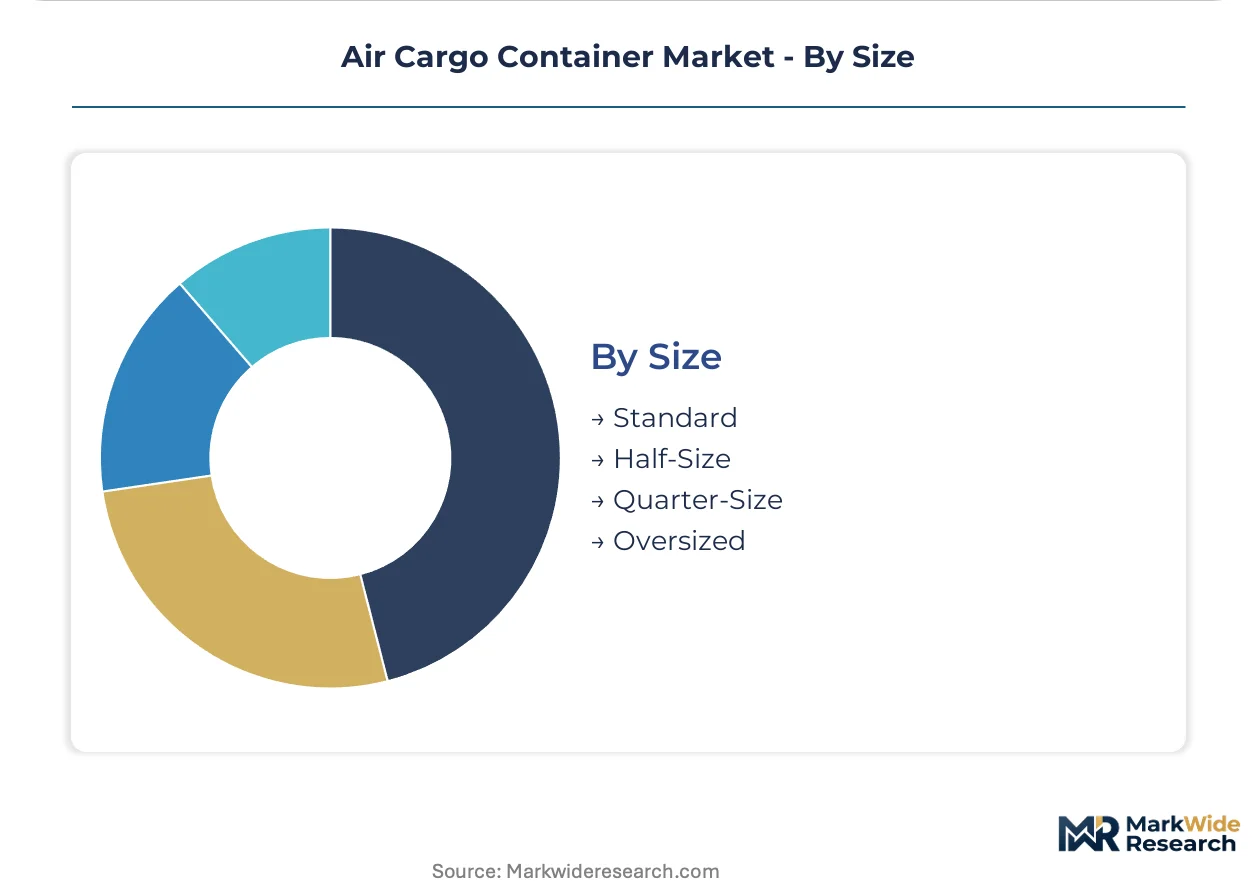
Size:
Volume distribution reflects the tension between main-deck cargo optimization and lower-hold compartment constraints.
- Standard:Full-size containers maximize volumetric efficiency on widebody main decks and account for the bulk of long-haul fleet investment. Boeing 777F and Airbus A350F operators specify standard ULDs for trans-Pacific and Europe-Asia trunk routes.
- Half-Size:Intermediate dimensions balance load flexibility with narrowbody compatibility for regional express networks. FedEx and UPS narrowbody feeders deploy half-size containers across European and North American short-haul networks.
- Quarter-Size:Compact formats serve parcel courier density requirements and last-mile intermodal handoffs.
- Oversized:Custom dimensions accommodate aerospace components, heavy machinery, and project cargo exceeding standard envelope limits.
Standard size leads deployment, while Half-Size is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redrawing container deployment patterns across major trade corridors. Net exporting regions prioritize lightweight composite designs to maximize payload revenue on outbound legs, while import-heavy markets emphasize rapid-turn pool networks to minimize dwell times.
United States
E-commerce parcel density requirements drive specification of half-size containers for automated sorting hubs. FAA airworthiness directives for fire-resistant materials filter supply toward certified composite fabricators. The Memphis and Louisville cargo clusters anchor express courier networks with dedicated ULD pools optimized for overnight sort operations.
Germany
Pharmaceutical cold chain exports to Asia and North America sustain premium demand for temperature-controlled ULD configurations. EASA CS-25 certification requirements concentrate approved manufacturing in the Frankfurt-Rhine-Main logistics corridor. The Rhine-Neckar industrial zone hosts composite specialists serving Lufthansa Cargo's hub-and-spoke operations.
China
Dual carbon goals under MEE enforcement accelerate airline procurement of fuel-saving composite containers on domestic trunk routes. GB standards for aviation materials progressively align with FAA and EASA fire-resistance benchmarks. The Yangtze River Delta manufacturing belt supplies carbon-fiber sandwich panels to both domestic carriers and export markets.
India
PLI scheme incentives for aerospace components attract container assembly migration from European production zones. DGFT export promotion programs target pharmaceutical cold chain logistics as a priority sector for ULD fleet expansion. The Bangalore-Chennai aerospace corridor develops precision composite fabrication capacity for regional airline customers.
United Arab Emirates
Trans-shipment cargo volumes through Dubai International and Al Maktoum International demand flexible container pool-sharing arrangements across multiple airline operators. The country's national aviation regulator enforces fire-resistance standards equivalent to FAA and EASA protocols. Jebel Ali's free zone logistics parks concentrate third-party ULD management providers serving Gulf carrier networks.
Air Cargo Container Market Vendor Landscape
Concentration sits with aerospace-certified composite specialists and global ULD lessors operating pool networks. The vendor base stratifies across three tiers: asset-heavy lessors commanding fleet utilization economics, precision fabricators with EASA and FAA credentials capturing certification premiums, and regional metal-forming operations serving price-sensitive replacement demand. Dominant competitive moves include backward integration into carbon-fiber supply chains and strategic partnerships with pharmaceutical logistics operators for temperature-controlled fleet deployment.
Among the named participants, TransDigm Group exemplifies the precision-engineering archetype through its aerospace components heritage, while Envirotainer AB occupies a defensible position in active temperature-control systems. ACL Airshop LLC represents the pool-network model competing on turnaround velocity and global asset coverage. DoKaSch GmbH and CSafe Global sit within the certified-specialist tier serving pharmaceutical cold chain requirements.
| Leading Market Players |
|---|
| ACL Airshop LLC |
| Envirotainer AB |
| TransDigm Group |
| Unilode Aviation Solutions Switzerland Ltd. |
| Nordisk Aviation Products AS |
| Brambles |
| DoKaSch GmbH |
| CSafe Global |
| Safran |
| Others |
Supply Flow & Price Mechanics
Asset utilization rates above 80% in Frankfurt-Rhine-Main manufacturing corridors establish scale thresholds that filter out sub-scale composite fabricators and set price floors for EASA CS-25 certified ULD production. This concentration dynamics rewards backward-integrated precision manufacturers with aerospace credentials while compressing margins for legacy metal-forming operations dependent on volatile LME aluminum inputs.
Pricing Analysis
Airline procurement teams anchor container pricing through unbundled asset purchases with transparent lifecycle cost modeling. Three-tier pricing structure across active temperature-control, passive composite, and legacy aluminum configurations reflects certification grade and fuel-burn reduction potential. Cost compression in aluminum ULD tiers is intensifying because raw material volatility erodes fixed-contract margins. E-commerce retailers exhibit highest price sensitivity, while pharmaceutical logistics operators absorb premium pricing for FDA-EMA compliant active heating-cooling systems.
Supply Chain Analysis
Carbon-fiber prepreg supply from Japan's Toray and Germany's SGL Carbon underwrites composite sandwich panel production for EU Green Deal compliant container programs. Manufacturing capacity concentrates in Germany, France, and emerging zones in India under PLI scheme incentives. Raw material sourcing draws from aerospace-certified resin formulators and autoclave equipment fabricators in Italy and the United States. Single-source vulnerability in phenolic-core formulations creates exposure to FAA-EASA fire-resistance test protocol revisions. Distribution runs through airline captive pools, third-party ULD lessors, and direct manufacturer sales to freight forwarders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air cargo container demand sits in early-cycle expansion as pharmaceutical cold chain logistics penetration accelerates across FDA and EMA jurisdictions. Temperature-controlled ULD adoption for biologics transport represents the primary tailwind justifying capacity investment ahead of fleet replacement cycles.
For Market Incumbents: Secure EASA CS-25 and FAA dual certification for phenolic-core composite designs before regulatory timelines compress further. Deepen backward integration into carbon-fiber supply chains to offset aerospace prepreg price volatility and defend margin position against emerging Indian assembly operations attracted by PLI incentives. For New Entrants and Emerging Players: Anchor in India's Bangalore-Chennai aerospace corridor to exploit production-linked incentive arbitrage against European manufacturing costs. Target net container segments serving Southeast Asian perishable horticulture exports where tare weight sensitivity exceeds certification premium tolerance. Pursue direct sales relationships with Middle Eastern trans-shipment operators seeking flexible pool-sharing alternatives to legacy lessor networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ULD lessors operating global pool networks with pharmaceutical cold chain specialization. Long-term viability over a 5-10 year horizon favors asset-light telemetry-integrated service models over pure manufacturing exposure. Monitor MEE enforcement of China's dual carbon goals as the inflection signal for composite container procurement acceleration on domestic trunk routes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Fiber Supply | Captive prepreg sourcing insulates margin from aerospace material cost volatility and secures allocation priority. |
| IoT Telemetry Platform Integration | Real-time cargo monitoring embedded in container architecture commands premium pricing in pharmaceutical lanes. |
| EASA-FAA Dual Certification Investment | Approved production status filters competition and concentrates supply among qualified manufacturing facilities. |
| India PLI Scheme Manufacturing Migration | Cost arbitrage against European production attracts container assembly to emerging aerospace corridors. |
| Pharmaceutical Cold Chain Fleet Partnership | Dedicated temperature-controlled ULD deployment secures long-term offtake from biologics logistics operators. |
Methodological Framework
A spread of perspectives from airline procurement directors, ULD pool network managers, pharmaceutical logistics operators, and composite manufacturing engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EASA certification databases, FAA airworthiness directive filings, EU Green Deal policy documents, and customs trade data tracking carbon-fiber prepreg flows. Bottom-up container deployment estimates triangulated against top-down airline fleet expansion projections.
Segmentation dimensions modeled include container type, material composition, end-user channel, and dimensional specifications across the projection horizon. CAGRs were derived from installed base replacement cycles, pharmaceutical cold chain penetration curves, and composite adoption rates in new-build programs. Industry-specific forecast inputs incorporated sustainable aviation fuel mandate compliance timelines and MEE enforcement patterns for dual carbon goals.
Decision-makers should treat outputs as directional under assumptions of stable FAA-EASA regulatory convergence and continued EU Green Deal implementation; material deviation in certification timelines or carbon-border adjustment scope would warrant model refresh. Practitioners should keep alternative scenarios live as aerospace composite technician scarcity and India PLI scheme uptake rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Automotive Logistics Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
Spain Pharmaceutical Logistics Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Cloud Logistics Market