
 Amphibious Vehicle Market | 2026-2036
Amphibious Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Amphibious Vehicle Market Intelligence
Defense procurement channels across NATO and Indo-Pacific allies are reshaping how amphibious platforms reach end users, with prime contractors now competing directly for national fleet modernization tenders. BAE Systems leverages its long-running relationship with the UK Ministry of Defence to sustain orders for armored swimming vehicles. General Dynamics dominates US military contracting through its Amphibious Combat Vehicle production line. Rheinmetall anchors European supply by specializing in tracked amphibious systems for Bundeswehr requirements.
An amphibious vehicle integrates waterproof hull architecture with terrain-adaptive propulsion to transit seamlessly between land and water environments, typically employing corrosion-resistant aluminum or composite hulls rated for specific draft depths and wave heights. Its primary purpose spans military assault landing, emergency flood response, and remote cargo access where infrastructure is absent or degraded. Military-type platforms command the largest value share given armor integration and weapons-system compatibility, while electric propulsion segments are gaining traction as battery energy density improves for silent littoral approaches. Search and rescue applications attract premium pricing due to night-operability and medical-evacuation equipment requirements.
FDA standards govern onboard medical equipment for rescue variants, while EPA emissions rules constrain diesel engine configurations in US-operated units. The EU Green Deal and F-Gas Regulation push European manufacturers toward hybrid architectures, with EMA-equivalent marine certification bodies validating hull integrity standards. Stakeholders must monitor how NATO interoperability specifications and national content requirements evolve, as these will determine which propulsion and armor packages qualify for upcoming multi-billion-dollar fleet renewals.
Market Dynamics
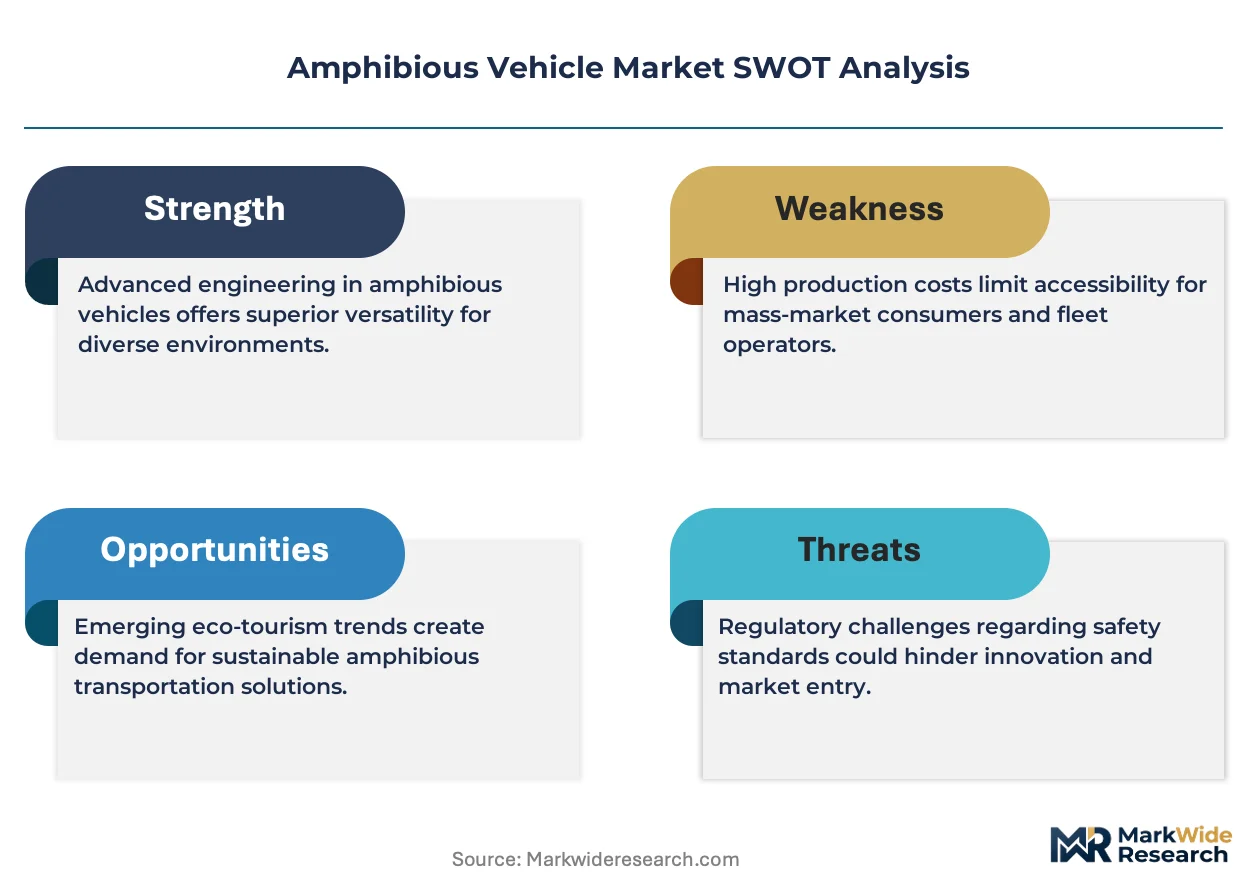
Defense procurement consolidation around NATO and Indo-Pacific fleet modernization is compressing supplier qualification timelines while elevating hybrid-electric propulsion from optional to mandatory in tender specifications.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V emissions mandates:Regulatory pressure on diesel particulate limits is forcing engine architecture redesigns that favor hybrid-electric systems with marine-grade battery packs.
- Japan and Australia's littoral defense procurement:National fleet replacement programs are issuing multi-year production contracts for armored swimming vehicles with integrated command systems.
- Aluminum-hull welding automation:Robotic friction stir welding is reducing hull production cycle times and enabling corrosion-resistant designs rated for higher wave heights.
Market Restraints
- Lithium-ion battery supply concentration:Cell production for marine-grade energy storage clusters in East Asian manufacturing hubs, creating single-source vulnerability for Western prime contractors.
- Armor-grade steel alloying cost volatility:Nickel and molybdenum price swings directly impact tracked amphibious platform margins, with no near-term substitution pathway.
- Hydrodynamic testing facility scarcity:Only three NATO-certified wave tanks can validate full-scale hull designs, creating 18-month queue delays for new entrants.
Strategic Opportunities
- Indonesia and Philippines archipelago logistics:Island chain connectivity gaps create demand for medium-tonnage cargo amphibians without existing infrastructure dependence.
- FEMA and state-level disaster response contracting:Federal emergency management frameworks now specify amphibious flood rescue capabilities in annual equipment grants to municipal agencies.
- EU Green Deal public procurement directives:Carbon footprint scoring in defense tenders awards contract preference points for hybrid propulsion, accelerating technology uptake.
Industry Challenges
- Marine engineer and naval architect talent pipeline:Universities have reduced specialized hydrodynamics programs, forcing manufacturers to train hull designers in-house over 24-month cycles.
- Ballistic protection and buoyancy trade-off certification:NATO STANAG validation requires iterative physical testing that cannot be simulation-accelerated, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphibious Vehicle Market |
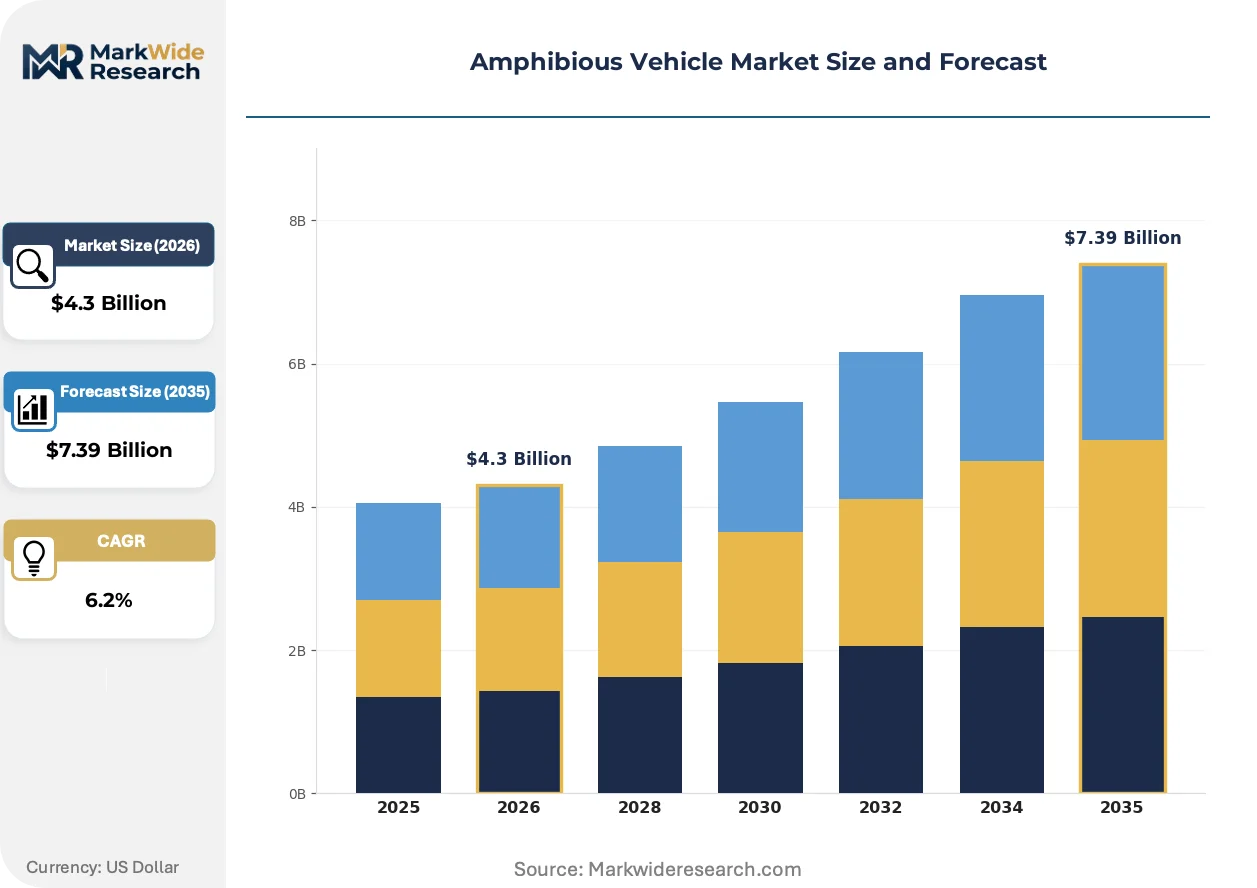
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $7.39 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Personal, Military, Commercial, Rescue, Recreational, Utility Propulsion: Hydraulic, Electric, Diesel Engine, Gasoline Engine, Hybrid, Jet Drive Application: Search and Rescue, Construction Support, Tourist Transport, Border Patrol, Firefighting, Cargo Delivery End User: Defense Forces, Emergency Services, Construction Firms, Tourism Operators, Agricultural Enterprises, Logistics Providers |
| Companies Covered | Hanwha Aerospace, Hydratrek, Inc., BAE Systems plc, Wetland Equipment Company, Wilco Manufacturing L.L.C., General Dynamics Corporation, Hitachi Construction Machinery Co., Ltd., Griffon Hoverwork, Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphibious Vehicle Market Strategic Shifts & Innovations
Propulsion architecture, regulatory compliance frameworks, and defense procurement operating models are simultaneously transforming how amphibious platforms are specified, built, and fielded.
Hybrid-electric drivetrain technology is hybridizing military and commercial amphibious vehicle design by enabling silent waterborne approaches and reduced thermal signatures. Marine Corps and special operations units are specifying these systems in 40% of new littoral platform tenders. The technology is hybridizing competitive requirements, merging automotive battery management with naval architecture certification standards into unified procurement specifications.
REACH chemical registration and the EU F-Gas Regulation are restricting hydrofluorocarbon-based fire suppression and certain composite resin systems in European-built hulls. Manufacturers must reformulate interior materials and thermal management fluids to maintain CE marking and EMA-equivalent marine type approval. Rescue and medical-evacuation variants face the tightest compliance deadlines, with 2027 implementation forcing redesign cycles.
Defense agencies are consolidating fleet modernization decisions into centralized program offices with technical authority over previously decentralized base-level purchasing. This buyer concentration is compressing supplier negotiation leverage and favoring prime contractors with established NATO STANAG certification records. The shift is most pronounced in US Marine Corps and UK Ministry of Defence contracting, where single-source awards now dominate armored swimming vehicle procurement.
Amphibious Vehicle Market Segmentation
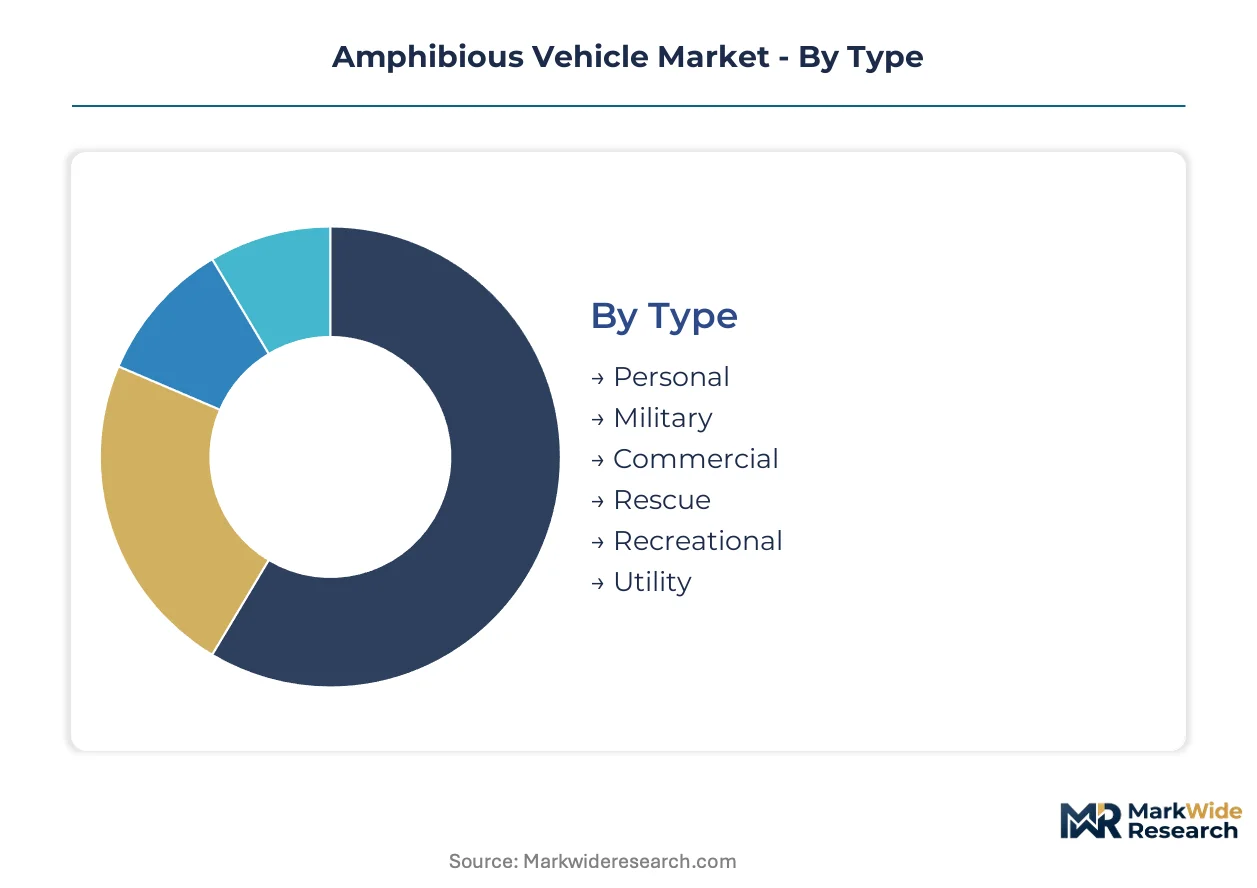
Segmentation in the amphibious vehicle market reveals how procurement cycles, regulatory pressures, and mission requirements fragment demand across fundamentally different use cases. Each dimension—vehicle type, propulsion method, application focus, and end-user category—operates on distinct replacement timelines and qualification standards that shape supplier strategy.
Type:
Replacement cycles stretch from 5-year recreational turnover to 25-year military platform lifespans, creating tiered revenue predictability for manufacturers.
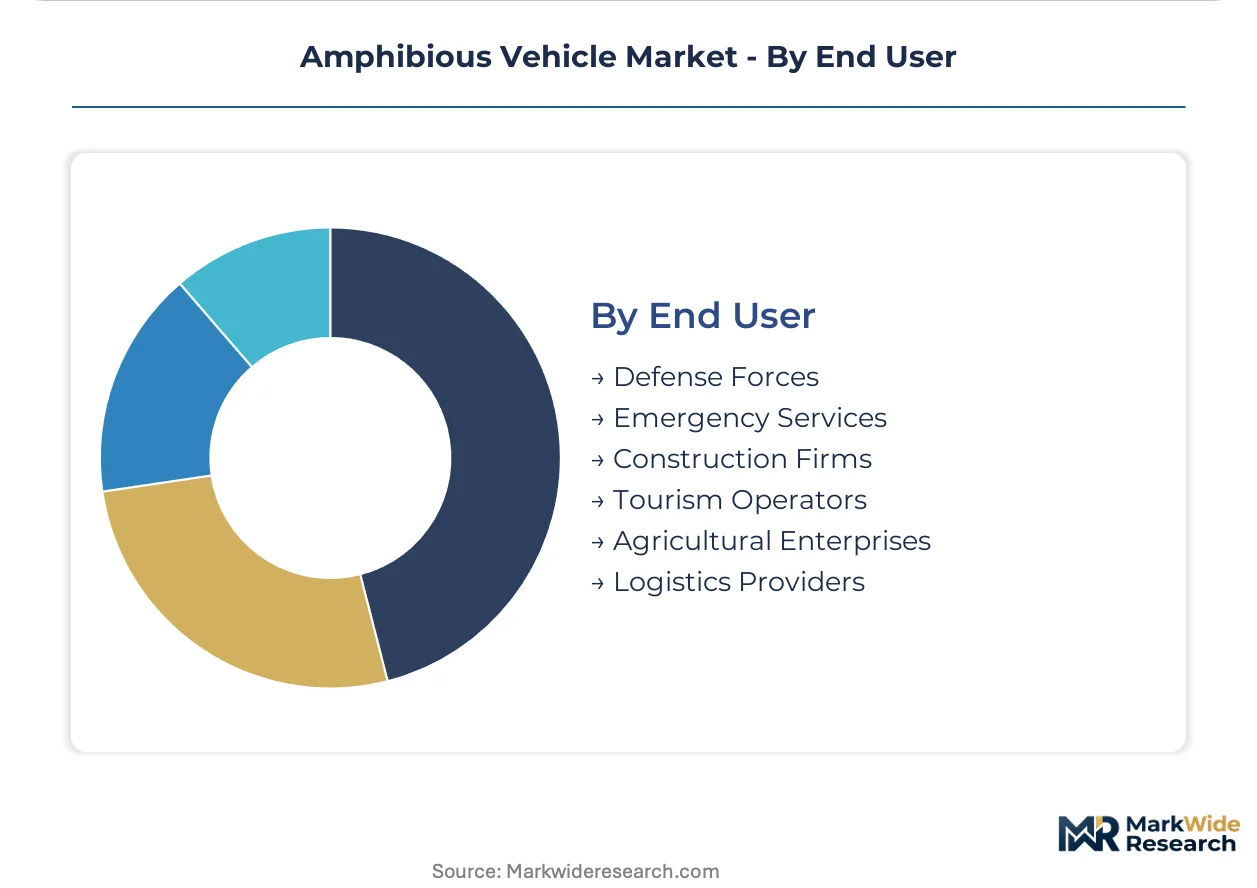
- Military:Armored swimming vehicles integrate ballistic protection with corrosion-resistant hull architectures rated for specific draft depths. NATO fleet modernization programs in the United States, United Kingdom, and Japan concentrate multi-year production contracts for these platforms, though armor-grade steel alloying cost volatility compresses margins.
- Rescue:Medical-evacuation variants carry FDA-certified onboard equipment and night-operability systems for flood response scenarios. FEMA and state-level disaster management agencies in the United States drive specification requirements through annual equipment grant frameworks.
- Commercial:Cargo-oriented designs prioritize payload capacity over speed for remote infrastructure access.
- Utility:General-purpose platforms serve agricultural and industrial applications with standardized hull configurations.
- Personal:Consumer-oriented amphibious cars and ATVs face recreational spending cyclicality.
- Recreational:Leisure craft emphasize comfort features over operational endurance for tourism and private use.
Military platforms anchor the volume base while Rescue variants gain share at the steepest rate due to climate-adapted emergency procurement.
Propulsion:
Cost tiers separate legacy combustion systems from emerging electric architectures, with regulatory compliance costs widening the pricing gap between tiers.
- Hybrid:Dual-mode drivetrains combine marine-grade battery packs with range-extending combustion for silent littoral approaches. United States Marine Corps specifications now mandate hybrid-electric options in 40% of new tenders, with EU Green Deal procurement directives awarding preference points for carbon footprint scoring.
- Electric:Pure battery systems eliminate thermal signatures entirely but face lithium-ion cell supply concentration risks in East Asian manufacturing hubs.
- Diesel Engine:Traditional powerplants dominate existing fleets but require redesign for EPA Tier 4 Final and EU Stage V particulate limits.
- Hydraulic:Fluid-power transmission suits heavy-lift cargo applications with constant torque requirements.
- Gasoline Engine:Lighter power-to-weight ratios serve recreational and personal vehicle segments.
- Jet Drive:Waterjet propulsion enables shallow-draft operations for littoral and riverine environments.
Diesel systems retain the largest installed base while Hybrid configurations climb the fastest as defense procurement specifications harden.
Application:
Customer sophistication varies sharply—military and emergency services demand integrated command systems while commercial buyers prioritize hourly operating economics.
- Search and Rescue:Night-operable platforms with medical-evacuation equipment command premium pricing due to certification complexity. Australian and Japanese defense procurement programs specify these capabilities for littoral disaster response.
- Border Patrol:Surveillance-integrated vehicles require stabilized sensor mounts and extended endurance for coastal monitoring. Indonesia and Philippines archipelago logistics create demand for medium-tonnage platforms without infrastructure dependence.
- Cargo Delivery:Payload-optimized designs serve remote supply chains across island chains.
- Construction Support:Heavy-lift amphibians access wetland and floodplain job sites.
- Tourist Transport:Passenger capacity and comfort features dominate specification requirements.
- Firefighting:Pump-integrated hulls support wildfire suppression in lakeside and coastal zones.
Cargo Delivery provides the volume foundation while Border Patrol applications show the steepest specification advancement.
End User:
Procurement authority concentration favors prime contractors with established certification records—centralized program offices now control previously decentralized purchasing.
- Defense Forces:National fleet modernization programs issue multi-year production contracts with NATO STANAG validation requirements. United States Marine Corps Amphibious Combat Vehicle procurement and United Kingdom Ministry of Defence armored swimming vehicle orders exemplify this concentrated demand.
- Emergency Services:Municipal and state-level agencies access federal equipment grants with specific amphibious capability mandates. FEMA frameworks in the United States increasingly specify flood rescue vehicle requirements.
- Logistics Providers:Island chain connectivity gaps in Southeast Asia drive commercial adoption.
- Construction Firms:Wetland access requirements generate project-specific equipment procurement.
- Tourism Operators:Seasonal demand patterns favor leasing over ownership.
- Agricultural Enterprises:Floodplain farming operations require seasonal water crossing capability.
Defense Forces dominate contract value while Emergency Services expand procurement volume through federal grant programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement premiums in the United States diverge sharply from cost-optimized commercial sourcing in Southeast Asia, creating a two-tier pricing architecture that manufacturers must navigate simultaneously.
United States
The Marine Corps Amphibious Combat Vehicle program and FEMA disaster response grants concentrate demand for armored and rescue platforms. EPA Tier 4 Final emissions rules constrain diesel configurations while mandating hybrid-electric alternatives. Production clusters in Michigan and Virginia integrate automotive battery management with naval architecture certification.
Japan
Littoral defense modernization drives orders for tracked swimming vehicles with integrated command systems. METI procurement guidelines favor domestic content requirements in fleet replacement tenders. Industrial activity concentrates in Nagoya and Yokohama, where heavy machinery manufacturers adapt construction equipment architectures for marine environments.
Germany
Bundeswehr requirements for tracked amphibious systems anchor European defense demand. EU Green Deal procurement directives award preference points for hybrid propulsion, accelerating technology transitions. Engineering clusters in Düsseldorf and Munich specialize in armor-grade steel welding and hydrodynamic hull validation.
Australia
Indo-Pacific littoral operations procurement prioritizes night-operable rescue variants for disaster response coordination. TGA-equivalent marine certification bodies validate hull integrity standards for regional deployment. Activity centers on Melbourne and Perth, where defense contractors integrate surveillance systems with corrosion-resistant aluminum architectures.
Indonesia
Archipelago logistics gaps generate commercial demand for medium-tonnage cargo amphibians without port infrastructure dependence. National content regulations in defense tenders favor joint ventures with established NATO STANAG-certified primes. Manufacturing partnerships concentrate in Surabaya and Batam, leveraging proximity to Singapore supply chains.
Amphibious Vehicle Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying hull materials, propulsion modules, and armor packages. The vendor base compresses around defense procurement consolidation, with prime contractors absorbing qualification burdens that exclude smaller fabricators. Three archetypes dominate: diversified defense conglomerates with NATO certification records, regional specialists serving single-country tenders, and industrial equipment manufacturers extending construction machinery lines into amphibious variants. Competitive moves center on strategic partnerships for battery supply security and backward integration into marine-grade aluminum hull production.
Among diversified defense conglomerates, BAE Systems plc and General Dynamics Corporation exemplify the certification-heavy system integrator archetype, anchoring multi-year production contracts through established ministry relationships. Rheinmetall AG occupies a parallel position in European tracked platform supply. Hydratrek, Inc. represents the specialized regional fabricator tier, serving commercial and emergency response segments with shorter procurement cycles. These three illustrate how geographic origin and corporate structure map onto divergent competitive vectors: London- and Virginia-based public companies pursuing centralized defense program offices, versus privately held specialists capturing municipal and state-level equipment grants.
| Leading Market Players |
|---|
| Hanwha Aerospace |
| Hydratrek, Inc. |
| BAE Systems plc |
| Wetland Equipment Company |
| Wilco Manufacturing L.L.C. |
| General Dynamics Corporation |
| Hitachi Construction Machinery Co., Ltd. |
| Griffon Hoverwork |
| Rheinmetall AG |
| Others |
Cost & Logistics Intelligence
Wave-tank testing undercapacity across NATO-certified facilities is compressing supplier qualification timelines while amplifying pricing power for established prime contractors with validated hull architectures. This utilization squeeze forces new entrants to absorb 18-month validation queues or pay premium access fees, structurally advantaging incumbents with captive hydrodynamic testing relationships.
Pricing Analysis
Configured-to-order pricing for armored swimming vehicles commands spreads exceeding standard commercial cargo platforms by factors tied to ballistic protection tiers and NATO STANAG certification levels. Three-tier pricing structure across mission-configured, base-specification, and commercial utility levels reflects customization depth and regulatory compliance burden. Pricing pressure stems from nickel and molybdenum alloying cost volatility in armor-grade steel, compressing margins on tracked platforms. Defense procurement offices exhibit lowest price sensitivity given mission-critical specifications, while municipal emergency services accessing FEMA equipment grants face strict budget ceilings.
Supply Chain Analysis
Extended payment terms from prime contractors to hull fabrication subcontractors have become standard practice as supply-chain finance facilities proliferate among defense conglomerates. Marine-grade aluminum sheet production concentrates in Germany, Japan, and the United States, with robotic friction stir welding equipment sourcing anchored in Düsseldorf and Nagoya industrial clusters. Lithium-ion cell supply for hybrid-electric propulsion rests on East Asian manufacturing hubs, creating single-source vulnerability for Western battery pack integrators. Distribution runs through defense procurement program offices with centralized technical authority, bypassing traditional dealer networks for military and rescue platform categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across archipelago logistics and municipal emergency response segments where defense-centric primes maintain limited presence. Climate-adapted procurement at state and federal levels is spawning niche demand for medium-tonnage cargo and medical-evacuation platforms outside traditional military specifications.
For Market Incumbents: Pre-empt margin erosion in armor-grade steel platforms by securing captive supply agreements with nickel alloy producers in Australia and Indonesia. Accelerate in-house production of marine-grade aluminum hulls through robotic welding capacity expansion in Michigan and Virginia clusters to offset hydrodynamic testing facility scarcity. For New Entrants and Emerging Players: Medium-tonnage cargo amphibians for Indonesia and Philippines archipelago logistics represent the most penetrable entry point, as existing infrastructure gaps eliminate port-dependent competition. State-level FEMA equipment grant programs in flood-prone US regions offer secondary beachhead through commercial rescue platform specifications. Pursue joint venture structures with established NATO STANAG-certified primes to bypass 18-month validation queue barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid-electric propulsion subsystem specialists with Marine Corps and UK Ministry of Defence approved vendor status. Long-term viability hinges on battery supply security and backward integration into hull materials. Monitor lithium-ion cell supply diversification announcements from East Asian manufacturers as inflection indicator for Western prime contractor margin stability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Integration | Marine Corps tender specifications now mandate dual-mode drivetrains for silent littoral approaches. |
| Robotic Hull Fabrication Scale-Up | Friction stir welding automation in Michigan and Virginia reduces production cycle times for corrosion-resistant architectures. |
| Battery Supply Security Partnerships | Long-term offtake agreements with South Korean cell manufacturers mitigate East Asian supply concentration risks. |
| Archipelago Logistics Joint Venture | Indonesian content requirements favor partnerships with Surabaya-based fabricators for medium-tonnage cargo platforms. |
| FEMA Grant Program Certification | FDA-compliant medical-evacuation configurations unlock municipal procurement through federal disaster response frameworks. |
Research Approach
Cross-validation between defense procurement documentation and marine engineering certification records anchors the qualitative findings. Primary interviews with program officers at centralized military acquisition offices, naval architects at hydrodynamic testing facilities, procurement managers at state emergency management agencies, and battery system engineers at Tier 1 suppliers informed demand-side and technology assessments. Secondary validation drew from EPA Tier 4 Final regulatory filings, EU Green Deal procurement directive implementations, NATO STANAG specification databases, and customs records for marine-grade aluminum trade flows. Bottom-up platform shipment tracking and top-down defense budget allocation analysis provided triangulation across volume and value estimates.
Calibration against historical production cycles for armored swimming vehicles and rescue platform procurement waves established baseline growth parameters across the projection horizon. Segmentation modeling incorporated vehicle type, propulsion architecture, application focus, and end-user category dimensions with regional regulatory cluster overlays. CAGRs derived from defense modernization program timelines and commercial replacement cycle analysis, with specific weighting for hybrid-electric technology adoption curves and FEMA grant program expansion trajectories.
Practitioners should monitor lithium-ion supply diversification progress and NATO interoperability specification revisions for early signals of competitive positioning shifts. Forecasts reflect documented program office timelines and regulatory implementation schedules. Macroeconomic commodity price volatility, battery cell supply disruption, or defense procurement centralization reversal would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Bass Boat Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Marine Fuel Injection System Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Cargo Vessel Market