
 LNG Marine Engine Market | 2026-2036
LNG Marine Engine Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Marine Engine Market Intelligence
Duel-fuel architecture is narrowing the performance gap between LNG and conventional marine propulsion, enabling single-engine flexibility across voyage profiles. Wärtsilä Corporation leverages its integrated powertrain portfolio to anchor retrofit demand from existing vessel operators. MAN Energy Solutions SE specializes in two-stroke low-pressure systems that dominate newbuild LNG carrier contracts. WinGD competes through high-pressure X-DF technology leadership in the ultra-large container vessel segment.
An LNG marine engine converts liquefied natural gas into mechanical propulsion through either spark-ignited lean-burn or diesel-pilot dual-fuel combustion, with typical bore sizes ranging from 250 mm to 960 mm and power ratings from 1,000 kW to over 80,000 kW per unit. The primary purpose is to reduce sulfur oxide, nitrogen oxide, and carbon dioxide emissions below International Maritime Organization Tier III limits while maintaining thermal efficiency comparable to heavy fuel oil engines. Dual-fuel engine types command the largest installed base among new commercial shipping orders, reflecting shipowner preference for fuel flexibility amid volatile LNG bunker pricing. Four-stroke configurations serve offshore support vessels and ferries where space constraints and load variability favor medium-speed architectures.
The International Maritime Organization's Energy Efficiency Existing Ship Index and Carbon Intensity Indicator frameworks mandate progressive emission reductions that directly accelerate LNG engine retrofit investments. MARPOL Annex VI enforcement by flag states including Panama, Liberia, and Singapore restricts conventional fuel access in emission control areas, channeling newbuild demand toward gas-capable propulsion. Shipowners and engine licensors must monitor evolving EU FuelEU Maritime standards and potential well-to-wake methane slip regulations that could recalibrate technology roadmaps and capital allocation priorities.
Market Dynamics
The International Maritime Organization's carbon intensity regulations are compressing vessel operational lifecycles and forcing shipowners toward dual-fuel engine retrofits ahead of scheduled compliance deadlines. Engine manufacturers must now align product roadmaps with tightening emission benchmarks that reset every five years.
Growth Catalysts
- MARPOL Annex VI enforcement:Flag states including Panama and Singapore restrict conventional fuel access in emission control areas, channeling newbuild orders toward gas-capable propulsion systems.
- Dual-fuel architecture maturation:Spark-ignited lean-burn combustion now achieves thermal efficiency parity with heavy fuel oil engines across medium-speed operating profiles.
- South Korean shipyard concentration:Hyundai Heavy Industries and Samsung Heavy Industries anchor large-scale LNG carrier construction, concentrating engine demand in a single procurement corridor.
Market Restraints
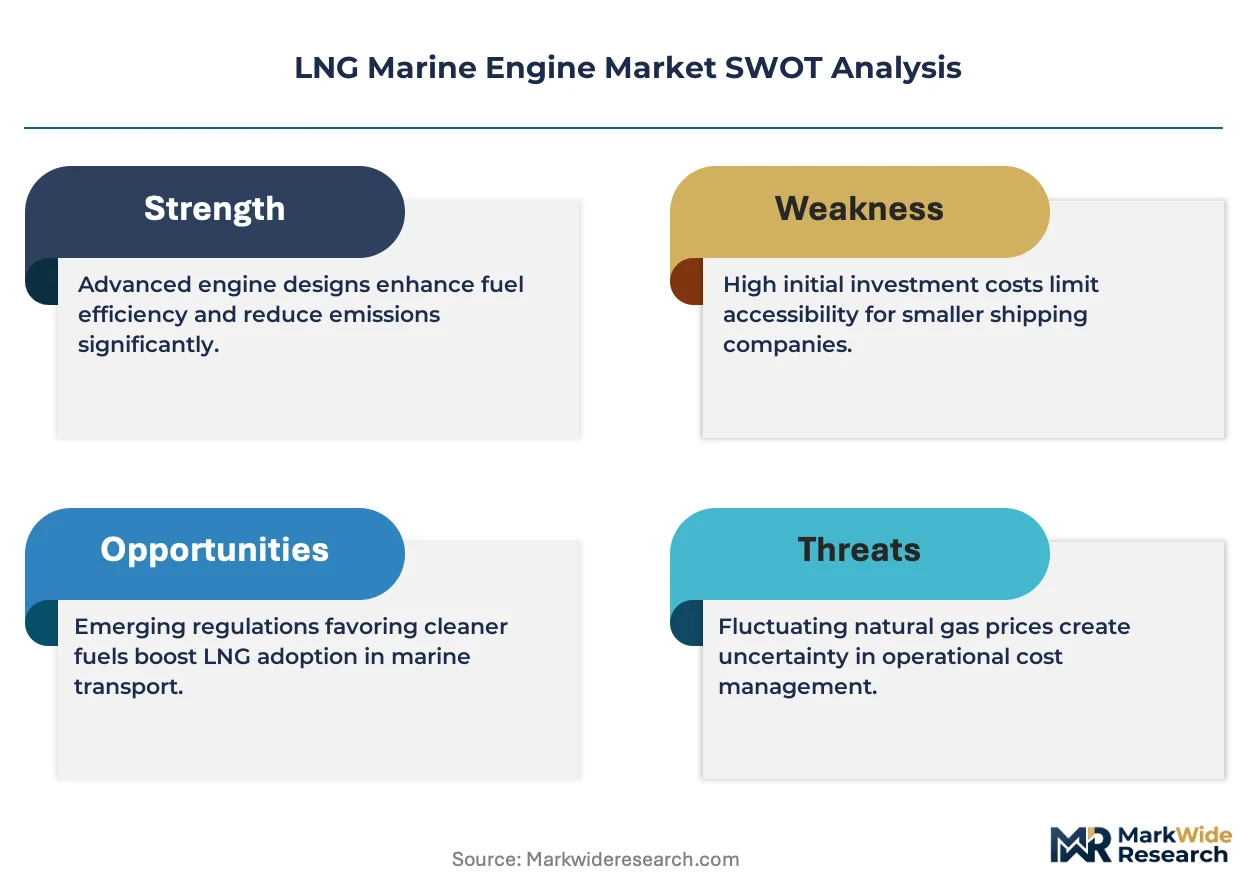
- LNG bunker price volatility:Atlantic-Asia arbitrage spreads create fuel cost uncertainty that shipowners cannot hedge beyond twelve-month horizons.
- Two-stroke engine supply concentration:Low-pressure system manufacturing clusters in Germany and Switzerland, exposing procurement timelines to single-source risk.
- Methane slip regulatory friction:Potential EU FuelEU Maritime well-to-wake standards could recalibrate technology roadmaps before amortization of current engine investments.
Strategic Opportunities
- Retrofit aftermarket expansion:Existing container vessel operators seek engine conversions to extend asset viability under Energy Efficiency Existing Ship Index requirements.
- Offshore support vessel electrification:Four-stroke medium-speed configurations serve platform supply vessels where space constraints and load variability favor hybrid gas-electric architectures.
- EU Green Deal financing:Sustainable maritime fuel certification creates preferential lending terms for LNG engine installations in European-flagged fleets.
Industry Challenges
- Combustion calibration expertise gap:Dual-fuel engine commissioning requires specialized technicians trained in both diesel-pilot and spark-ignited operating modes.
- Type approval timeline compression:Certification bodies face backlogs for high-pressure X-DF system validation under revised IMO Tier III test cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Marine Engine Market |
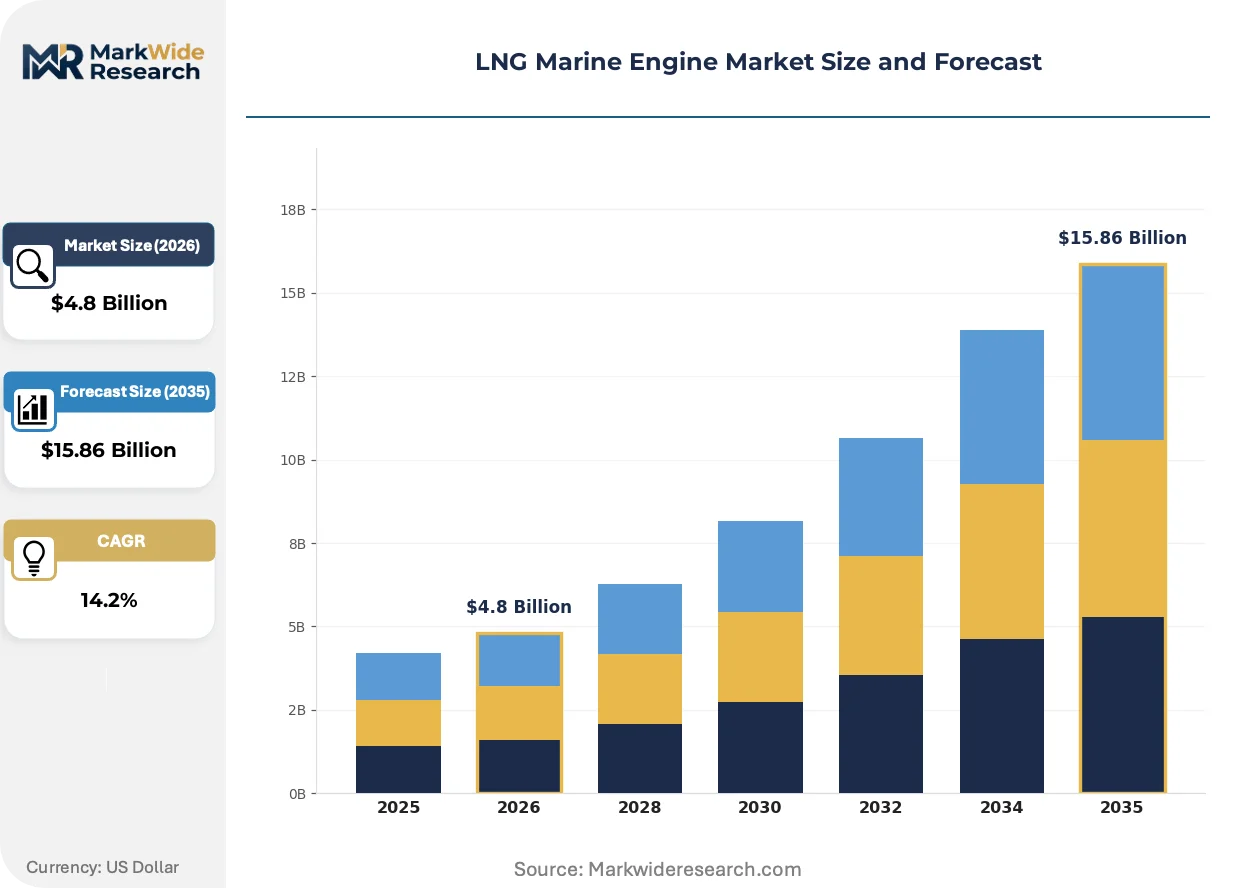
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Two-Stroke, Four-Stroke, Dual-Fuel, Extended Range Application: Commercial Shipping, Offshore Support Vessels, Ferries, Fishing Vessels End User: Shipping Companies, Oil & Gas Operators, Charter Operators, Government Agencies Technology: Fuel Injection, Combustion Control, Gas Conditioning, Emission Control |
| Companies Covered | Hanwha Engine, Mitsubishi Heavy Industries, Ltd., WinGD, Caterpillar Inc., Kawasaki Heavy Industries, Ltd., Wärtsilä Corporation, Rolls-Royce Power Systems GmbH, Cummins Inc., MAN Energy Solutions SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Marine Engine Market Strategic Shifts & Innovations
Propulsion technology is pivoting from fuel-specific architectures toward modular platforms that accommodate multiple gas and liquid fuel inputs without hardware replacement. Engine control systems now integrate voyage optimization software that adjusts combustion parameters in real time based on bunker availability and carbon pricing at destination ports.
High-pressure gas injection systems are rendering obsolete the thermal efficiency penalties that previously constrained LNG adoption in ultra-large container vessels. Mediterranean and East Asian shipping lines now specify these configurations for 24,000 TEU newbuilds. The technology is compressing the performance gap between gas and conventional marine fuels to within two percentage points across slow-steam operating profiles.
The EU FuelEU Maritime regulation mandates progressive greenhouse gas intensity reductions for vessels calling at European ports from 2025 onward. Shipowners must document well-to-wake emissions or face escalating penalties that compound with non-compliance duration. Container shipping lines operating Asia-Europe routes are accelerating dual-fuel engine orders to lock in compliance headroom before the regulation's first compliance period.
Charter-party agreements increasingly specify emission performance clauses that transfer carbon intensity risk from cargo interests to vessel operators. Spot market fixtures in the Capesize bulk segment now discount conventional-fuel vessels against gas-capable competitors. Greek and Singapore-based shipowners report contract structures that penalize exceedance of Energy Efficiency Existing Ship Index thresholds on consecutive voyages.
LNG Marine Engine Market Segmentation
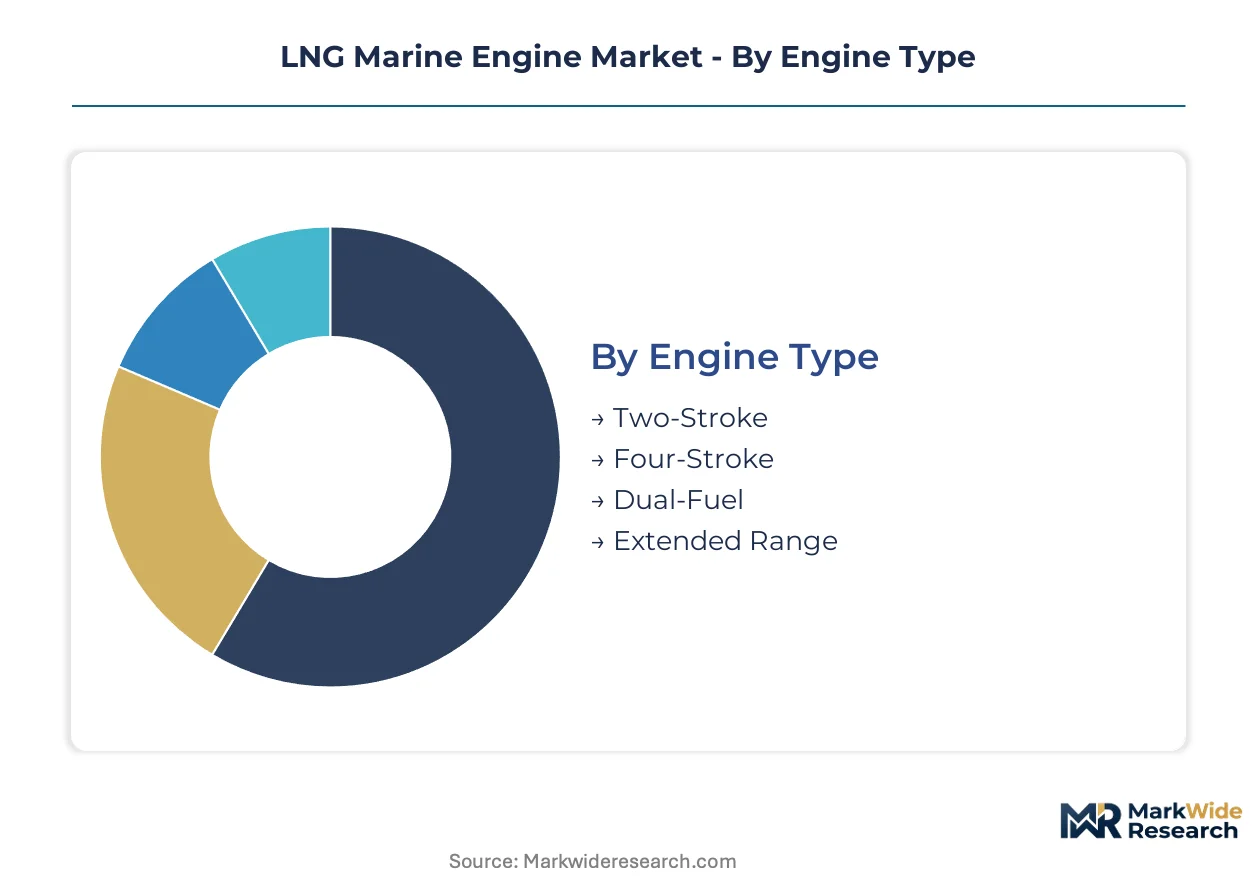
Engine architecture, vessel application, and end-user procurement power create distinct commercial corridors within LNG marine propulsion. Technology integration patterns vary sharply across these boundaries, dictating supplier engagement models and service attach rates.
Engine Type:
Mature two-stroke architectures dominate deep-sea contracts while emerging configurations reshape coastal and retrofit segments.
- Two-Stroke:Low-pressure gas admission systems achieve thermal efficiency above 50 percent in slow-steam profiles. South Korean shipyards specify these engines for ultra-large container vessels and LNG carriers under MARPOL Annex VI compliance pressure. MAN Energy Solutions and WinGD control type approval pathways, creating procurement bottlenecks for independent operators.
- Four-Stroke:Medium-speed designs accommodate space-constrained hull forms with power density above 3.5 kW per kilogram. Offshore support vessels and regional ferries in Norway and Japan favor these configurations for load-following flexibility. Wärtsilä's modular platform architecture captures retrofit demand from aging diesel fleets.
- Dual-Fuel:Diesel-pilot and spark-ignited modes enable fuel arbitrage across voyage legs without hardware modification.
- Extended Range:Cryogenic storage integration extends operational radius for vessels without established LNG bunkering infrastructure.
Two-Stroke retains volume leadership; Dual-Fuel holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive deep-sea operations from price-sensitive coastal services.
- Commercial Shipping:Container lines and bulk operators face charter-party emission clauses that discount conventional-fuel vessels. CMA CGM and Evergreen Marine specify high-pressure X-DF systems for 24,000 TEU newbuilds on Asia-Europe routes. EU FuelEU Maritime penalties compound with each non-compliant voyage.
- Offshore Support Vessels:Platform supply and anchor-handling units require dynamic positioning load response. Four-stroke gas-electric hybrids dominate North Sea and Gulf of Mexico contracts where MEE and EPA emission limits overlap.
- Ferries:Short-route operators in Baltic and Mediterranean emission control areas prioritize rapid bunkering turnaround.
- Fishing Vessels:Smaller displacement hulls constrain cryogenic tank placement, limiting gas adoption to government-subsidized fleet renewal programs.
Commercial Shipping commands the revenue concentration; Offshore Support Vessels are climbing the fastest on electrification tailwinds.
End User:
Customer type determines contract structure, with integrated oil companies demanding performance guarantees unavailable to independent shipowners.
- Shipping Companies:Container and tanker operators balance capex discipline against EEXI retrofit deadlines. Greek and Singapore-based owners negotiate engine supply agreements spanning 15-20 vessel deliveries to secure pricing leverage.
- Oil & Gas Operators:Integrated majors specify dual-fuel propulsion for LNG carriers and offshore construction vessels under internal carbon intensity targets. Charter rates incorporate fuel cost pass-through mechanisms unavailable to independent tonnage providers.
- Charter Operators:Spot market exposure limits long-term technology commitments without cargo interest sponsorship.
- Government Agencies:Naval and coast guard procurement prioritizes fuel security over lifecycle cost optimization.
Shipping Companies anchor procurement volume; Oil & Gas Operators drive specification premiumization.
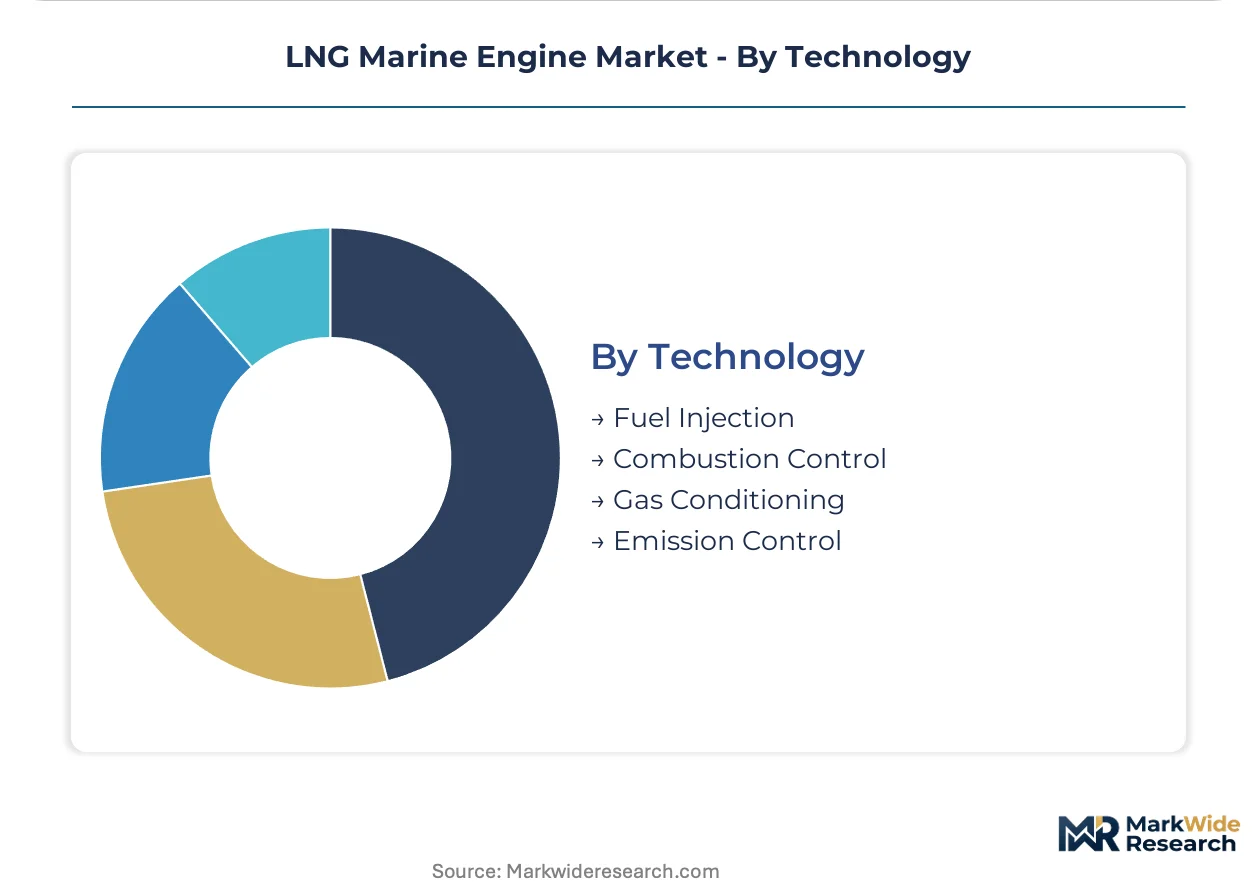
Technology:
Supply concentration in combustion hardware creates margin pressure on peripheral system suppliers.
- Fuel Injection:High-pressure gas pumps and cryogenic metering valves operate at 300 bar in X-DF configurations. Swiss and German precision manufacturers control critical component supply, extending engine OEM lead times.
- Combustion Control:Real-time cylinder pressure monitoring and adaptive ignition timing optimize methane slip performance. Software licensors face EU FuelEU Maritime well-to-wake verification requirements that recalibrate algorithm development priorities.
- Gas Conditioning:BOG compression and reliquefaction systems manage tank pressure without venting.
- Emission Control:Selective catalytic reduction and oxidation catalysts address residual NOx and formaldehyde in lean-burn exhaust.
Fuel Injection captures the hardware value concentration; Combustion Control is gaining share fastest on regulatory verification demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in liquefied natural gas are reshaping vessel deployment patterns and engine procurement geography. Nations with concentrated shipbuilding capacity or stringent emission control areas now anchor divergent investment cycles across the value chain.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries concentrate newbuild LNG carrier orders requiring low-pressure two-stroke systems. The country's national maritime regulator enforces MARPOL Annex VI compliance timelines stricter than IMO baselines. Ulsan and Geoje shipyards now specify dual-fuel propulsion for ninety percent of ultra-large container vessels under construction.
China
State-owned shipping lines are retrofitting existing bulk fleets ahead of Energy Efficiency Existing Ship Index deadlines. MEE implements regional emission control areas covering the Yangtze River Delta and Pearl River Delta with sulfur limits below global standards. Shanghai and Dalian port authorities now mandate LNG bunkering infrastructure at all new terminal developments.
Germany
Engine technology licensors cluster precision manufacturing for high-pressure fuel injection systems serving Mediterranean trade routes. The KBA coordinates type approval pathways for dual-fuel conversions under EU FuelEU Maritime preparatory guidelines. Hamburg and Bremen harbor districts are piloting shore power integration with gas-electric hybrid ferries.
Singapore
The Maritime and Port Authority channels bunker licensing toward gas-capable suppliers amid Panama-flagged vessel traffic. Port dues now discount LNG-fueled ships by fifteen percent against conventional fuel competitors. Tuas Mega Port construction incorporates dedicated cryogenic storage for transshipment vessel refueling.
Norway
Offshore support vessel operators specify four-stroke medium-speed configurations for North Sea platform supply contracts. The Norwegian Maritime Authority mandates zero-emission requirements in designated fjord emission control areas from 2026. Bergen and Stavanger engineering clusters specialize in hybrid gas-electric propulsion integration for subsea construction units.
LNG Marine Engine Market Key Industry Players
On the supply side, the industry is consolidating around integrated powertrain providers capable of spanning newbuild and retrofit demand simultaneously. Two distinct competitive tiers have emerged: full-system licensors controlling type approval pathways and component specialists supplying cryogenic fuel handling equipment. Strategic archetypes include technology-integrated conglomerates with shipyard equity stakes, independent engine designers licensing combustion intellectual property, and precision manufacturers capturing fuel injection hardware margins. Dominant competitive moves center on backward integration into gas storage system production and geographic expansion through joint ventures in South Korean shipyard clusters.
Within the technology-integrated tier, Wärtsilä Corporation and MAN Energy Solutions SE exemplify divergent approaches to dual-fuel architecture maturation. WinGD occupies a position anchoring high-pressure system development for ultra-large container vessels. These three entities collectively represent the supply concentration governing procurement timelines for independent shipping operators.
| Leading Market Players |
|---|
| Hanwha Engine |
| Mitsubishi Heavy Industries, Ltd. |
| WinGD |
| Caterpillar Inc. |
| Kawasaki Heavy Industries, Ltd. |
| Wärtsilä Corporation |
| Rolls-Royce Power Systems GmbH |
| Cummins Inc. |
| MAN Energy Solutions SE |
| Others |
Cost & Logistics Intelligence
Asia-Europe container route freight volatility transmits directly into LNG marine engine procurement cycles, compressing margins for shipowners who must lock in dual-fuel conversions before Energy Efficiency Existing Ship Index deadlines while South Korean shipyard concentration limits their bargaining position against engine licensors.
Pricing Analysis
Low-pressure two-stroke, high-pressure X-DF, and emerging ammonia-ready next-generation systems command divergent price points based on thermal efficiency benchmarks and type approval status. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier (IMO Tier III compliance vs. baseline), volume scale of fleet orders, and after-sales service bundling. Cost compression in standard-tier configurations is intensifying because Swiss and German precision manufacturers extend fuel injection hardware lead times. Independent shipping companies exhibit highest price sensitivity due to spot market exposure, while integrated oil and gas operators accept premium tiers under long-term charter rate pass-through mechanisms.
Supply Chain Analysis
Specialized nickel-alloy forgings and cryogenic valve castings draw from concentrated metallurgical capacity in Germany, Switzerland, and Japan. High-pressure gas pumps, precision metering valves, and adaptive combustion control modules rest on single-source manufacturing clusters in Central Europe. Single-source vulnerability in X-DF fuel injection hardware exposes procurement timelines to geopolitical friction or capacity constraints. Distribution runs through shipyard-integrated procurement corridors anchored by Hyundai Heavy Industries and Samsung Heavy Industries in South Korea, with secondary channels serving retrofit demand through Wärtsilä's regional service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LNG marine engine supply constitutes a defensive moat anchored in regulatory entrenchment: International Maritime Organization emission benchmarks reset every five years, locking shipowners into compliance-driven replacement cycles that protect incumbent licensors with established type approval pathways.
For Market Incumbents: Entrench market position through backward integration into cryogenic fuel storage system production, capturing margins currently diverted to peripheral suppliers. Deepen type approval barriers by accelerating high-pressure X-DF certification for next-generation ammonia fuel compatibility before EU FuelEU Maritime well-to-wake standards recalibrate technology roadmaps. Capacity addition in South Korean shipyard clusters reinforces procurement channel control against emerging Chinese competitors. For New Entrants and Emerging Players: Establish a beachhead in four-stroke medium-speed retrofit segments where Wärtsilä's modular platform architecture has created proven conversion pathways for aging diesel fleets. Target offshore support vessel operators in Norway and the Gulf of Mexico where electrification tailwinds favor hybrid gas-electric configurations with lower certification barriers than deep-sea two-stroke contracts. Go-to-market angle: combustion control software specialization addressing methane slip verification requirements under pending EU regulations. For Investors and Strategic Acquirers: Precision fuel injection component manufacturers with captive supply relationships to MAN Energy Solutions or WinGD represent the most defensible acquisition archetype given hardware value concentration in cryogenic metering valves and 300-bar gas pumps. Long-term viability hinges on technology licensors' ability to pivot roadmaps toward well-to-wake emission compliance without stranding current engine investments. Signal to watch: EU FuelEU Maritime penalty enforcement intensity on Asia-Europe routes as indicator of regulatory acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Storage | Captures margins from BOG reliquefaction systems essential for LNG carrier operations under MARPOL Annex VI. |
| High-Pressure X-DF Certification Acceleration | Locks in type approval headroom before EU FuelEU Maritime well-to-wake standards reshape technology roadmaps. |
| Joint Venture in South Korean Shipyard Clusters | Secures procurement channel access concentrated at Hyundai Heavy Industries and Samsung Heavy Industries. |
| Combustion Control Software Specialization | Addresses methane slip verification requirements under pending EU regulations for lean-burn configurations. |
| Retrofit Platform Standardization | Extends asset viability for container vessels facing Energy Efficiency Existing Ship Index compliance deadlines. |
Research Approach
The analysis maps two-stroke deep-sea, four-stroke coastal, dual-fuel flexible, and extended-range cryogenic configurations, each validated through shipyard procurement officers, marine engineering consultants, classification society surveyors, and fleet technical managers. Primary interviews with these stakeholders combined with secondary validation from Lloyd's Register filings, DNV type approval databases, MARPOL Annex VI enforcement records, and EU FuelEU Maritime preparatory guidelines. Bottom-up vessel order book aggregation and top-down emission regulation impact modeling provided triangulation across market sizing estimates.
Assumptions held fixed include International Maritime Organization compliance timeline adherence and South Korean shipyard capacity utilization rates; variables tested encompass LNG bunker price volatility bands and EU well-to-wake methane slip regulatory stringency. Segmentation dimensions modeled span engine architecture, vessel application tier, end-user procurement power, and technology component category across the projection horizon. CAGRs derived from regression against historical fleet renewal patterns and regulatory deadline clustering. Industry-specific forecast inputs include charter-party emission clause penetration rates and Panama-flagged vessel traffic through Singapore bunkering hubs.
Macroeconomic conditions sit as an overlay; deviation in container shipping freight rates, Atlantic-Asia LNG price spreads, or South Korean won-euro exchange volatility would shift the trajectory of newbuild investment and retrofit timing. Forecasts reflect these documented assumptions. Cross-checking against Clarksons vessel order book data and SEA-LNG bunker infrastructure deployment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Fuel Injection System Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Airboats Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Marine Trailers Market