
 Boat Davits Market | 2026-2036
Boat Davits Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Davits Market Analysis
Marine welding and certified rigging technician availability is bifurcating the competitive landscape between premium and volume davit suppliers. MacGregor leverages its integrated hydraulic engineering footprint to dominate offshore and mega-yacht contracts. Palfinger Marine anchors its position through geographic density in Nordic shipyards. Hi-Tide competes on recreational boating accessibility with simplified permanent-mount systems.
Boat davits are mechanical lifting arms designed to raise, lower, and stow auxiliary watercraft, typically rated by safe working load from 300 kg to over 20 tonnes and fabricated through CNC-machined aluminum extrusion or welded stainless steel tube construction. Their primary purpose is to eliminate manual handling risk while securing tenders, rescue craft, or fishing skiffs against vessel motion. Swing davit architectures retain the largest installed base across recreational boating, though telescopic variants are capturing margin pools in yachting where deck space commands premium valuation. Aluminum material selection leads volume production for its strength-to-weight ratio, while fiber reinforced polymer segments are gaining traction in fishing applications requiring corrosion immunity.
CE marking under the EU Machinery Directive and ISO 15085 welding certification govern market access for European-manufactured davits, with Lloyd's Register and Bureau Veritas type approval increasingly specified for commercial marine tenders. The US Coast Guard's small passenger vessel regulations and ABYC standards shape recreational product liability exposure in North American distribution. Stakeholders must monitor classification society harmonization between prescriptive load-testing protocols and performance-based design standards.
Market Dynamics
EU F-Gas Regulation phase-down schedules and MDR compliance mandates are compressing fabrication timelines for European davit manufacturers while elevating stainless steel and aluminum certification requirements across Mediterranean superyacht refit yards.
Growth Catalysts
- Superyacht fleet expansion:Mediterranean marinas in Italy, Spain, and Greece are accelerating tender lift procurement as refit activity concentrates in coastal clusters.
- REACH and RoHS alignment:European coating and surface treatment standards are driving substitution toward marine-grade aluminum extrusion and passivated stainless steel assemblies.
- ISO 15085 welding certification:Automated MIG and TIG welding protocols are reducing defect rates in davit boom fabrication for commercial rescue craft applications.
Market Restraints
- Aluminum alloy price volatility:LME aluminum fluctuations and energy input costs are compressing margins for volume producers serving recreational boating segments.
- Certified technician scarcity:Lloyd's Register and Bureau Veritas welder qualification bottlenecks in Nordic shipyards are extending delivery lead times for custom hydraulic systems.
- Fiber reinforced polymer substitution:Corrosion-immune FRP tender cradles are displacing metal davit alternatives in commercial fishing fleets operating in high-salinity environments.
Strategic Opportunities
- Electric tender integration:Battery-powered auxiliary craft under 500 kg are creating demand for low-profile telescopic davits with integrated charging umbilicals.
- CE marking harmonization:EU Machinery Directive alignment with ISO 9001 quality frameworks is streamlining market access for modular davit kits in Baltic shipyards.
- Aftermarket service unbundling:Independent rigging technicians in French and Croatian ports are capturing hydraulic maintenance revenue previously retained by OEMs.
Industry Challenges
- Marine welding skill gaps:ISO 9606-certified aluminum welder availability is constraining production scaling for premium yacht davit manufacturers.
- Classification society divergence:Prescriptive load-testing protocols at Lloyd's Register versus performance-based design standards at Bureau Veritas are forcing dual certification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Davits Market |
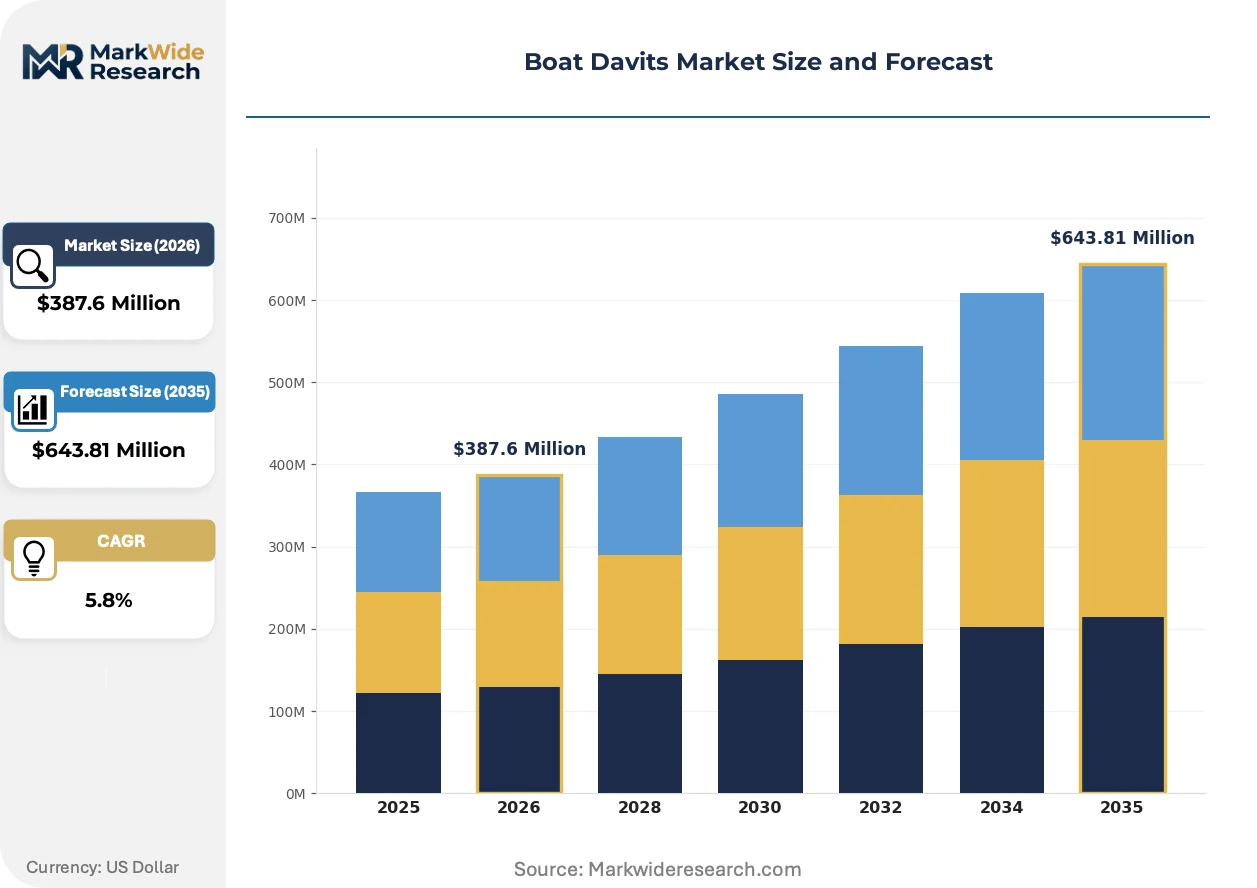
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed Davits, Swing Davits, Radial Davits, Telescopic Davits Application: Recreational Boating, Marine Services, Fishing, Yachting Material: Aluminum, Stainless Steel, Plastic, Fiber Reinforced Polymer Installation Method: Permanent Mount, Portable, Bow Mount, Transom Mount |
| Companies Covered | MacGregor, Palfinger Marine, Davit Master, Hi-Tide, Forespar, Tecnometalli, Spencer Carter, Nautical Structures, Kato Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Davits Market Emerging Trajectories
Digital load monitoring and predictive maintenance architectures are penetrating davit control systems, while material science advances and regulatory harmonization pressures are reshaping competitive differentiation across fabrication tiers.
Telescopic carbon fiber boom technology is fragmenting traditional swing-arm dominance in yachting applications. Superyacht builders above 40 meters are specifying carbon fiber telescopic systems at accelerating rates. This material shift is fragmenting established supply relationships between shipyards and legacy aluminum extrusion suppliers.
EU F-Gas Regulation hydrofluorocarbon phase-down mandates are eliminating certain refrigerant-based hydraulic cooling systems from new davit installations. Equipment suppliers must redesign thermal management for electric-hydraulic power packs. Mega-yacht and offshore vessel segments are responding by accelerating specification of air-cooled or seawater-cooled alternatives ahead of 2027 compliance deadlines.
Buyer concentration among superyacht management companies is compressing tender lift procurement cycles. Fleet operators are consolidating vendor relationships and demanding standardized davit configurations across multiple hulls. This pattern is most visible in Monaco and Barcelona, where management firms control tender specifications for 60-plus vessel portfolios.
Boat Davits Market Segmentation
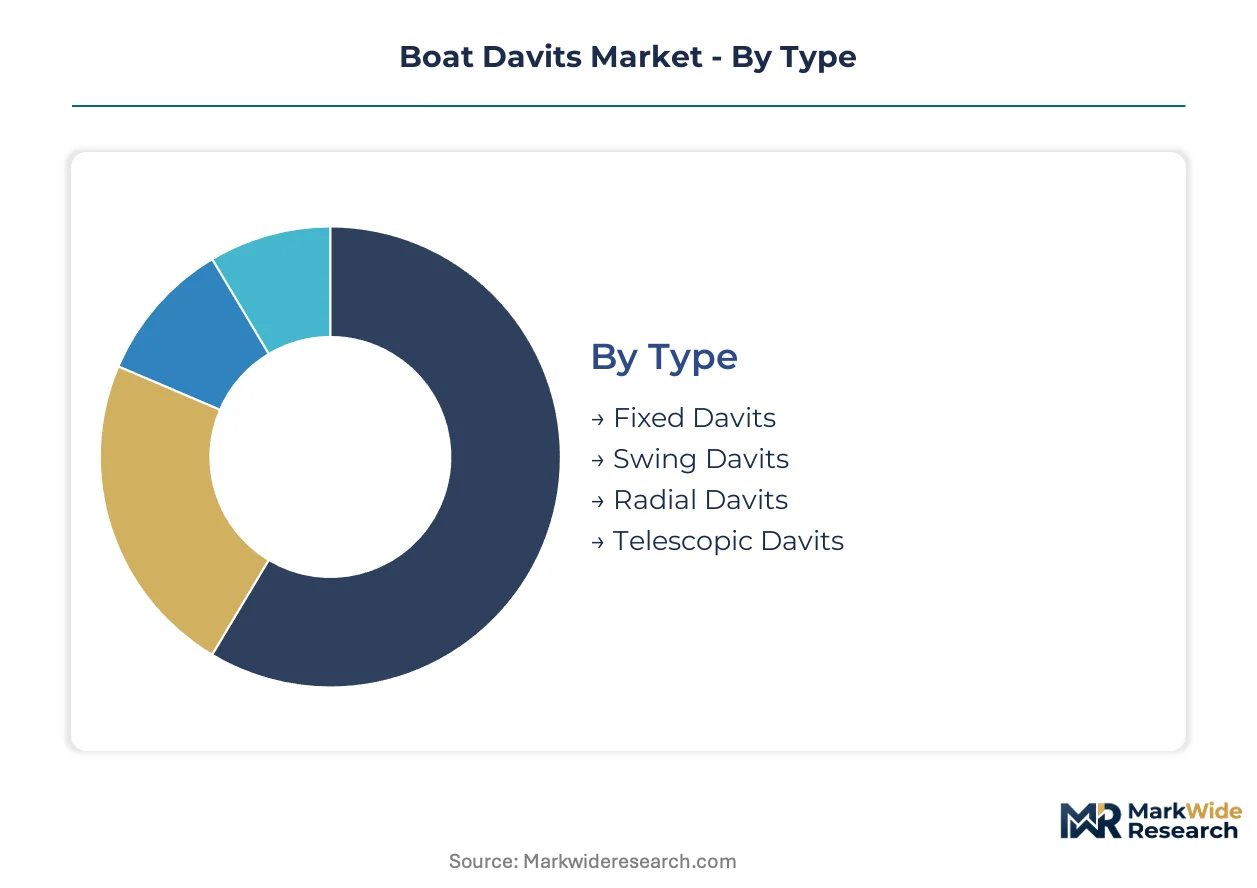
Boat davit procurement channels bifurcate sharply between recreational retail networks and commercial shipyard direct contracts. Material certification requirements and installation complexity determine which segments flow through marine distributors versus OEM-integrated supply chains.
Type:
Distribution density concentrates swing davit variants through recreational marine retailers, while telescopic systems command direct shipyard specification channels.
- Swing Davits:Pivot-arm architectures fabricated from welded aluminum tube or stainless steel dominate recreational tender lift installations. Italian and Spanish coastal marinas drive replacement demand as Mediterranean superyacht refit activity accelerates tender upgrade cycles.
- Telescopic Davits:Multi-stage boom systems extend and retract within confined deck footprints, commanding premium specification in yachting above 40 meters. Carbon fiber variants are displacing aluminum extrusion in Monaco and Barcelona fleet management procurement.
- Fixed Davits:Static A-frame structures serve commercial fishing vessel rescue craft stowage through Nordic shipyard direct channels.
- Radial Davits:Arc-swing geometries optimize stern quarter deployment in limited-space fishing and marine service applications.
By volume, Swing Davits leads. By growth pace, Telescopic Davits is climbing the fastest.
Application:
Cost tier stratification separates recreational price-sensitive procurement from yachting specification where deck space commands premium valuation.
- Yachting:Superyacht tender lifts above 500 kg safe working load require Lloyd's Register or Bureau Veritas type approval. Fleet operators in Monaco and Barcelona consolidate vendor relationships across 60-plus vessel portfolios.
- Recreational Boating:Simplified permanent-mount systems under 300 kg target accessibility through marine retail channels. Hi-Tide and comparable suppliers compete on installation simplicity for private boat owners.
- Marine Services:Commercial rescue craft applications demand ISO 15085-certified welding and automated MIG/TIG fabrication protocols.
- Fishing:High-salinity operating environments drive fiber reinforced polymer substitution for corrosion immunity in North Atlantic and Mediterranean fleets.
By revenue concentration, Yachting dominates. By volume scale, Recreational Boating leads procurement.
Material:
Margin structure diverges between commodity aluminum extrusion and certified stainless steel assemblies subject to REACH and RoHS surface treatment mandates.
- Aluminum:CNC-machined extrusion and welded tube construction deliver optimal strength-to-weight ratios for volume production. LME price volatility compresses margins for recreational segment suppliers.
- Stainless Steel:Passivated marine-grade assemblies satisfy MDR compliance and EU F-Gas Regulation fabrication timelines for Mediterranean superyacht refit yards.
- Fiber Reinforced Polymer:Corrosion-immune tender cradles gain specification in commercial fishing and high-salinity environments.
- Plastic:Injection-molded components serve lightweight recreational applications with limited load requirements.
By installed base, Aluminum leads. By substitution momentum, Fiber Reinforced Polymer is expanding most quickly.
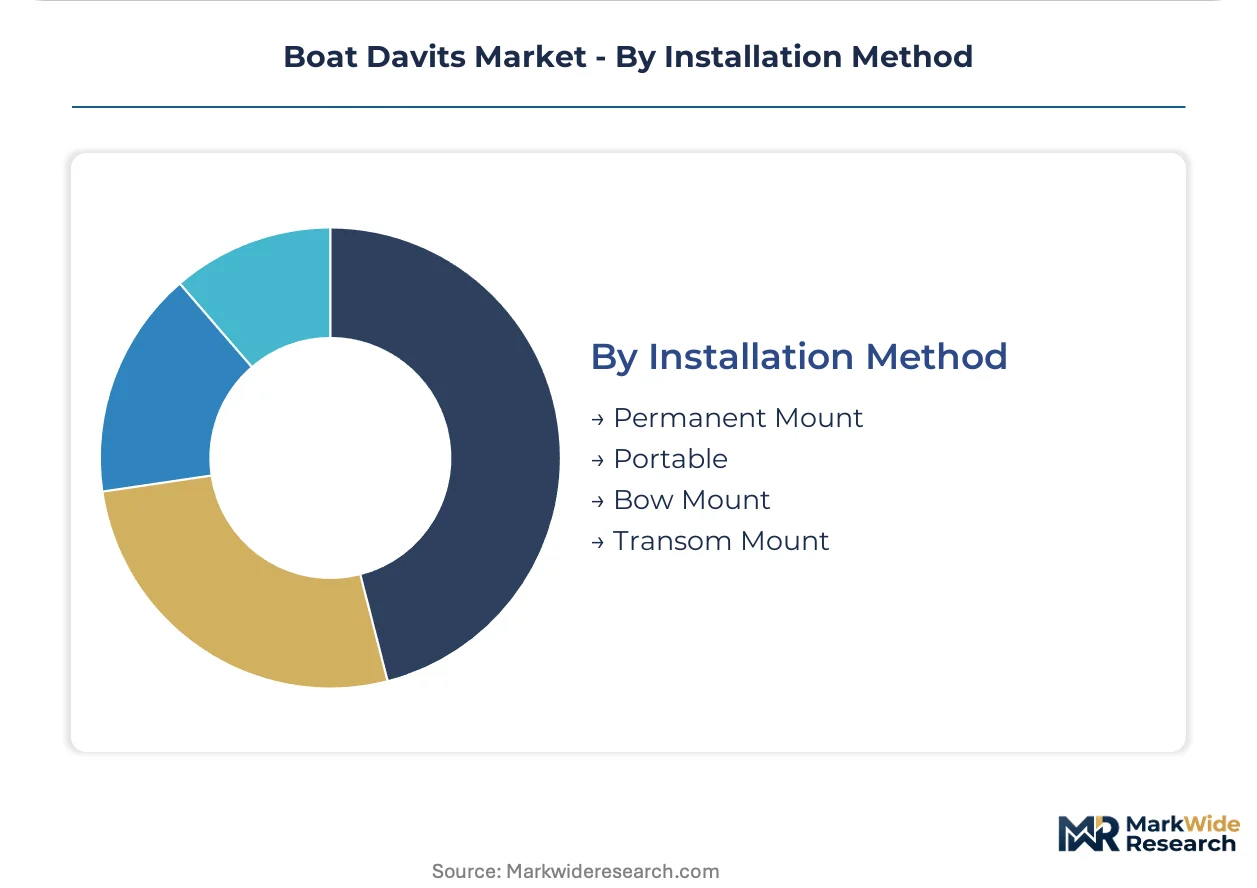
Installation Method:
Customer type determines channel flow: permanent mount systems integrate at shipyard build or refit, while portable variants distribute through aftermarket marine retail.
- Permanent Mount:Structural integration during hull construction or major refit requires classification society load-testing certification. Nordic and Mediterranean shipyards specify these for commercial and yachting applications.
- Portable:Clamp-on or rail-mounted systems target recreational boaters seeking seasonal flexibility without hull modification.
- Bow Mount:Foredeck positioning optimizes tender retrieval in following seas for offshore fishing and expedition yachting.
- Transom Mount:Stern placement dominates recreational boating for swim platform accessibility and simplified line handling.
By specification value, Permanent Mount leads. By unit accessibility, Portable is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy deploys boat davits predominantly for superyacht tender operations, while Norway concentrates on commercial fishing and offshore rescue craft applications, creating divergent specification requirements across Mediterranean and Nordic maritime clusters.
Italy
Superyacht refit activity in Genoa and Viareggio is accelerating procurement of Lloyd's Register-certified telescopic systems. The EU F-Gas Regulation is compressing fabrication timelines for stainless steel assemblies. Shipyards in La Spezia report extended lead times for ISO 15085-certified welding capacity.
Norway
Commercial fishing fleets operating in the North Atlantic are specifying corrosion-immune fiber reinforced polymer alternatives to aluminum davits. The country's national maritime regulator enforces strict load-testing protocols for rescue craft stowage. Bergen and Ålesund shipyards dominate hydraulic system integration for offshore supply vessels.
United States
Recreational boating demand in Florida and the Pacific Northwest is concentrating procurement through marine retail channels for simplified permanent-mount systems under 300 kg. The US Coast Guard's small passenger vessel regulations shape product liability exposure. Miami and Fort Lauderdale distributors report seasonal inventory compression ahead of spring commissioning.
Spain
Barcelona fleet management companies are consolidating vendor relationships across 60-plus vessel portfolios, standardizing davit configurations. CE marking under the EU Machinery Directive governs market access for modular kits. Palma de Mallorca refit yards are absorbing overflow demand from Italian capacity constraints.
Greece
Athens-based superyacht management firms are driving tender lift upgrades as the fleet expands in Aegean and Ionian cruising grounds. REACH and RoHS alignment is elevating marine-grade aluminum extrusion requirements. Piraeus shipyards are investing in automated MIG welding to reduce ISO 15085 certification bottlenecks.
Boat Davits Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hydraulic engineering capabilities separating premium contract winners from volume recreational suppliers. The upper tier commands direct shipyard relationships through classification society type approval, while the lower tier competes on installation simplicity and marine retail distribution density. Two strategic archetypes dominate: integrated marine equipment conglomerates with offshore engineering heritage, and dedicated davit fabricators with Nordic or Mediterranean geographic concentration. Competitive moves center on backward integration into certified welding capacity and geographic expansion into Baltic and Adriatic shipyard clusters.
Among the integrated engineering conglomerates, MacGregor exemplifies the offshore and mega-yacht contract archetype through its hydraulic systems heritage, while Palfinger Marine occupies a position anchored in Nordic shipyard density. Hi-Tide represents the accessibility-focused tier competing on simplified permanent-mount systems for recreational boaters. These three names illustrate the vertical stratification between specification-driven and price-accessible market tiers.
| Leading Market Players |
|---|
| MacGregor |
| Palfinger Marine |
| Davit Master |
| Hi-Tide |
| Forespar |
| Tecnometalli |
| Spencer Carter |
| Nautical Structures |
| Kato Marine |
| Others |
Supply Flow & Price Mechanics
Project-based shipyard contracts with milestone-linked payment terms lock in aluminum extrusion supply commitments from Italian and Greek fabricators while insulating premium davit manufacturers from LME spot volatility. Mediterranean superyacht refit yards leverage these structures to secure ISO 15085-certified welding capacity ahead of EU F-Gas Regulation compliance deadlines.
Pricing Analysis
Long-term offtake agreements dominate procurement between Nordic shipyards and hydraulic system integrators, while spot purchasing persists in recreational retail channels. Three-tier pricing structure across Lloyd's Register-certified premium systems, CE-marked standard assemblies, and economy portable units reflects certification grade and after-sales service bundling. Cost compression in aluminum extrusion tiers is intensifying because LME price volatility and energy input costs are squeezing volume producers serving recreational boating segments. Recreational boaters exhibit highest price sensitivity, whereas superyacht fleet operators prioritize deck-space optimization and classification society approval over unit cost.
Supply Chain Analysis
ISO 9606-certified aluminum welder availability in Italian and Spanish coastal clusters functions as the primary chokepoint constraining production scaling for premium yacht davit manufacturers. Raw material flows draw from Norwegian stainless steel mills, German hydraulic component specialists, and Chinese CNC-machined aluminum extrusion suppliers. Single-source vulnerability concentrates in Lloyd's Register and Bureau Veritas welder qualification bottlenecks extending delivery lead times for custom hydraulic systems. Distribution runs through direct shipyard specification channels for commercial and yachting applications, while marine retail networks handle recreational aftermarket sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified marine welding capacity and classification society type approval function as the scarcest capabilities in this market, creating defensive moats for incumbent fabricators while raising barriers for new entrants lacking shipyard relationships.
For Market Incumbents: Shield margin position by capturing independent rigging technician networks in French and Croatian ports to retain hydraulic maintenance revenue previously lost to aftermarket competitors. Deepen backward integration into automated MIG and TIG welding capacity to reduce ISO 15085 certification bottlenecks. Prioritize air-cooled or seawater-cooled thermal management R&D ahead of EU F-Gas Regulation phase-down deadlines. For New Entrants and Emerging Players: Anchor in electric tender integration segments under 500 kg safe working load, where battery-powered auxiliary craft demand is creating white-space for low-profile telescopic systems with integrated charging umbilicals. Target Baltic shipyard clusters seeking CE marking harmonization under modular davit kit configurations. Pursue go-to-market partnerships with fleet management companies in Monaco and Barcelona standardizing davit configurations across 60-plus vessel portfolios. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap fabricators with captive ISO 15085-certified welding capacity and established Lloyd's Register type approval, positioned to consolidate as classification society divergence forces dual certification investments. Long-term viability hinges on exposure to superyacht refit cycles rather than recreational boating cyclicality. Monitor carbon fiber telescopic system penetration rates above 40 meters as the signal indicating material substitution momentum sufficient to fragment legacy aluminum extrusion supply relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Welding | Captive ISO 15085 capacity reduces defect rates in davit boom fabrication for commercial rescue craft. |
| Carbon Fiber Telescopic System Launch | Carbon fiber variants displace aluminum extrusion in Monaco and Barcelona fleet management procurement. |
| Aftermarket Service Network Acquisition | Control over French and Croatian rigging technicians recaptures hydraulic maintenance revenue from independents. |
| Electric Tender Charging Integration | Low-profile telescopic davits with umbilical systems address battery-powered auxiliary craft under 500 kg. |
| Baltic Shipyard Geographic Expansion | CE marking harmonization streamlines market access for modular davit kits in underserved Baltic clusters. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across shipyard procurement directors, marine welding supervisors, fleet management company technical directors, and independent rigging technicians in Mediterranean and Nordic ports. Secondary validation incorporated Lloyd's Register type approval databases, Bureau Veritas certification records, EU Machinery Directive compliance filings, and aluminum trade flow data from customs authorities. Bottom-up tender lift procurement tracking was triangulated against top-down superyacht fleet expansion metrics.
Across the analysis window, volume and value outputs were modeled by davit type, application tier, material specification, and installation method, with additional segmentation by classification society approval status. CAGRs were derived from compound growth trajectory analysis applied to shipyard order backlogs and refit cycle frequencies. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and REACH-aligned surface treatment substitution patterns.
Decision-makers should treat outputs as directional under base assumptions of sustained Mediterranean superyacht refit activity and stable aluminum alloy pricing; material deviation in LME volatility or welding certification bottlenecks would warrant model refresh. Practitioners should keep alternative scenarios live as fiber reinforced polymer substitution momentum and electric tender fleet penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Seats Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Yacht Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Global Boat Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Boat Tachometer Market