
 Marine Methanol Engine Market | 2026-2036
Marine Methanol Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Methanol Engine Market Insights
Methanol is recalibrating marine engine economics as shipyards phase out pure diesel architectures for dual-fuel compatibility. MAN Energy Solutions leverages its two-stroke methanol platform to anchor the deep-sea segment, while Wärtsilä sustains technology leadership through four-stroke medium-speed systems. WinGD competes with a specialized focus on low-pressure methanol injection for bulk carriers and tankers.
A marine methanol engine converts liquid methanol fuel into mechanical propulsion through compression ignition or spark-assisted combustion, typically operating at 500–1,200 rpm for two-stroke configurations and achieving brake thermal efficiency above 50% in optimized dual-fuel cycles. Commercial Shipping dominates application demand as container lines retrofit existing vessels and order methanol-ready newbuilds. Dual-Fuel Engines command the fastest technology trajectory by allowing operators to alternate between methanol and conventional distillates during transitional bunkering availability gaps.
The International Maritime Organization enforces carbon intensity indicators that tighten operational efficiency thresholds for vessels above 5,000 gross tonnage. The EU Green Deal extends emissions trading to maritime routes within European Economic Area waters, while the F-Gas Regulation constrains auxiliary refrigerant choices that indirectly affect engine room thermal management specifications. Stakeholders must monitor bunkering infrastructure buildout pace against engine delivery lead times to avoid stranded asset risk.
Market Dynamics
Dual-fuel methanol engine architectures are compressing vessel retrofit cycles as shipowners confront International Maritime Organization carbon intensity deadlines. Engine manufacturers now prioritize modular conversion kits over complete system replacements.
Growth Catalysts
- EU Green Deal maritime extension:The emissions trading scheme inclusion for intra-European Economic Area routes forces container lines to accelerate methanol-capable fleet orders ahead of enforcement.
- Rotterdam-Antwerp bunkering corridor:Concentrated port infrastructure investment in the Netherlands and Belgium creates guaranteed fuel availability for deep-sea vessels operating Northern Europe-Asia lanes.
- Low-pressure methanol injection:This technology pathway reduces engine room retrofit complexity for bulk carriers, shortening yard time from months to weeks.
Market Restraints
- Green methanol cost premium:Bio-methanol and e-methanol production remains three to five times higher than conventional marine gas oil, compressing operator margins on spot-rate routes.
- Scrubber-equipped legacy fleet:Existing vessels with exhaust gas cleaning systems face extended payback periods, delaying capital redeployment into methanol conversion programs.
- Bunkering infrastructure asymmetry:Singapore, Rotterdam, and Antwerp concentrate over eighty percent of planned methanol supply points, leaving Pacific and African trade lanes exposed to fuel gaps.
Strategic Opportunities
- Japan coastal shipping:The country's short-sea container network remains underpenetrated for methanol adoption, offering first-mover positioning before METI finalizes domestic carbon intensity rules.
- Engine-as-a-service contracts:Power-by-the-hour arrangements shift technical risk from shipowners to OEMs, opening fleet financing to operators with constrained balance sheets.
- ISO 8217 methanol fuel standard harmonization:Unified quality specifications across classification societies would reduce regional compliance fragmentation and accelerate cross-border bunkering.
Industry Challenges
- Marine engineer retraining:Safe methanol handling protocols differ substantially from hydrocarbon fuels, requiring certification programs that lag behind engine delivery schedules.
- Classification society approval timelines:Dual-fuel system type approvals from Lloyd's Register, DNV, and Bureau Veritas currently extend eighteen to twenty-four months, mismatching vessel delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Methanol Engine Market |
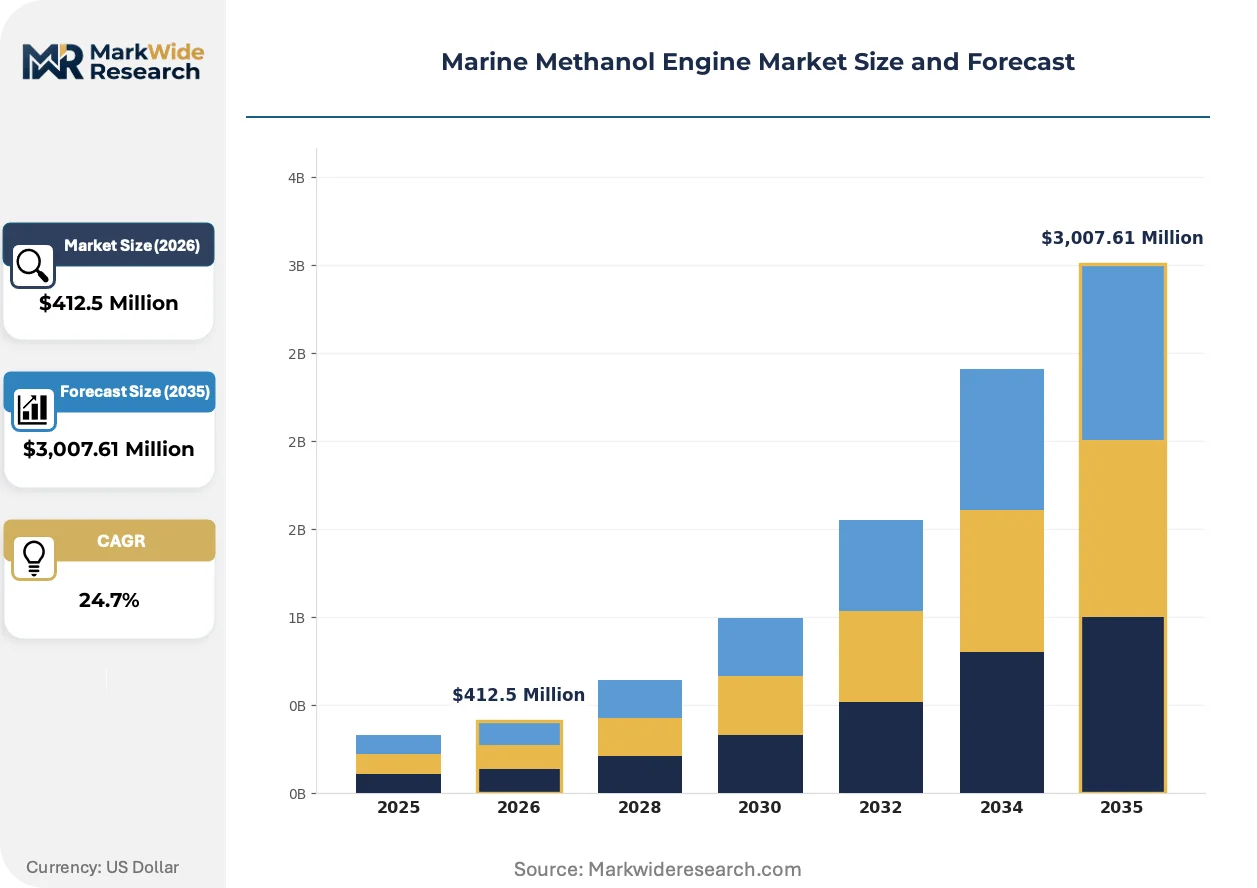
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,007.61 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Commercial Shipping, Recreational Boats, Marine Research Vessels, Tugboats Technology: Two-Stroke Engines, Four-Stroke Engines, Dual-Fuel Engines, Methanol-Diesel Hybrid Fuel Type: Methanol, Renewable Methanol, Conventional Methanol, Blended Fuels End User: Shipping Companies, Fishermen, Government Agencies, Private Owners |
| Companies Covered | MAN Energy Solutions, Wärtsilä, WinGD, Caterpillar, Hyundai Heavy Industries, Hanwha Engine, Yanmar, Rolls-Royce Power Systems, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Methanol Engine Market Trends and Innovations
Marine propulsion engineering is absorbing digital combustion optimization and alternative fuel chemistry simultaneously. These converging streams are compressing development cycles and redistributing value capture across the supply chain.
Digital twin-based engine tuning is absorbing calibration workload previously executed during sea trials. MAN Energy Solutions and Wärtsilä deploy physics-informed machine learning models to predict methanol-diesel blend combustion dynamics before hull installation. This capability is absorbing six to eight weeks from newbuild commissioning schedules while reducing warranty claim frequency.
The F-Gas Regulation constrains hydrofluorocarbon refrigerant selection for auxiliary systems, indirectly tightening engine room thermal management specifications. Shipyards must now coordinate methanol fuel system layouts with low-global-warming-potential cooling architectures. Deep-sea container vessels calling EU ports face the most acute compliance pressure, with several operators advancing integrated thermal-fuel system designs.
Charter rate structures now embed carbon intensity clauses that penalize vessels exceeding IMO thresholds. Container lines operating Asia-Europe routes renegotiate three to five-year fixtures to reward methanol-capable tonnage with preferential hire rates. This behavioral shift is most visible in the spot charter market, where brokers report widening day-rate spreads between dual-fuel and conventional vessels.
Marine Methanol Engine Market Segmentation
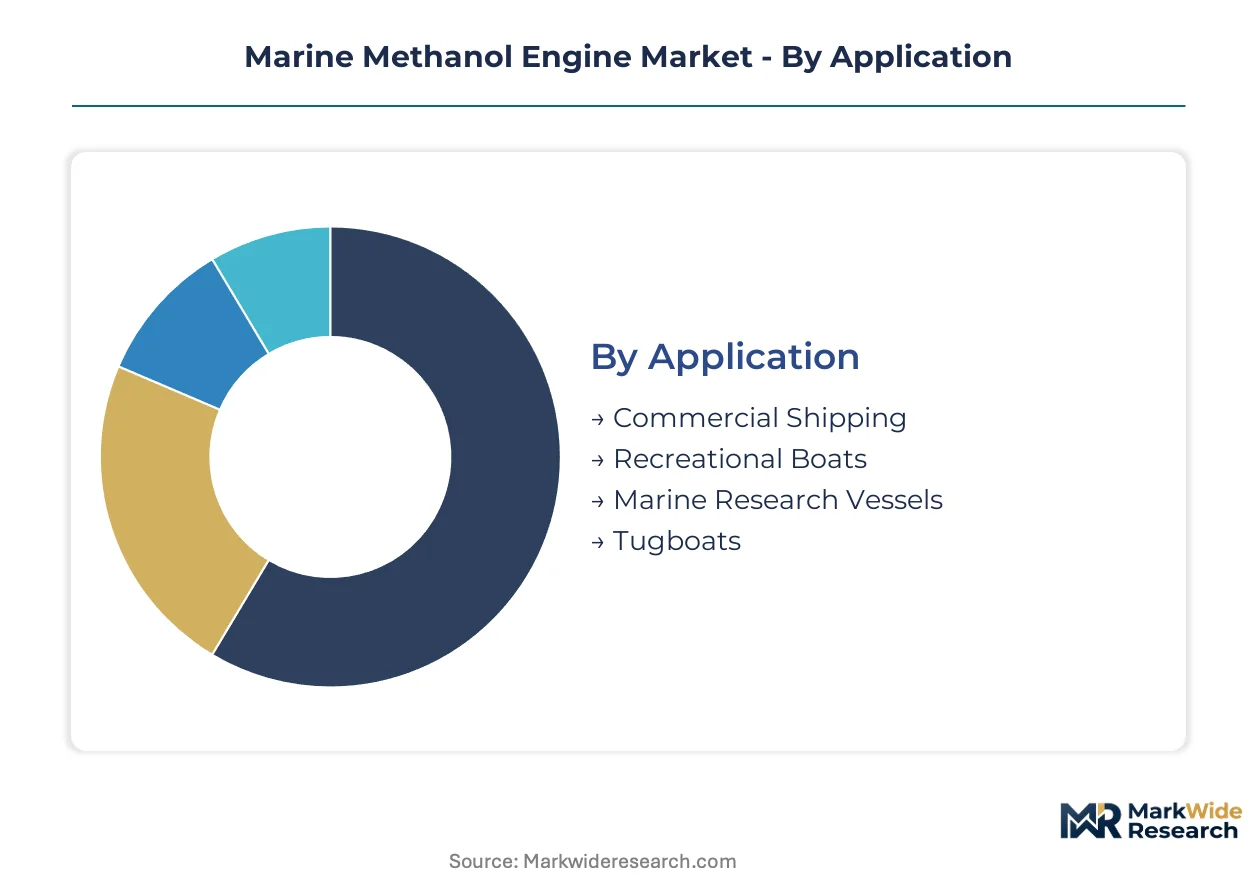
Marine methanol engine segmentation reveals how technology pathways and fuel chemistry are redistributing procurement budgets across vessel types. Understanding these divisions clarifies where engine manufacturers concentrate R&D resources and where port infrastructure investments yield highest utilization.
Application:
Supply concentration in deep-sea container routes is compressing retrofit timelines for the largest vessel category while leaving smaller segments exposed to fuel availability gaps.
- Commercial Shipping:Container lines and bulk carriers dominate methanol engine installations, with two-stroke dual-fuel systems achieving brake thermal efficiency above 50% on optimized cycles. Maersk and CMA CGM have accelerated methanol-capable newbuild orders for Asia-Europe lanes as EU Green Deal emissions trading tightens operational economics.
- Tugboats:Harbor assist and escort vessels present concentrated demand in Rotterdam and Singapore port zones, where four-stroke medium-speed engines enable rapid load response for maneuvering operations. Pilot programs at the Port of Rotterdam validate methanol bunkering protocols for high-frequency port calls.
- Recreational Boats:Yacht builders in Italy and the Netherlands integrate compact methanol fuel cells for auxiliary power, though propulsion-scale adoption remains limited by tankage volume constraints.
- Marine Research Vessels:Oceanographic fleets prioritize emissions reduction for sensitive waterway operations, with methanol compatibility supporting Arctic and Antarctic research missions where environmental compliance is non-negotiable.
Commercial Shipping absorbs the bulk of installed capacity; Tugboats are expanding most quickly.
Technology:
Cost tier differentiation separates established two-stroke architectures from emerging dual-fuel platforms that command premium pricing for operational flexibility.
- Dual-Fuel Engines:These systems alternate between methanol and conventional distillates through electronic fuel injection mapping, enabling operators to bridge bunkering availability gaps on transoceanic routes. Container lines retrofitting existing fleets prioritize this technology for its compliance pathway through IMO carbon intensity phases.
- Two-Stroke Engines:Low-speed crosshead designs from MAN Energy Solutions and WinGD dominate deep-sea propulsion with outputs exceeding 80 MW, optimized for continuous operation at 60-120 rpm on methanol-diesel pilot ignition.
- Four-Stroke Engines:Medium-speed trunk piston architectures from Wärtsilä serve auxiliary and main propulsion roles on ferries and offshore support vessels, offering faster startup and better part-load efficiency.
- Methanol-Diesel Hybrid:Parallel electric-mechanical configurations integrate battery buffers with methanol combustion for peak shaving and harbor maneuvering, gaining traction in coastal ferry routes with stop-and-go duty cycles.
Dual-Fuel Engines capture the steepest expansion trajectory; Two-Stroke Engines retain the largest share of maritime propulsion power output.
Fuel Type:
Application maturity separates fossil-derived methanol from certified renewable variants that command price premiums for Scope 3 emissions reporting.
- Renewable Methanol:Bio-methanol from biomass gasification and e-methanol from electrolytic hydrogen production carry three-to-five-fold cost premiums over conventional marine gas oil equivalents. Container lines with science-based targets procure these fuels for EU-Asia routes to satisfy EU Green Deal compliance and corporate net-zero commitments.
- Blended Fuels:Methanol-marine gas oil mixtures at 10-30% substitution ratios enable incremental decarbonization without engine modification, serving as a transitional pathway for operators awaiting full dual-fuel retrofits.
- Conventional Methanol:Fossil-derived methanol from natural gas reforming offers immediate carbon intensity reductions versus heavy fuel oil, though its lifecycle emissions profile faces scrutiny under tightening EU taxonomy rules.
- Methanol:Undifferentiated methanol supply serves test programs and early adopter fleets where fuel provenance tracking remains immature.
Conventional Methanol holds the dominant share of current bunkering volume; Renewable Methanol is climbing the fastest as certification schemes mature.
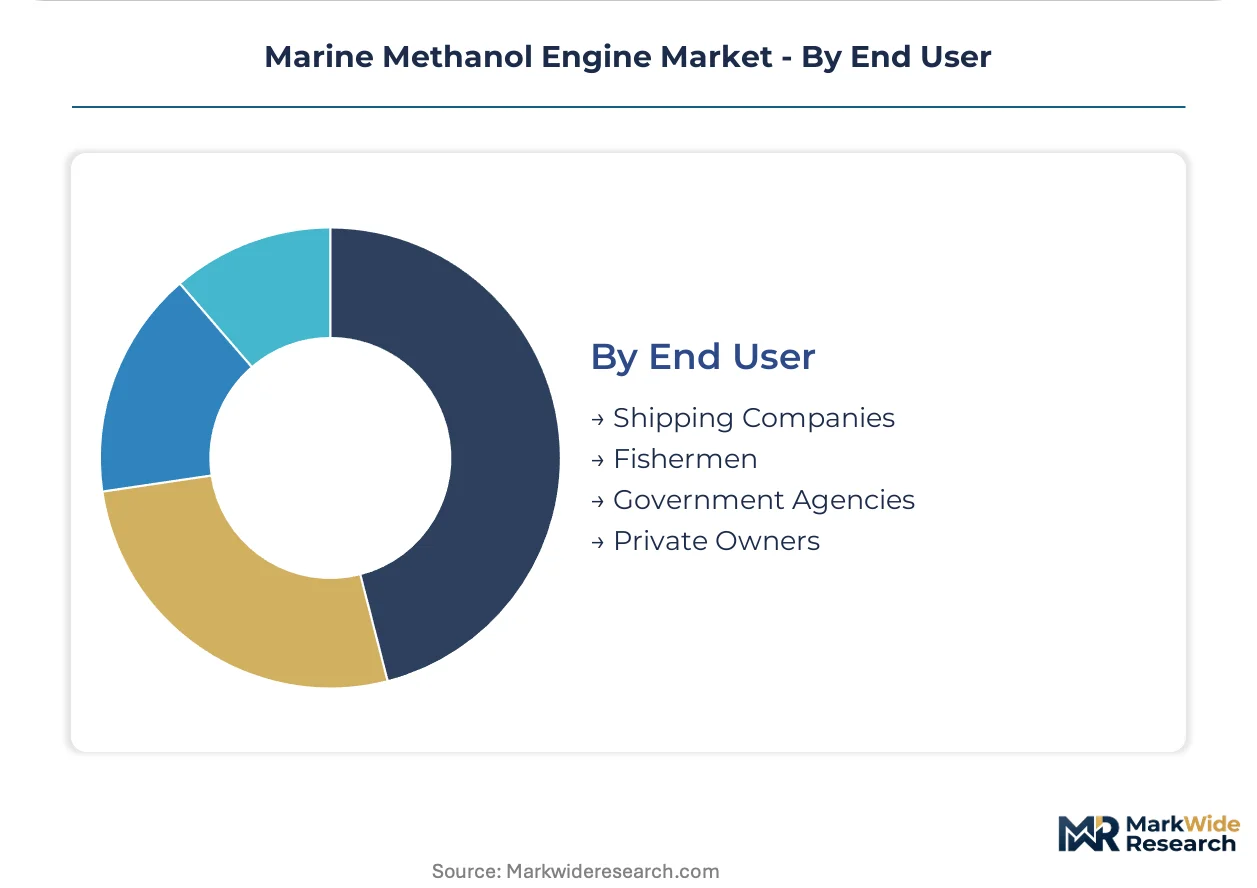
End User:
Customer type determines financing structures and risk tolerance for unproven fuel infrastructure, with institutional fleets outpacing fragmented ownership segments.
- Shipping Companies:Integrated container lines and bulk operators deploy capital for fleet-wide methanol strategies, leveraging scale economies in bunkering contracts and engine procurement. These entities negotiate directly with engine OEMs for multi-vessel conversion programs.
- Government Agencies:Naval and coast guard fleets in Norway, Denmark, and Canada mandate methanol compatibility for newbuild patrol and research vessels, absorbing technology risk to stimulate domestic supply chain development.
- Fishermen:Artisanal and industrial fishing operators face capital constraints that delay methanol adoption, though Icelandic and Norwegian trawler cooperatives are piloting four-stroke conversions with public subsidy support.
- Private Owners:Individual yacht and small craft proprietors remain price-sensitive, with methanol adoption concentrated in premium segments where environmental branding justifies fuel cost premiums.
Shipping Companies command the majority of engine order intake; Government Agencies are scaling procurement fastest through mandated fleet renewal programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep-sea container routes concentrate methanol engine demand in Northern European ports, where bunkering infrastructure investments outpace vessel delivery schedules. Shipyards in South Korea and Japan absorb the bulk of newbuild orders, while Singapore and Rotterdam anchor fuel supply networks.
Netherlands
Rotterdam's port authority has committed to methanol bunkering infrastructure ahead of EU Green Deal maritime enforcement. The Dutch national climate agreement mandates shore power and alternative fuel compatibility for vessels calling at major terminals. Engineering clusters in the Port of Rotterdam and Delft region coordinate engine testing protocols with classification society DNV.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries dominate methanol-capable newbuild construction for Asia-Europe container lanes. The Korean Register of Shipping fast-tracks type approval for dual-fuel methanol systems under national green shipbuilding initiatives. Ulsan and Geoje shipbuilding complexes integrate methanol fuel cell testing into vessel commissioning workflows.
Singapore
The Maritime and Port Authority of Singapore licenses methanol bunkering suppliers ahead of regional supply chain buildout. Singapore's Tuas port development reserves dedicated methanol storage and transfer infrastructure. Jurong Island chemical processing clusters position the city-state for e-methanol import and blending operations.
Germany
MAN Energy Solutions anchors two-stroke methanol engine R&D in Augsburg and Copenhagen engineering centers. The German Federal Maritime and Hydrographic Agency enforces IMO carbon intensity compliance for vessels under German flag. Hamburg and Bremen port operators pilot methanol supply chains for feeder container services.
Japan
Mitsubishi Heavy Industries and Yanmar advance four-stroke methanol engines for coastal and auxiliary applications. METI's green innovation fund subsidizes methanol fuel cell demonstrations in domestic shipping corridors. Nagoya and Kobe manufacturing bases coordinate with classification society ClassNK on methanol safety protocols.
Marine Methanol Engine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated engine OEMs commanding premium pricing for dual-fuel architectures while shipyards pursue in-house capability development. Market structure tilts toward consolidation at the high-power end, where two-stroke development costs exclude mid-tier entrants. Strategic archetypes include technology licensors, integrated power system suppliers, and shipyard-captive engine divisions. Dominant competitive moves center on modular conversion kit development and strategic bunkering infrastructure partnerships.
Among European integrated power system suppliers, MAN Energy Solutions and Wärtsilä occupy positions spanning two-stroke and four-stroke methanol architectures. South Korean shipyard-captive engine divisions, represented by Hyundai Heavy Industries, exemplify vertical manufacturing integration from hull construction through propulsion system commissioning. WinGD, a Swiss-based technology licensor, represents the specialized two-stroke design house archetype focused on low-pressure methanol injection for bulk carrier and tanker segments.
| Leading Market Players |
|---|
| MAN Energy Solutions |
| Wärtsilä |
| WinGD |
| Caterpillar |
| Hyundai Heavy Industries |
| Hanwha Engine |
| Yanmar |
| Rolls-Royce Power Systems |
| Mitsubishi Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal maritime emissions trading extension gates qualified supply and premium-tier pricing access, compressing margins for operators lacking dual-fuel certification while rewarding compliant engine OEMs with preferential contract terms. Shipowners face a bifurcated procurement landscape where IMO carbon intensity compliance separates price-takers from price-makers across the newbuild and retrofit segments.
Pricing Analysis
Volume concentrates in standardized two-stroke contracts while margins concentrate in modular dual-fuel conversion kits. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from green methanol cost premiums compressing operator spot-rate economics. Container lines with science-based targets exhibit lowest price sensitivity; artisanal fishing cooperatives face acute capital constraints.
Supply Chain Analysis
Reverse-logistics flows for engine refurbishment and remanufacturing center on Augsburg, Copenhagen, and Ulsan manufacturing bases. Component sourcing draws from South Korea, Germany, and Japan for precision fuel injection systems and electronic control modules. Nickel alloy and high-pressure pump dependencies create single-source vulnerability for specialized subassemblies. Distribution runs through shipyard-captive procurement channels and OEM direct sales for aftermarket conversion programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IMO carbon intensity indicator framework operates as a cost-of-compliance story, erecting a barrier-to-entry moat for engine manufacturers with approved dual-fuel type certifications from DNV, Lloyd's Register, and Bureau Veritas.
For Market Incumbents: To counter low-pressure methanol injection entrants from Asian shipyard-captive divisions, MAN Energy Solutions and Wärtsilä should deepen backward integration into electronic fuel injection module production and accelerate modular conversion kit certification timelines. Priority investment in Rotterdam-Antwerp bunkering corridor partnerships secures fuel availability guarantees that lock in long-term service contracts. For New Entrants and Emerging Players: Japanese coastal shipping operators represent an underserved buyer archetype with METI subsidy support and limited incumbent penetration. First-mover positioning in four-stroke auxiliary engine retrofits for domestic ferry routes offers white-space access before carbon intensity rules finalize. Go-to-market execution through ClassNK-certified local engineering partners reduces approval timeline risk. For Investors and Strategic Acquirers: Korean Register of Shipping fast-track approval announcements for dual-fuel methanol systems is the leading indicator that shipyard-captive engine divisions are scaling production capacity. Long-term viability favors vertically integrated manufacturers with in-house fuel system testing and bunkering infrastructure partnerships. Acquisition targets should demonstrate captive port relationships and classification society pre-approval pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Conversion Kit Development | Compresses retrofit yard time from months to weeks for bulk carrier operators. |
| Bunkering Infrastructure Partnership | Secures fuel availability guarantees at Rotterdam, Singapore, and Antwerp terminals. |
| Classification Society Fast-Track | Accelerates DNV and Korean Register approval timelines for dual-fuel systems. |
| Green Methanol Supply Agreement | Locks in bio-methanol and e-methanol offtake for EU-Asia container routes. |
| Digital Twin Commissioning | Absorbs six to eight weeks from newbuild sea trial schedules for MAN and Wärtsilä. |
Research Methodology
Independent corroboration across engine OEM technical directors, shipyard procurement leads, and port authority fuel infrastructure planners underwrites the qualitative findings. Primary fieldwork involved structured interviews with classification society surveyors, container line fleet managers, and marine engineering consultants across Northern Europe and East Asia. Secondary validation drew from IMO regulatory filings, EU Green Deal implementation documents, Korean Register type approval databases, and customs trade data for methanol engine component flows. Bottom-up vessel order book analysis and top-down fuel consumption modeling were cross-referenced for triangulation.
Rate-of-change decomposition across the analysis window isolates technology adoption curves from regulatory enforcement phases and bunkering infrastructure buildout timing. Segmentation dimensions modeled include engine architecture, vessel application category, fuel chemistry tier, and regional regulatory cluster. CAGRs were derived from installed base projections and replacement cycle analysis. Industry-specific forecast inputs incorporated Rotterdam-Antwerp corridor utilization rates and METI subsidy program disbursement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to green methanol production scale-up and EU taxonomy rule refinements. Practitioners should monitor Korean Register fast-track approval volumes and Singapore Tuas port methanol storage commissioning for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Boat Davits Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Marine Fuel Injection System Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Sea-Based Vehicle Carrier Market
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Hydrogen-Powered Yacht Market