
 Marine Reciprocating Engine Market | 2026-2036
Marine Reciprocating Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Reciprocating Engine Market Insights
The split between premium dual-fuel systems and conventional diesel architectures is shifting order patterns across shipyards. Wärtsilä leverages its LNG portfolio to anchor premium positioning in container and tanker segments. MAN Energy Solutions sustains technology leadership through two-stroke ammonia-ready development programs. Cummins competes in the high-speed auxiliary engine tier where retrofit cycles run shorter and price sensitivity runs higher.
A marine reciprocating engine converts thermal energy from fuel combustion into mechanical work through piston-driven crankshaft rotation, typically operating at compression ratios between 12:1 and 22:1 depending on fuel type and speed classification. These engines serve as primary or auxiliary propulsion systems aboard commercial vessels, offshore platforms, and naval craft where torque density and fuel flexibility determine operational economics. Two-stroke engines dominate deep-sea propulsion applications where thermal efficiency above 50 percent justifies their physical scale and maintenance complexity. Four-stroke architectures lead in auxiliary power and medium-speed propulsion roles where space constraints and load responsiveness matter more than absolute fuel economy. LNG fuel type penetration is accelerating fastest among fuel categories as EEDI Phase 3 compliance deadlines tighten and bunkering infrastructure matures at Rotterdam, Singapore, and Busan.
The International Maritime Organization's MARPOL Annex VI framework, enforced by flag-state administrations including the US Coast Guard and Panama Maritime Authority, mandates progressive sulfur oxide and nitrogen oxide emission reductions that directly determine engine certification pathways and market access. The EU MRV regulation and IMO's Carbon Intensity Indicator add operational transparency requirements that favor engines with verified fuel consumption profiles and onboard monitoring integration. Shipowners and engine OEMs must monitor ammonia and methanol fuel readiness standards as classification societies including DNV and Lloyd's Register finalize safety rules for alternative fuels.
Market Dynamics
Dual-fuel propulsion architecture is fragmenting procurement criteria between deep-sea operators pursuing EEDI Phase 3 compliance and coastal fleets prioritizing capital efficiency over fuel flexibility.
Growth Catalysts
- IMO MARPOL Annex VI Phase 3:Container ship operators in South Korea and China face mandatory carbon intensity reductions that favor LNG-ready engine retrofits over conventional diesel architectures.
- Rotterdam-Singapore-Busan bunkering triangle:LNG infrastructure maturation at these three ports removes operational uncertainty that previously constrained dual-fuel adoption among tanker fleets.
- Ammonia-ready two-stroke development:Classification societies DNV and Lloyd's Register advancing safety rules for ammonia combustion are pulling forward R&D investment from engine OEMs.
Market Restraints
- Nickel and cobalt price volatility:Catalyst materials for exhaust after-treatment systems face input cost swings that compress margin visibility for mid-speed engine manufacturers.
- South Korean yard concentration:Hyundai Heavy Industries and Samsung Heavy Industries control over half of newbuild contracting, creating single-source dependency risk for European engine suppliers.
- Ammonia toxicity standards:Pending IMO guidelines for crew safety and fuel handling are delaying certification timelines that would otherwise unlock 2028-2030 order windows.
Strategic Opportunities
- India coastal fleet modernization:The country's Maritime India Vision 2030 targets 500+ vessel additions where high-speed auxiliary engines face shorter replacement cycles and lower price elasticity than deep-sea propulsion.
- Methanol-to-hydrogen reforming convergence:Integration of onboard reforming systems with four-stroke medium-speed engines opens retrofit pathways for existing Ro-Ro and ferry operators.
- EU Emissions Trading System maritime inclusion:Carbon pricing mechanisms covering voyages to and from European ports create compliance cost arbitrage that rewards verifiable fuel consumption monitoring.
Industry Challenges
- Combustion simulation talent scarcity:Computational fluid dynamics expertise for alternative fuel injection mapping concentrates among a handful of specialized engineering consultancies.
- Retrofit integration complexity:Legacy crankcase designs from the 1990s-2000s newbuild wave require structural modifications to accommodate dual-fuel injection hardware without dry-dock timeframes that exceed charter loss tolerance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Reciprocating Engine Market |
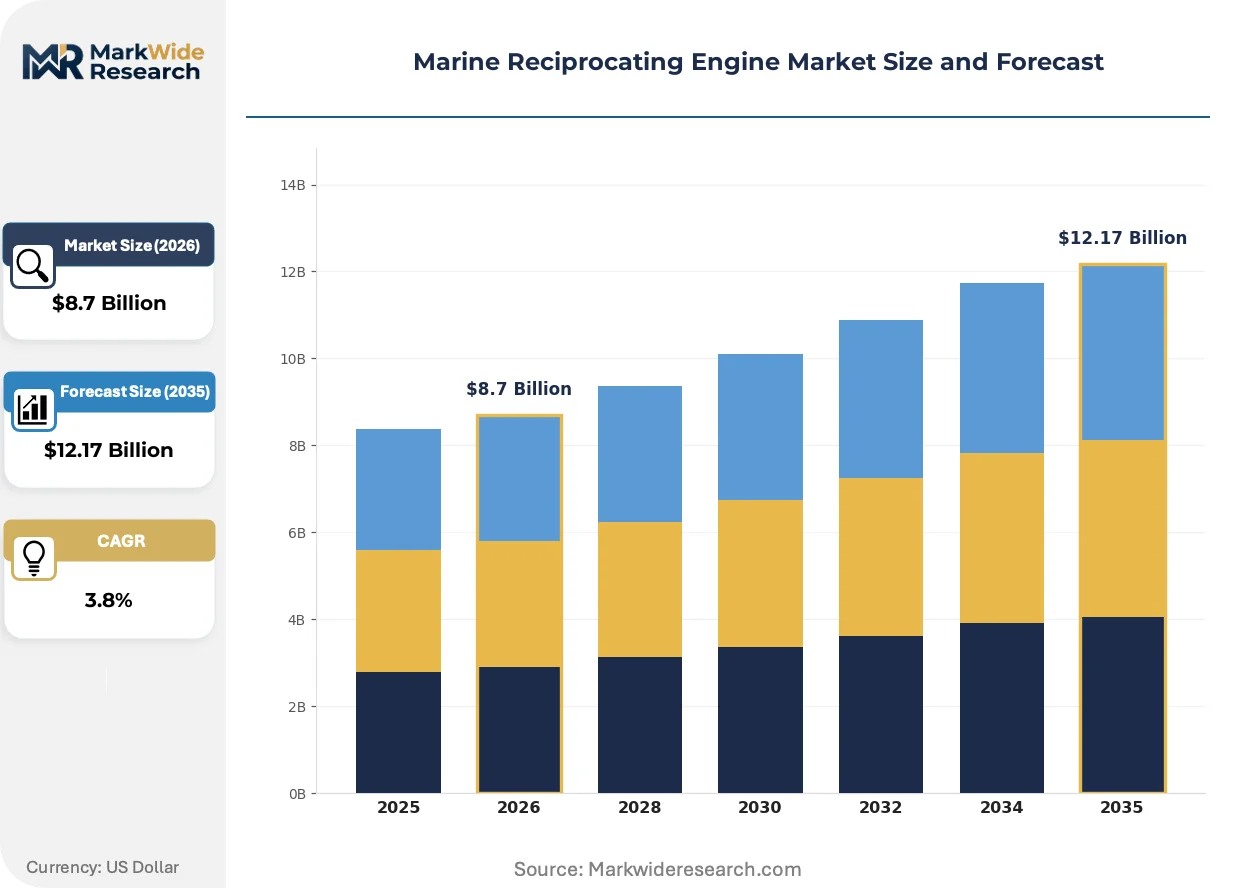
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Two-stroke, Four-stroke, Medium-speed, High-speed Fuel Type: Marine Diesel Oil, Heavy Fuel Oil, Liquefied Natural Gas, Marine Gas Oil Vessel Application: Container Ships, Bulk Carriers, Tankers, Passenger Ships End User: Shipbuilders, Maritime Operators, Offshore Service Providers, Government Maritime Agencies |
| Companies Covered | Caterpillar, Wärtsilä, MAN Energy Solutions, Rolls-Royce, Cummins, AB Volvo Penta, Mitsubishi Heavy Industries, Yanmar Holdings, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Reciprocating Engine Market Trends and Innovations
Propulsion system electrification is compressing the boundary between mechanical power transmission and integrated power management, forcing engine OEMs to recast their value proposition around energy optimization rather than standalone hardware supply.
Digital twin-based performance optimization is electrifying how operators manage combustion efficiency across variable load profiles. Container lines including MSC and Maersk subsidiary fleets are deploying vessel-wide sensor networks that feed real-time cylinder pressure data to shore-based analytics centers. This convergence of mechanical engineering and cloud infrastructure is compressing the traditional separation between engine manufacturing and aftermarket service revenue streams.
The EU F-Gas Regulation and its phasedown of hydrofluorocarbon refrigerants is redirecting investment toward CO2-based secondary loop cooling for engine room climate control. Shipyards in Germany and Finland are specifying low-global-warming-potential alternatives for newbuild contracts destined for European flag registries. This regulatory pressure is most acute in the cruise and ferry segment where passenger comfort requirements conflict with refrigerant containment complexity.
Charterers now specify fuel consumption transparency clauses that unbundle engine warranty from performance guarantees. Greek and Singapore-based shipowners are demanding ISO 19030-compliant hull and propeller monitoring as a condition of fixture, displacing traditional time-based maintenance contracts. This behavioral shift is most visible in the Capesize bulk carrier segment where voyage economics hinge on marginal fuel efficiency gains.
Marine Reciprocating Engine Market Segmentation
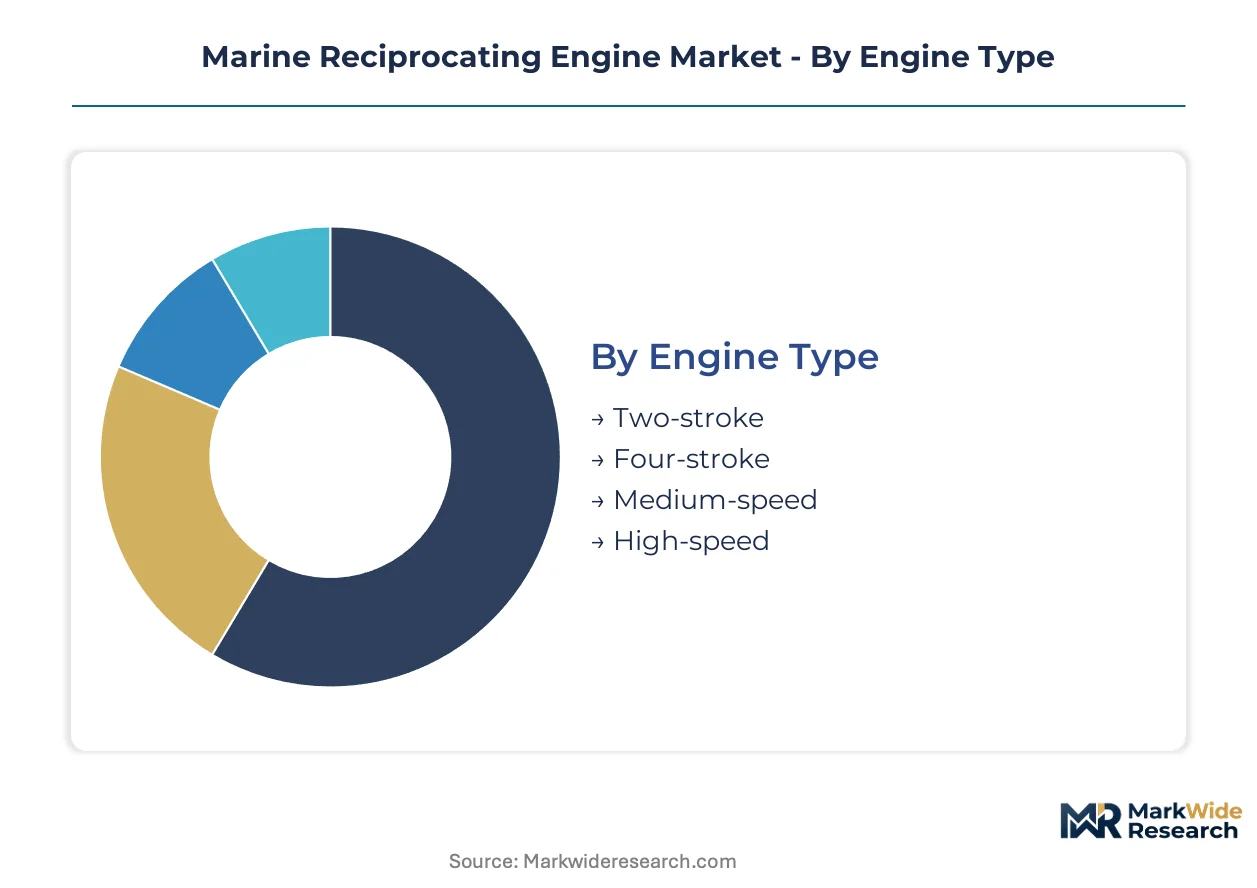
Segmentation in marine reciprocating engines reveals how procurement criteria diverge between deep-sea operators prioritizing thermal efficiency and coastal fleets optimizing capital deployment. Understanding these splits clarifies why two-stroke architectures command premium positioning while high-speed segments face compressed replacement cycles.
Engine Type:
Standardization dominates at the low-speed extreme where two-stroke designs achieve thermal efficiency above 50 percent, while customization intensifies toward higher speeds where space constraints and load responsiveness reshape specifications.
- Two-stroke:These engines operate at compression ratios between 15:1 and 22:1 with uniflow or loop scavenging architectures that maximize thermal efficiency in deep-sea propulsion roles. Demand concentrates among container ship operators in South Korea where Hyundai Heavy Industries and Samsung Heavy Industries anchor newbuild contracting for EEDI Phase 3 compliance.
- Four-stroke:Operating at 500-1,000 RPM with trunk or crosshead piston configurations, these architectures sacrifice absolute fuel economy for compact footprint and rapid load response. Medium-speed variants dominate auxiliary power generation aboard tankers where redundancy requirements override single-engine efficiency optimization.
- Medium-speed:Spanning 300-1,000 RPM, these engines bridge the gap between slow-speed propulsion and high-speed auxiliary roles with modular cylinder configurations.
- High-speed:Operating above 1,000 RPM, these engines serve fast ferry and naval craft where power-to-weight ratios determine competitive viability.
Most installed capacity flows through two-stroke architectures. Expansion is steepest in high-speed segments where Indian coastal fleet modernization drives replacement demand.
Fuel Type:
Cost tier stratification separates established liquid fuels with mature bunkering infrastructure from gaseous alternatives requiring capital-intensive storage and delivery systems.
- Marine Diesel Oil:A distillate fuel with sulfur content capped at 0.5 percent under IMO MARPOL Annex VI, this specification dominates auxiliary engine applications where cold-start reliability and combustion stability matter more than unit fuel cost. Demand concentrates in retrofit markets where legacy vessel operators prioritize operational continuity over fuel flexibility investments.
- Liquefied Natural Gas:Stored at minus 162 degrees Celsius in Type C vacuum-insulated tanks, this fuel requires dual-fuel injection systems and cryogenic handling infrastructure that add 15-25 percent to propulsion system capital cost. The Rotterdam-Singapore-Busan bunkering triangle removes operational uncertainty that previously constrained adoption among tanker fleets pursuing EEDI Phase 3 compliance.
- Heavy Fuel Oil:Residual fuel requiring onboard purification and heated storage systems, this lowest-cost option retains share in bulk carrier segments where voyage economics tolerate higher maintenance burden.
- Marine Gas Oil:Ultra-low sulfur distillate meeting 0.1 percent caps in Emission Control Areas, this fuel serves as compliance bridge where scrubber installation is uneconomical.
Volume concentration remains with residual and distillate liquid fuels. LNG-compatible systems are climbing the fastest as bunkering infrastructure matures at priority ports.
Vessel Application:
Application-driven specification divergence separates deep-sea trades where thermal efficiency dominates from passenger segments where redundancy and comfort requirements reshape priorities.
- Container Ships:These vessels demand propulsion systems delivering 40,000-80,000 kW in single-engine configurations where specific fuel consumption below 160 g/kWh justifies two-stroke scale and complexity. South Korean yards concentrate newbuild contracting for 15,000-24,000 TEU vessels where EEDI Phase 3 deadlines accelerate LNG-ready engine specification.
- Tankers:Crude and product carriers prioritize cargo space preservation through compact engine room layouts, favoring medium-speed four-stroke architectures with integrated shaft generators. Demand clusters in Greek and Singapore-based fleets where charter rate sensitivity amplifies fuel efficiency scrutiny.
- Bulk Carriers:Capesize and Panamax segments accept lower propulsion power density in exchange for capital cost minimization and maintenance accessibility.
- Passenger Ships:Cruise and ferry operators specify vibration-isolated four-stroke configurations where passenger comfort requirements override pure fuel economy optimization.
Order value concentrates in container ship propulsion. Steepest specification change is occurring in tanker segments where dual-fuel retrofits respond to charterer carbon intensity clauses.
End User:
Customer type determines whether procurement emphasizes first-cost minimization, lifecycle cost optimization, or regulatory compliance assurance.
- Shipbuilders:These integrators specify engines as part of total vessel construction contracts where delivery schedule certainty and warranty integration outweigh standalone component pricing. Hyundai Heavy Industries and Samsung Heavy Industries in South Korea concentrate procurement leverage through volume aggregation across multiple vessel programs.
- Maritime Operators:Container lines including MSC and Maersk subsidiary fleets deploy vessel-wide sensor networks that feed real-time cylinder pressure data to shore-based analytics centers, unbundling engine warranty from performance guarantees.
- Offshore Service Providers:Platform supply and anchor handling vessel operators prioritize load responsiveness and redundancy over absolute fuel efficiency in harsh environment operations.
- Government Maritime Agencies:Naval procurement emphasizes operational security through domestic supply chain requirements and classified performance specifications that override commercial efficiency metrics.
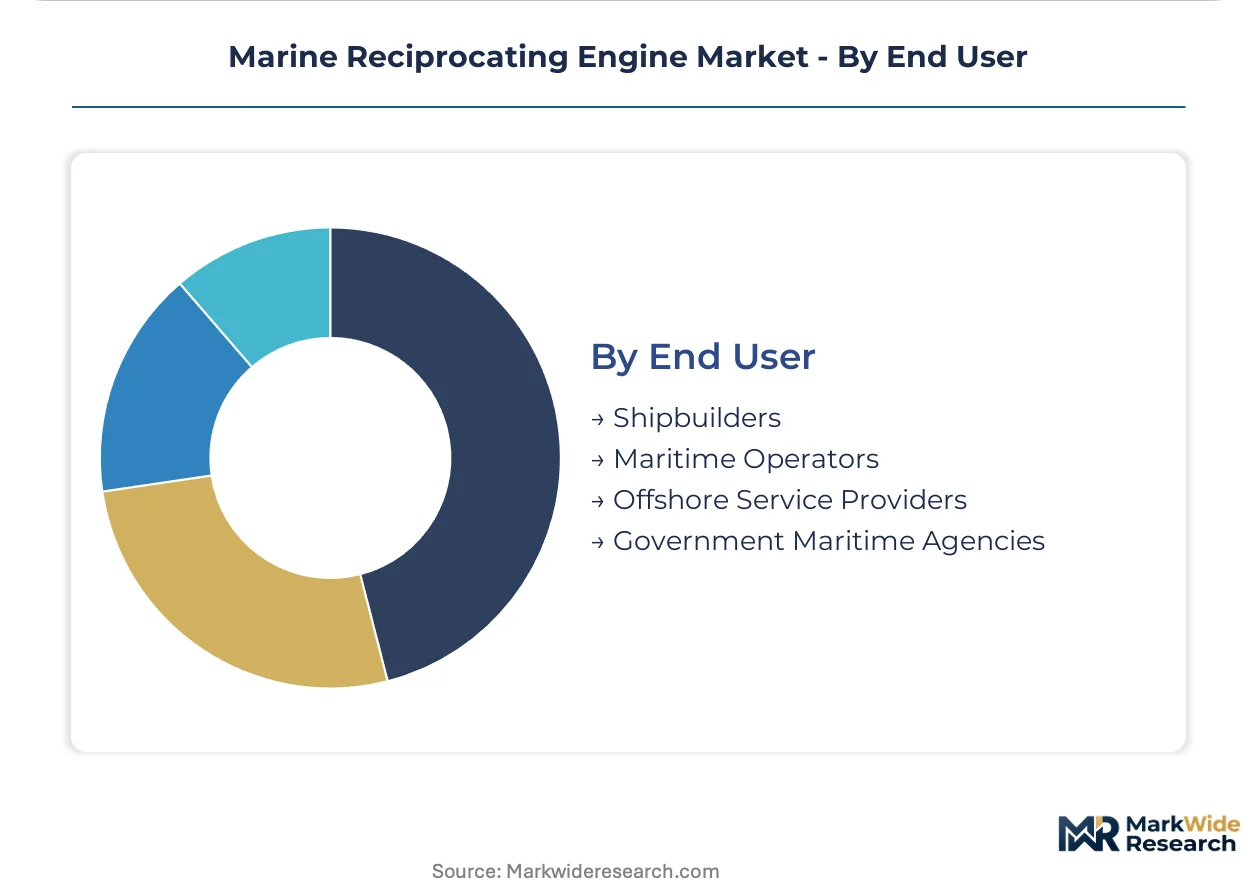
Shipbuilders channel the largest engine volume. Maritime operators are gaining procurement influence fastest through performance-based chartering clauses and fuel transparency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine engineering talent clusters in South Korea's shipbuilding belt, Germany's northern industrial corridor, and Japan's maritime manufacturing centers. These workforce concentrations anchor regional demand patterns for propulsion systems.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries concentrate newbuild contracting for 15,000-24,000 TEU container vessels where EEDI Phase 3 compliance accelerates LNG-ready engine specification. The country's Ministry of Oceans and Fisheries enforces Green Ship-K certification standards that mandate dual-fuel compatibility for subsidized fleet renewal. Ulsan and Geoje shipyards channel over half of global ultra-large container vessel propulsion demand.
China
State-owned shipbuilders at Dalian, Shanghai, and Guangzhou expand two-stroke engine manufacturing partnerships with European licensors to reduce import dependency. MIIT's 14th Five-Year Plan for Shipbuilding prioritizes domestic production of low-speed marine engines above 80,000 kW. The Yangtze River Delta anchors auxiliary engine demand for coastal bulk carriers serving domestic cabotage trades.
Japan
METI's GX League decarbonization commitments pull forward ammonia-ready two-stroke development programs at Nagasaki and Kobe manufacturing sites. Classification society Nippon Kaiji Kyokai advances safety rules for alternative fuel handling that shape OEM certification timelines. The Setouchi region concentrates medium-speed four-stroke production for domestic ferry and coastal tanker operators.
Germany
Augsburg and Hamburg engineering centers sustain two-stroke fuel injection technology leadership through computational fluid dynamics expertise concentrated among specialized consultancies. The EU Emissions Trading System maritime inclusion creates compliance cost arbitrage for vessels calling at Hamburg and Bremerhaven. Lower Saxony shipyards specify methanol-ready medium-speed engines for North Sea offshore service vessels.
United States
EPA Tier 4 marine engine standards and US Coast Guard MARPOL Annex VI enforcement shape certification pathways for Great Lakes bulk carriers and Jones Act tankers. Caterpillar and Cummins manufacturing footprints in Illinois and Indiana anchor high-speed auxiliary engine supply for inland waterway operators. The Gulf Coast concentrates LNG bunkering infrastructure development at Houston and Corpus Christi that enables dual-fuel retrofits for tanker fleets.
Marine Reciprocating Engine Market Competitive Landscape
Top-tier vendors anchor technology leadership in two-stroke propulsion systems, while mid-tier specialists compete on four-stroke auxiliary engine customization and aftermarket service density. The market structure reflects dual-fuel R&D concentration among a handful of integrated OEMs with classification society partnerships. Three archetypes dominate: full-line propulsion integrators, high-speed engine specialists, and regional license-holders with manufacturing joint ventures. Competitive moves center on ammonia-ready platform development and digital twin service contracts that unbundle hardware from performance guarantees.
Among European integrated OEMs, Wärtsilä and MAN Energy Solutions occupy positions as archetypes of full-line propulsion strategy, with the former representing LNG portfolio depth and the latter exemplifying two-stroke ammonia-ready development investment. Caterpillar anchors the high-speed auxiliary engine tier where shorter replacement cycles and price-sensitive procurement reshape competitive positioning. These three companies collectively illustrate how geographic origin and organizational scale map to distinct strategic postures in a market fragmenting between deep-sea efficiency optimization and coastal fleet capital efficiency.
| Leading Market Players |
|---|
| Caterpillar |
| Wärtsilä |
| MAN Energy Solutions |
| Rolls-Royce |
| Cummins |
| AB Volvo Penta |
| Mitsubishi Heavy Industries |
| Yanmar Holdings |
| General Electric |
| Others |
Pricing and Supply Chain Analysis
Container ship operators at Hyundai Heavy Industries and Samsung Heavy Industries concentrate procurement leverage through volume aggregation, forcing engine OEMs toward performance-linked contract structures that unbundle hardware from aftermarket service guarantees. This buyer concentration compresses margin visibility for mid-speed engine manufacturers while rewarding integrated suppliers with dual-fuel certification depth.
Pricing Analysis
Hardware-software unbundling is fragmenting contract structures across the marine propulsion tier. Three-tier pricing structure across premium, standard, and economy levels separates ammonia-ready two-stroke platforms from conventional diesel architectures and high-speed auxiliary engines. Price differentiation rests on EEDI Phase 3 certification status and integrated digital twin monitoring capabilities. Cost compression in the high-speed auxiliary tier is intensifying because Indian coastal fleet operators prioritize capital efficiency over fuel flexibility. Greek and Singapore-based shipowners exhibit lowest price sensitivity where charter rate economics reward verified fuel consumption transparency.
Supply Chain Analysis
Refurbishment flows for legacy crankcase designs from the 1990s-2000s newbuild wave are creating secondary parts markets that compete with OEM aftermarket channels. Manufacturing concentration centers on South Korea, Germany, and Japan where two-stroke fuel injection technology and computational fluid dynamics expertise cluster. Nickel and cobalt catalyst materials for exhaust after-treatment systems draw from mining operations in Indonesia and the Democratic Republic of Congo. Single-source vulnerability runs through South Korean yard concentration where Hyundai Heavy Industries and Samsung Heavy Industries control over half of newbuild contracting. Distribution runs through shipbuilder-integrated procurement with direct OEM relationships displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine reciprocating engine market functions as a stable compounder where IMO decarbonization timelines generate predictable replacement cycles across deep-sea and coastal fleets. Regulatory compliance deadlines create visible demand windows that reduce forecasting volatility relative to discretionary capital equipment sectors.
For Market Incumbents: Anchor technology leadership in ammonia-ready two-stroke development programs before classification societies finalize safety rules. Defend against emerging Chinese engine manufacturers by deepening backward integration into fuel injection system production. Prioritize certification investment with DNV and Lloyd's Register to lock in premium positioning for 2028-2030 order windows. For New Entrants and Emerging Players: Enter via India's Maritime India Vision 2030 coastal fleet modernization where high-speed auxiliary engine replacement cycles run shorter and procurement criteria favor cost efficiency over brand heritage. Target the methanol-to-hydrogen reforming convergence segment for Ro-Ro and ferry operators seeking retrofit pathways without dry-dock timeframes exceeding charter loss tolerance. Pursue joint development agreements with European consultancies possessing scarce computational fluid dynamics expertise for alternative fuel injection mapping. For Investors and Strategic Acquirers: Marine engine OEMs with integrated digital twin service platforms are the most active acquirer targets in this space as hardware margins compress and recurring revenue streams gain valuation premium. Long-term viability favors suppliers with ammonia-ready certification pipelines and established classification society partnerships over pure manufacturing scale. Monitor IMO guideline finalization for ammonia toxicity standards as the critical inflection signal for 2028-2030 order window unlocking.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Ready Platform Development | Positions OEMs for IMO alternative fuel certification before competitors achieve safety rule compliance. |
| Digital Twin Service Integration | Enables MSC and Maersk fleets to unbundle engine warranty from ISO 19030-compliant performance guarantees. |
| Backward Integration into Fuel Injection | Secures supply chain control over two-stroke combustion technology concentrated in German engineering centers. |
| Joint Venture with Classification Society | Accelerates certification timelines with DNV and Lloyd's Register for dual-fuel propulsion systems. |
| High-Speed Auxiliary Engine Capacity Expansion | Captures Indian coastal fleet replacement demand under Maritime India Vision 2030 vessel addition targets. |
Research Methodology
Bottom-up vessel application modeling reconciled against top-down engine OEM production tracking forms the analytical core of this study. Primary interviews with shipyard procurement directors, maritime operator fleet managers, classification society technical leads, and aftermarket service heads were validated against secondary sources including IMO MARPOL Annex VI regulatory filings, Lloyd's Register and DNV certification databases, and EU MRV emissions monitoring records. Triangulation between installation data from South Korean and Chinese shipbuilders and order book disclosures from European integrated OEMs ensures statistical consistency across the analysis window.
Input-output matrices map engine type, fuel compatibility, and vessel application dimensions against regional regulatory frameworks and bunkering infrastructure maturity. Segmentation modeling spans two-stroke versus four-stroke architectures, LNG versus residual fuel specifications, and container ship versus tanker versus bulk carrier applications. CAGRs were derived from order book run-rates and replacement cycle analysis rather than macroeconomic extrapolation. Forecast inputs include EEDI Phase 3 compliance deadlines, Rotterdam-Singapore-Busan LNG bunkering infrastructure buildout, and ammonia-ready engine development timelines.
Inputs from shipyard order books and classification society certification records were available through the study window; gaps in ammonia toxicity standard finalization and methanol fuel handling rules introduce uncertainty bands around alternative fuel adoption trajectories. Forecasts reflect assumptions regarding IMO regulatory enforcement consistency and bunkering infrastructure investment continuity. Practitioners should monitor classification society safety rule advancement and South Korean yard capacity utilization for early signals of order window timing and pricing pressure direction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Global Boat Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Airboats Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Marine Fuel Injection System Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Air-Cushion Vehicle Market