
 Crane Barge Market | 2026-2036
Crane Barge Market Size, Share, and Industry Trends Forecast 2026-2036
Crane Barge Market Analytics
Modular crane barge configurations is decoupling vessel ownership from project-specific lift requirements, letting contractors charter customized units without full capital commitment. Damen Shipyards Group leverages standardized hull platforms to reduce delivery cycles for modular builds. Heerema Marine Contractors anchors its competitive position through in-house engineering of heavy-lift systems integrated onto purpose-built barges. Van Oord sustains fleet flexibility by operating a mixed portfolio of self-propelled and non-propelled units across European offshore wind zones.
A crane barge is a flat-deck marine vessel equipped with one or more pedestal or lattice-boom cranes, typically rated from 200 to over 1,000 tons lifting capacity, designed to perform heavy lifts in harbors, rivers, or open water where land-based cranes cannot operate. The vessel's hull form prioritizes stability through pontoon-style construction with ballast systems that counteract overturning moments during load picks. Self-propelled crane barges command premium day rates due to reduced tug dependency, while non-propelled units dominate long-term deployment contracts where mobility is secondary to lift capacity. The above-1000-tons load capacity segment captures concentrated margin pools from offshore oil platform decommissioning and next-generation wind turbine installation.
The International Maritime Organization's Energy Efficiency Existing Ship Index shapes newbuild specifications by penalizing high-emission hull designs, while classification societies including Lloyd's Register and DNV enforce structural standards for dynamic positioning and crane load charts. The EU Green Deal's sustainable maritime fuels mandate accelerates hybrid propulsion adoption among European-flagged operators. Stakeholders must monitor how carbon border adjustments on marine equipment imports reshape build-versus-charter economics across regional fleets.
Market Dynamics
Hybrid propulsion retrofits are compressing vessel replacement cycles as owners weigh charter rate premiums against compliance penalties under tightening carbon intensity regimes.
Growth Catalysts
- Offshore wind farm installation:Turbine scaling beyond 15MW requires heavy-lift vessels with 1,000-ton-plus hook capacity, pulling forward fleet renewal timelines among European marine contractors.
- China's port expansion programs:State-backed coastal infrastructure investment sustains domestic orders for modular crane barge configurations with standardized hull platforms.
- IMO Energy Efficiency Existing Ship Index:The regulation penalizes high-emission hull designs, accelerating owner investment in battery-hybrid propulsion systems and shore-power compatibility.
Market Restraints
- Steel plate cost volatility:Hull construction depends on high-tensile marine-grade steel, with price swings compressing shipyard margins on fixed-price newbuild contracts.
- Asian shipyard concentration:Over 70% of heavy-lift vessel construction concentrates in Chinese and South Korean yards, creating bottlenecks during order surges.
- Dynamic positioning certification delays:Lloyd's Register and DNV structural approval timelines extend 8-14 months, stretching capital deployment cycles for specialized units.
Strategic Opportunities
- US Gulf Coast decommissioning:Aging oil platform removal creates demand for above-1,000-ton lift capacity in a market currently served by chartered European assets.
- EU Green Deal sustainable fuels mandate:The regulation accelerates methanol-ready newbuild specifications among European-flagged operators seeking future fuel flexibility.
- Modular crane integration:Lattice-boom systems from onshore manufacturers are converging with marine pedestal foundations, enabling faster reconfiguration between harbor and offshore duties.
Industry Challenges
- Marine crane operator certification:Shortages of personnel qualified for simultaneous crane operations in dynamic positioning mode limit vessel utilization rates during complex lifts.
- Ballast system integration complexity:Retrofitting automated stability controls onto legacy pontoon hulls requires extensive structural modification and class society reapproval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crane Barge Market |
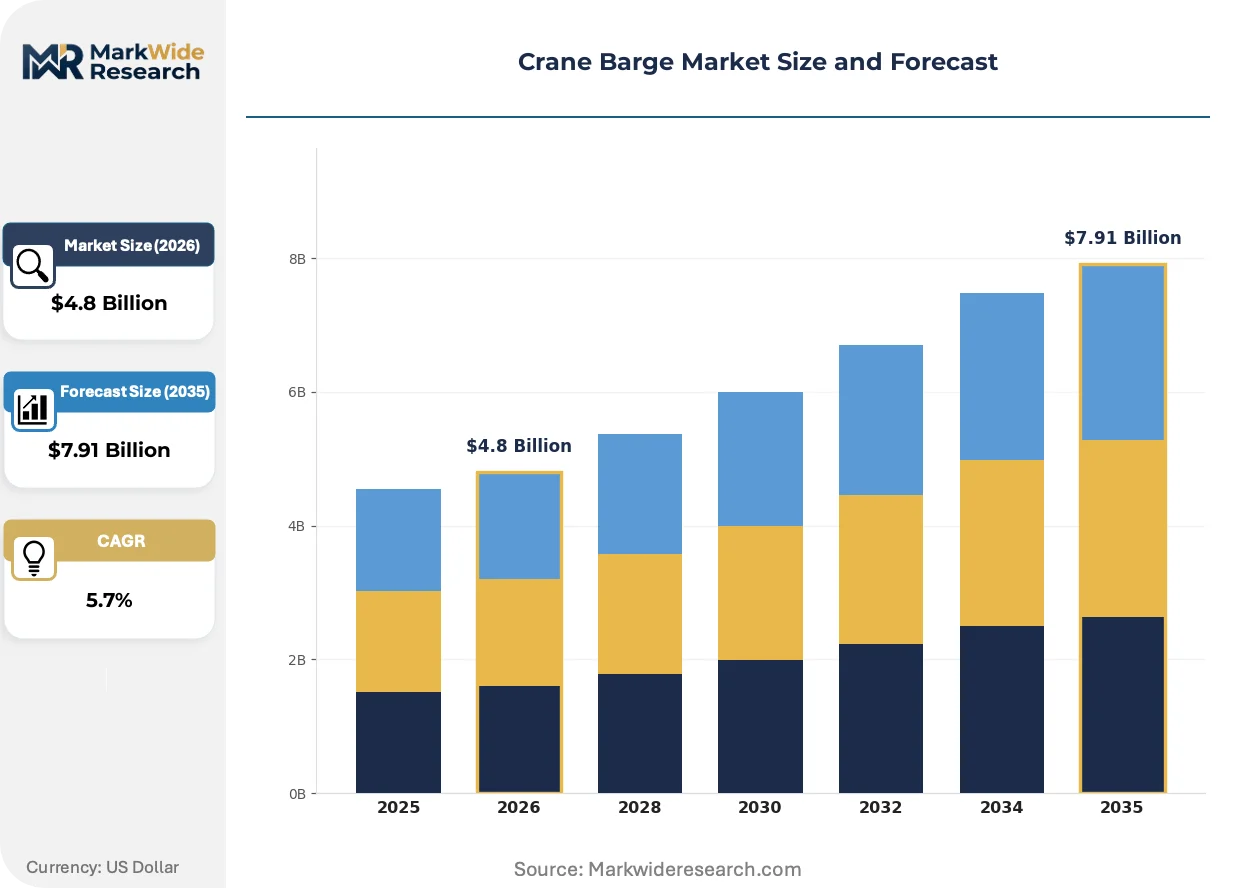
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Self-Propelled, Non-Propelled, Modular, Hybrid Application: Construction, Dredging, Maintenance, Offshore Operations End User: Marine Contractors, Shipping Companies, Government Agencies, Oil & Gas Load Capacity: Below 200 Tons, 200-500 Tons, 500-1000 Tons, Above 1000 Tons |
| Companies Covered | Damen Shipyards Group, Donjon Marine Co., Inc., Heerema Marine Contractors, Van Oord, Saipem S.p.A., TechnipFMC plc, Liebherr Group, Konecranes, Huisman Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crane Barge Market Evolving Landscape
Digital twin technology is compressing vessel commissioning timelines while regulatory pressure on emissions intensifies hardware-software integration across newbuild specifications.
Condition-based monitoring systems using fiber-optic strain sensors are converging with cloud-based fleet analytics platforms. Offshore wind contractors are adopting these packages on 18-24 month charter contracts. The technology is converging with predictive maintenance workflows that reduce unplanned downtime during turbine installation weather windows.
The EU Green Deal's sustainable maritime fuels mandate is forcing methanol and ammonia-ready engine specifications into newbuild tenders. European-flagged operators face 2030 compliance deadlines for well-to-wake emissions reductions. Above-1,000-ton capacity units on order at Dutch and German yards now incorporate dual-fuel architecture as standard.
Charterers are unbundling crane barge contracts from integrated installation packages. Independent vessel operators in the North Sea now bid directly to project developers, bypassing traditional marine contractor intermediaries. This disintermediation is most advanced in German and Danish offshore wind zones where developer-owned port infrastructure reduces logistics coordination complexity.
Crane Barge Market Segmentation
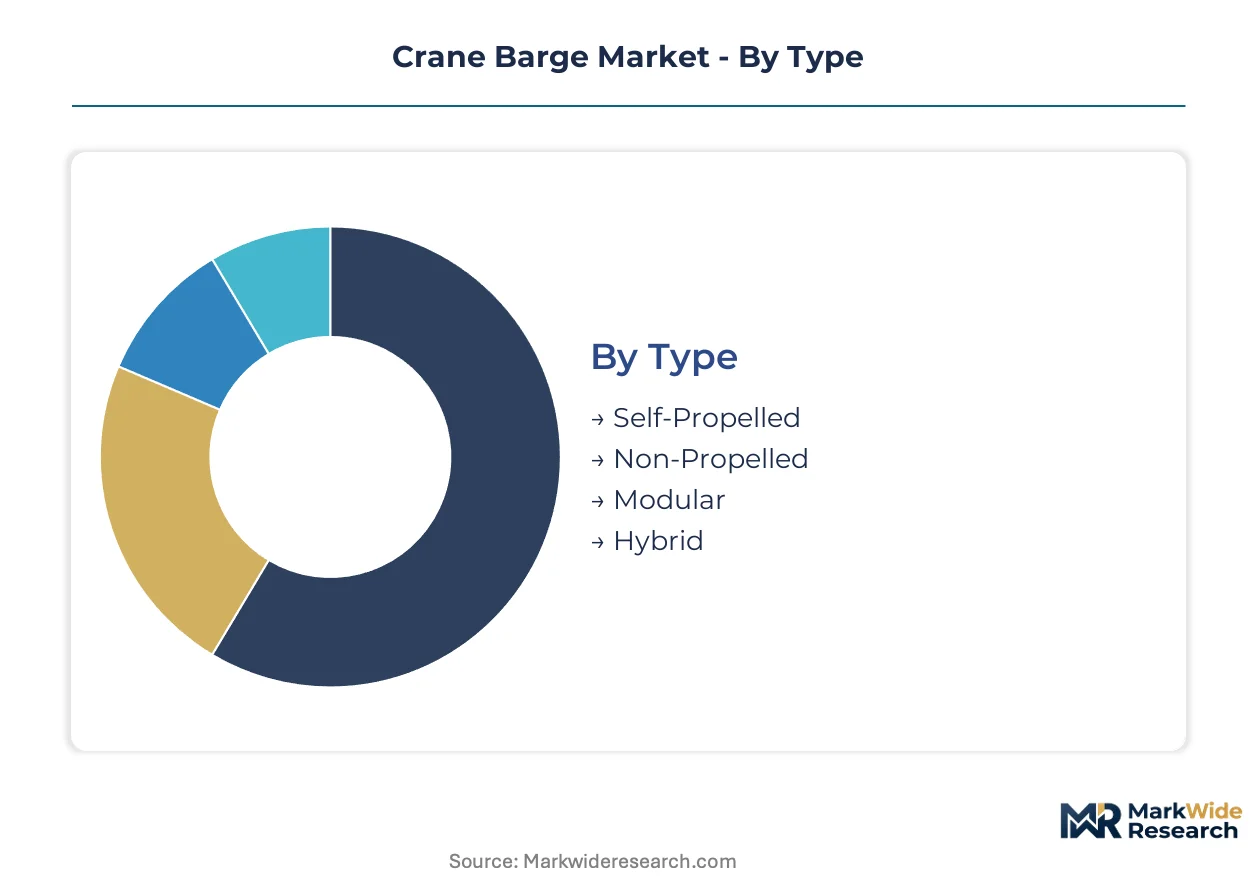
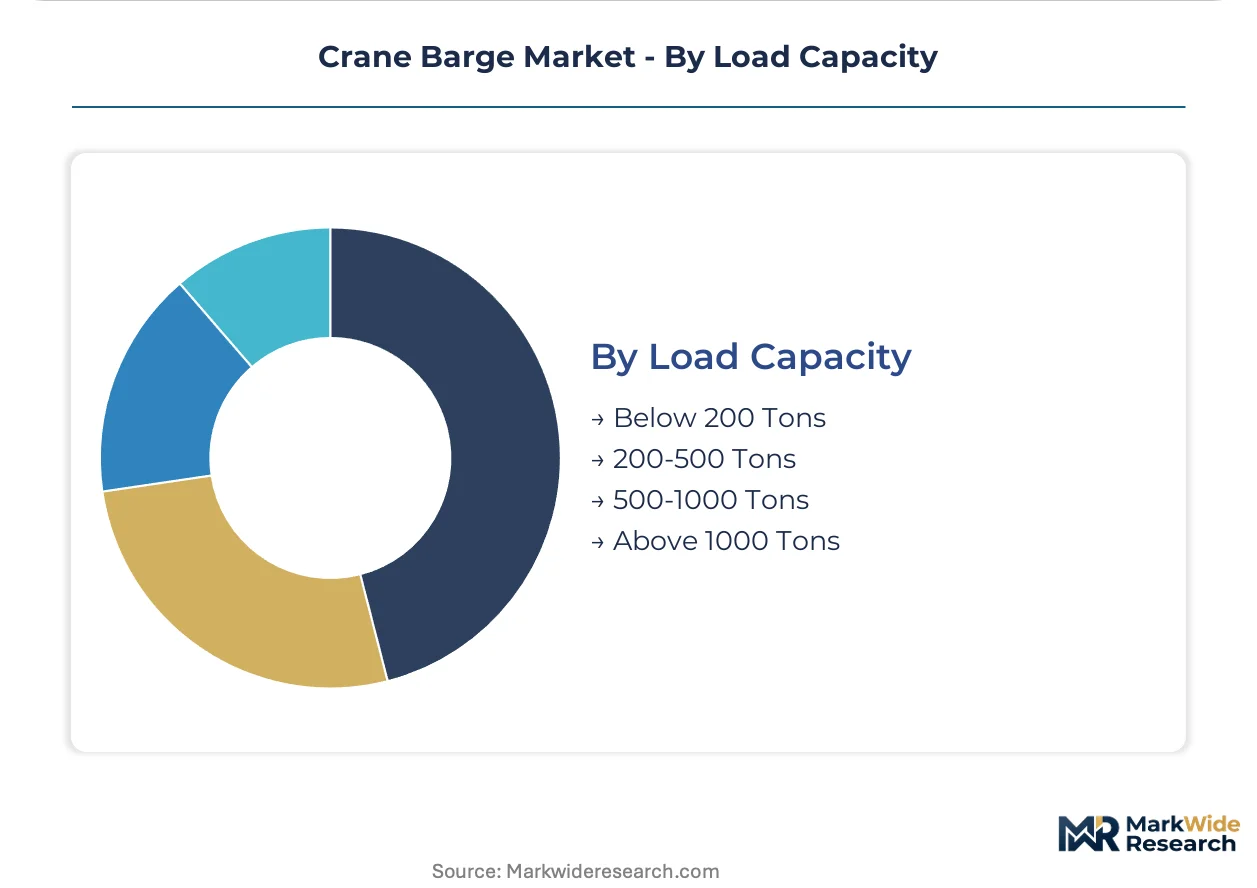
Crane barge segmentation maps directly to charter rate structures and capital deployment cycles. Vessel specifications determine tug requirements, crew certification tiers, and fuel compliance pathways that shape total cost of ownership for marine contractors.
Type:
Propulsion architecture separates buyers by mobility requirements and regulatory exposure.
- Self-Propelled:Integrated diesel-electric or mechanical propulsion eliminates tug dependency and reduces weather downtime during offshore positioning. European offshore wind developers prioritize these units for turbine installation campaigns where schedule certainty outweighs day rate premiums.
- Non-Propelled:Pontoon hulls with external ballast systems maximize deck space for lattice-boom cranes at lowest capital cost. Long-term harbor construction contracts in China and the US Gulf Coast favor these configurations where site mobility is managed by support tugs.
- Modular:Standardized hull platforms from Damen Shipyards Group accept interchangeable crane pedestals and accommodation blocks. Contractors charter customized configurations without full vessel ownership, compressing project mobilization timelines.
- Hybrid:Battery-electric peak shaving and shore-power compatibility address IMO carbon intensity regulations. European-flagged operators specify these systems to avoid compliance penalties under tightening emission regimes.
Volume sits with Non-Propelled units; growth tilts toward Hybrid configurations.
Application:
Project duration and technical complexity dictate whether contractors charter or own.
- Construction:Bridge piling, quay wall installation, and caisson placement require precise load positioning over extended campaigns. Chinese port expansion programs sustain demand for above-500-ton capacity units with dynamic positioning.
- Dredging:Support barges carry booster stations, pipeline sections, and cutter heads for trailing suction hopper operations. The Netherlands and Belgium maintain specialized fleets for North Sea channel maintenance contracts.
- Maintenance:Short-duration harbor repairs and fender replacement utilize smaller self-propelled units with rapid mobilization. Seasonal demand peaks during post-storm infrastructure assessments along the US Atlantic coast.
- Offshore Operations:Platform decommissioning and wind turbine installation demand the highest lift capacities and station-keeping precision. German and Danish developers now charter directly from vessel operators, bypassing traditional marine contractor intermediaries.
Construction commands the largest fleet deployment; offshore operations are expanding most quickly.
End User:
Procurement authority and balance sheet capacity determine charter-versus-own decisions.
- Marine Contractors:Heerema Marine Contractors and Van Oord maintain mixed fleets of self-propelled and non-propelled units, optimizing asset allocation across European offshore wind zones. These firms engineer heavy-lift systems in-house to differentiate charter offerings.
- Shipping Companies:Container terminal operators deploy crane barges for quay crane maintenance and fender repair. Singapore and Rotterdam port authorities specify modular units for multi-site flexibility.
- Government Agencies:Coastal defense and waterway maintenance agencies in the US Army Corps of Engineers and China's Ministry of Transport favor long-term deployment contracts with domestic builders.
- Oil & Gas:Platform decommissioning schedules in the US Gulf Coast and North Sea pull chartered European assets into regions lacking indigenous heavy-lift capacity. Asset retirement obligations accelerate demand for above-1000-ton lift systems.
Marine contractors hold the dominant share; oil and gas decommissioning is gaining share fastest.
Load Capacity:
Hook rating determines vessel structural requirements and classification society scrutiny intensity.
- Below 200 Tons:Harbor maintenance and small-scale construction utilize standard pontoon hulls with pedestal cranes. Chinese coastal municipalities deploy these for routine infrastructure upkeep.
- 200-500 Tons:Mid-range lattice-boom systems handle bridge construction and medium dredging support. European inland waterway contractors favor these for Rhine and Danube infrastructure projects.
- 500-1000 Tons:Offshore wind foundation installation and platform module lifts require enhanced stability systems and dynamic positioning. Lloyd's Register and DNV certification timelines extend 8-14 months for these specifications.
- Above 1000 Tons:Purpose-built hulls with integrated heavy-lift systems command premium day rates for next-generation 15MW-plus turbine installation and complete platform removal. Dutch and German yards now incorporate methanol-ready dual-fuel architecture as standard.
Deployment concentrates in the 200-500 ton band; above-1000 ton units show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of newbuild crane barges while European operators consume premium heavy-lift capacity for offshore wind installation. This production-consumption divide shapes charter rate differentials and fleet deployment patterns across major maritime zones.
China
State-backed port expansion along the Yangtze River Delta and Pearl River Delta sustains domestic orders for modular crane barge configurations. The Ministry of Transport's coastal infrastructure programs mandate standardized hull platforms for rapid deployment. Shanghai and Guangzhou shipyards concentrate heavy-lift vessel construction, with Damen Shipyards Group leveraging local partnerships for hull fabrication.
Germany
North Sea offshore wind developers charter directly from vessel operators for 15MW-plus turbine installation campaigns. The EU Green Deal's sustainable maritime fuels mandate accelerates methanol-ready dual-fuel specifications at Hamburg and Bremen yards. The KBA enforces emission standards that push owners toward hybrid propulsion retrofits.
United States
Aging oil platform decommissioning in the Gulf of Mexico pulls chartered European assets into a market lacking indigenous above-1,000-ton lift capacity. The US Army Corps of Engineers maintains specialized fleets for coastal defense and waterway maintenance. Houston and New Orleans serve as primary logistics hubs for heavy-lift vessel mobilization.
Netherlands
Rotterdam port authorities specify modular crane barges for multi-site terminal maintenance flexibility. Dutch-flagged operators face stringent EU carbon intensity regulations that favor battery-hybrid newbuilds. Heerema Marine Contractors and Van Oord anchor their competitive positions through Rotterdam-based engineering of integrated heavy-lift systems.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries concentrate ultra-large crane barge construction for export markets. The country's national shipbuilding regulator enforces structural standards that align with Lloyd's Register and DNV certification requirements. Busan-Ulsan industrial clusters specialize in dynamic positioning systems for offshore installation vessels.
Crane Barge Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the crane barge value chain. The market structures around three tiers: integrated marine contractors owning mixed fleets, independent vessel operators chartering standardized units, and shipyards delivering modular configurations. Strategic archetypes include in-house heavy-lift system engineers, fleet flexibility optimizers, and standardized platform specialists. Competitive moves concentrate on M&A for vertical capability integration and geographic expansion into offshore wind zones.
Within the integrated marine contractor tier, Heerema Marine Contractors exemplifies the in-house engineering archetype through purpose-built barge development, while Van Oord represents fleet flexibility optimization across European offshore wind markets. Damen Shipyards Group anchors the standardized platform specialist position, leveraging modular hull configurations to compress delivery cycles for charter-customized units.
| Leading Market Players |
|---|
| Damen Shipyards Group |
| Donjon Marine Co., Inc. |
| Heerema Marine Contractors |
| Van Oord |
| Saipem S.p.A. |
| TechnipFMC plc |
| Liebherr Group |
| Konecranes |
| Huisman Equipment |
| Others |
Value Network & Pricing Analysis
High-tensile marine-grade steel plate indices cascade through crane barge construction economics, compressing shipyard margins on fixed-price newbuild contracts while amplifying rate premiums for hybrid-propulsion units that command charter premiums under IMO carbon intensity regimes.
Pricing Analysis
Margin tightening in non-propelled units reflects steel cost volatility and Asian shipyard concentration, while self-propelled and hybrid configurations sustain rate premiums through reduced tug dependency and regulatory compliance value. Pricing stratifies across premium hybrid-electric, standard diesel-electric, and economy non-propelled tiers differentiated by propulsion architecture and dynamic positioning certification. Cost-down pressure on standard configurations accelerates because Chinese yards absorb steel price swings to maintain order books. Marine contractors show highest price sensitivity for harbor construction deployments, whereas offshore wind developers prioritize schedule certainty over day rate premiums.
Supply Chain Analysis
Regional distribution of heavy-lift vessel components follows hub-and-spoke patterns anchored in Shanghai, Busan-Ulsan, and Rotterdam industrial clusters. Hull fabrication concentrates in China and South Korea, with dynamic positioning systems and lattice-boom crane components sourcing from Dutch and German engineering centers. Raw material dependencies rest on high-tensile steel plate, marine-grade aluminum, and fiber-optic sensor packages. Single-source vulnerability in dynamic positioning certification creates bottlenecks, as Lloyd's Register and DNV approval timelines extend capital deployment cycles. Distribution runs through marine contractor fleets, independent vessel operators, and direct developer charters in European offshore wind zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crane barge competition is becoming a vertical-integration race, with players pursuing in-house heavy-lift system engineering to differentiate charter offerings and capture margin pools from installation contractors.
For Market Incumbents: Anchor competitive position through backward integration into heavy-lift system engineering and selective hybrid-propulsion retrofits that preempt IMO compliance penalties. Defend against disintermediation by offshore wind developers through long-term charter partnerships with port infrastructure owners. Prioritize certification investment in above-1000-ton dynamic positioning systems to maintain premium tier access. For New Entrants and Emerging Players: Begin with modular hull platform specialization targeting US Gulf Coast decommissioning demand, where indigenous above-1000-ton capacity scarcity creates white-space opportunity. Focus on methanol-ready dual-fuel specifications for European-flagged operator tenders. Pursue direct charter relationships with German and Danish offshore wind developers as the most penetrable go-to-market channel. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap vessel operators with established Lloyd's Register and DNV certification pipelines in the Netherlands and Germany. Long-term viability hinges on exposure to offshore wind installation demand and regulatory-compliant propulsion architectures. Watch methanol fuel infrastructure deployment timelines as the critical inflection signal for asset valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit | Battery-electric peak shaving addresses IMO carbon intensity penalties while sustaining charter rate premiums. |
| Modular Hull Platform Expansion | Standardized configurations from Damen Shipyards Group compress delivery cycles for charter-customized units. |
| Dynamic Positioning Certification Investment | Lloyd's Register and DNV approvals unlock above-500-ton offshore installation contract access. |
| Methanol-Ready Dual-Fuel Specification | EU Green Deal compliance deadlines force future fuel flexibility into European-flagged newbuild tenders. |
| Direct Developer Charter Relationships | Bypassing marine contractor intermediaries captures margin pools in German and Danish offshore wind zones. |
Research Methodology
Document review covered Lloyd's Register classification records, DNV vessel databases, and IMO regulatory filings, complemented by interviews with marine contractor fleet managers, shipyard procurement directors, offshore wind project developers, and port authority engineering leads. Secondary validation drew from customs trade data, shipbuilding order books, and EU Green Deal implementation reports. Bottom-up vessel deployment tallies triangulated against top-down market value estimates.
Segment-level outputs across the projection horizon reflect modeled interactions between propulsion type, load capacity tier, and end-use application, with offshore operations and above-1000-ton specifications treated as distinct growth vectors. CAGRs derived from charter rate trajectory analysis and fleet replacement cycle timing, incorporating steel price elasticity assumptions and regulatory compliance cost pass-through coefficients.
Underlying measurement precision varies by segment; self-propelled and hybrid configurations carry tighter precision than non-propelled harbor units due to more transparent charter market data. Forecasts reflect assumptions on IMO enforcement timelines and offshore wind turbine scaling trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market