
 Submersible Dredge Pump Market | 2026-2036
Submersible Dredge Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Submersible Dredge Pump Market Insights
A shift from single-source procurement to multi-source supplier networks is pivoting how marine contractors secure submersible dredge pump fleets. Grundfos Holding A/S leverages its integrated manufacturing footprint across Denmark and China to shorten lead times for large-bore units. The Weir Group anchors its position through aftermarket service density in Australasian mining corridors. Sulzer Ltd. competes on hydraulic design specialization for high-abrasion slurry environments.
A submersible dredge pump is a sealed-motor centrifugal pump designed to operate fully immersed in fluid, typically handling solids concentrations up to 60% by weight with discharge heads exceeding 100 meters; its primary purpose is hydraulic transport of sediment, slurry, or tailings in infrastructure and resource extraction settings. Centrifugal designs dominate harbor maintenance fleets due to mature servicing infrastructure and parts interchangeability, while vortex configurations are gaining share in mining operations where fibrous or irregular debris would clog conventional impellers. Electric motor technology leads the installed base, though diesel engine variants retain priority in remote Indonesian and West African sites lacking grid connectivity.
The EPA enforces National Pollutant Discharge Elimination System permits that limit turbidity from dredging operations, compelling contractors to specify pumps with precision flow control and reduced sediment resuspension. China's MEE implements GB standards for water body conservation that restrict allowable suspended solids in discharge streams, creating compliance-driven replacement cycles across Pearl River Delta fleets. The EU F-Gas Regulation and REACH chemical restrictions indirectly shape seal and lubricant specifications for equipment sold into European harbors. Stakeholders must monitor how tightening particulate discharge rules in multiple jurisdictions will redefine the performance threshold between standard and premium pump tiers.
Market Dynamics
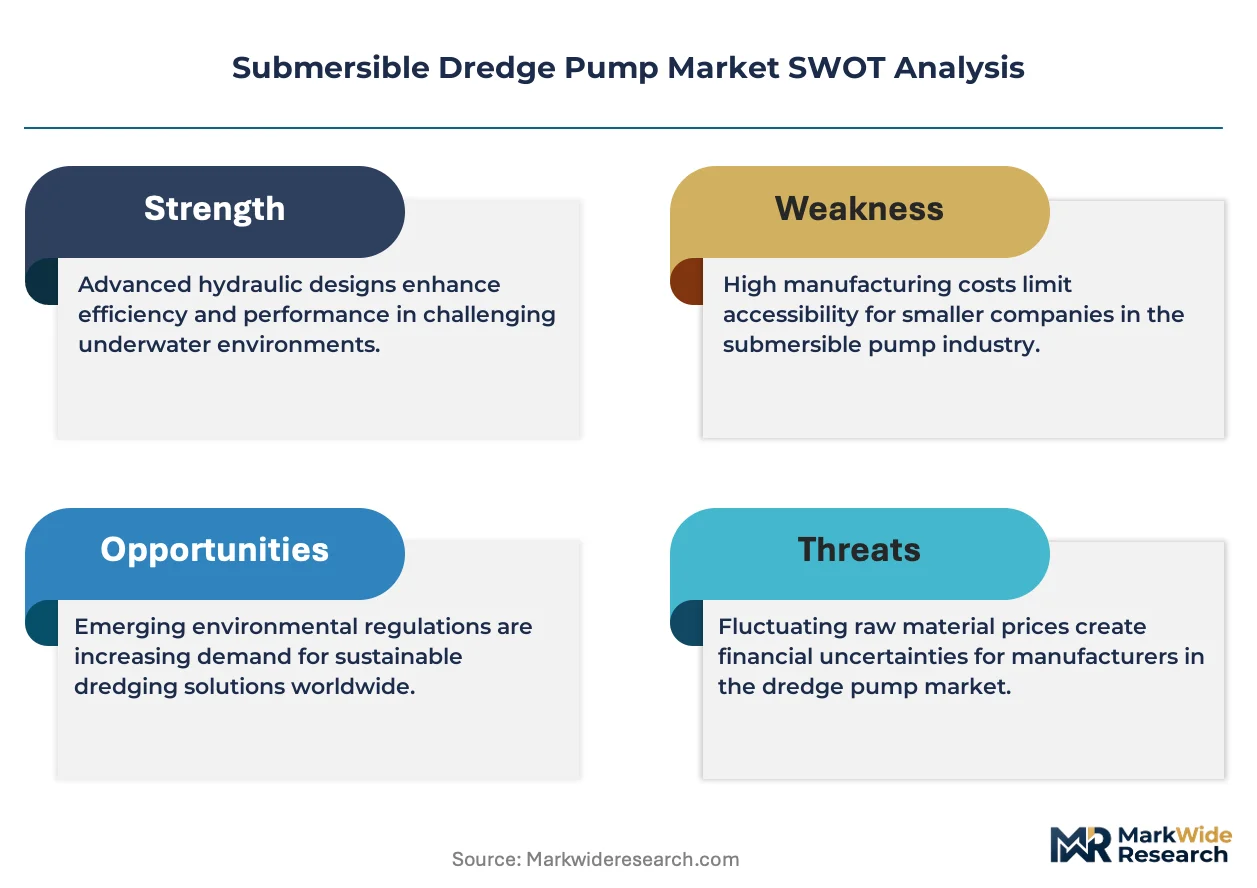
Stringent EPA discharge permits and China's MEE enforcement are compressing replacement cycles, forcing contractors to retire legacy pumps ahead of schedule and reallocate capital toward precision flow-control systems.
Growth Catalysts
- Alluvial Mining Expansion:Australian and Indonesian operators are deploying larger-bore submersible fleets to access deeper placer deposits. Contractors in the Mekong Delta corridor are modernizing sediment management infrastructure.
- GB Standards Enforcement:China's MEE water quality mandates are triggering fleet turnover across Pearl River Delta harbor maintenance operations. Discharge stream suspended solids limits now exceed legacy pump capabilities.
- Grid Electrification:Southeast Asian port authorities are prioritizing electric motor variants over diesel engine units. Reduced fuel logistics burden and lower particulate output align with tightening harbor air quality protocols.
Market Restraints
- High-Abrasion Component Costs:Tungsten carbide impeller inserts and ceramic-lined volutes face volatile raw material pricing. Mining operators absorb 15-25% spare parts cost premiums versus standard construction-grade pumps.
- Specialized Servicing Concentration:Factory-authorized rebuild capabilities cluster in Denmark, China, and Australia. Remote Indonesian and West African sites experience 6-10 week turnaround delays for critical hydraulic component restoration.
- Seal Technology Limitations:Double mechanical seals rated for 60% solids concentration remain proprietary to three component suppliers. Standard lip seal configurations fail prematurely in fibrous slurry environments common to palm oil mill effluent handling.
Strategic Opportunities
- Deep-Pit Extraction Applications:Copper and gold operations in Chile and Peru are specifying submersible units for tailings dam reclamation. Pump depths exceeding 150 meters exceed traditional suction dredge economics.
- EU F-Gas Compliance Pathway:European harbor fleets must transition seal and lubricant formulations by 2030. Biodegradable synthetic lubricant compatibility creates specification differentiation for proactive manufacturers.
- Condition Monitoring Convergence:Vibration analytics and thermal imaging are integrating with pump control systems. Predictive maintenance contracts are displacing time-based service agreements in Australasian mining corridors.
Industry Challenges
- Hydraulic Specialist Scarcity:Computational fluid dynamics expertise for high-solids impeller design concentrates among aging engineering cohorts. Universities in Denmark and Germany produce fewer graduates specializing in slurry pump hydraulics.
- MEE Certification Timelines:Chinese type-approval testing for imported pump systems extends 14-18 months. Domestic manufacturers benefit from accelerated GB standard compliance verification pathways.
- Legacy Control System Integration:Variable frequency drives with precision flow modulation require SCADA architecture upgrades. Harbor authorities in Indonesia and Vietnam face capital constraints modernizing 1990s-era pump station automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submersible Dredge Pump Market |
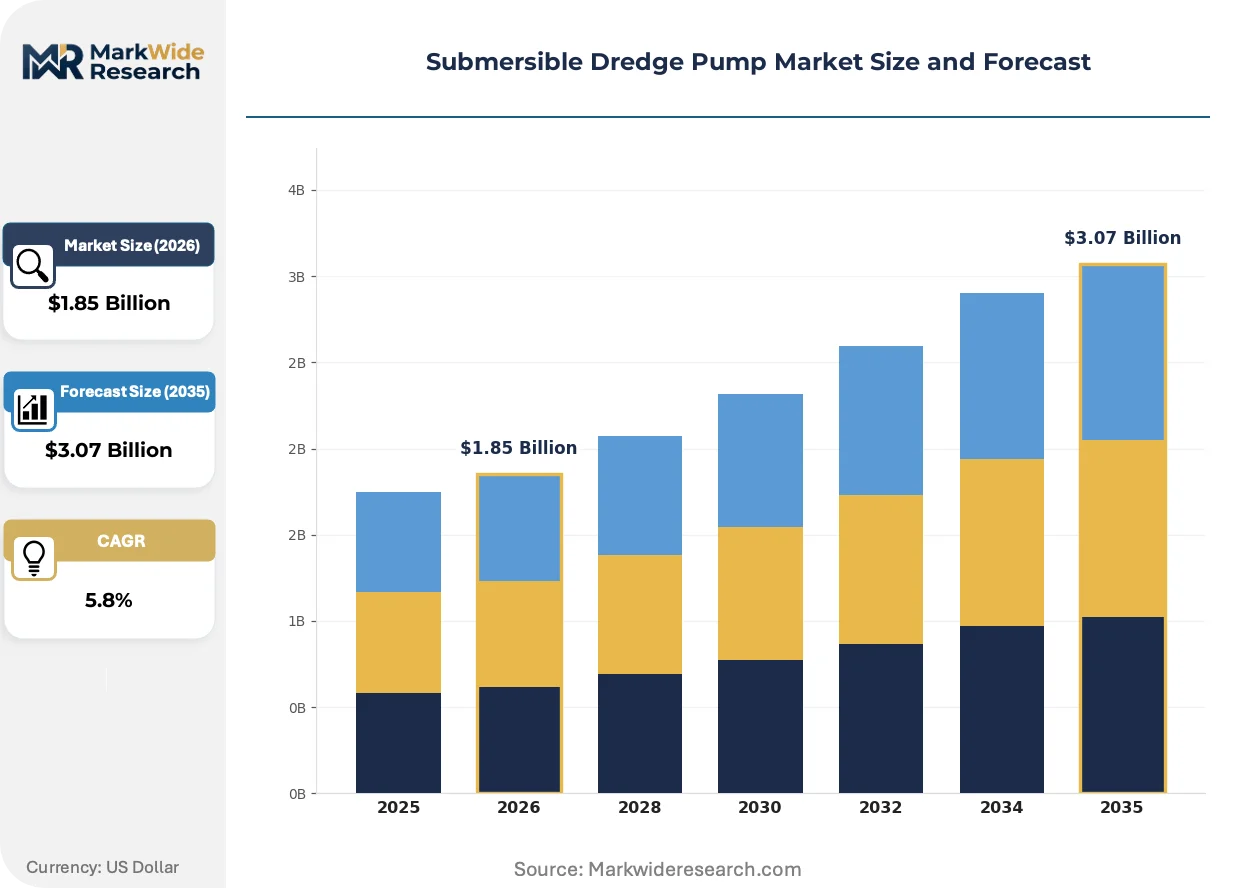
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Axial Flow, Mixed Flow, Vortex Technology: Hydraulic, Electric Motor, Diesel Engine, Solar Powered Application: Harbor Maintenance, River Dredging, Mining Operations, Land Reclamation End User: Marine Contractors, Mining Companies, Construction Firms, Environmental Agencies |
| Companies Covered | Grundfos Holding A/S, The Weir Group, Sulzer Ltd., Xylem Inc., Flowserve Corporation, KSB SE & Co., Atlas Copco AB, EBARA Corporation, Damen Dredging Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submersible Dredge Pump Market Trends and Innovations
Permanent magnet synchronous motor technology is compressing energy consumption benchmarks while digital twin simulation is shortening prototype development cycles for extreme abrasion environments.
Permanent magnet synchronous motor systems are replacing induction motor configurations in harbor maintenance fleets. Port authorities in Rotterdam and Singapore specify IE5 efficiency ratings for new pump procurements. This technology is electrifying demand for integrated motor-pump packages that eliminate surface power station infrastructure.
REACH chemical restrictions and the EU F-Gas Regulation are mandating biodegradable lubricant formulations and fluorinated gas-free cooling systems. Seal manufacturers are reformulating elastomer compounds to maintain abrasion resistance without restricted plasticizers. European harbor operators now require full material disclosure documentation for pump components handling sensitive marine ecosystems.
Multi-source supplier networks are displacing single-source procurement frameworks among marine contractors. Indonesian tin mining operators now qualify three pump vendors minimum per fleet category. This pattern concentrates most visibly in the Mekong Delta corridor, where sediment management contractors negotiate shorter lead times through distributed manufacturing footprints.
Submersible Dredge Pump Market Segmentation
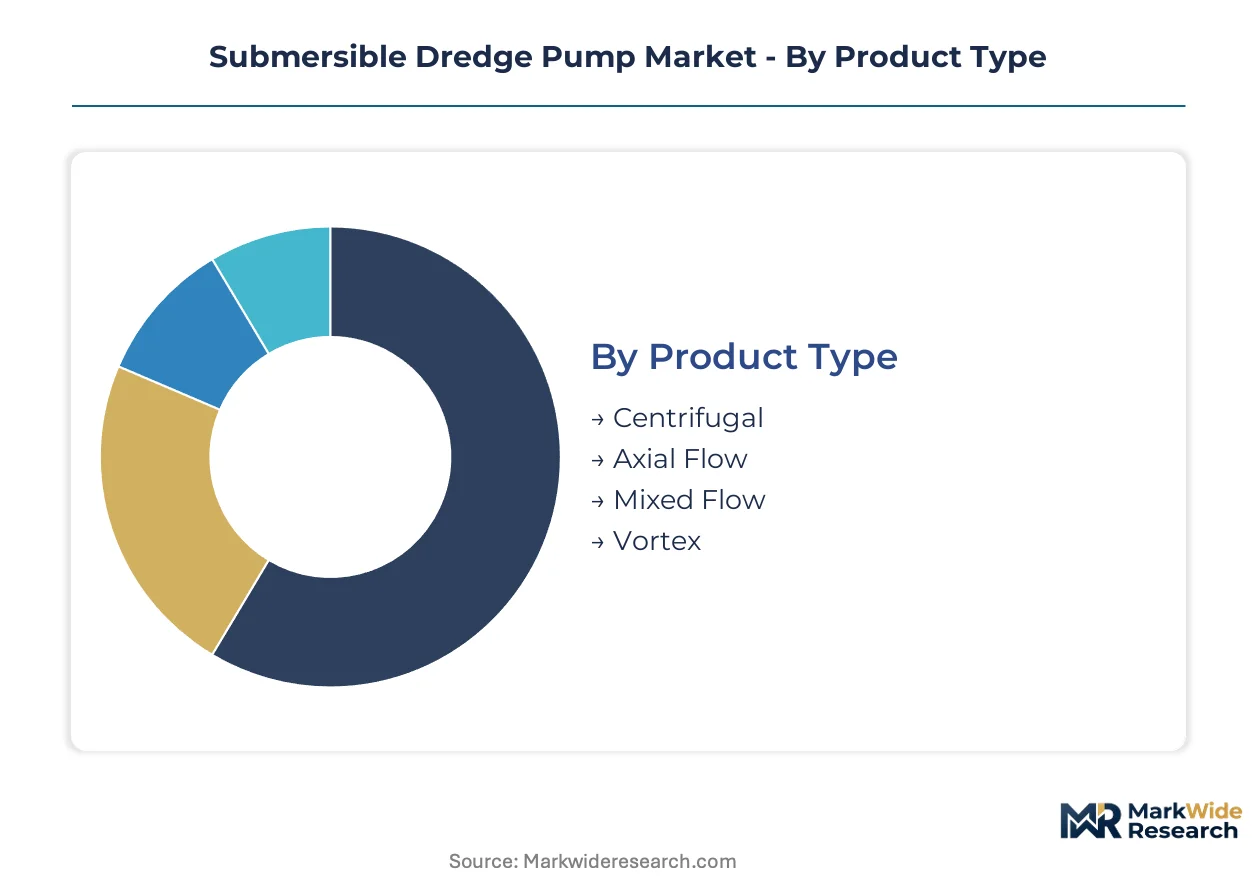
Submersible dredge pump procurement varies sharply by operational intensity and infrastructure requirements. Capital allocation patterns differ between harbor authorities seeking standardized replacement fleets and mining operators demanding specialized abrasion-resistant configurations.
Product Type:
Capital intensity peaks with vortex and mixed-flow designs requiring precision casting and proprietary impeller geometries, while centrifugal units leverage mature supply chains that compress upfront investment.
- Centrifugal:Sealed-motor designs with radial impellers dominate harbor maintenance fleets due to parts interchangeability and established servicing infrastructure. Demand concentrates in Rotterdam and Singapore port authorities modernizing aging fleets under tightening discharge permit requirements.
- Vortex:Recessed impeller configurations handle fibrous debris and irregular solids without clogging, commanding 40-60% capital premiums over centrifugal equivalents. Indonesian tin mining operators and Mekong Delta sediment contractors specify these for palm oil mill effluent and alluvial extraction where conventional impellers fail.
- Axial Flow:Propeller-style designs optimize low-head, high-volume applications in riverine systems.
- Mixed Flow:Hybrid geometries balance pressure and flow characteristics for tailings dam reclamation projects.
Most installed capacity flows through centrifugal designs. Expansion is steepest in vortex configurations.
Technology:
Grid-connected electric motor systems concentrate capital in surface infrastructure, while diesel and solar variants shift investment toward mobile power generation and storage subsystems.
- Electric Motor:Permanent magnet synchronous configurations achieve IE5 efficiency ratings and eliminate surface power stations through integrated submersible packages. Rotterdam and Singapore port authorities mandate these for new procurements, while Southeast Asian harbor operators prioritize them to reduce fuel logistics burdens.
- Diesel Engine:Self-contained power units retain priority in remote Indonesian and West African sites lacking grid connectivity, though particulate output conflicts with tightening harbor air quality protocols. Higher operating costs and maintenance complexity constrain adoption outside off-grid applications.
- Hydraulic:Surface power pack configurations suit deep-pit extraction where electric cable management proves impractical.
- Solar Powered:Photovoltaic-battery hybrid systems emerge for low-duty-cycle environmental monitoring and small-scale land reclamation.
Electric motor systems carry the largest cumulative installed base. Diesel engine deployments are expanding most quickly in frontier mining corridors.
Application:
Revenue concentration aligns with project scale and regulatory scrutiny, with mining operations and harbor maintenance commanding multi-unit fleet purchases versus episodic riverine contracting.
- Mining Operations:Deep-pit extraction and tailings dam reclamation require pump depths exceeding 150 meters, rendering suction dredge economics unviable. Copper and gold operations in Chile and Peru specify submersible units for abrasive slurry transport at concentrations up to 60% solids by weight.
- Harbor Maintenance:Continuous sediment management in Rotterdam, Singapore, and Pearl River Delta ports drives predictable replacement cycles. EPA National Pollutant Discharge Elimination System permits and China's GB standards compel precision flow-control specifications that retire legacy pumps ahead of schedule.
- River Dredging:Episodic flood mitigation and navigation channel maintenance characterizes Mekong Delta and Bangladesh corridor demand.
- Land Reclamation:Fill material transport for coastal development projects in Vietnam and Indonesia drives periodic large-bore unit procurement.
Harbor maintenance absorbs the greatest unit volume. Mining operations show the steepest specification escalation toward abrasion-resistant premium tiers.
End User:
Procurement sophistication varies by technical capability, with mining companies and marine contractors driving specification complexity while environmental agencies emphasize compliance documentation.
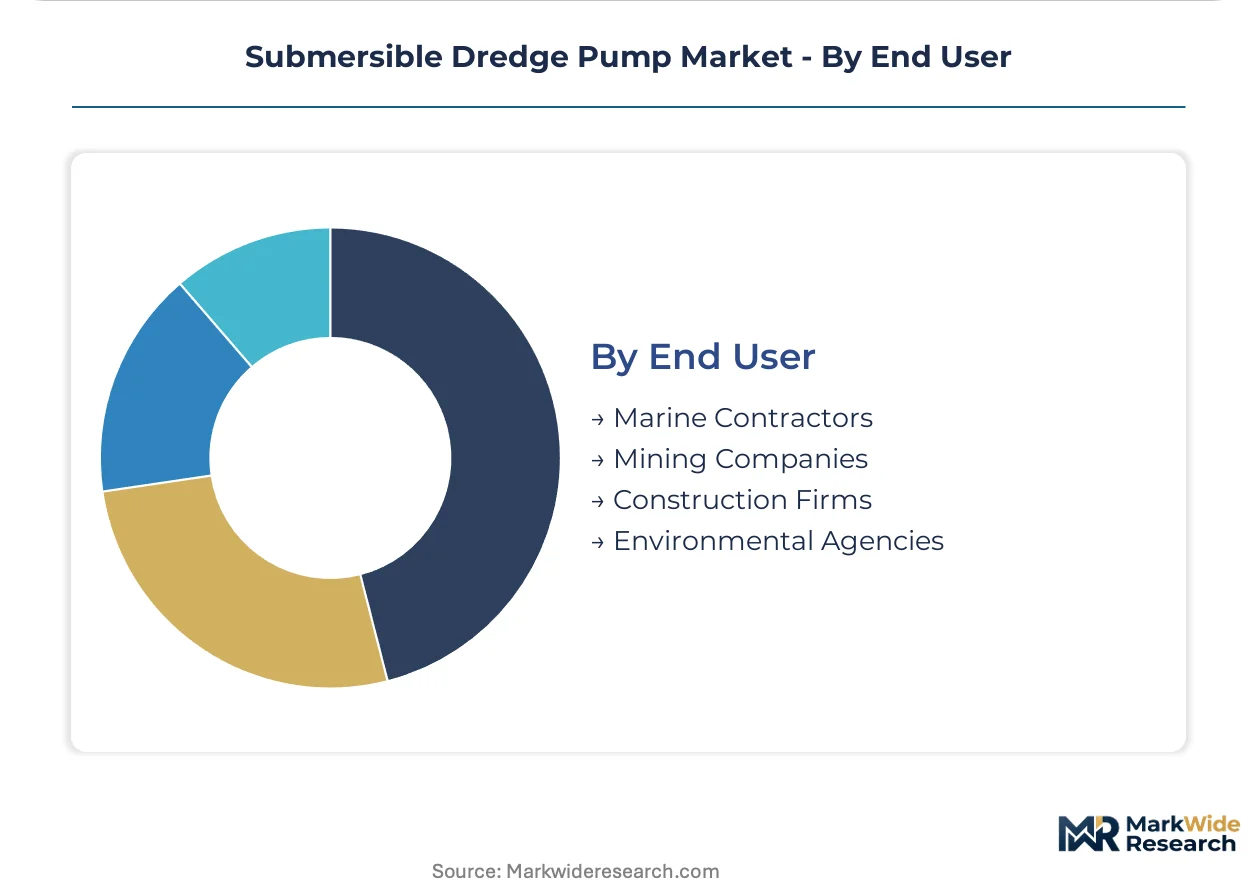
- Mining Companies:Australian and Indonesian operators deploy larger-bore fleets for alluvial and deep-pit extraction, absorbing 15-25% spare parts cost premiums for tungsten carbide impeller inserts and ceramic-lined volutes. Multi-source supplier qualification mandates now require three pump vendors minimum per fleet category.
- Marine Contractors:Sediment management specialists in the Mekong Delta corridor negotiate distributed manufacturing footprints to compress lead times. Condition monitoring convergence through vibration analytics and thermal imaging is displacing time-based service agreements.
- Construction Firms:Land reclamation project developers specify units for finite-duration deployments with secondary market resale considerations.
- Environmental Agencies:Regulatory compliance-driven procurement emphasizes discharge monitoring integration and material disclosure documentation for sensitive marine ecosystems.
Mining companies represent the largest revenue concentration. Marine contractors are gaining procurement sophistication fastest through predictive maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta anchors submersible dredge pump procurement intensity, with Chinese harbor authorities modernizing sediment management fleets under tightening discharge mandates. Australian mining corridors and Indonesian tin operations drive parallel demand for abrasion-resistant deep-pit extraction systems. Rotterdam and Singapore port authorities set efficiency benchmarks that reshape supplier qualification criteria across Southeast Asian procurement networks.
China
MEE enforcement of GB water quality standards is compressing replacement cycles across Pearl River Delta harbor maintenance operations. Discharge stream suspended solids limits now exceed legacy pump capabilities, forcing contractors toward precision flow-control specifications. Shanghai and Guangzhou port authorities are retiring induction-motor fleets ahead of schedule to comply with dual carbon goals.
United States
EPA National Pollutant Discharge Elimination System permits are limiting turbidity from dredging operations in Gulf Coast and Chesapeake Bay corridors. Contractors specify pumps with reduced sediment resuspension to maintain compliance. Houston-Galveston and Norfolk-Newport News harbor clusters drive replacement demand as infrastructure renewal cycles converge with regulatory deadlines.
Australia
Deep-pit extraction expansion in Western Australian gold and Queensland coal corridors requires pump depths exceeding 150 meters. Mining operators absorb spare parts cost premiums for tungsten carbide impeller inserts. Perth and Brisbane serve as aftermarket service hubs, though remote Pilbara sites experience extended turnaround delays for hydraulic component restoration.
Indonesia
Alluvial tin mining operators in the Bangka-Belitung Islands deploy larger-bore submersible fleets to access deeper placer deposits. Grid electrification gaps in remote sites sustain diesel engine variant priority despite tightening harbor air quality protocols. Jakarta port authority procurement patterns influence qualification standards across the archipelago's sediment management contractors.
Netherlands
Rotterdam harbor maintenance fleets mandate IE5 efficiency ratings for new pump procurements under EU F-Gas Regulation compliance pathways. REACH chemical restrictions shape seal and lubricant specifications for equipment handling sensitive North Sea ecosystems. Dutch sediment management contractors are negotiating distributed manufacturing footprints to compress lead times for European harbor modernization programs.
Submersible Dredge Pump Market Competitive Landscape
Global majors compete with regional champions across manufacturing footprint density and aftermarket service reach. The vendor base clusters around integrated motor-pump package specialists, hydraulic design specialists, and diversified industrial conglomerates with pump divisions. Three archetypes dominate: European engineering houses with captive foundry capacity, Asian fabricators leveraging cost-optimized supply chains, and mining-focused specialists with deep abrasion-application expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing distributed production nodes to compress lead times for large-bore units.
Among Danish engineering houses, Grundfos Holding A/S exemplifies the integrated manufacturing archetype through its Denmark-China production footprint. The Weir Group anchors the mining-specialist tier with aftermarket service density concentrated in Australasian corridors. Sulzer Ltd. occupies a position within the hydraulic design specialization tier, with expertise concentrated in high-abrasion slurry environments. Xylem Inc. and Flowserve Corporation represent diversified industrial conglomerates with pump divisions that compete on portfolio breadth and global distribution reach.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| The Weir Group |
| Sulzer Ltd. |
| Xylem Inc. |
| Flowserve Corporation |
| KSB SE & Co. |
| Atlas Copco AB |
| EBARA Corporation |
| Damen Dredging Equipment |
| Others |
Pricing and Supply Chain Analysis
Captive foundry capacity in Denmark and China anchors pricing power for integrated motor-pump packages, while outsourced casting networks in Southeast Asia compress margins for standard centrifugal units. Tungsten carbide sourcing concentration and ceramic liner fabrication bottlenecks create tiered cost structures that mining operators absorb through aftermarket service premiums.
Pricing Analysis
Input-cost pass-through from volatile tungsten carbide and rare earth magnet pricing stratifies procurement tiers across premium abrasion-resistant and standard harbor maintenance specifications. Three-tier pricing structure across IE5 permanent magnet synchronous, induction motor electric, and diesel engine configurations reflects efficiency certification premiums and fuel logistics burden differentials. Cost compression in mid-tier induction fleets intensifies because Chinese domestic manufacturers accelerate GB standard compliance verification. Mining companies absorb the highest absolute cost premiums for ceramic-lined volutes, while municipal harbor authorities demonstrate greatest price sensitivity to upfront capital outlays.
Supply Chain Analysis
High-grade ductile iron casting rests on Danish and German specialty foundries, while rare earth magnet supply feeds from Chinese processing refineries and Southeast Asian assembly nodes. Tungsten carbide impeller inserts draw from Swedish powder metallurgy specialists, ceramic liner formulations from Japanese technical ceramics producers, and precision bearings from German and Japanese manufacturers. Single-source vulnerability concentrates in double mechanical seal assemblies rated for 60% solids concentration, where proprietary elastomer compounds remain tethered to three component suppliers. Distribution runs through factory-authorized service hubs concentrated in Perth, Brisbane, and Rotterdam, with remote Indonesian and West African sites experiencing extended turnaround cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EPA National Pollutant Discharge Elimination System permit renewals and China's MEE GB standard enforcement compress replacement cycles into predictable demand windows.
For Market Incumbents: Deepen aftermarket service density in Australasian mining corridors to lock in spare parts revenue streams against emerging hydraulic design specialists. Anchor captive foundry capacity for large-bore vortex units to defend margin position from Chinese fabricators accelerating MEE certification timelines. Prioritize biodegradable lubricant compatibility investments ahead of EU F-Gas Regulation deadlines. For New Entrants and Emerging Players: Capture white-space in solar-powered hybrid configurations for low-duty-cycle environmental monitoring applications where incumbent portfolios remain thin. Target Mekong Delta sediment management contractors through distributed manufacturing footprints that compress lead times against Danish engineering houses. Lead with predictive maintenance platform integration as primary go-to-market differentiation. For Investors and Strategic Acquirers: Roll-up economics work for hydraulic design specialists with deep abrasion-application expertise because computational fluid dynamics talent concentrates among aging engineering cohorts with limited university pipeline replacement. Five-to-ten year viability favors targets with proven high-solids impeller geometries and existing factory-authorized rebuild certifications. Watch MEE type-approval timeline differentials between imported and domestic Chinese manufacturers as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Distributed Manufacturing Nodes | Compresses lead times for large-bore units serving Indonesian tin belt and Mekong Delta contractors. |
| Backward Integration into Rare Earth Magnet Supply | Secures permanent magnet synchronous motor cost position against Chinese processing concentration. |
| Biodegradable Lubricant Formulation Transition | Aligns seal and lubricant specifications with EU F-Gas Regulation and REACH chemical restrictions. |
| Predictive Maintenance Platform Development | Displaces time-based service agreements through vibration analytics and thermal imaging integration. |
| Joint Venture for Localized MEE Certification | Accelerates GB standard compliance verification against 14-18 month imported pump timelines. |
Research Methodology
Bottom-up mining and harbor maintenance modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with maintenance directors at Australian deep-pit operations, procurement leads at Rotterdam and Singapore port authorities, aftermarket service heads in Perth and Brisbane, and plant engineers at Indonesian tin mining sites combined with secondary validation from customs trade data, EPA discharge permit filings, MEE GB standard documentation, and SEC 10-K filings from diversified industrial conglomerates. Triangulation across these sources calibrated unit deployment assumptions against regulatory compliance-driven replacement cycle timing.
Historical trendline analysis of fleet modernization patterns across Pearl River Delta harbor authorities and Western Australian gold corridors established baseline replacement velocity parameters. Segmentation modeling spanned product type, motor technology, application intensity, and end-user procurement sophistication dimensions across the projection horizon. CAGRs derived from regression against installed base age profiles and regulatory deadline clustering. Industry-specific forecast inputs included MEE enforcement trajectory assumptions and permanent magnet synchronous motor adoption curves in grid-electrifying Southeast Asian ports.
Raw material price volatility, regulatory timeline delays, and grid electrification pace variations are the dominant revision risks. Forecasts reflect documented assumptions regarding GB standard implementation consistency and EPA permit renewal scheduling. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Offshore Pipeline Market