
 Crawler Drill Rig Market | 2026-2036
Crawler Drill Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Crawler Drill Rig Market Analytics
High-spec automation tiers is collapsing the addressable market for manual and semi-automated alternatives across hard-rock applications. Atlas Copco AB leverages its autonomous drill rig architecture to sustain premium positioning in underground mining contracts. Sandvik AB anchors its presence through integrated drill-and-blast systems that control the full excavation workflow. Komatsu Ltd. differentiates via connected fleet management platforms that extend equipment utilization rates across dispersed quarry operations.
A crawler drill rig is a self-propelled drilling machine mounted on continuous track undercarriage, typically rated by mast pullback force, rotary torque output, and hole diameter capacity ranging from 50 mm to 400 mm. These units perform blasthole drilling, exploration coring, and foundation anchoring in terrain where wheeled mobility proves inadequate. Hydraulic crawler configurations dominate the installed base due to superior power density and precision control in variable rock hardness. Mining applications generate the deepest margin pools, while geotechnical contracting represents the fastest-growing demand segment as urban tunneling and slope stabilization projects multiply. Electric crawler variants remain nascent but attract disproportionate R&D allocation as emission restrictions tighten at underground mine sites.
EPA Tier 4 Final and EU Stage V standards are forcing engine redesigns and after-treatment retrofits, directly elevating development costs and narrowing the supplier base to capital-intensive manufacturers. ISO 18758 and national mining safety codes in Australia and Canada mandate operator protection structures and emergency shutdown systems that shape product architecture decisions. China's MIIT enforces GB stage emission limits that parallel European benchmarks, creating dual-compliance burdens for exporters. Stakeholders must monitor how battery-electric powertrain maturation intersects with underground ventilation cost economics to determine optimal fleet transition timing.
Market Dynamics
Automation architecture is collapsing the viable product mix across hard-rock mining as fleet operators in Australia and Chile accelerate replacement cycles toward fully autonomous drilling platforms. This technological compression is reshaping supplier economics and narrowing the competitive field to capital-intensive manufacturers capable of integrated drill-and-blast system development.
Growth Catalysts
- EU Stage V engine regulations:Emission mandates are compressing demand toward electric and hybrid powertrains, accelerating R&D allocation into battery-electric architectures for underground ventilation-constrained environments.
- China's western provinces:State-backed infrastructure and mineral extraction projects in Xinjiang and Qinghai are concentrating heavy-duty crawler-mounted unit procurement through state-owned enterprise channels.
- Autonomous drilling platforms:Underground mining contractors are specifying unmanned operation capabilities as baseline requirements, elevating premium-tier system penetration in hard-rock applications.
Market Restraints
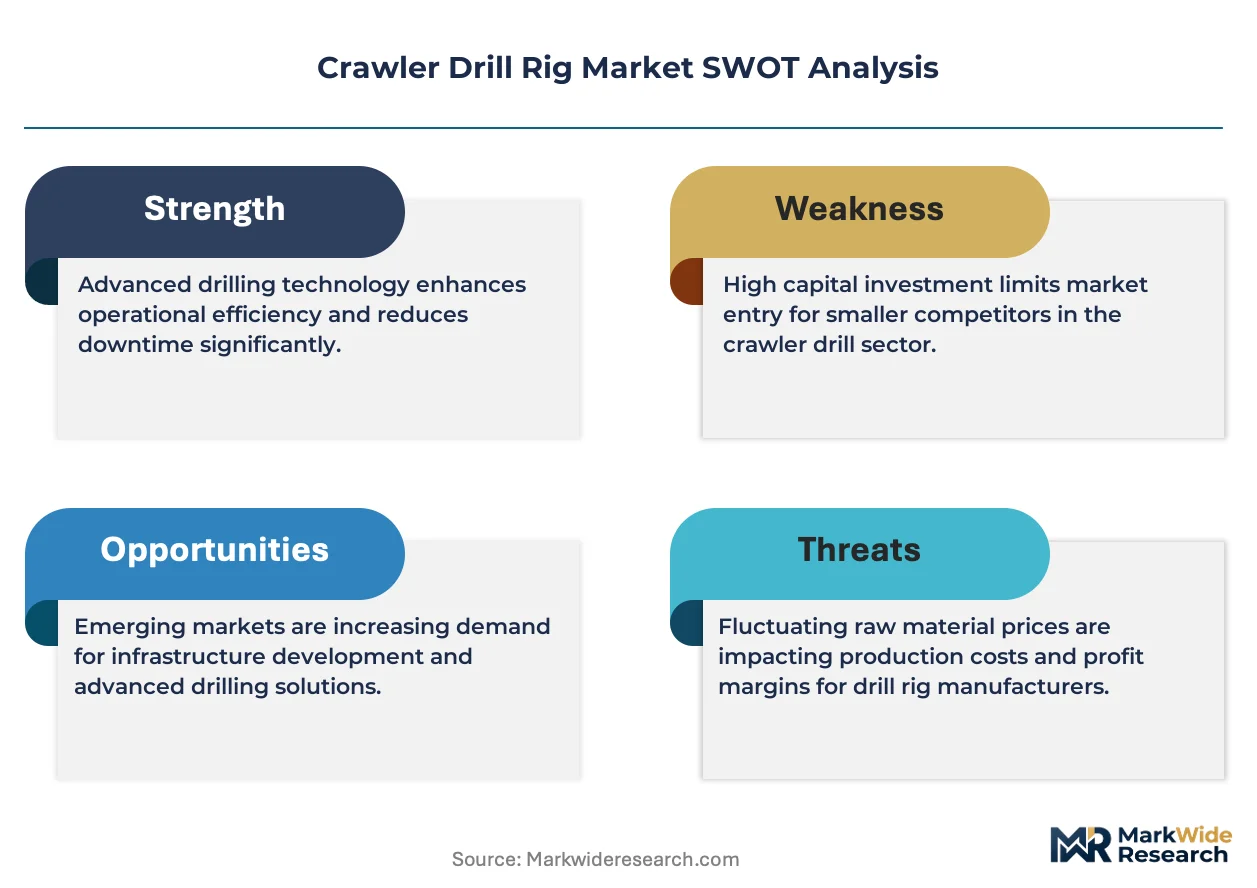
- After-treatment retrofits:EPA Tier 4 Final compliance is elevating engine development costs and compressing margins for mid-tier suppliers lacking captive diesel-electric integration capabilities.
- Supply concentration:High-torque hydraulic component manufacturing clusters in Germany and Japan create geographic vulnerability for non-integrated rig assemblers.
- Technical limitation:Battery energy density constraints restrict electric crawler variants to short-radius underground operations, excluding open-pit applications from current electrification pathways.
Strategic Opportunities
- Geotechnical contracting:Urban tunneling and slope stabilization projects are multiplying fastest in India's Himalayan corridor and Peru's Andean infrastructure belt.
- Dual carbon goals:China's MIIT enforcement of GB stage emission limits creates regulatory tailwind for domestic electric rig manufacturers serving Belt and Road export markets.
- 5G fleet connectivity:Convergence of telematics and real-time blast optimization software is enabling outcome-based drilling contracts in dispersed quarry operations.
Industry Challenges
- Automation engineering talent:Shortage of embedded systems specialists capable of integrating machine vision with hydraulic control architectures is extending product development timelines.
- ISO 18758 certification:Operator protection structure validation requirements in Australia and Canada are creating multi-year compliance pathways for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crawler Drill Rig Market |
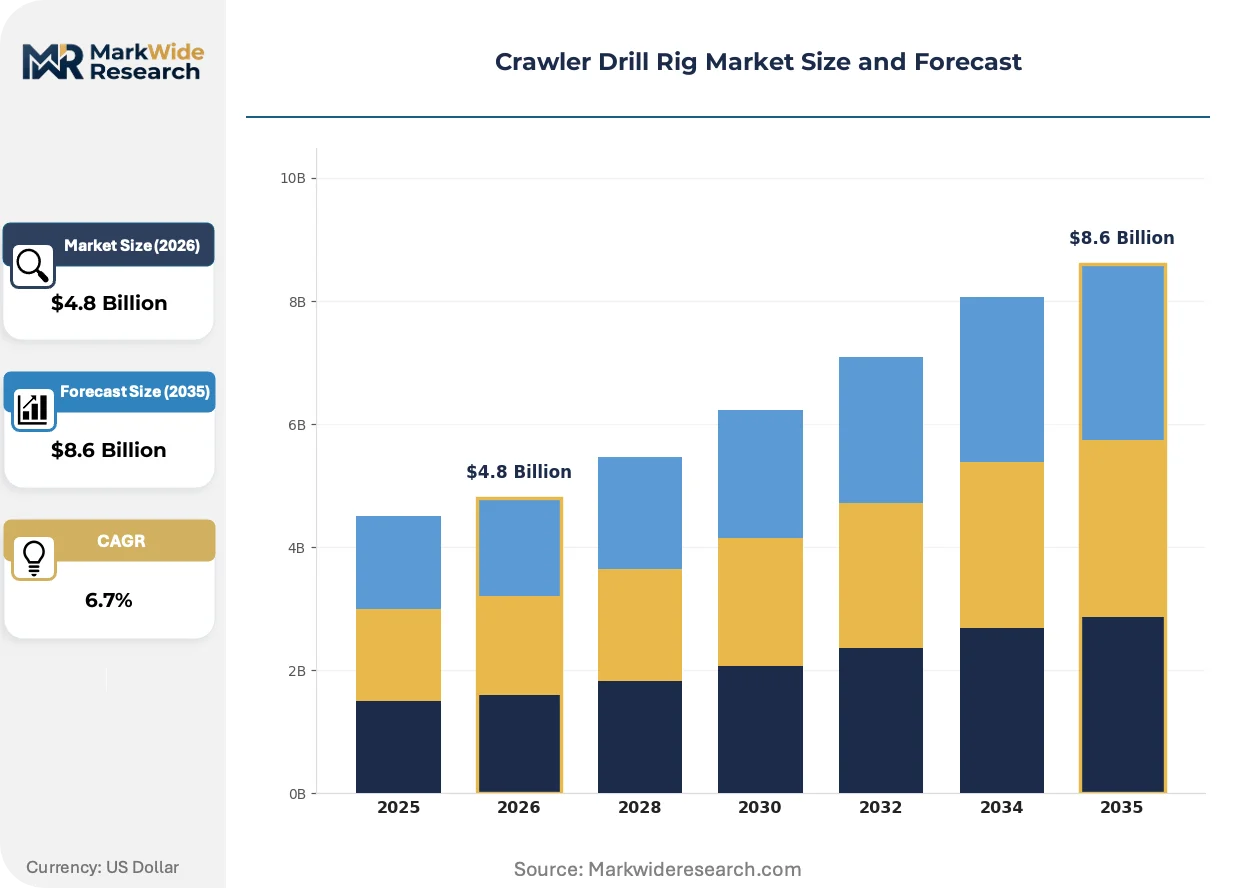
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Crawler, Pneumatic Crawler, Electric Crawler, Hybrid Crawler Application: Mining, Construction, Water Well Drilling, Geotechnical End User: Contractors, Mining Companies, Utilities, Government Size: Small, Medium, Large, Extra Large |
| Companies Covered | Atlas Copco AB, Furukawa Rock Drill Co. Ltd., Epiroc AB, Liebherr Group, Komatsu Ltd., Sandvik AB, Xuzhou Construction Machinery Group, Boart Longyear Ltd., Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crawler Drill Rig Market Evolving Landscape
Electrification and digital integration are compressing the technology lifecycle across crawler drill rig architectures, forcing simultaneous investment in powertrain transformation and autonomous control systems.
Downhole sensor arrays are miniaturizing. These fiber-optic measurement tools now deliver real-time rock hardness and borehole deviation data directly to rig control systems. Underground mining contractors in Chile are specifying these as standard equipment on new fleet orders. The technology is miniaturizing the addressable market for manual core logging services and compressing geological interpretation timelines.
EPA Tier 4 Final and EU Stage V standards are forcing synchronous engine redesigns across diesel-hydraulic product lines. After-treatment system packaging is consuming previously available frame space, compelling modular architecture reconfigurations. Suppliers serving North American and European underground markets are responding with parallel electric powertrain development tracks to circumvent ongoing emission escalation.
Service unbundling is fragmenting traditional procurement relationships. Mining contractors in Australia's Pilbara region are separating drilling equipment acquisition from consumables supply and maintenance execution. Independent service providers are capturing aftermarket revenue pools that OEMs previously controlled through captive parts distribution networks.
Crawler Drill Rig Market Segmentation
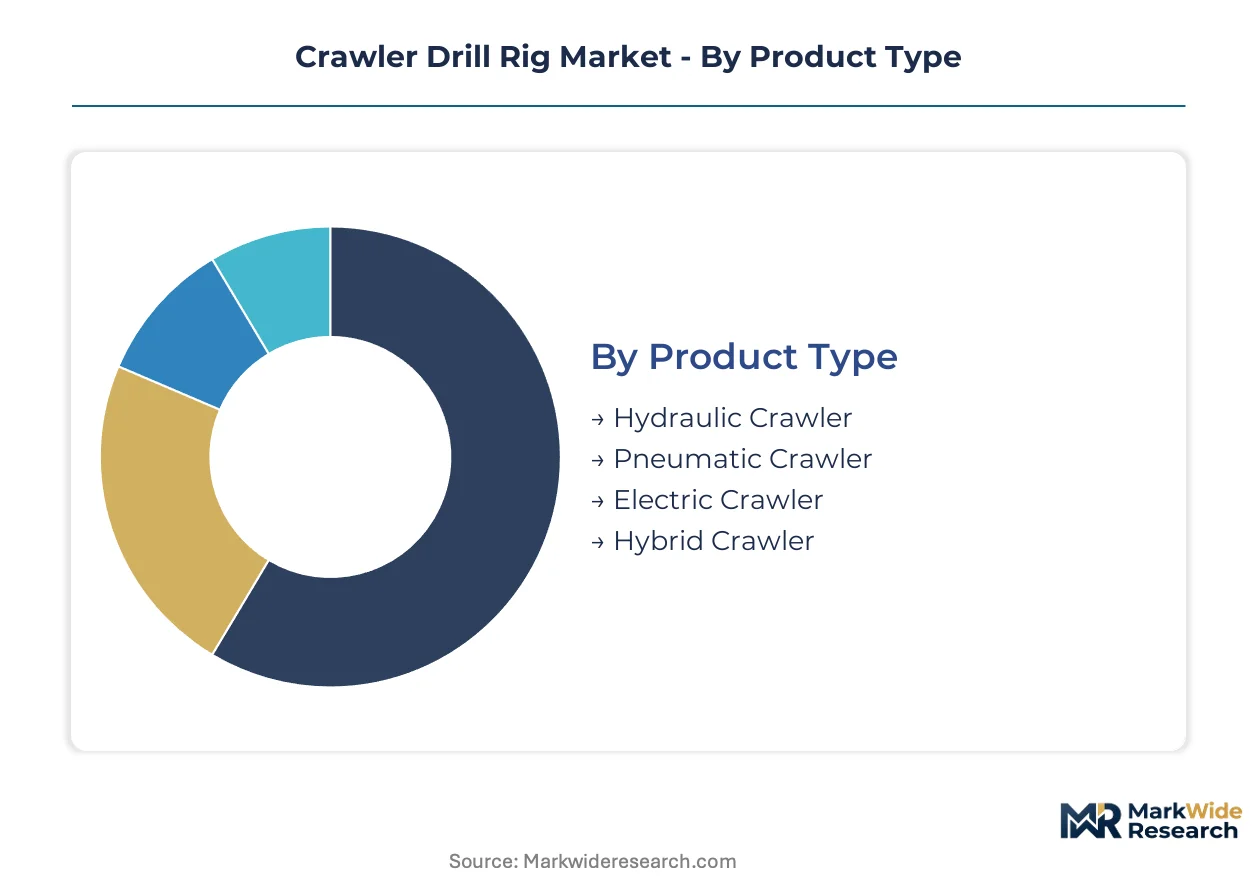
Crawler drill rig procurement patterns diverge sharply across powertrain technologies and end-use verticals. Mining automation requirements and emission compliance timelines are compressing product lifecycles unevenly across these dimensions.
Product Type:
Hydraulic crawler rigs dominate domestic replacement cycles in Australia and Chile, while electric and hybrid variants attract disproportionate export-led development investment from European and Chinese manufacturers.
- Hydraulic Crawler:These units deploy high-pressure fluid power systems delivering 20,000–40,000 Nm rotary torque for blasthole drilling in variable rock hardness. Australian iron ore operators specify hydraulic platforms for open-pit autonomous fleet deployments where power density requirements exceed current battery alternatives. EPA Tier 4 Final after-treatment packaging is compressing frame space availability and elevating development costs for North American configurations.
- Electric Crawler:Battery-electric architectures eliminate diesel particulate emissions for underground ventilation-constrained environments. Chinese state-owned enterprises in Xinjiang are piloting 300 kWh lithium-iron-phosphate systems for western province mineral extraction, though energy density constraints restrict operational radius to short-haul tramming cycles.
- Pneumatic Crawler:Compressed-air drive systems serve explosive atmospheres in underground coal seams where ignition source elimination is mandatory.
- Hybrid Crawler:Diesel-electric series configurations optimize engine loading for intermittent drilling cycles while maintaining mobility independence from charging infrastructure.
Hydraulic crawler holds the largest share; momentum sits with electric crawler as underground ventilation cost economics shift.
Application:
Margin structures vary threefold across these verticals, with mining commanding premium automation tiers and geotechnical contracting absorbing volume through dispersed urban infrastructure.
- Mining:Hard-rock extraction demands autonomous drilling platforms with machine vision-guided rod handling and real-time deviation correction. Chilean copper operators specify these systems as baseline procurement requirements, collapsing viable supply to integrated drill-and-blast specialists.
- Geotechnical:Slope stabilization and tunnel pre-support drilling are expanding most quickly in India's Himalayan corridor and Peru's Andean infrastructure belt. These projects require compact crawler units with rapid setup cycles for fragmented mobilization schedules.
- Construction:Foundation anchoring and micropile installation drive standardized hydraulic platform demand through general contracting channels.
- Water Well Drilling:Rural groundwater access programs in sub-Saharan Africa and South Asia specify cost-optimized pneumatic and hydraulic units with manual rod handling.
Mining commands revenue concentration; geotechnical is gaining share fastest as urban tunneling multiplies.
End User:
Procurement authority is fragmenting as Australian mining contractors unbundle equipment acquisition from consumables supply, while state-backed channels concentrate volume in China's western provinces.
- Mining Companies:Integrated operators in Australia's Pilbara region specify autonomous fleet platforms with 10-year total cost of ownership contracts, shifting supplier relationships toward outcome-based drilling metrics.
- Contractors:Independent drilling specialists capture aftermarket service revenue pools through separated maintenance execution and parts procurement.
- Government:State-owned enterprise channels in Xinjiang and Qinghai concentrate heavy-duty crawler procurement through centralized mineral extraction tenders.
- Utilities:Water infrastructure agencies specify standardized platforms for wellfield development with extended warranty requirements.
Mining companies hold the largest share; contractors are expanding procurement autonomy fastest.
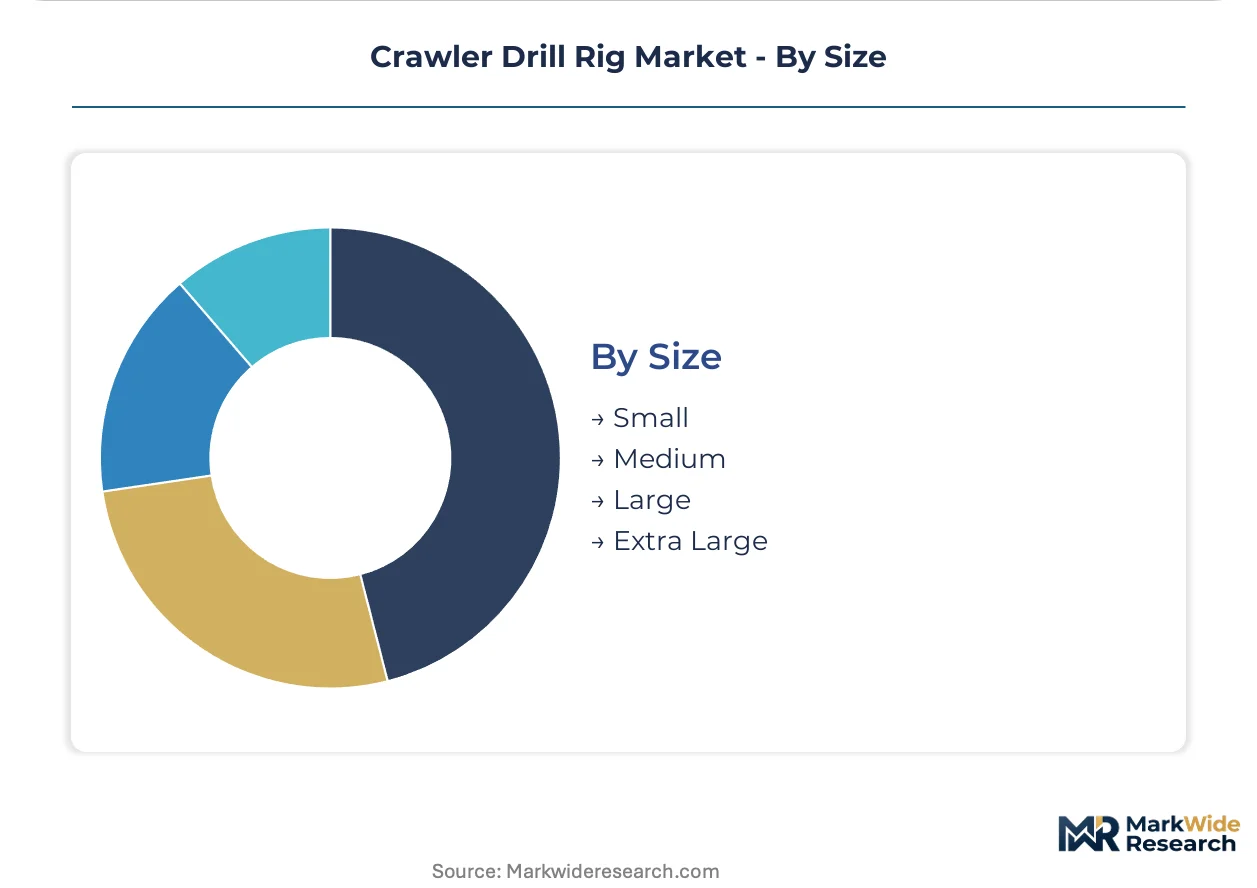
Size:
Physical scale correlates directly with application torque requirements and mobility constraints, with medium and large units capturing overlapping demand pools.
- Large:These rigs deliver 400 mm maximum hole diameter capacity for open-pit blasthole drilling. Australian iron ore autonomous fleets standardize on this tier for production drilling uniformity.
- Medium:150–250 mm diameter range serves construction and geotechnical verticals with trailer-transportable mass limits for rapid site mobilization.
- Small:Compact units under 8 tonnes operating weight access confined underground development headings and urban foundation work.
- Extra Large:Specialized platforms exceed 50 tonnes for quarry production drilling with automated rod storage and 12-meter single-pass depth capability.
Large holds the largest share; medium is climbing the fastest as geotechnical contracting scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-torque hydraulic component manufacturing clusters in Germany and Japan concentrate supply-side capacity for crawler drill rig assemblies. Australian mining contractors and Chilean copper operators drive demand-side procurement volume. China's western provinces absorb state-backed fleet deployment through centralized mineral extraction tenders.
Australia
Pilbara iron ore operators specify autonomous drilling platforms with decade-long total cost of ownership contracts. The country's national mining safety codes mandate operator protection structures and emergency shutdown systems that extend product development timelines. Perth-based fleet management specialists coordinate autonomous deployment across dispersed quarry operations.
Chile
Underground copper contractors specify unmanned operation capabilities as baseline procurement requirements. The national mining regulator enforces ventilation standards that compress viable powertrain options toward electric architectures. Antofagasta and Calama industrial corridors concentrate heavy-duty crawler unit deployment for hard-rock extraction.
China
State-owned enterprises in Xinjiang and Qinghai pilot battery-electric architectures for western province mineral extraction. MIIT enforces GB stage emission limits that parallel European benchmarks, creating dual-compliance burdens for exporters. Chengdu and Xuzhou manufacturing bases anchor domestic rig assembly capacity serving Belt and Road export markets.
Germany
EU Stage V engine regulations compress demand toward hybrid powertrains for underground ventilation-constrained environments. The KBA enforces emission compliance timelines that elevate development costs for mid-tier suppliers. Ruhr Valley component clusters supply high-torque hydraulic systems to integrated rig assemblers across Europe.
United States
EPA Tier 4 Final standards force synchronous engine redesigns across diesel-hydraulic product lines. After-treatment system packaging consumes previously available frame space, compelling modular architecture reconfigurations. Appalachian quarry operators and Southwest copper developers anchor domestic procurement through autonomous fleet specifications.
Crawler Drill Rig Market Competitive Landscape
Concentration sits with integrated drill-and-blast specialists capable of autonomous system development. The supplier base narrows toward capital-intensive manufacturers with captive diesel-electric integration capabilities. Three archetypes dominate: full-system integrators controlling excavation workflows, component specialists supplying high-torque hydraulics, and regional assemblers serving cost-optimized pneumatic segments. Competitive moves center on strategic partnerships for 5G fleet connectivity and portfolio diversification into battery-electric architectures.
Among European-based full-system integrators, Atlas Copco AB and Sandvik AB occupy positions exemplifying autonomous drilling platform development. Epiroc AB represents the spin-off archetype focused on mining equipment specialization. These entities anchor premium-tier positioning through integrated control architectures rather than component supply relationships.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Furukawa Rock Drill Co. Ltd. |
| Epiroc AB |
| Liebherr Group |
| Komatsu Ltd. |
| Sandvik AB |
| Xuzhou Construction Machinery Group |
| Boart Longyear Ltd. |
| Caterpillar Inc. |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final compliance gates both supplier qualification and price differentiation simultaneously, compressing the viable vendor base to capital-intensive manufacturers while stratifying procurement tiers by emission architecture maturity. This regulatory anchor elevates development costs for diesel-hydraulic configurations while accelerating premium capture for electric and hybrid alternatives.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across crawler drill rig procurement, stratifying offerings by after-treatment system integration and powertrain architecture. Three-tier pricing structure across premium autonomous platforms, standard diesel-hydraulic units, and economy pneumatic configurations reflects certification grade and automation depth. Cost compression in mid-tier diesel offerings is intensifying because after-treatment packaging consumes frame space and elevates engineering overhead. Mining companies in Australia's Pilbara region exhibit lowest price sensitivity due to decade-long total cost of ownership contracting, while geotechnical contractors in India's Himalayan corridor absorb highest price sensitivity through fragmented project-based procurement.
Supply Chain Analysis
Inventory cycles for high-torque hydraulic components extend 16-24 weeks, constraining rig assembly scheduling for non-integrated manufacturers. Manufacturing clusters in Germany, Japan, and China draw from specialized foundries producing 20,000–40,000 Nm rated rotary heads and precision-engineered track undercarriage systems. Single-source vulnerability concentrates in German Ruhr Valley hydraulic component suppliers serving European integrated rig assemblers. Distribution runs through OEM captive parts networks in mining-centric markets, shifting toward independent service providers in geotechnical contracting corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect through 5G fleet connectivity convergence, where telematics integration transforms equipment procurement toward outcome-based drilling contracts anchored by real-time blast optimization interoperability.
For Market Incumbents: Fortify autonomous system architectures against emerging electric powertrain specialists by deepening captive diesel-electric integration capabilities and securing ISO 18758 certification pathways for Australian and Canadian market access. Capacity addition in Chengdu and Xuzhou manufacturing bases anchors cost position for Belt and Road export markets. For New Entrants and Emerging Players: Aftermarket service unbundling in Australia's Pilbara region exposes white-space opportunity for independent maintenance execution and consumables supply separated from equipment acquisition. Geotechnical contracting in Peru's Andean infrastructure belt offers most penetrable entry point through compact crawler units with rapid setup cycles. Go-to-market leverage rests on 5G-enabled fleet management partnerships with dispersed quarry operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier hydraulic component suppliers lacking electric powertrack development capabilities. Five-to-ten year viability favors integrated drill-and-blast specialists controlling full excavation workflows. Signal to watch: battery energy density breakthroughs enabling open-pit electric crawler deployment, which would collapse diesel-hydraulic residual value.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Development | MIIT GB stage compliance in China's western provinces accelerates domestic manufacturer R&D allocation. |
| Autonomous Drill Rig Architecture | Chilean copper operators specify unmanned operation as baseline procurement requirement. |
| 5G Fleet Connectivity Integration | Perth-based fleet management specialists coordinate autonomous deployment across dispersed quarry operations. |
| Aftermarket Service Unbundling | Australian mining contractors separate equipment acquisition from consumables supply and maintenance execution. |
| Geotechnical Application Diversification | Urban tunneling in India's Himalayan corridor multiplies compact crawler unit demand. |
Research Methodology
The analysis maps hydraulic crawler, electric crawler, pneumatic crawler, and hybrid crawler sub-sectors, each validated through maintenance directors at mining operations, plant engineers at geotechnical contracting firms, OEM procurement teams at integrated drill-and-blast specialists, and aftermarket service heads at independent parts distributors. Primary interview insights triangulate against customs and trade data, mining safety code filings with Australian and Canadian regulators, SEC 10-K disclosures from capital-intensive manufacturers, and state-owned enterprise tender documents from China's western provinces. Bottom-up unit demand modeling reconciles with top-down market value estimates across the projection horizon.
Consistency checks validate volume and value outputs against external benchmarks including IEA mineral extraction equipment forecasts and OEM production disclosures. Segmentation dimensions span powertrain technology, application vertical, end-user procurement authority, and physical size tier. CAGRs derive from annualized growth rate calculations applied to base-year market sizing. Industry-specific forecast inputs incorporate battery energy density trajectories and underground ventilation cost economics for electric crawler adoption curves.
Forecasts assume regulatory continuity in EPA Tier 4 Final, EU Stage V, and MIIT GB stage regimes; material policy shifts would require re-modeling powertrain transition timelines. Commodity price volatility in lithium and rare earth inputs, alongside automation engineering talent scarcity, constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Africa Mining Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
DTH Drill Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Air Core Drilling Market