
 Global Marine Ventilation Systems Market | 2026-2036
Global Marine Ventilation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marine Ventilation Systems Market Intelligence
A shift from single-source procurement to multi-vendor qualification is repositioning how fleet operators secure ventilation packages. Heinen & Hopman leverages its Dutch engineering base to dominate custom HVAC integration for superyachts and naval contracts. Drews Marine GmbH anchors its position through captive production of corrosion-resistant ducting for chemical tankers. JEC Marine competes aggressively on turnaround speed for ship repair yards in Mediterranean ports.
Marine ventilation systems encompass engineered air movement and climate control equipment designed to regulate temperature, humidity, and contaminant levels within vessel compartments, typically constructed from marine-grade aluminum or coated steel to withstand salt-laden environments and continuous vibration. These systems maintain breathable atmospheres in engine rooms, cargo holds, and accommodation blocks while exhausting hazardous fumes and managing thermal loads from propulsion machinery. Centrifugal fans command the largest product share due to their higher pressure capability for ducted distribution through complex ship geometries. Energy-efficient technology segments gain share as dual-fuel propulsion layouts demand precision cooling to protect electronic control rooms. Naval ships represent the most specification-intensive application tier, with survivability requirements driving redundant fan configurations and blast-damper integration.
IMO's Energy Efficiency Existing Ship Index and the EU F-Gas Regulation jointly constrain refrigerant choices and fan motor efficiency thresholds for vessels calling at European ports. The US Coast Guard enforces fire-damper spacing and smoke-extraction protocols under 46 CFR subchapter J, affecting system layout approvals for ships entering American waters. Classification societies including DNV and Lloyd's Register embed ventilation performance into notations for crew comfort and machinery preservation. Stakeholders must track how ammonia-fuel engine rooms reshape airflow calculations and explosion-venting specifications before committing to next-generation platform designs.
Market Dynamics
Dual-fuel propulsion architectures are recalibrating thermal management specifications across newbuild programs, forcing ventilation suppliers to engineer precision cooling for electronically dense control rooms while maintaining legacy redundancy for conventional machinery spaces.
Growth Catalysts
- IMO Energy Efficiency Existing Ship Index:Retrofit mandates for aging fleets drive specification upgrades in engine room climate systems, particularly for vessels trading European routes.
- Ammonia-fuel engine rooms:Emerging fuel chemistries require redesigned airflow calculations and explosion-venting protocols, opening engineering contracts for specialized ducting and damper configurations.
- Ulsan shipbuilding cluster:Concentrated yard output in South Korea generates synchronized procurement waves for integrated HVAC packages across tanker and containership segments.
Market Restraints
- Marine-grade aluminum price volatility:Raw material swings compress fabrication margins for ducting manufacturers serving price-sensitive repair yards.
- Corrosion-resistant coating supply:Concentrated specialty chemical production creates input bottlenecks for suppliers of chemical tanker ventilation systems.
- F-Gas refrigerant phase-down:EU regulatory constraints limit working fluid options for accommodation cooling, extending equipment qualification timelines.
Strategic Opportunities
- Brazilian offshore expansion:Pre-salt field development drives demand for platform HVAC systems in a market with limited local fabrication capacity.
- Naval survivability specifications:Redundant fan configurations and blast-damper integration command premium engineering fees in defense procurement.
- Smart damper actuation:Convergence of marine ventilation with building automation protocols enables remote diagnostics and predictive maintenance contracts.
Industry Challenges
- Marine HVAC commissioning expertise:Shortage of technicians qualified for salt-environment system balancing extends installation timelines in Mediterranean repair hubs.
- Classification society harmonization:Divergent DNV and Lloyd's Register interpretation of smoke-extraction protocols complicates multi-flag fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marine Ventilation Systems Market |
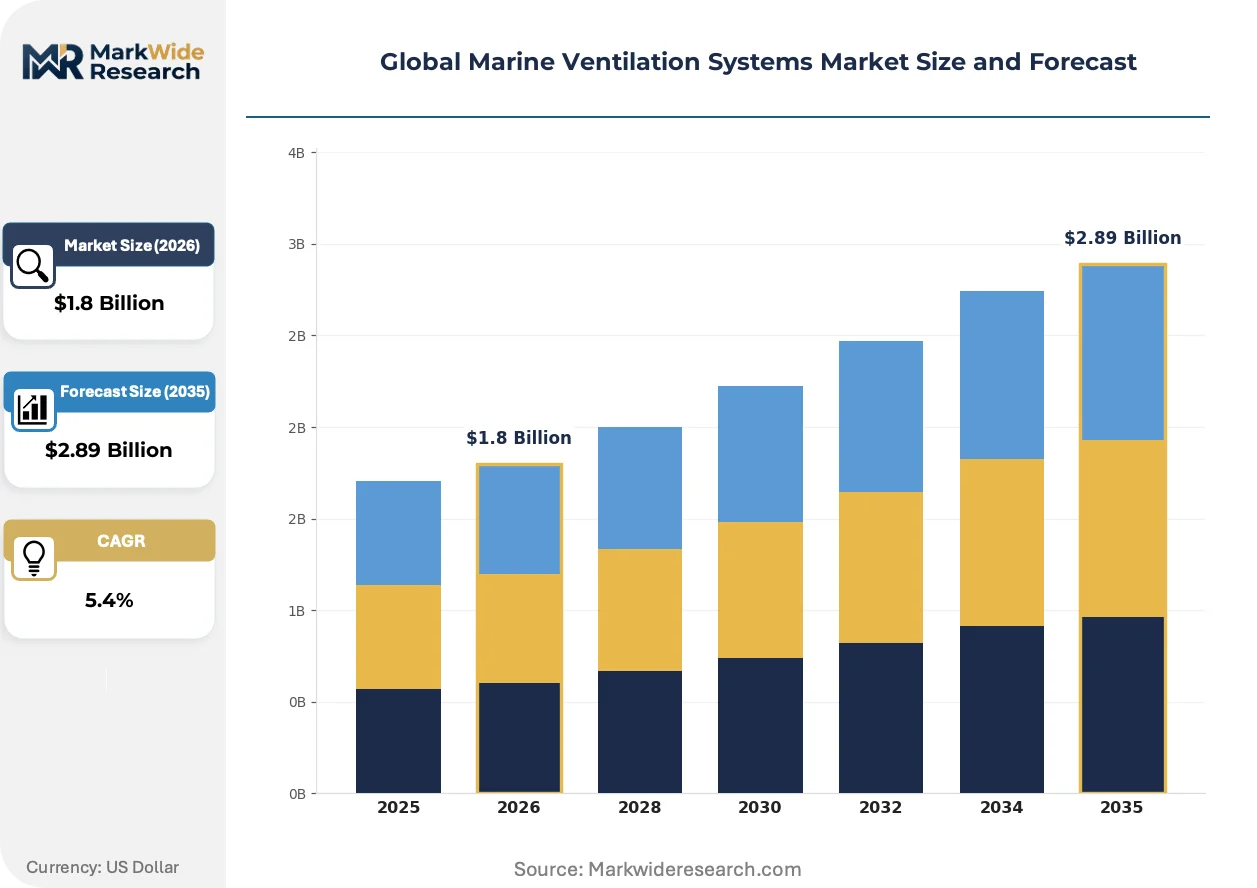
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Mixed Flow Fans, Exhaust Systems, Supply Units Technology: Variable Frequency Drive, Fixed Speed, Heat Recovery, Energy Efficient, Noise Reduction Application: Cargo Ships, Passenger Liners, Offshore Platforms, Fishing Vessels, Naval Ships End User: Shipbuilders, Ship Repair Yards, Offshore Contractors, Marine Equipment Suppliers, Port Authorities |
| Companies Covered | JEC Marine, Drews Marine GmbH, Heinen & Hopman, Delta "T" Systems, NADI Airtechnics, Lindab, HORN International, Bronswerk Marine, Marinco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marine Ventilation Systems Market Strategic Shifts & Innovations
Electrification of fan drive systems is compressing energy profiles while digital integration enables condition-based maintenance, reshaping how shipyards specify and operators manage climate infrastructure.
Permanent magnet synchronous motors are electrifying axial fan architectures for accommodation ventilation, cutting power draw by half compared to induction alternatives. Cruise line newbuild programs in Finnish and German yards specify these drives for galley and cabin supply systems. The technology is electrifying procurement criteria, displacing first-cost optimization with lifecycle energy accounting in owner specifications.
EU F-Gas Regulation tightens refrigerant containment standards for vessels calling at European ports, mandating leak detection systems and accelerating hydrofluoroolefin adoption. Shipowners trading Atlantic routes face equipment replacement decisions ahead of phasedown deadlines. Reefer vessel operators bear the steepest compliance burden, retrofitting central cooling plants to maintain port access.
Fleet operators now unbundle ventilation packages from integrated shipyard contracts, qualifying multiple vendors for recurring repair and upgrade work. Mediterranean port clusters see the most aggressive disintermediation, with ship managers contracting JEC Marine and Drews Marine GmbH directly for turnaround-critical damper and fan replacements. This procurement fragmentation compresses margins for yard-integrated HVAC suppliers while expanding addressable market for independent service specialists.
Global Marine Ventilation Systems Market Segmentation
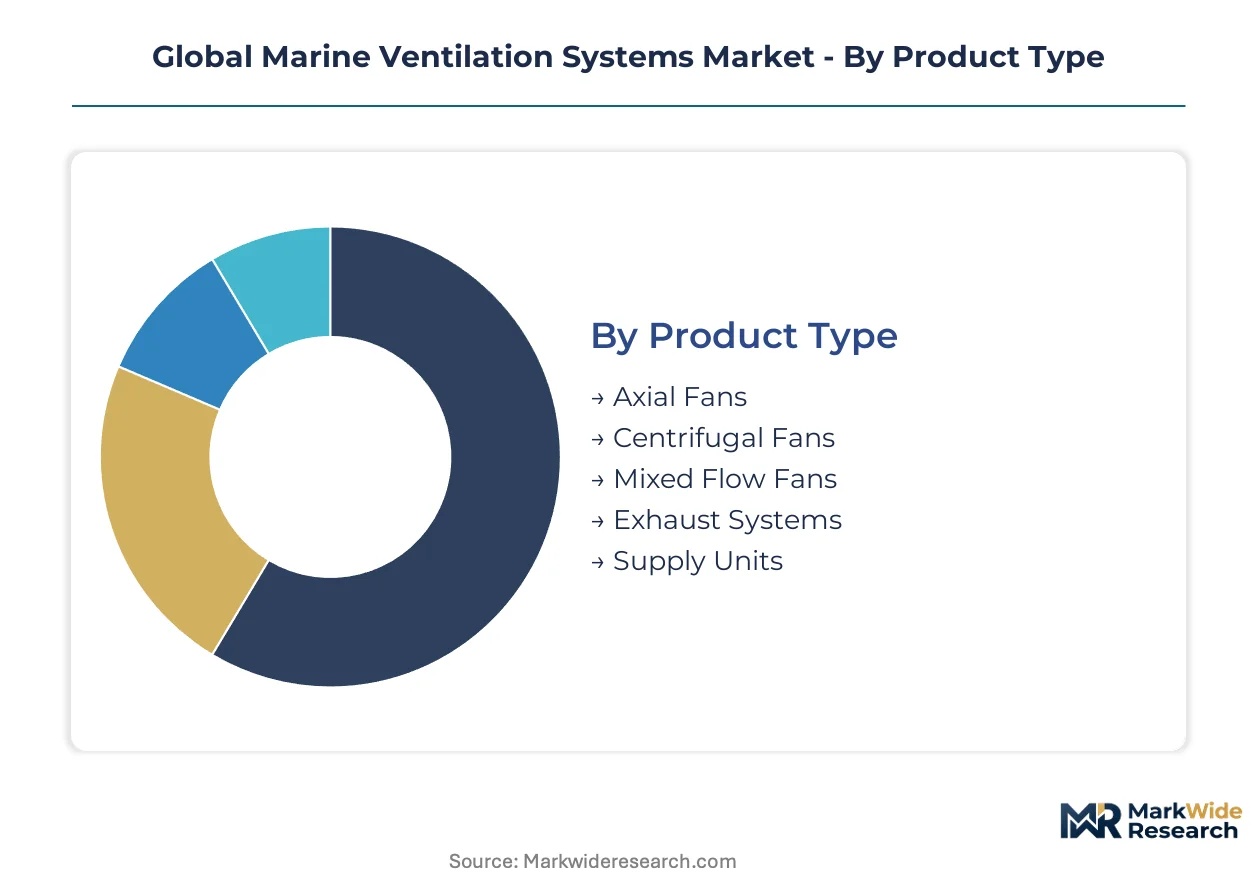
Segmentation reveals how upgrade cycles and regulatory pressures concentrate demand across distinct equipment categories. Procurement patterns diverge sharply between newbuild specifications and retrofit-driven replacement markets.
Product Type:
Replacement cycles accelerate as dual-fuel propulsion architectures force recalibration of airflow specifications across aging fleets.
- Centrifugal Fans:Engineered for higher pressure capability through complex ducted ship geometries. Demand concentrates in South Korea's Ulsan cluster where tanker and containership newbuilds specify integrated HVAC packages.
- Axial Fans:Permanent magnet synchronous motors are electrifying accommodation ventilation architectures, cutting power draw by half compared to induction alternatives. Finnish and German cruise line newbuild programs specify these drives for galley and cabin supply systems.
- Mixed Flow Fans:Hybrid pressure-velocity characteristics suit intermediate duct runs in mid-size cargo vessels.
- Exhaust Systems:Fire-damper spacing and smoke-extraction protocols under US Coast Guard 46 CFR subchapter J drive layout approvals.
- Supply Units:Modular configurations serve Mediterranean repair yards requiring rapid turnaround on damper and fan replacements.
Centrifugal fans sit at the top of the volume ranking, with axial fans climbing the fastest as electrification reshapes procurement criteria.
Technology:
Cost tiers stratify sharply between legacy fixed-speed installations and premium energy-efficient retrofits demanded by EU port regulations.
- Energy Efficient:Dual-fuel propulsion layouts demand precision cooling to protect electronic control rooms while maintaining legacy redundancy. IMO Energy Efficiency Existing Ship Index mandates retrofit specifications for vessels trading European routes.
- Variable Frequency Drive:Enables condition-based maintenance and remote diagnostics through building automation protocol convergence. Smart damper actuation opens predictive maintenance contracts for fleet operators.
- Heat Recovery:Waste heat capture from engine room exhaust preconditions accommodation air supply in Arctic-class vessels.
- Fixed Speed:Baseline installations persist in price-sensitive fishing vessel segments where first-cost optimization dominates.
- Noise Reduction:Accommodation block specifications for cruise liners and superyachts mandate attenuated fan architectures.
Energy efficient technology commands premium positioning, with variable frequency drive adoption expanding most quickly through digital integration mandates.
Application:
Application mix tracks directly to specification intensity, with naval and offshore segments demanding redundant configurations absent in commercial cargo.
- Naval Ships:Survivability requirements drive redundant fan configurations and blast-damper integration. Premium engineering fees attach to defense procurement specifications.
- Offshore Platforms:Brazilian pre-salt field development drives platform HVAC demand in a market with limited local fabrication capacity.
- Cargo Ships:Bulk carrier and tanker retrofit programs concentrate in Mediterranean repair hubs facing technician shortages for salt-environment system balancing.
- Passenger Liners:Crew comfort notations from DNV and Lloyd's Register embed ventilation performance into classification requirements.
- Fishing Vessels:Smallest specification intensity with basic engine room exhaust and minimal accommodation climate control.
Naval ships anchor the premium tier, with offshore platforms gaining share fastest through Brazilian expansion and ammonia-fuel engine room redesigns.
End User:
Customer type determines procurement fragmentation, with direct contracting by ship managers displacing traditional yard-integrated supply.
- Shipbuilders:South Korean and Chinese yard output generates synchronized procurement waves for integrated HVAC packages. Ulsan cluster specifications cascade through global tanker and containership programs.
- Ship Repair Yards:Mediterranean port clusters see aggressive disintermediation as fleet operators unbundle ventilation packages from integrated contracts.
- Offshore Contractors:Platform newbuild and life-extension programs in Brazil and West Africa drive specialized ducting demand.
- Marine Equipment Suppliers:Distribution intermediaries serve secondary ports lacking direct manufacturer relationships.
- Port Authorities:Shore power and emissions monitoring infrastructure extends to vessel ventilation compliance verification.
Shipbuilders retain the largest contract value, with ship repair yards expanding most quickly through procurement fragmentation and direct vendor qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan shipbuilding cluster anchors global procurement gravity for marine ventilation systems, with South Korean yard output cascading specifications through tanker and containership programs worldwide. National regulatory frameworks and industrial concentrations in four additional countries shape competitive positioning across the forecast window.
South Korea
Dual-fuel propulsion retrofits and newbuild specifications concentrate demand in the Ulsan-Gyeongnam corridor, where Hyundai Heavy Industries and Samsung Heavy Industries synchronize HVAC procurement waves. MFDS marine equipment standards align with IMO DCS implementation timelines. Busan repair hubs face technician shortages for salt-environment system commissioning.
United States
US Coast Guard 46 CFR subchapter J enforcement drives fire-damper spacing and smoke-extraction protocol compliance for vessels entering American waters. Gulf Coast offshore platform operators expand HVAC life-extension programs for aging production assets. Houston fabricators supply corrosion-resistant ducting for chemical tanker retrofits.
Germany
EU F-Gas Regulation refrigerant phase-down mandates accelerate hydrofluoroolefin adoption in accommodation cooling systems for Atlantic-trading fleets. Hamburg and Bremerhaven repair yards unbundle ventilation packages from integrated shipyard contracts. Lloyd's Register interpretation of crew comfort notations shapes specification intensity for passenger liner segments.
Brazil
Pre-salt field development drives platform HVAC demand in a market with limited local fabrication capacity. ANVISA offshore safety protocols intersect with IMO energy efficiency mandates for floating production units. Rio de Janeiro state anchors engineering procurement for Petrobras-led newbuild programs.
Netherlands
Heinen & Hopman's Dutch engineering base dominates custom HVAC integration for superyachts and naval contracts. Rotterdam port infrastructure supports Mediterranean-facing repair logistics for damper and fan replacements. ECHA chemical safety frameworks influence coating specifications for North Sea chemical tanker operations.
Global Marine Ventilation Systems Market Key Industry Players
Global majors compete with regional champions across specification tiers, with Dutch and German engineering houses anchoring premium naval and superyacht segments while Mediterranean specialists capture repair-yard turnaround business. Market structure stratifies across three archetypes: integrated HVAC system designers, corrosion-resistant ducting fabricators, and rapid-response repair specialists. Capacity expansion and multi-vendor qualification programs represent the dominant competitive moves as fleet operators disintermediate traditional yard-integrated supply chains.
Among European engineering houses, Heinen & Hopman and Drews Marine GmbH occupy positions exemplifying the premium-systems archetype, with the former representing Dutch custom-integration capabilities and the latter anchoring German captive-production strength in chemical tanker applications. JEC Marine sits within the Mediterranean rapid-response tier, capturing direct contracting opportunities from ship managers seeking turnaround-critical replacements. These three company profiles illustrate how geographic specialization and service-model differentiation fragment procurement authority away from consolidated shipyard channels.
| Leading Market Players |
|---|
| JEC Marine |
| Drews Marine GmbH |
| Heinen & Hopman |
| Delta "T" Systems |
| NADI Airtechnics |
| Lindab |
| HORN International |
| Bronswerk Marine |
| Marinco |
| Others |
Cost & Logistics Intelligence
Offshore platform operators and naval procurement programs anchor pricing power with specification-intensive buyers commanding engineering premiums while commercial cargo fleets drive cost compression through multi-vendor qualification. This buyer dichotomy stratifies the market into project-based contracting for custom integration and transactional procurement for standardized replacement components.
Pricing Analysis
Marine-grade aluminum price volatility passes through fabrication margins unevenly, with South Korean shipbuilders absorbing input swings through long-term offtake agreements while Mediterranean repair yards face spot-market exposure. Three-tier pricing structure across premium, standard, and economy levels separates naval survivability specifications from commercial cargo retrofits and basic fishing vessel installations. Cost compression in repair-yard segments is intensifying because fleet operators disintermediate traditional yard-integrated supply chains. Commercial cargo operators exhibit highest price sensitivity, prioritizing first-cost optimization, while naval programs demonstrate lowest sensitivity due to blast-damper and redundant-fan mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Busan, and Houston maintain hub-and-spoke patterns serving ship repair clusters with turnaround-critical damper and fan inventories. Manufacturing concentrates in the Netherlands, Germany, and South Korea, with Dutch engineering houses feeding superyacht and naval channels while Ulsan cluster fabricators supply tanker and containership newbuilds. Raw material dependencies center on marine-grade aluminum sheet, corrosion-resistant coating chemicals, and permanent magnet motor components. Single-source vulnerability in specialty coating supply creates input bottlenecks for chemical tanker ventilation systems. Distribution runs through manufacturer-direct contracting for large fleet operators and equipment supplier intermediaries for secondary ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as dual-fuel propulsion retrofits and ammonia-fuel engine room redesigns shift demand toward precision-engineered climate systems with premium engineering fees.
For Market Incumbents: Hedge margin erosion in commercial cargo segments by deepening captive production of corrosion-resistant ducting while securing IMO Energy Efficiency Existing Ship Index retrofit contracts in European-trading fleets. Channel control through direct ship manager relationships displaces yard-integrated supply and protects pricing power against Mediterranean rapid-response specialists. For New Entrants and Emerging Players: Enter via Brazilian offshore platform HVAC demand, where pre-salt field development outpaces local fabrication capacity and ANVISA safety protocols intersect with energy efficiency mandates. Target ship repair yards in Mediterranean ports through modular supply unit configurations enabling rapid turnaround on damper replacements, bypassing entrenched shipbuilder relationships. For Investors and Strategic Acquirers: Marine HVAC engineering houses with naval and superyacht specialization are the most active acquirer targets in this space, as defense procurement consolidation favors scale players with Lloyd's Register and DNV certification depth. Long-term viability hinges on ammonia-fuel engine room airflow expertise. The signal to watch is classification society harmonization progress on smoke-extraction protocols, which would accelerate multi-flag fleet standardization and reward specification-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corrosion-Resistant Coating Production | Captive supply of specialty chemicals insulates margins from EU F-Gas Regulation bottlenecks. |
| Smart Damper Actuation Platform Launch | Building automation protocol convergence enables predictive maintenance contracts with Norwegian offshore operators. |
| Naval Survivability Certification Investment | Blast-damper integration capabilities unlock premium engineering fees in defense procurement channels. |
| Brazilian Offshore Joint Venture | Local fabrication partnerships address ANVISA compliance gaps for Petrobras-led platform programs. |
| Ammonia-Fuel Engine Room Engineering Contract | Explosion-venting specification expertise positions suppliers for next-generation propulsion retrofits. |
Research Approach
Multiple input streams — primary interviews with shipyard procurement directors, fleet technical managers, and classification society surveyors; secondary validation through IMO DCS implementation filings, EU MRV emissions databases, and shipbuilding order books; plus customs trade data on marine-grade aluminum flows — were reconciled through bottom-up and top-down triangulation. Stakeholder interviews captured specification evolution for dual-fuel propulsion architectures and ammonia-fuel engine room designs. Secondary sources included Lloyd's Register and DNV classification notations, SEC filings from listed shipbuilders, and South Korean MFDS equipment certification records.
Historical capacity utilization and order book patterns were cross-referenced against panel input from HVAC system designers and repair yard operators to build projection scenarios. Segmentation dimensions modeled include product type, technology tier, application intensity, and end-user procurement channel across the analysis window. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate timelines. Forecast inputs incorporated IMO Energy Efficiency Existing Ship Index compliance deadlines and EU F-Gas refrigerant phase-down schedules.
Inputs from classification society technical committees and shipbuilder engineering departments were available through the study window; gaps in ammonia-fuel engine room operational data introduce uncertainty bands around explosion-venting specification demand. Forecasts reflect documented assumptions on regulatory enforcement consistency and raw material price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market